
 Iron Salt Battery Market | 2026-2036
Iron Salt Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Salt Battery Market Insights
A capital-intensity divergence between well-funded demonstration projects and early commercial deployments is reorganizing competitive hierarchies in iron salt battery manufacturing. ESS Inc. leverages its all-iron flow chemistry to dominate utility-scale installations in Oregon and California. Form Energy anchors its position through multi-day iron-air systems designed explicitly for grid decarbonization timelines. CMBlu Energy AG competes with organic redox flow variants that extend operational flexibility beyond conventional iron chloride architectures.
Iron salt batteries employ aqueous electrolytes containing dissolved iron compounds—typically iron chloride or iron sulfate—to store electrochemical energy through reversible redox reactions at 1.0–1.2 V nominal cell voltage, with primary purpose of delivering cost-effective, non-flammable long-duration storage for stationary power applications. Iron chloride formulations occupy the most mature manufacturing position due to established supply chains and simpler electrolyte preparation protocols. Solid-state iron battery research is accelerating fastest among technology categories as laboratories pursue higher energy density without aqueous corrosion limitations.
The US EPA and FERC shape deployment through environmental permitting timelines and wholesale market participation rules for energy storage assets, while Germany's KBA and grid regulator Bundesnetzagentur influence European certification pathways for stationary battery systems. China's GB standards and MIIT technology roadmaps constrain import access but accelerate domestic iron-based chemistry development through state-directed research funding. Stakeholders must monitor how evolving fire safety codes in multiple jurisdictions treat aqueous versus non-aqueous electrolyte chemistries when siting large-scale installations near populated areas.
Market Dynamics
The US Inflation Reduction Act's standalone storage investment tax credit is restructuring project finance for long-duration battery deployments, pulling capital away from conventional lithium-ion procurement models toward aqueous iron-based chemistries.
Growth Catalysts
- Investment Tax Credit Policy:The IRA's standalone storage ITC eliminates tax equity partner requirements, enabling direct project ownership structures that favor capital-intensive iron salt systems with 20-year operational lifespans.
- Utility Procurement Mandates:California's SB 100 directive and Texas ERCOT market reforms are creating procurement quotas for multi-day storage, matching iron-air and iron-chloride discharge durations to grid reliability needs.
- Iron Sulfate Chemistry Maturation:Simplified electrolyte preparation protocols using commodity-grade iron salts are compressing manufacturing learning curves versus vanadium flow battery alternatives.
Market Restraints
- Electrolyte Cost Volatility:Industrial-grade iron chloride prices fluctuate with steel production cycles, exposing project developers to input cost uncertainty absent in lithium-ion supply contracts.
- Supply Concentration Risk:Membrane and bipolar plate manufacturing concentrates in Chinese industrial clusters, creating import dependency for non-domestic system integrators.
- Energy Density Ceiling:Aqueous iron chemistries face theoretical voltage limits near 1.2 V, constraining footprint-constrained urban installations versus solid-state alternatives.
Strategic Opportunities
- German Industrial Decarbonization:The EU Green Deal's carbon border adjustment mechanism and Bundesnetzagentur grid codes are opening procurement channels for iron flow systems in Ruhr Valley manufacturing clusters.
- Off-Grid Mining Applications:Remote Australian and Chilean extraction operations require 48-72 hour autonomy, matching iron-air discharge profiles without diesel generator backup.
- Hybrid Solar-Storage PPAs:Merchant power developers are bundling iron salt duration with photovoltaic assets, capturing capacity payments under evolving FERC Order 841 market participation rules.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Flow battery stack design and system integration expertise concentrates at a handful of national laboratories and early-stage manufacturers, constraining deployment velocity.
- UL 9540A Certification Timelines:Fire safety testing protocols for aqueous electrolyte systems lack established precedents, extending pre-commercial validation periods versus lithium-ion benchmarks.
- Legacy SCADA Integration Complexity:Utility control rooms require custom communication interfaces to dispatch iron salt assets, delaying interconnection approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Salt Battery Market |
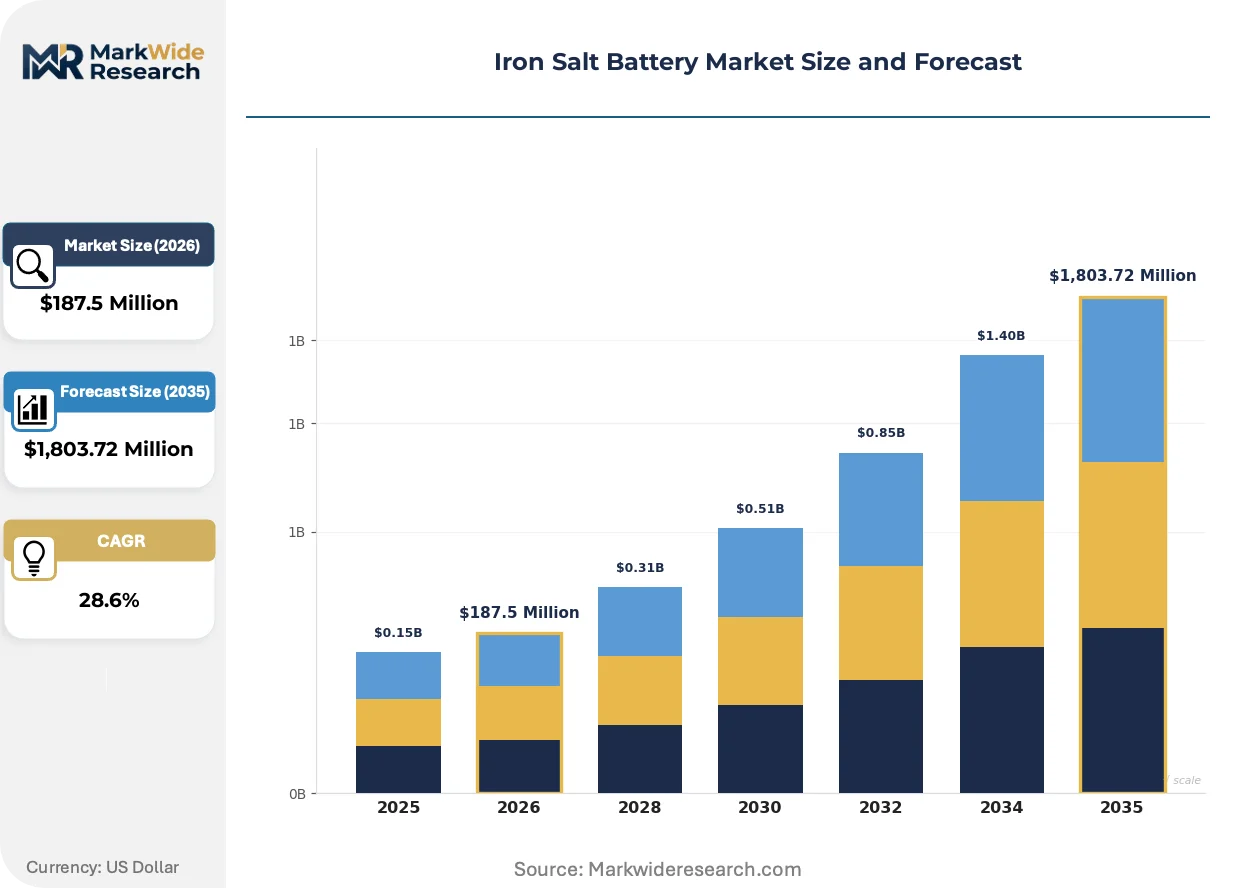
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $1,803.72 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron Chloride, Iron Sulfate, Iron Nitrate, Iron Acetate End User: Grid Storage, Electric Vehicles, Consumer Electronics, Industrial Applications Technology: Flow Battery, Solid-State Battery, Hybrid Battery, Lithium-Iron Battery Application: Renewable Energy, Uninterruptible Power Supply, Backup Power, Frequency Regulation |
| Companies Covered | ESS Inc., ESS Tech Inc., VoltStorage GmbH, Form Energy, Primus Power, Invinity Energy Systems, ViZn Energy Systems, CMBlu Energy AG, Enervault Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Salt Battery Market Trends and Innovations
Solid-state iron battery architectures are attracting accelerated laboratory investment as researchers pursue voltage and energy density breakthroughs unavailable to aqueous systems. Three convergent developments are reshaping competitive positioning.
Solid-state iron-sulfur configurations are decomposing the traditional trade-off between aqueous safety and lithium-ion density. Lawrence Berkeley National Laboratory and MIT spinouts are advancing ceramic electrolyte interfaces that suppress iron dendrite formation. Defense and aerospace procurement offices are funding pilot production for satellite and unmanned vehicle applications where thermal runaway tolerance outweighs mass penalties.
REACH chemical registration requirements and the EU Battery Regulation's carbon footprint disclosure mandates are forcing electrolyte suppliers to document supply chain provenance. German KBA and French ANSM regulators are coordinating certification pathways that treat iron chloride formulations as industrial chemicals rather than hazardous goods, reducing siting restrictions for urban installations. System integrators are responding by establishing European electrolyte blending facilities to satisfy origin requirements.
Power purchase agreement structures are unbundling energy and capacity revenue streams, enabling merchant developers to optimize iron salt dispatch for ancillary services rather than energy arbitrage alone. Texas and California independent power producers are signing 15-year contracts with explicit availability payments that match iron-air degradation profiles. This contractual innovation is most visible in ERCOT's ancillary service markets, where synchronous inertia replacement commands premium pricing.
Iron Salt Battery Market Segmentation
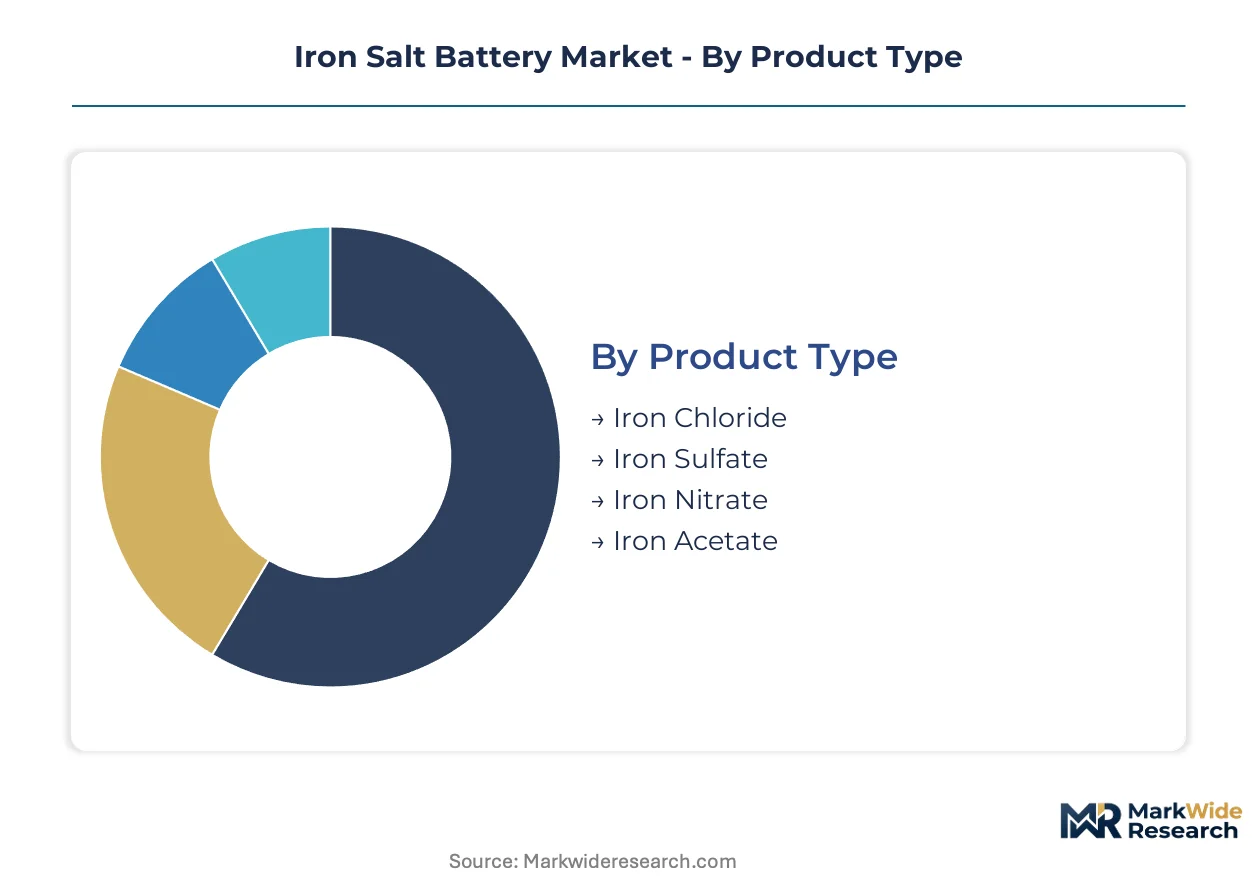
Segmentation in iron salt batteries reveals distinct margin architectures across chemistries and deployment contexts. Product type and end-user concentration determine where capital deployment yields durable returns versus commodity exposure.
Product Type:
Margin pools concentrate in formulations with established electrolyte supply chains and simplified manufacturing protocols.
- Iron Chloride:Aqueous electrolyte formulations leverage commodity-grade feedstocks from steel industry byproduct streams. Utility-scale procurement in California and Texas favors this chemistry for 8-12 hour discharge applications where capital cost minimization outweighs energy density constraints.
- Iron Sulfate:Simplified electrolyte preparation reduces blending facility capital requirements versus chloride alternatives. German industrial decarbonization projects in the Ruhr Valley are specifying sulfate systems to satisfy REACH chemical registration and EU Battery Regulation carbon footprint disclosure mandates.
- Iron Nitrate:Higher solubility limits enable concentrated electrolyte designs that compress system footprint for urban installations.
- Iron Acetate:Organic anion chemistry exhibits reduced corrosivity toward bipolar plate materials, extending stack replacement intervals in high-cycle applications.
The dominant share belongs to Iron Chloride, while Iron Sulfate is closing the gap fastest.
End User:
Volume concentration tracks regulatory-driven procurement mandates and merchant power market restructuring.
- Grid Storage:Multi-day discharge capabilities align with California SB 100 reliability requirements and Texas ERCOT ancillary service market reforms. FERC Order 841 participation rules enable capacity payment capture that improves project finance structures for 20-year asset lifespans.
- Industrial Applications:Remote mining operations in Australia and Chile require 48-72 hour autonomy without diesel backup, matching iron-air discharge profiles. Off-grid extraction sites bypass interconnection queues that delay utility-connected deployments.
- Electric Vehicles:Aqueous chemistry safety profiles attract niche commercial fleet applications where thermal runaway tolerance outweighs mass penalties.
- Consumer Electronics:Solid-state research trajectories target satellite and unmanned vehicle power systems where energy density requirements exclude aqueous alternatives.
Grid Storage commands the largest deployment base, with Industrial Applications expanding most quickly.
Technology:
Customer type stratification separates demonstration-phase capital from commercial procurement with bankable technology risk profiles.
- Flow Battery:Modular stack architecture permits independent scaling of power and energy capacity. All-iron flow systems dominate Oregon and California utility installations where 20-year operational lifespans match depreciation schedules.
- Solid-State Battery:Ceramic electrolyte interfaces suppress iron dendrite formation at higher current densities. Lawrence Berkeley National Laboratory and MIT spinouts are advancing pilot production for defense and aerospace procurement.
- Hybrid Battery:Combined aqueous and solid-state architectures attempt to bridge safety and density trade-offs for commercial vehicle applications.
- Lithium-Iron Battery:Cathode-active iron compounds paired with lithium anodes occupy intermediate positions in energy density and cost.
Flow Battery retains the deepest commercial footprint, though Solid-State Battery is gaining share fastest.
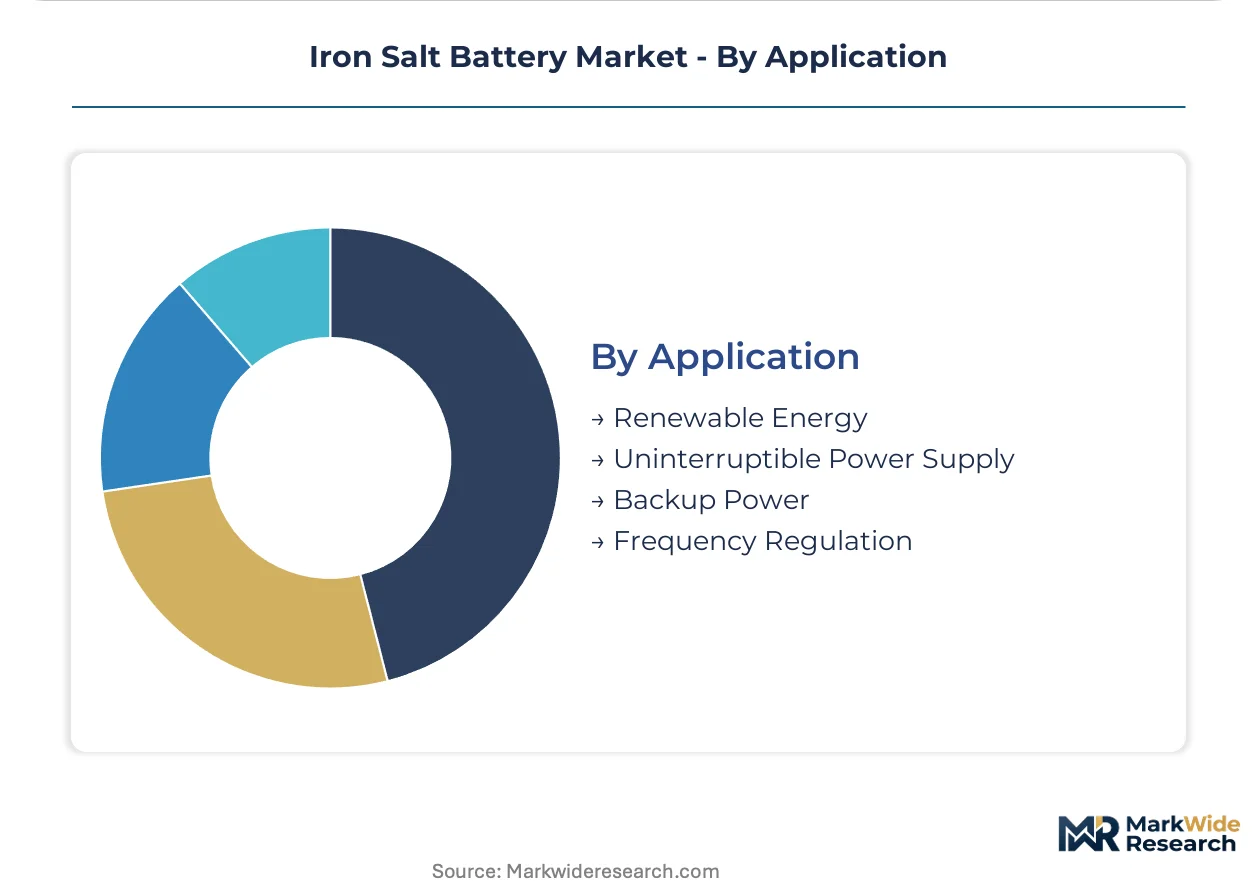
Application:
Cost tier differentiation separates premium availability payments from energy arbitrage revenue streams.
- Renewable Energy:Hybrid solar-storage PPAs bundle iron salt duration with photovoltaic assets to capture evolving capacity payment structures. Merchant developers optimize dispatch for ancillary services rather than energy arbitrage alone.
- Backup Power:Critical facility installations value aqueous electrolyte non-flammability for urban siting near populated areas. UL 9540A fire safety testing protocols for aqueous systems lack established precedents, extending validation timelines.
- Uninterruptible Power Supply:Data center and healthcare applications require sub-second response times that favor high-power stack configurations.
- Frequency Regulation:Fast-cycling revenue streams stress membrane and bipolar plate durability, favoring designs with replaceable stack components.
Renewable Energy integration holds the leading position, while Backup Power is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial procurement where EU carbon border mechanisms enforce premium qualification standards, while Texas and California markets compete on capital cost minimization for utility-scale deployments. This asymmetry shapes where technology developers prioritize certification investment versus manufacturing scale.
United States
Utility procurement mandates in California and Texas are accelerating iron salt deployments for multi-day grid storage. The IRA's standalone storage ITC eliminates tax equity requirements, enabling direct ownership structures that favor 20-year asset lifespans. Oregon and California host the deepest project pipelines for all-iron flow installations.
Germany
Ruhr Valley manufacturing clusters are specifying iron sulfate systems to satisfy REACH registration and EU Battery Regulation carbon footprint mandates. The Bundesnetzagentur's grid codes and KBA certification pathways treat iron chloride as industrial chemicals rather than hazardous goods. Berlin-Brandenburg electrolyte blending facilities are expanding to satisfy origin requirements.
Australia
Remote mining operations in Western Australia and Queensland require 48-72 hour autonomy without diesel backup, matching iron-air discharge profiles. Off-grid extraction sites bypass interconnection queues that delay utility-connected deployments. The country's national energy regulator is adapting market rules for long-duration storage participation.
China
GB standards and MIIT technology roadmaps constrain import access while accelerating domestic iron-based chemistry development through state-directed research funding. Membrane and bipolar plate manufacturing concentrates in eastern industrial clusters, creating supply concentration for non-domestic integrators. Yangtze River Delta laboratories are advancing solid-state iron-sulfur configurations.
Iron Salt Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where demonstration-phase specialists compete against scaled manufacturing operators. The market fragments across flow battery incumbents with utility track records, solid-state research ventures pursuing defense procurement, and hybrid architecture developers bridging safety and density requirements. Three strategic archetypes dominate: chemistry-agnostic system integrators, vertically specialized stack manufacturers, and project development affiliates of industrial conglomerates. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure electrolyte supply agreements and membrane sourcing contracts.
Among US-based developers, ESS Inc. and Form Energy exemplify contrasting scale strategies within the long-duration storage archetype, while CMBlu Energy AG occupies a position representing European organic redox flow specialization. These three anchors illustrate how geographic regulatory alignment shapes competitive positioning more than pure technology differentiation.
| Leading Market Players |
|---|
| ESS Inc. |
| ESS Tech Inc. |
| VoltStorage GmbH |
| Form Energy |
| Primus Power |
| Invinity Energy Systems |
| ViZn Energy Systems |
| CMBlu Energy AG |
| Enervault Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for iron chloride electrolyte lock in both supply access and price visibility for utility-scale developers, insulating project finance structures from steel industry commodity cycles while exposing non-contracted buyers to input cost volatility.
Pricing Analysis
The customization-premium spread separates configured-to-order iron flow battery systems from standardized iron-chloride product tiers. Project-based pricing dominates utility procurement, with differentiation driven by discharge duration configuration and UL 9540A certification tier. Pricing pressure stems from lithium-ion cost compression in shorter-duration segments, squeezing iron salt margins for 4-6 hour applications. Merchant power developers exhibit highest price sensitivity, while industrial off-grid mining operators accept premiums for 72-hour autonomy guarantees.
Supply Chain Analysis
Membrane manufacturing chokepoints in Chinese industrial clusters tether non-domestic system integrators to import-dependent procurement timelines. Electrolyte preparation draws from commodity iron feedstocks in China, Germany, and the United States, while bipolar plate fabrication rests on specialty graphite sources. Single-source vulnerability concentrates in ion-exchange membrane supply, where two producers serve the global flow battery market. Distribution runs through EPC contractors and direct utility procurement channels, with project-based logistics dominating over inventory-based models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iron salt batteries occupy an early-cycle expansion trajectory, with the US Inflation Reduction Act's standalone storage ITC accelerating capital deployment faster than manufacturing scale can match.
For Market Incumbents: Fortify electrolyte supply agreements through backward integration into steel industry byproduct streams, securing captive iron chloride access against commodity price swings. Expand stack manufacturing capacity in Oregon and California to capture California SB 100 procurement mandates before lithium-ion vendors adapt multi-hour product lines. Prioritize UL 9540A fire safety certification investment to compress pre-commercial validation timelines that currently delay interconnection approvals. For New Entrants and Emerging Players: Lead with iron-sulfate chemistry formulations targeting German Ruhr Valley industrial decarbonization projects, where REACH registration requirements and EU Battery Regulation carbon footprint mandates favor compliant suppliers over established chloride incumbents. Capture white-space in Australian remote mining operations requiring 48-72 hour diesel replacement autonomy, bypassing utility interconnection queues that constrain grid-connected competitors. Deploy pilot installations through power purchase agreement structures that unbundle energy and capacity revenue streams, demonstrating bankable technology risk profiles to project finance lenders. For Investors and Strategic Acquirers: Chemistry-agnostic system integrators with demonstrated utility track records represent the most defensible acquisition archetype, capturing value from regulatory-driven procurement mandates without technology-specific obsolescence risk. Frame long-term viability around 10-year grid decarbonization timelines, where multi-day storage requirements displace lithium-ion dominance in 8-hour-plus applications. Monitor FERC Order 841 implementation progress as the critical inflection signal, where expanded market participation rules for energy storage assets determine merchant revenue capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Supply Agreement | Long-term iron chloride offtake contracts insulate project developers from steel industry commodity cycles. |
| UL 9540A Certification Investment | Fire safety testing protocols for aqueous systems compress pre-commercial validation timelines versus lithium-ion benchmarks. |
| Stack Manufacturing Scale-Up | Modular production expansion in Oregon and California captures California SB 100 procurement mandates. |
| European Electrolyte Blending Facility | Origin-compliant production satisfies REACH registration and EU Battery Regulation carbon footprint disclosure requirements. |
| Hybrid Solar-Storage PPA Structure | Unbundled energy and capacity revenue streams optimize iron salt dispatch for ERCOT ancillary service markets. |
Research Methodology
A spread of perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators converged on the working assumptions shaping demand forecasts. Primary fieldwork combined structured interviews with electrolyte suppliers and membrane manufacturers alongside secondary validation through FERC filings, EIA capacity data, IEA long-duration storage reports, and project development databases. Bottom-up installation tracking triangulated against top-down regulatory mandate analysis to establish volume baselines.
Segmentation dimensions modeled span chemistry formulation, technology architecture, discharge duration tier, end-use application, and regional regulatory framework across the projection horizon. CAGRs were derived from fitted adoption curves calibrated to policy implementation timelines and manufacturing learning rates. Forecast inputs incorporated IRA tax credit utilization rates, California SB 100 procurement schedules, and German Bundesnetzagentur grid code evolution.
The analysis sits within stated boundaries; outcomes outside sustained IRA incentive extension and FERC Order 841 market participation expansion would require recalibration. Practitioners should keep alternative scenarios live as electrolyte cost volatility and membrane supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Alkaline Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
West Africa Battery Market
Batteries
Lead Carbon Battery Market
Batteries
N-Type Battery Market
Batteries
Global Primary Cells Market
Batteries
Hybrid Flow Battery Market
Batteries
Drone Power Sources Market
Batteries
Battery Anode Materials Market
Batteries
DMC for Battery Market
Batteries
Dry Cell Battery Market
Batteries
Medical Batteries Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Mobile Battery Market
Batteries
Solid Electrolyte Market