
 Semi-Solid Flow Battery Market | 2026-2036
Semi-Solid Flow Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Semi-Solid Flow Battery Market Insights
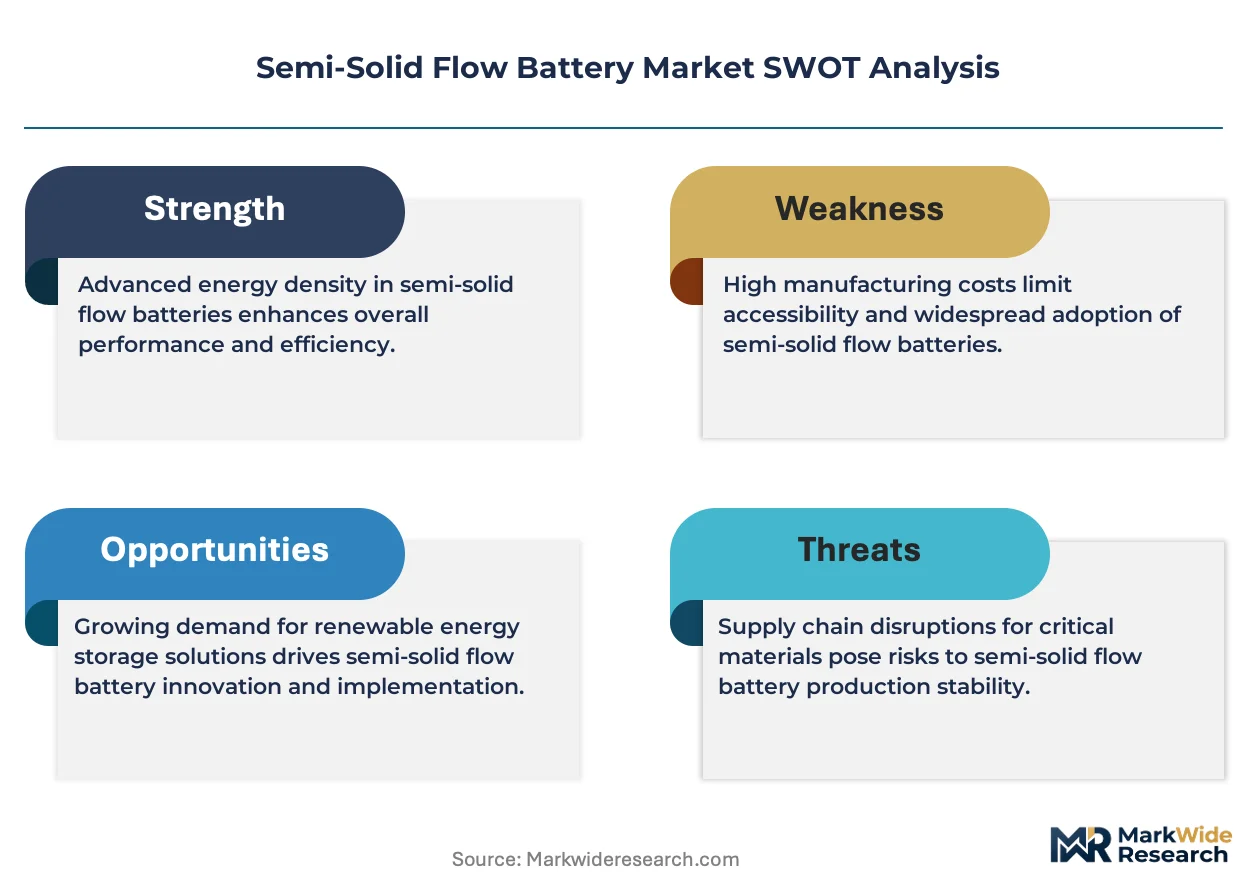
Electrolyte engineering talent is bifurcating the competitive landscape as PhD-level expertise in slurry electrochemistry remains scarce. ESS Tech Inc. leverages its iron-flow platform to anchor utility-scale deployments across North America. Invinity Energy Systems dominates vanadium-based installations with proven operational data from grid-connected projects. Sumitomo Electric Industries sustains manufacturing scale through backward integration into electrolyte precursor production.
Semi-solid flow batteries store energy in pumped slurries of active material suspended in liquid electrolyte, typically achieving energy densities of 20-40 Wh/L while decoupling power and capacity for flexible scaling. These systems serve commercial and industrial applications requiring 4-12 hour discharge durations where lithium-ion degradation costs prove prohibitive. Redox flow technology occupies the mature installation base with decades of operational validation, while zinc-bromine chemistries represent the fastest-growing segment as developers target cost parity with peaker plants. Utility Companies concentrate procurement volume under long-term power purchase agreements, whereas Industrial Sector buyers prioritize behind-the-meter resilience against tariff volatility.
FERC Order 2222 enables distributed energy resource aggregation, directly expanding addressable market access for semi-solid flow systems in wholesale markets. EPA greenhouse gas standards for power generation create compliance-driven demand for zero-emission long-duration storage paired with renewable assets. California's CPUC mandates 1,000 MW of non-lithium storage by specified procurement deadlines, establishing a regulatory template other state commissions evaluate. Stakeholders must monitor which chemistry platforms secure certification under evolving UL 9540A fire safety protocols before committing capital to manufacturing expansion.
Market Dynamics
Utility procurement mandates for non-lithium long-duration storage are compressing technology qualification timelines while electrolyte engineering scarcity concentrates competitive advantage among firms with captive R&D pipelines.
Growth Catalysts
- State-level procurement mandates:California's CPUC directive for 1,000 MW of non-lithium storage establishes procurement templates that Texas and New York regulators evaluate for adoption.
- Iron-flow chemistry maturation:Decades of operational data from grid-connected vanadium systems now validates semi-solid architectures for risk-averse utility buyers.
- FERC Order 2222 implementation:Distributed energy resource aggregation rules expand addressable market access for behind-the-meter semi-solid systems in wholesale electricity markets.
Market Restraints
- Electrolyte precursor supply concentration:Vanadium pentoxide refining capacity clusters in South Africa and China, exposing project developers to geopolitical supply disruptions.
- PhD-level slurry electrochemistry scarcity:University programs graduate fewer than fifty specialists annually, constraining scale-up velocity for commercial deployments.
- UL 9540A certification timelines:Fire safety protocol validation requires eighteen to twenty-four months, delaying utility interconnect approvals.
Strategic Opportunities
- Zinc-bromine cost parity targeting:Developers in Germany and Texas pursue manufacturing scale sufficient to undercut peaker plant economics on an LCOE basis.
- Behind-the-meter industrial resilience:C&I buyers in tariff-volatile jurisdictions seek 4-12 hour discharge systems to arbitrage time-of-use electricity pricing.
- ARPA-E funding redirection:Non-lithium chemistry grants from the US Department of Energy accelerate pilot-to-commercial transitions for novel electrolyte formulations.
Industry Challenges
- Electrolyte formulation IP thickets:Patent estates held by legacy redox flow developers complicate freedom-to-operate analysis for zinc-bromine entrants.
- Interconnection queue congestion:Utility-scale projects face thirty-six month grid connection delays in high-penetration renewable zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semi-Solid Flow Battery Market |
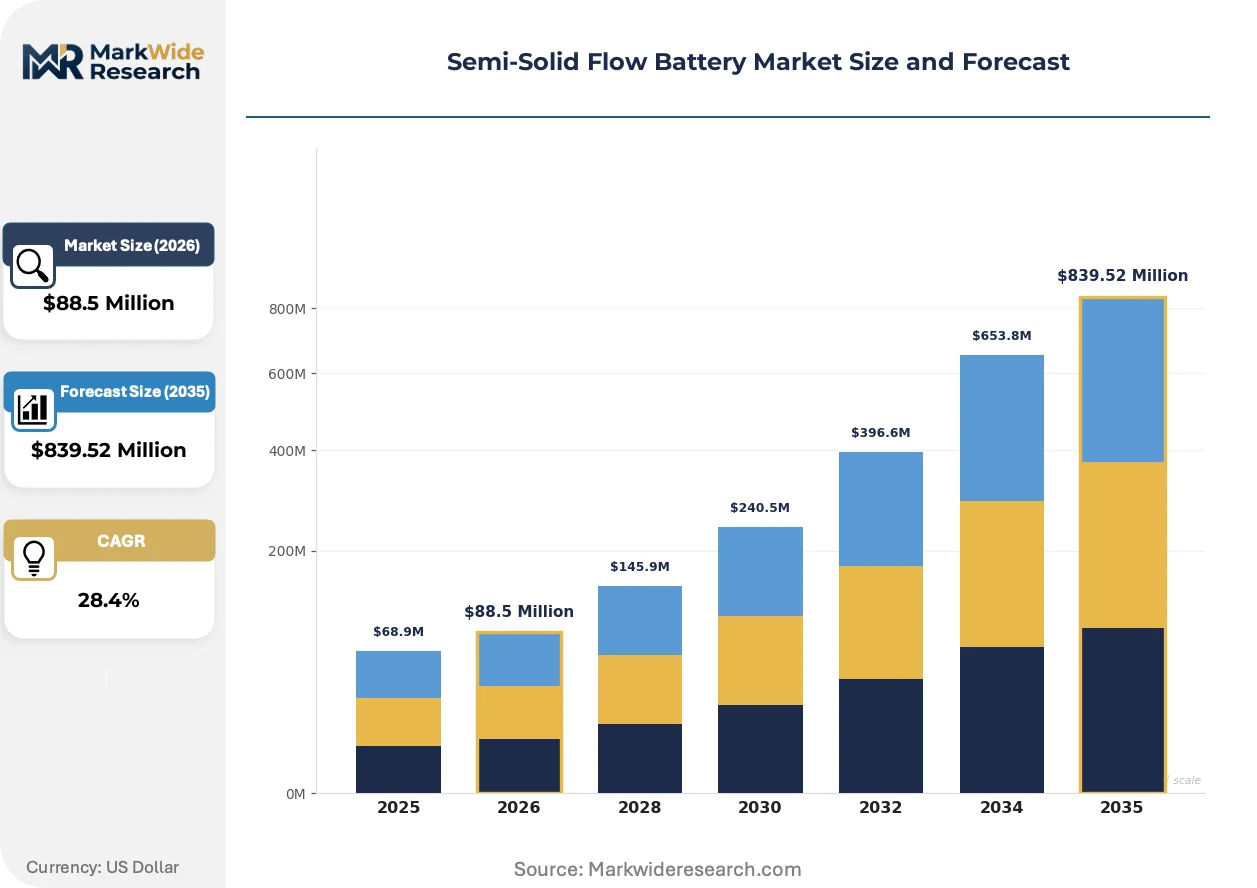
| Market Size in 2026 | $88.5 Million |
| Market Size in 2035 | $839.52 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Redox Flow, Lithium-Ion, Sodium-Ion, Zinc-Bromine Application: Renewable Energy, Grid Storage, Electric Vehicles, Backup Power End User: Utility Companies, Industrial Sector, Residential Users, Commercial Buildings Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | ESS Tech Inc., Invinity Energy Systems, Sumitomo Electric Industries, Ltd., CellCube (Enerox GmbH), VRB Energy, Largo Inc., Lockheed Martin Corporation, Primus Power Solutions, UniEnergy Technologies, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semi-Solid Flow Battery Market Trends and Innovations
Semi-solid architectures are displacing conventional redox flow systems in utility procurement portfolios as energy density advantages compound with manufacturing learning curves.
Zinc-bromine semi-solid chemistries are displacing aqueous vanadium systems in 4-8 hour duration tenders. Texas and California independent power producers now specify slurry-based architectures for greenfield solar-plus-storage projects. The technology is displacing lithium-ion in applications where degradation-driven replacement costs exceed capital expenditure differentials.
EPA greenhouse gas standards for power generation create compliance-driven procurement for zero-emission storage paired with renewable assets. Industrial facilities subject to emissions caps now prioritize long-duration systems in capital planning cycles. Utilities in coal-dependent states accelerate semi-solid pilot programs to preempt regulatory penalties.
Long-term power purchase agreements are supplanting equipment-only transactions as the dominant commercial structure. Utility buyers now require fifteen to twenty-year performance guarantees backed by operational data from grid-connected reference projects. This contracting evolution concentrates procurement volume among developers with proven manufacturing scale and electrolyte supply chain control.
Semi-Solid Flow Battery Market Segmentation
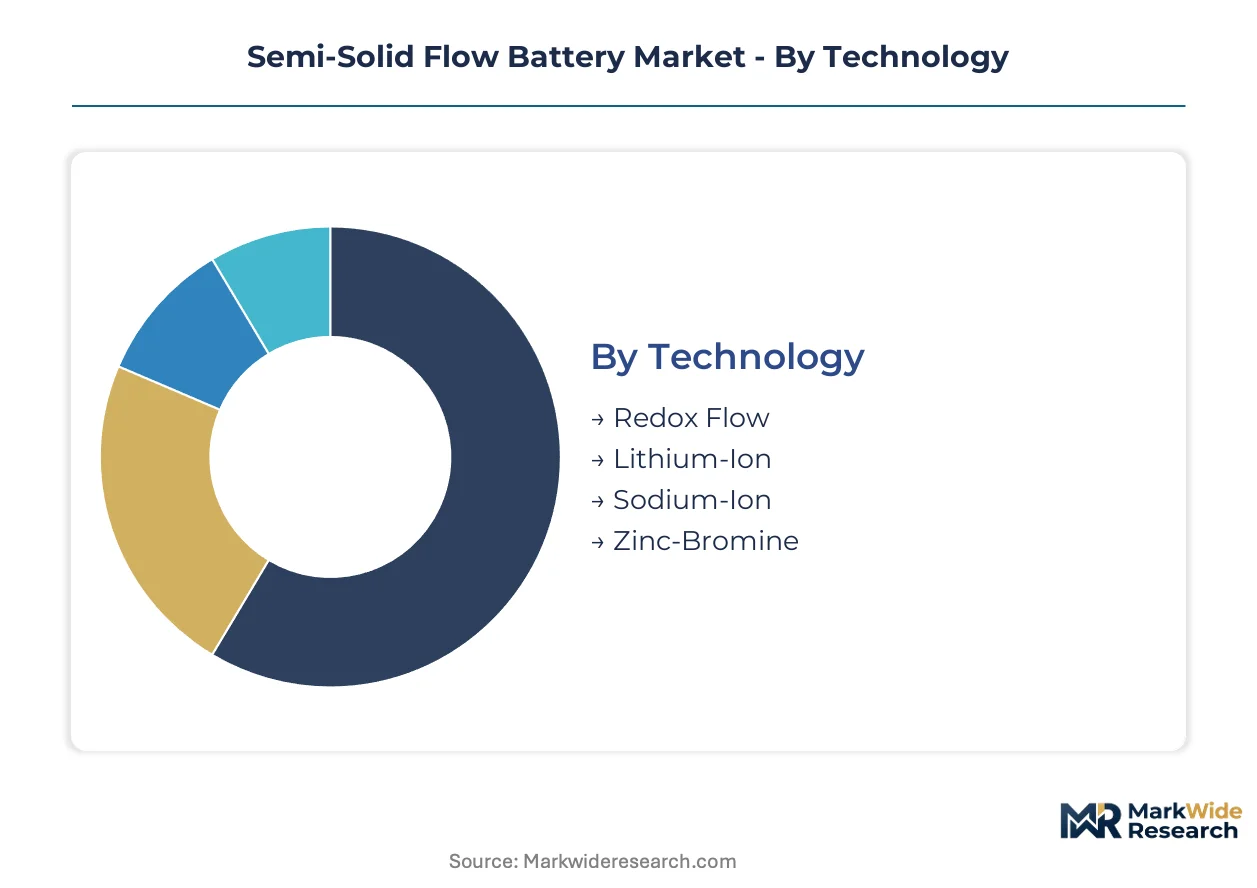
Technology-platform differentiation determines procurement economics as utility buyers weigh degradation profiles against capital intensity. Application-specific duty cycles and end-user risk appetites further stratify vendor targeting strategies across deployment scales.
Technology:
Redox flow architectures face intensifying substitution pressure from zinc-bromine semi-solid systems targeting cost parity with gas peakers.
- Redox Flow:Vanadium-based aqueous chemistries deliver 20+ year operational lifespans with minimal capacity fade. Utility procurement in Germany and Texas concentrates here where long-duration cycling economics outweigh upfront capital premiums.
- Zinc-Bromine:Semi-solid slurry architectures achieve 40% higher energy density than conventional flow systems while eliminating membrane degradation pathways. Developers in California and Texas now specify zinc-bromine for 4-8 hour solar-plus-storage tenders.
- Lithium-Ion:Dominant in short-duration applications below four hours where manufacturing scale compresses unit costs.
- Sodium-Ion:Emerging chemistry targeting cost-sensitive grid storage with abundant precursor availability.
Redox flow retains volume leadership among risk-averse utility buyers; zinc-bromine holds the steepest expansion curve as semi-solid manufacturing matures.
Application:
Cost-tier stratification separates premium long-duration contracts from commoditized short-cycling equipment sales.
- Grid Storage:Utility-scale deployments requiring 4-12 hour discharge durations dominate procurement volume. FERC Order 2222 aggregation rules in the United States expand revenue stacking opportunities for behind-the-meter assets participating in wholesale markets.
- Renewable Energy:Solar-plus-storage and wind-plus-storage configurations mandate storage co-location to firm intermittent generation. California CPUC mandates for non-lithium storage accelerate iron-flow and zinc-bromine pilot deployments.
- Backup Power:Critical facility resilience applications prioritize instantaneous response over cycling economics.
- Electric Vehicles:Mobility applications favor energy density over duration, limiting semi-solid flow penetration.
Grid storage commands the premium pricing tier; renewable energy co-location projects are expanding most quickly as IRA incentives compress project finance costs.
End User:
Customer-type concentration clusters procurement authority among entities with balance-sheet capacity for fifteen-year performance contracts.
- Utility Companies:Vertically integrated generators and independent power producers issue long-term power purchase agreements requiring operational data from grid-connected reference projects. Procurement timelines stretch thirty-six months including interconnection queue delays.
- Industrial Sector:Behind-the-meter installations at manufacturing facilities and data centers target tariff arbitrage and resilience against grid instability. German industrial buyers lead European adoption as electricity price volatility exceeds storage capital recovery thresholds.
- Commercial Buildings:Office and retail properties with predictable load profiles evaluate 4-hour systems for demand charge management.
- Residential Users:Single-family and multi-family deployments remain marginal due to footprint constraints and soft costs.
Utility companies anchor procurement volume through standardized tender structures; industrial sector buyers are gaining share fastest as C&I solar-plus-storage economics improve.
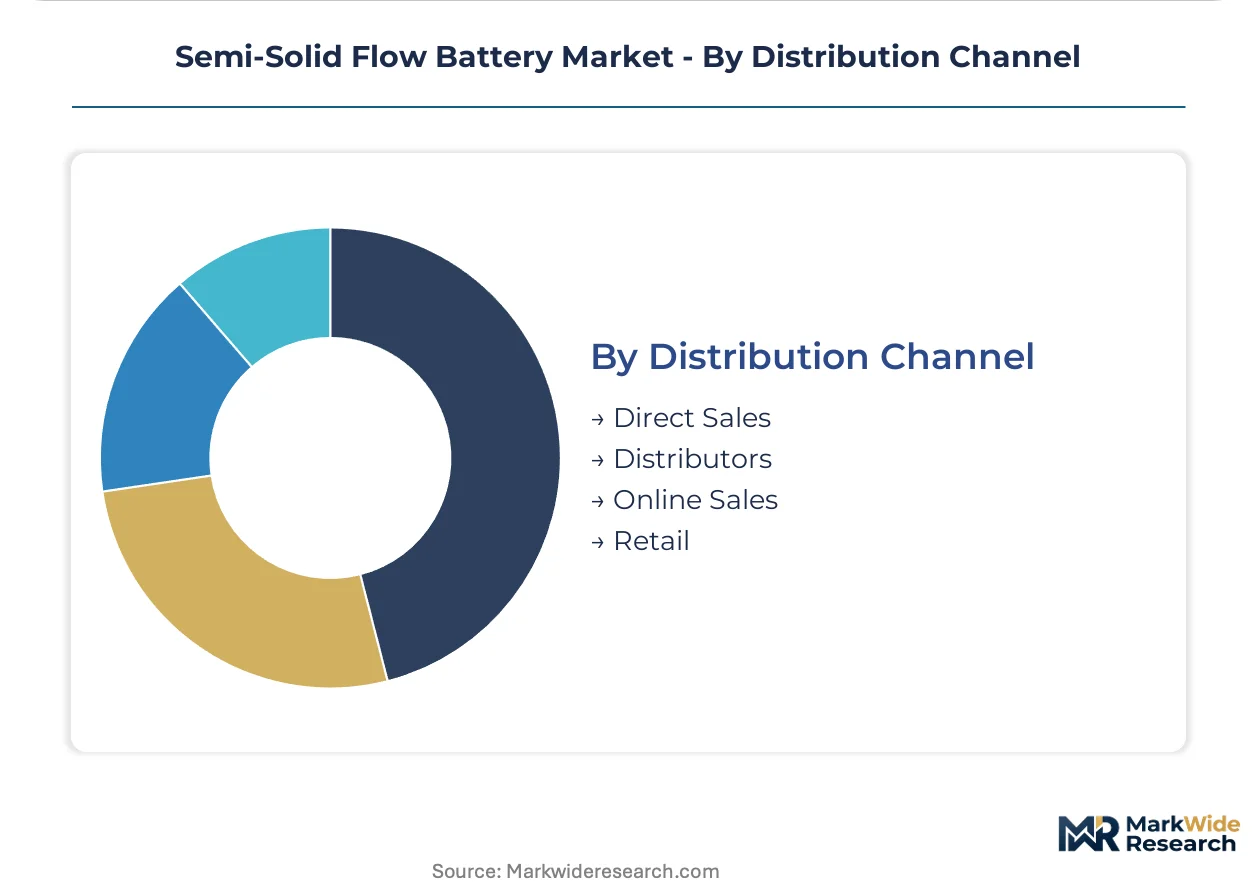
Distribution Channel:
Supply concentration in electrolyte precursor refining shapes channel economics and geographic availability.
- Direct Sales:Original equipment manufacturers engage utility and industrial buyers through dedicated account teams. ESS Tech and Invinity Energy Systems deploy field engineering resources for project development support.
- Distributors:Regional equipment wholesalers serve commercial building and small-scale industrial segments with standardized system configurations.
- Online Sales:Digital procurement platforms facilitate component sourcing for system integrators and EPC contractors.
- Retail:Limited to ancillary components and monitoring hardware rather than complete energy storage systems.
Direct sales dominate value capture; distributor networks are climbing the fastest as commercial segment standardization reduces technical pre-sales requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 2222 and California's CPUC mandates anchor North American procurement gravity, while Germany's industrial electricity tariffs and China's dual carbon goals concentrate manufacturing investment across three continents.
United States
Utility-scale solar-plus-storage tenders in Texas and California specify semi-solid architectures for 4-8 hour durations. The Inflation Reduction Act production tax credits compress project finance costs for iron-flow deployments. Houston and Austin clusters host independent power producers aggregating behind-the-meter assets under FERC Order 2222 rules.
Germany
Industrial facilities in Bavaria and North Rhine-Westphalia procure vanadium systems to arbitrage volatile day-ahead electricity pricing. The EU Green Deal carbon border adjustment mechanism accelerates coal plant retirement timelines. ESS Tech and CellCube maintain project development offices in Munich serving C&I buyers.
China
State Grid Corporation pilots zinc-bromine installations in Gansu and Qinghai provinces paired with wind generation assets. MIIT battery industry guidelines prioritize non-lithium chemistries for grid-scale applications. Yangtze River Delta electrolyte precursor refineries supply vanadium pentoxide to domestic integrators.
Japan
METI long-duration storage subsidies fund demonstration projects at Hokkaido wind farms requiring 6-12 hour discharge capability. Sumitomo Electric Industries leverages captive electrolyte production from Osaka chemical complexes. Kansai Electric Power evaluates semi-solid alternatives to pumped hydro for frequency regulation.
Semi-Solid Flow Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with electrolyte engineering depth separating premium-tier vendors from assembly-focused integrators. The vendor base concentrates among firms with decade-plus operational data and captive precursor supply. Three strategic archetypes dominate: vanadium-based incumbents with proven grid-connected track records, iron-flow specialists targeting utility-scale procurement mandates, and zinc-bromine developers pursuing manufacturing scale for peaker plant parity. Competitive moves center on backward integration into electrolyte refining and fifteen-year performance guarantee underwriting.
Among North American developers, ESS Tech Inc. exemplifies the iron-flow archetype with utility-scale deployment concentration, while Invinity Energy Systems occupies the vanadium-based position through operational data accumulation. Sumitomo Electric Industries represents the integrated industrial conglomerate model with in-house electrolyte precursor production. These three firms anchor procurement shortlists for risk-averse utility buyers requiring grid-connected reference projects.
| Leading Market Players |
|---|
| ESS Tech Inc. |
| Invinity Energy Systems |
| Sumitomo Electric Industries, Ltd. |
| CellCube (Enerox GmbH) |
| VRB Energy |
| Largo Inc. |
| Lockheed Martin Corporation |
| Primus Power Solutions |
| UniEnergy Technologies, LLC |
| Others |
Pricing and Supply Chain Analysis
Manufacturing scale in Yangtze River Delta electrolyte refineries compresses unit costs for vanadium pentoxide while simultaneously concentrating pricing power among South African and Chinese producers. This scale asymmetry creates divergent price floors across procurement regions.
Pricing Analysis
Texas and California utility tenders exhibit 15-20% price spreads against German industrial contracts, reflecting divergent risk premiums and after-sales service bundling. Project-based long-term offtake agreements dominate utility procurement, while commercial buyers face spot-price volatility for electrolyte replenishment. Cost compression in zinc-bromine systems stems from manufacturing learning curves in Texas and China. Industrial sector buyers demonstrate highest price sensitivity due to capital recovery thresholds, whereas utility companies accept premium pricing for fifteen-year performance guarantees.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes vanadium pentoxide shipments from South African refineries to Middle Eastern project sites. Supply concentrates in China, South Africa, and Russia for vanadium pentoxide feedstock, with bromine extraction anchored in Dead Sea chemical complexes and Arkansas brine operations. The chain draws from membrane manufacturing in Germany, bipolar plate fabrication in Japan, and pump assembly in the United States. Single-source vulnerability in South African vanadium refining creates geopolitical exposure. Distribution runs through direct OEM-to-utility channels for large projects, with regional distributors serving commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PhD-level slurry electrochemistry expertise functions as the binding constraint on commercial deployment velocity, with fewer than fifty annual graduates available to serve expanding manufacturing pipelines.
For Market Incumbents: Shield established market positions by accelerating backward integration into electrolyte precursor production and securing captive vanadium pentoxide offtake from South African refiners. Invest in UL 9540A certification pipelines ahead of interconnect queue deadlines to preempt zinc-bromine substitution threats in California and Texas procurement cycles. For New Entrants and Emerging Players: Lead with behind-the-meter industrial resilience applications in tariff-volatile German jurisdictions, where electricity price arbitrage economics exceed grid-scale tender complexity. Target 4-8 hour duration commercial installations through standardized system configurations and regional distributor partnerships rather than direct utility sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among iron-flow developers with fifteen-year power purchase agreement backlogs and operational data from grid-connected reference projects. Long-term viability hinges on electrolyte engineering depth and manufacturing scale sufficient to underwrite performance guarantees. Monitor FERC Order 2222 implementation velocity as the inflection indicator for distributed energy resource aggregation revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Precursor Backward Integration | Captive vanadium pentoxide supply from South African refiners insulates against geopolitical disruption. |
| UL 9540A Fire Safety Certification | California CPUC mandates require validated thermal runaway protocols for interconnect approval. |
| Long-term Power Purchase Agreements | Fifteen-year performance guarantees concentrate procurement volume among proven manufacturers. |
| Zinc-Bromine Manufacturing Scale-Up | Texas and German production expansion targets cost parity with gas peaker plants. |
| FERC Order 2222 Aggregation Platforms | Behind-the-meter asset participation in wholesale markets expands addressable revenue streams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FERC interconnection filings, EIA storage deployment databases, and ARPA-E funding disclosures. Utility planning officers, IPP project developers, EPC contractors, and electrolyte engineering specialists provided operational perspectives on technology qualification timelines. Secondary validation drew from CPUC procurement mandate documents, EPA greenhouse gas standard rulemakings, and NREL technical reports. Bottom-up project pipeline aggregation triangulates against top-down market sizing from manufacturing capacity announcements.
Segmentation dimensions modeled span technology platform, application duty cycle, end-user procurement authority, and distribution channel structure across the projection horizon. CAGRs derive from electrolyte cost trajectory assumptions, manufacturing learning curve coefficients, and regulatory mandate implementation schedules. Forecast inputs incorporate interconnection queue duration estimates, UL certification timeline distributions, and state-level procurement target fulfillment rates.
Forecasts assume regulatory continuity in FERC Order 2222 implementation and California CPUC mandate enforcement; material policy shifts would require re-modeling aggregation revenue potential and procurement volume timing. Technology substitution risks from lithium-ion cost declines or sodium-ion maturation could revise chemistry-specific growth trajectories. Practitioners should keep alternative scenarios live as electrolyte precursor supply stability and fire safety protocol evolution reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Italy SLI Battery Market
Batteries
America SLI Battery Market
Batteries
Flow Battery Market
Batteries
North America Industrial Battery Market
Batteries
Drone Power Sources Market
Batteries
Seawater Battery Market
Batteries
Global Primary Cells Market
Batteries
South Europe Battery Market
Batteries
Iron Salt Battery Market
Batteries
India Micro Batteries Market
Batteries
South America Rechargeable Battery Market
Batteries
North Europe Battery Market
Batteries
Aluminum Based Battery Market
Batteries
Aluminum-Air Battery Market
Batteries
Japan Rechargeable Battery Market
Batteries
Battery Swapping Market