
 Mobile Mapping Systems Market | 2026-2036
Mobile Mapping Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Mapping Systems Market Outlook
Multi-source procurement of LiDAR sensors and GNSS receivers is consolidating around vertically integrated platform providers. Trimble Inc. leverages its agriculture and construction channel density to bundle mobile mapping with field software ecosystems. Leica Geosystems AG anchors its position through R&D intensity in laser scanning subsystems. Hexagon AB extends its reach via backward integration into geospatial analytics software that consumes raw mapping feeds.
Mobile mapping systems integrate vehicle-mounted LiDAR, photogrammetry, GNSS, and inertial measurement units to generate georeferenced 3D point clouds and imagery at highway speeds, typically achieving absolute accuracies of 2-5 centimeters in survey-grade configurations. Their primary purpose spans civil engineering corridor mapping, urban digital twin construction, and precision agriculture terrain modeling. LiDAR product types dominate revenue owing to superior canopy penetration and all-weather operability, while hybrid systems represent the fastest-expanding category as operators blend optical and laser sensors to reduce single-technology risk. On the application side, asset management commands widening margins because recurring inspection contracts generate sustained data-service revenue beyond hardware sales.
Europe's EARSC geospatial standards and the EU Green Deal spatial data mandates shape product certification requirements for cross-border infrastructure projects. The US Federal Highway Administration's survey accuracy specifications and OSHA work-zone safety rules directly determine sensor resolution and vehicle-integration protocols for domestic contractors. China's MIIT GB standards and dual carbon goals are redirecting procurement toward electric-vehicle-compatible mapping platforms with reduced power draw. Stakeholders must decide whether to absorb regulatory compliance costs in-house or partner with certified local integrators as data sovereignty rules fragment.
Market Dynamics
EU AI Act compliance mandates and GDPR data sovereignty rules are forcing mobile mapping operators to re-architect cloud pipelines and localize processing nodes, compressing vendor margins while creating certification barriers for non-EU platform providers.
Growth Catalysts
- EU Green Deal spatial data mandates:Infrastructure funds in Germany, France, and the Netherlands now require survey-grade mobile mapping for carbon accounting verification on transport corridors.
- Smart city digital twin construction:Municipal procurement in Barcelona, Copenhagen, and Vienna is accelerating adoption of vehicle-mounted LiDAR for real-time urban asset monitoring.
- Precision agriculture terrain modeling:Farm cooperatives across Denmark and the Netherlands are deploying mobile mapping for variable-rate irrigation and drainage optimization.
Market Restraints
- LiDAR sensor supply concentration:Core solid-state and mechanical LiDAR subsystems depend on a limited set of East Asian component foundries, exposing European integrators to allocation risk.
- GDPR cross-border data friction:The regulation's territorial scope and adequacy requirements block seamless transfer of raw geospatial point clouds to non-EU processing centers.
- High-precision GNSS correction costs:Subscription fees for RTK and PPP-RTK services add recurring operational burden on small surveying contractors.
Strategic Opportunities
- Poland and Romania transport corridors:EU cohesion fund investments in highway and rail modernization are opening procurement windows for mobile mapping services in underpenetrated CEE markets.
- Hybrid sensor convergence:Platforms combining LiDAR, photogrammetry, and thermal imaging are capturing inspection contracts for district heating networks and electrical substations.
- CSRD sustainability reporting:The directive's spatial data requirements for infrastructure asset condition disclosure is creating recurring revenue streams for mapping-as-a-service providers.
Industry Challenges
- Geodetic surveyor talent scarcity:The specialized skill set combining GNSS post-processing, inertial navigation, and point cloud classification faces generational replacement gaps across EU member states.
- CE marking timeline compression:New machinery directive amendments and radio equipment certification for 5G-connected mapping vehicles are extending product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Mapping Systems Market |
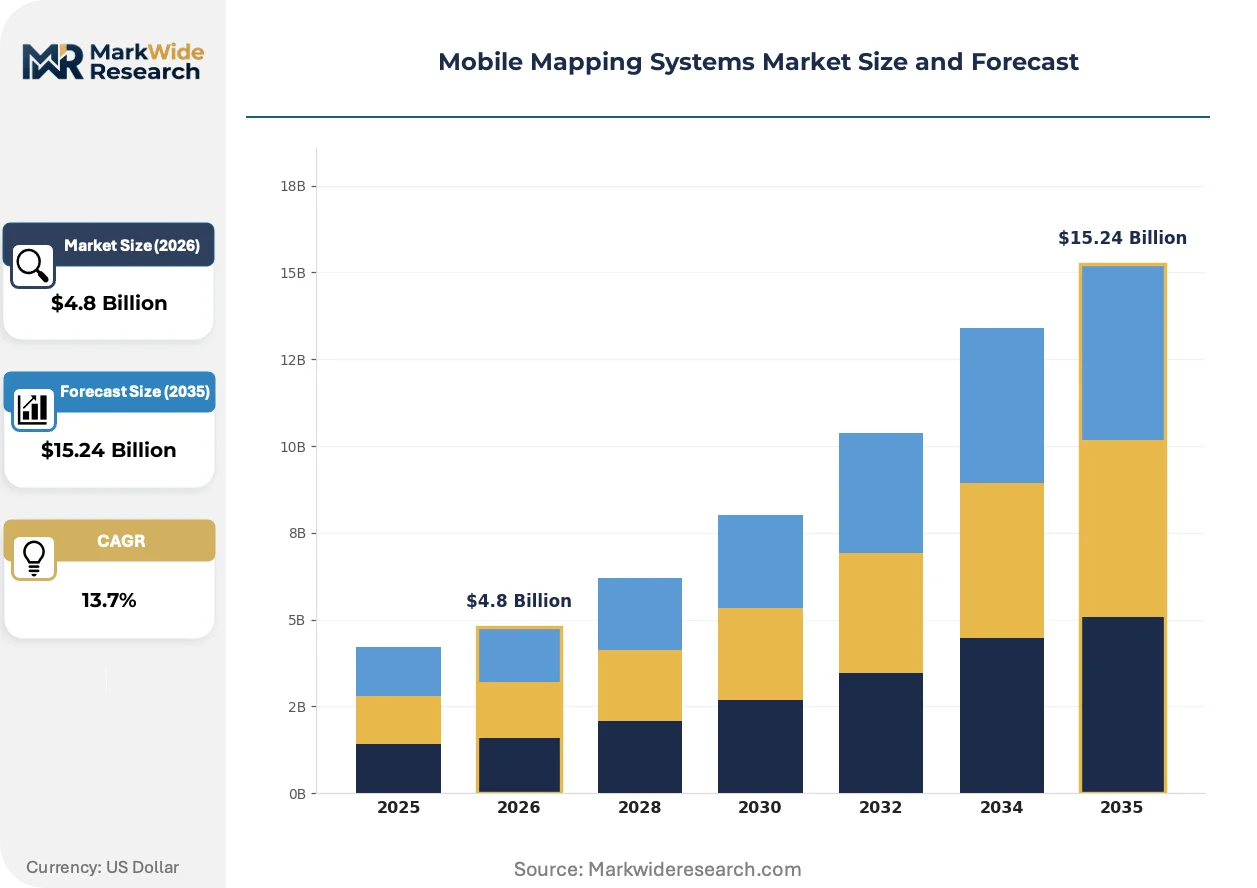
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LiDAR, Photogrammetry, GNSS, Hybrid Systems Application: Civil Engineering, Agriculture, Urban Planning, Asset Management Technology: 3D Imaging, GPS, Laser Scanning, Mobile GIS End User: Government, Construction, Transportation, Public Safety |
| Companies Covered | Trimble Inc., Leica Geosystems AG, Topcon Corporation, Teledyne Optech Inc., RIEGL Laser Measurement Systems GmbH, GeoSLAM Ltd., FARO Technologies Inc., imajing SAS, Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Mapping Systems Market Strategic Shifts
Solid-state LiDAR architectures and edge-computing pipelines are compressing hardware footprints while elevating real-time data quality, enabling new deployment modes that bypass traditional vehicle-integration constraints.
Solid-state MEMS LiDAR is integrating photonic beam-steering chips with silicon photonics substrates to eliminate mechanical rotation assemblies. Civil engineering contractors in Germany and Sweden are adopting these units for drone and backpack deployments where vibration tolerance matters. The technology is integrating mobile mapping into confined infrastructure assets—tunnels, culverts, and bridge interiors—previously inaccessible to vehicle-mounted systems.
The EU AI Act's risk-classification framework for biometric and geospatial AI is mandating conformity assessments for automated feature-extraction algorithms. Mapping platform vendors must now document training data provenance and model drift monitoring for infrastructure inspection outputs. German automotive suppliers and French utility operators are demanding certified algorithmic transparency as a procurement gate, favoring providers with in-house MLOps audit trails.
Subscription-based data-service contracts are displacing perpetual hardware sales in municipal and utility segments. Danish and Dutch water authorities now procure annual corridor-monitoring subscriptions rather than capitalizing mobile mapping systems directly. This shift concentrates buyer power among platform operators with captive cloud infrastructure, squeezing independent survey contractors into subcontractor roles.
Mobile Mapping Systems Market Segmentation
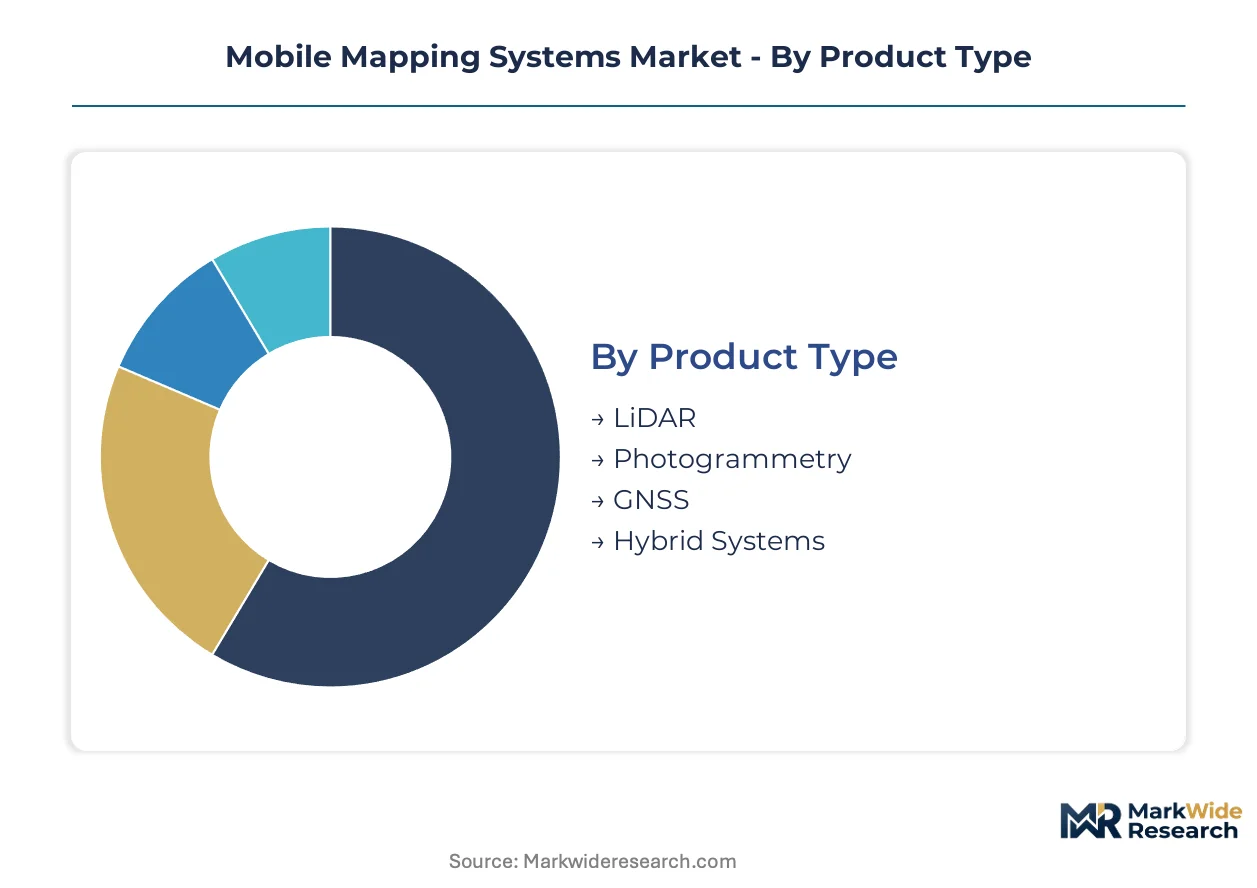
Mobile mapping systems fragment across four dimensions that determine procurement priorities and vendor positioning. Product type dictates hardware margins and sensor replacement cycles. Application focus shapes whether contracts emphasize capital equipment or recurring data services. Technology architecture and end-user verticals further refine competitive differentiation in a market where precision requirements vary sharply by use case.
Product Type:
Upgrade cycles in mobile mapping hardware concentrate around sensor obsolescence timelines and accuracy threshold improvements that trigger fleet replacement decisions.
- LiDAR:Vehicle-mounted laser scanning subsystems generate dense 3D point clouds through time-of-flight or phase-shift measurement, achieving survey-grade absolute accuracies of 2-5 centimeters. German civil engineering contractors and French utility operators prioritize LiDAR for transport corridor mapping where canopy penetration and all-weather operability override cost considerations.
- Photogrammetry:Optical imaging arrays with calibrated stereo baselines reconstruct surfaces through multi-view geometry, offering color texture capture that LiDAR cannot match. Danish agricultural cooperatives and Dutch water authorities select photogrammetry for terrain modeling where vegetation cover is sparse and spectral classification adds value.
- GNSS:Multi-constellation receivers with RTK or PPP-RTK correction integrate with inertial units for georeferencing without optical or laser sensors. Standalone GNSS dominates budget-constrained municipal surveys in Poland and Romania where infrastructure density permits satellite visibility.
- Hybrid Systems:Fused LiDAR-photogrammetry-GNSS platforms reduce single-technology risk through sensor redundancy. These configurations are gaining procurement share in Barcelona and Copenhagen smart city tenders where digital twin completeness requirements mandate multi-source data capture.
LiDAR sits at the top of the volume ranking, with hybrid systems climbing the fastest.
Application:
Contract structures diverge sharply across application verticals, with some segments favoring perpetual hardware sales and others locking vendors into multi-year data-service subscriptions.
- Civil Engineering:Corridor mapping for highways, railways, and utilities demands survey-grade accuracy specifications that filter procurement toward established platform providers. German federal transport infrastructure funds and EU Green Deal carbon accounting mandates are accelerating replacement of static total station workflows with mobile systems.
- Agriculture:Variable-rate irrigation and drainage optimization in Denmark and the Netherlands deploy vehicle-mounted or drone-integrated mapping for sub-field terrain modeling. Farm cooperatives favor subscription-based data delivery over capital expenditure, compressing hardware vendor margins.
- Urban Planning:Municipal digital twin construction in Vienna and Barcelona requires repeated capture cycles for change detection, creating recurring revenue pools for platform operators with captive cloud infrastructure.
- Asset Management:Infrastructure condition monitoring for district heating networks and electrical substations commands premium pricing through inspection contracts that bundle sensor deployment with automated defect detection algorithms.
Civil engineering dominates current procurement volumes, while asset management is expanding most quickly through recurring contract structures.
Technology:
Technology selection in mobile mapping follows a maturity curve where established methods face displacement from integrated platforms that compress data processing latency.
- 3D Imaging:Volumetric reconstruction pipelines fuse point clouds with photorealistic textures for immersive visualization and measurement. Swedish tunnel inspection contractors and German bridge maintenance authorities specify 3D imaging deliverables for structural deformation monitoring.
- GPS:Multi-frequency GNSS reception with real-time kinematic correction remains the foundational georeferencing layer across all mobile mapping configurations. High-precision correction subscription costs burden small surveying contractors in fragmented European markets.
- Laser Scanning:Time-of-flight and phase-based LiDAR subsystems provide direct range measurement independent of ambient illumination. Solid-state MEMS architectures are displacing mechanical rotating assemblies in confined-space deployments.
- Mobile GIS:Edge-computing pipelines with on-vehicle classification and feature extraction reduce cloud transfer volumes and address GDPR data sovereignty constraints. French utility operators and German automotive suppliers demand certified algorithmic transparency for automated outputs under EU AI Act risk classifications.
Laser scanning leads technology deployment by revenue, with mobile GIS gaining share fastest through regulatory pressure for localized processing.
End User:
End-user verticals concentrate buying power unevenly, with government and transportation segments consolidating procurement through framework agreements that squeeze independent contractors.
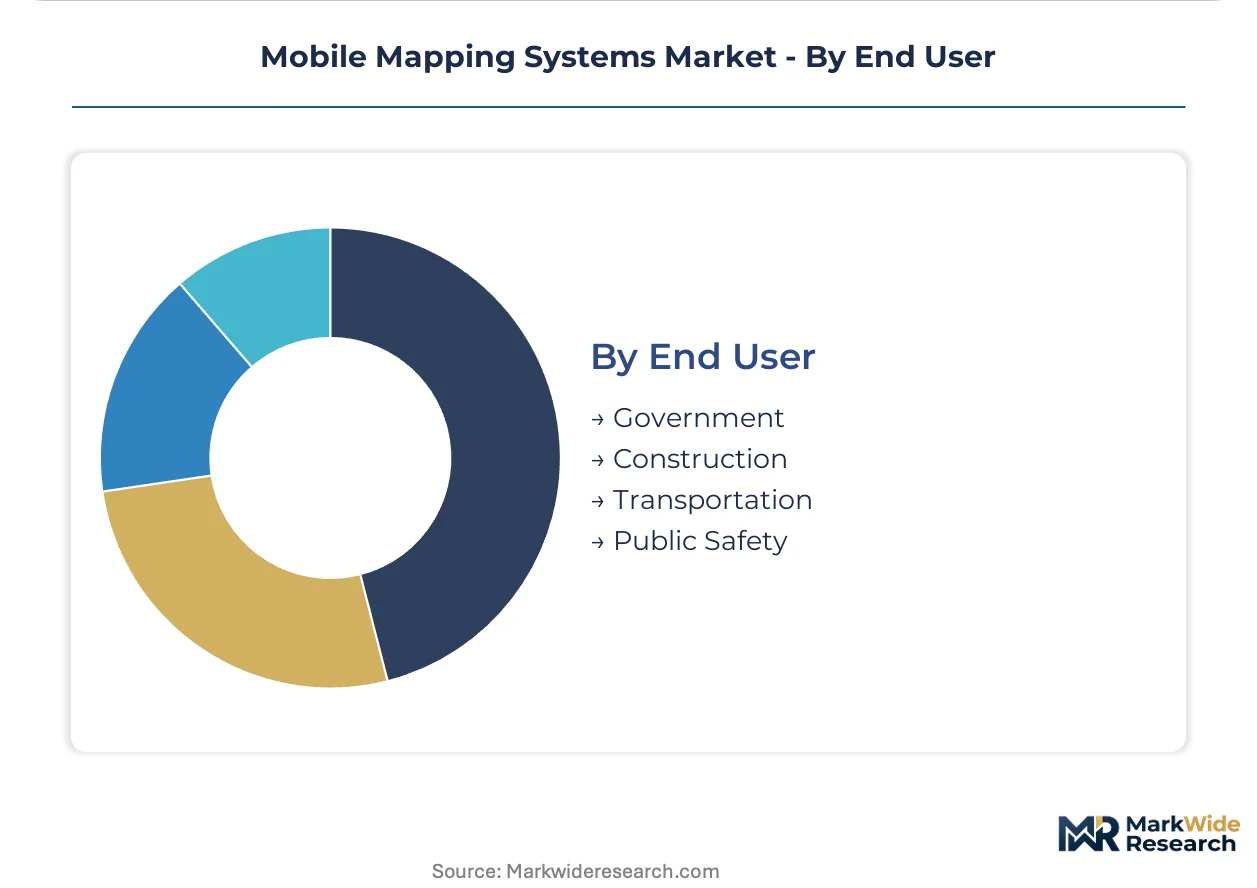
- Government:National mapping agencies and environmental regulators in Germany, France, and the Netherlands specify survey-grade accuracy and cross-border data interoperability. EU Green Deal spatial data mandates and CSRD sustainability reporting requirements are redirecting procurement budgets toward carbon verification workflows.
- Construction:Civil engineering firms and earthworks contractors prioritize productivity gains from rapid corridor capture over absolute precision. Equipment rental channels and field software ecosystems influence platform selection in fragmented contractor markets.
- Transportation:Railway operators and highway authorities in Poland and Romania are opening procurement windows through EU cohesion fund investments in corridor modernization. Inspection contracts for track geometry and pavement condition favor vendors with certified measurement protocols.
- Public Safety:Emergency response and disaster management agencies deploy mobile mapping for rapid post-event damage assessment. Thermal imaging integration for search-and-rescue and wildfire perimeter mapping is emerging in Mediterranean member states.
Government accounts anchor procurement volumes, with transportation climbing fastest through infrastructure fund deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory compliance costs in the European Union are pushing mobile mapping procurement toward jurisdictions with streamlined certification pathways, while infrastructure fund deployment concentrates demand in Germany, France, and emerging Central European corridors.
Germany
Federal transport infrastructure investments and automotive supplier precision requirements dominate procurement volumes. The KBA vehicle certification framework and EU AI Act conformity assessments filter platform selection toward vendors with documented algorithmic transparency. Munich and Stuttgart industrial clusters anchor demand for solid-state LiDAR integration in confined-space tunnel inspections.
France
Utility operator digital twin mandates and CSRD sustainability reporting requirements redirect procurement budgets toward recurring data-service contracts. ANSM data governance guidelines and CNIL oversight shape cross-border point cloud transfer protocols. Lyon and Paris metropolitan authorities concentrate smart city tender activity for vehicle-mounted corridor monitoring systems.
United States
Federal Highway Administration survey accuracy specifications and OSHA work-zone safety rules determine sensor resolution thresholds for domestic contractors. The FAA unmanned aircraft systems integration office influences drone-mounted mapping deployment protocols. California and Texas transportation departments lead state-level procurement for pavement condition assessment networks.
China
MIIT GB standards and dual carbon goals redirect procurement toward electric-vehicle-compatible platforms with reduced power draw. The national spatial data infrastructure initiative concentrates demand in Yangtze River Delta and Pearl River Delta megacity clusters. Shanghai and Shenzhen municipal governments prioritize real-time urban asset monitoring for digital twin construction.
Poland
EU cohesion fund investments in highway and rail modernization are opening procurement windows previously dominated by static surveying methods. National road authority technical specifications align with European Committee for Standardization geodetic frameworks. Warsaw and Kraków engineering consortia are consolidating mobile mapping service capacity for corridor modernization contracts.
Mobile Mapping Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue solid-state miniaturization and edge-computing integration. The vendor base stratifies across three tiers: integrated platform operators with captive software ecosystems, component specialists supplying laser scanning subsystems, and regional service providers bunding hardware with local survey expertise. Dominant competitive moves include backward integration into geospatial analytics software and strategic partnerships with automotive OEMs for vehicle-integrated deployment channels.
Within the integrated platform tier, Trimble Inc. and Hexagon AB exemplify archetypes combining hardware distribution density with field software ecosystems. Leica Geosystems AG occupies a position representing precision optics heritage and R&D intensity in laser measurement subsystems. Among component specialists, RIEGL Laser Measurement Systems GmbH and Teledyne Optech Inc. anchor the high-performance LiDAR subsystem segment. Emerging entrants including GeoSLAM Ltd. and imajing SAS sit within the mobile-first archetype pursuing backpack and handheld form factors that bypass traditional vehicle-integration constraints.
| Leading Market Players |
|---|
| Trimble Inc. |
| Leica Geosystems AG |
| Topcon Corporation |
| Teledyne Optech Inc. |
| RIEGL Laser Measurement Systems GmbH |
| GeoSLAM Ltd. |
| FARO Technologies Inc. |
| imajing SAS |
| Hexagon AB |
| Others |
Value Chain & Pricing Dynamics
Solid-state MEMS LiDAR miniaturization is compressing unit economics while concentrating component sourcing around East Asian photonics foundries, creating asymmetric margin pressure across European integrators and vertically integrated platform providers.
Pricing Analysis
Distributor margins in mobile mapping hardware concentrate around 15-25% for survey-grade LiDAR platforms, with direct-to-OEM arrangements commanding steeper discounts. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified EU AI Act-compliant systems from uncertified imports and refurbished legacy units. Cost compression in entry-level photogrammetry bundles is intensifying because Chinese component suppliers are bypassing traditional distribution channels. Small surveying contractors in Poland and Romania exhibit highest price sensitivity, while German federal transport authorities prioritize certification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for European mobile mapping hardware, with final assembly concentrating in Germany, Sweden, and Switzerland. Solid-state LiDAR subsystems draw from Taiwanese MEMS foundries and Chinese laser diode manufacturers, while precision GNSS receivers source from Swiss and American chipset designers. Single-source vulnerability in photonic beam-steering chips exposes integrators to allocation risk during demand surges. Distribution runs through certified systems integrators who bundle hardware with local survey expertise and regulatory compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile mapping systems market functions as a geographic-arbitrage play where GDPR-compliant processing infrastructure in Germany commands premium pricing against non-compliant imports, while Polish and Romanian procurement windows offer volume scale at lower certification burden.
For Market Incumbents: Anticipate margin erosion from solid-state LiDAR entrants by deepening backward integration into geospatial analytics software that captures recurring data-service revenue. Prioritize CE marking investment and EU AI Act algorithmic transparency certification to filter procurement in German federal transport tenders. Channel control through equipment rental networks defends position against emerging backpack-mapping specialists. For New Entrants and Emerging Players: Municipal water authorities in Denmark and the Netherlands represent the most penetrable segment, as subscription-based procurement models displace capital expenditure and favor agile cloud-native platforms. Target Poland and Romania transport corridor modernization funded by EU cohesion investments, where incumbent presence remains thin. A channel partnership with civil engineering consortia in Warsaw and Kraków accelerates market access without direct sales infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among regional service providers bundling hardware with local survey expertise, as subscription economics concentrate buyer power among platform operators with captive cloud infrastructure. The long-term viability window favors acquisition targets with certified EU AI Act compliance and established MLOps audit trails for automated feature extraction. Watch CSRD sustainability reporting adoption rates as the signal indicating inflection in recurring mapping-as-a-service contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Algorithmic Certification | Conformity assessments for automated feature extraction open procurement gates in German automotive and French utility segments. |
| Backward Integration into Geospatial Analytics | Captive software ecosystems transform hardware vendors into recurring revenue platforms serving Danish water authorities. |
| Solid-State LiDAR Miniaturization | MEMS architectures enable tunnel and bridge interior deployments previously inaccessible to vehicle-mounted systems. |
| Hybrid Sensor Platform Development | Fused LiDAR-photogrammetry-thermal configurations capture premium inspection contracts for district heating networks. |
| Regional Distribution Hub Expansion | Rotterdam and Hamburg consolidation points reduce logistics friction for Polish and Romanian corridor modernization tenders. |
Study Parameters
Direct dialogue with mobile mapping platform engineers, civil engineering procurement directors, utility asset managers, and geodetic surveyor training program leads grounded qualitative findings in operational reality. Secondary validation drew from EU Green Deal spatial data mandate documentation, EARSC geospatial standards publications, KBA vehicle certification frameworks, and SEC filings of publicly traded sensor manufacturers. Bottom-up unit economics modeling triangulated against top-down infrastructure fund deployment forecasts.
Segment-level demand projections across product type, application, technology architecture, and end-user vertical fed into an analytical framework spanning the projection horizon. Modeled dimensions included survey-grade accuracy tier, deployment mode, regulatory compliance cluster, and regional procurement maturity. CAGRs derived from replacement cycle analysis of sensor obsolescence timelines and accuracy threshold improvements, with inputs from RTK correction service subscription trends and EU cohesion fund allocation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to LiDAR sensor supply allocation disruptions and GDPR adequacy ruling revisions affecting cross-border point cloud transfers. Outputs reflect documented assumptions around infrastructure fund deployment timelines and solid-state MEMS yield improvements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Residential Water Leak Detection System Market
Sensors
Eye Tracking Solutions Market
Sensors
Global Equipment Monitoring Market
Sensors
Data Buoy Market
Sensors
Underground Utility Mapping Market
Sensors
Europe Lidar Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Vibration Monitoring Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Body Area Network Market
Sensors
Vision Positioning System Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Heat Stress Meter Market
Sensors
Lidar in Construction Market