
 Weigh-In-Motion System Market | 2026-2036
Weigh-In-Motion System Market Size, Share, and Industry Trends Forecast 2026-2036
Weigh-In-Motion System Market Intelligence
Silicon carbide sensor substrates are repositioning piezoelectric WIM economics by extending sensor lifespan under heavy-axle loads. Kistler Group leverages its Swiss manufacturing base to sustain premium positioning in high-speed weighbridge applications. TE Connectivity anchors North American supply chains through captive strain gauge production. Mettler-Toledo dominates precision calibration protocols that differentiate European toll-road installations.
Weigh-in-motion systems measure dynamic axle and gross vehicle weights at traffic speed through embedded road sensors, typically achieving accuracy within five percent at velocities exceeding one hundred kilometers per hour. Their primary purpose is enabling automated enforcement and data collection without disrupting commercial traffic flow. Fixed systems occupy the largest installed base among product configurations, while hybrid architectures are gaining share where agencies seek phased infrastructure upgrades. Piezoelectric sensors lead technology deployment due to proven durability, though electromagnetic alternatives are capturing interest for non-intrusive installation profiles. Traffic monitoring applications generate the steadiest revenue streams, whereas weight enforcement commands premium pricing through certification requirements.
The U.S. Federal Highway Administration and Germany's KBA enforce divergent accuracy certification standards that fragment product development roadmaps. The EU Green Deal's heavy-duty vehicle emissions tracking mandates are expanding WIM data integration into carbon accounting frameworks. Stakeholders must monitor whether emerging AI-enabled sensor fusion protocols trigger new interoperability standards before committing to long-term platform investments.
Market Dynamics
Silicon carbide sensor substrates are compressing replacement cycles and forcing recalibration of vendor cost structures across installed highway infrastructure.
Growth Catalysts
- EU Green Deal emissions tracking:Heavy-duty vehicle carbon accounting mandates are expanding WIM data integration into toll-road billing systems across German autobahn corridors.
- Piezoelectric durability advances:Extended sensor lifespan under repetitive heavy-axle loading is reducing total cost of ownership for highway freight carriers.
- U.S. FHWA enforcement mandates:Updated truck weight compliance requirements are accelerating state-level infrastructure replacement programs.
Market Restraints
- Sensor substrate supply concentration:High-purity silicon carbide wafer production clusters in limited manufacturing geographies, creating input vulnerability.
- Divergent accuracy certification:The U.S. FHWA and Germany's KBA enforce incompatible calibration standards, fragmenting product development roadmaps.
- Electromagnetic alternative threat:Non-intrusive installation profiles of electromagnetic sensors appeal to agencies seeking minimal road disruption.
Strategic Opportunities
- AI-enabled sensor fusion:Machine learning integration with piezoelectric arrays is creating predictive maintenance revenue streams for system integrators.
- Hybrid architecture adoption:Phased infrastructure upgrade programs in North American states favor modular installations combining fixed and portable elements.
- Swiss precision calibration services:Premium positioning in high-speed weighbridge applications supports margin expansion through certified service contracts.
Industry Challenges
- Interoperability standard delays:Emerging AI protocols lack unified data exchange formats, complicating multi-vendor procurement decisions.
- Legacy system integration friction:State transportation departments face complex retrofit requirements when connecting new WIM arrays to existing traffic management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weigh-In-Motion System Market |
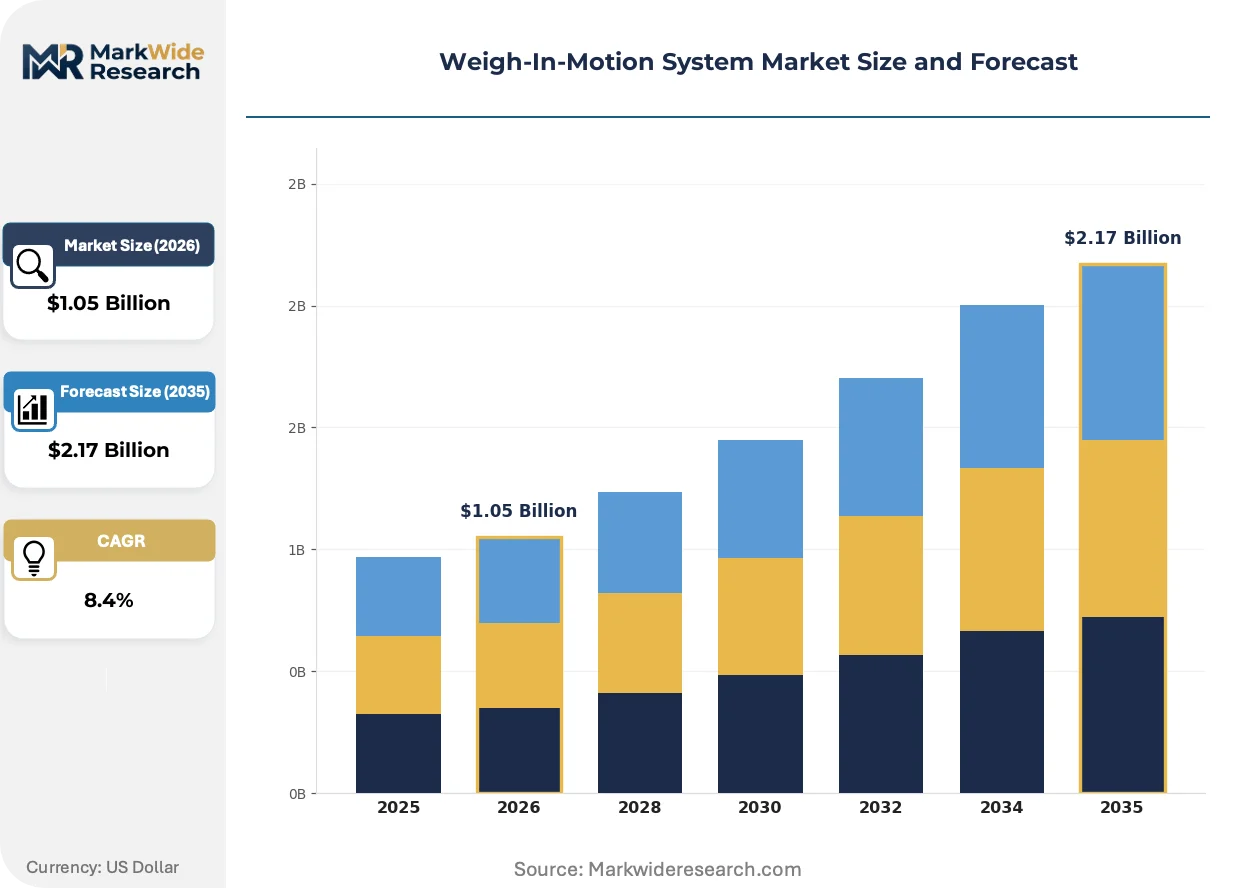
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Fixed Systems, Hybrid Systems, In-Motion Scales End User: Transportation Agencies, Logistics Providers, Freight Carriers, Road Authorities Technology: Piezoelectric Sensors, Load Cells, Strain Gauges, Electromagnetic Sensors Application: Traffic Monitoring, Weight Enforcement, Data Collection, Vehicle Classification |
| Companies Covered | International Road Dynamics, TE Connectivity, Kistler Group, Sensys Networks, Mettler-Toledo, Kapsch TrafficCom, SWARCO AG, FLIR Systems, Q-Free ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weigh-In-Motion System Market Strategic Shifts & Innovations
Sensor material science and regulatory data mandates are converging to transform how transportation agencies capture and monetize vehicle weight intelligence.
Silicon carbide substrates are rewriting piezoelectric WIM economics by extending operational lifespan under sustained heavy-axle stress. German autobahn operators are adopting these sensors at accelerated replacement cycles. The structural consequence is compressing vendor service revenue models toward predictive analytics rather than hardware refresh.
The EU Green Deal's heavy-duty vehicle emissions framework is mandating WIM integration into carbon accounting protocols. Toll-road operators must now weight-certify freight for CO2 billing accuracy. European installations are prioritizing precision-calibrated systems that satisfy both enforcement and environmental reporting requirements.
State procurement offices are consolidating vendor relationships around integrated sensor-to-cloud platforms. Single-source contracts are displacing fragmented component purchasing across U.S. highway districts. California and Texas transportation departments are piloting unified data architectures that bundle installation, calibration, and analytics subscriptions.
Weigh-In-Motion System Market Segmentation
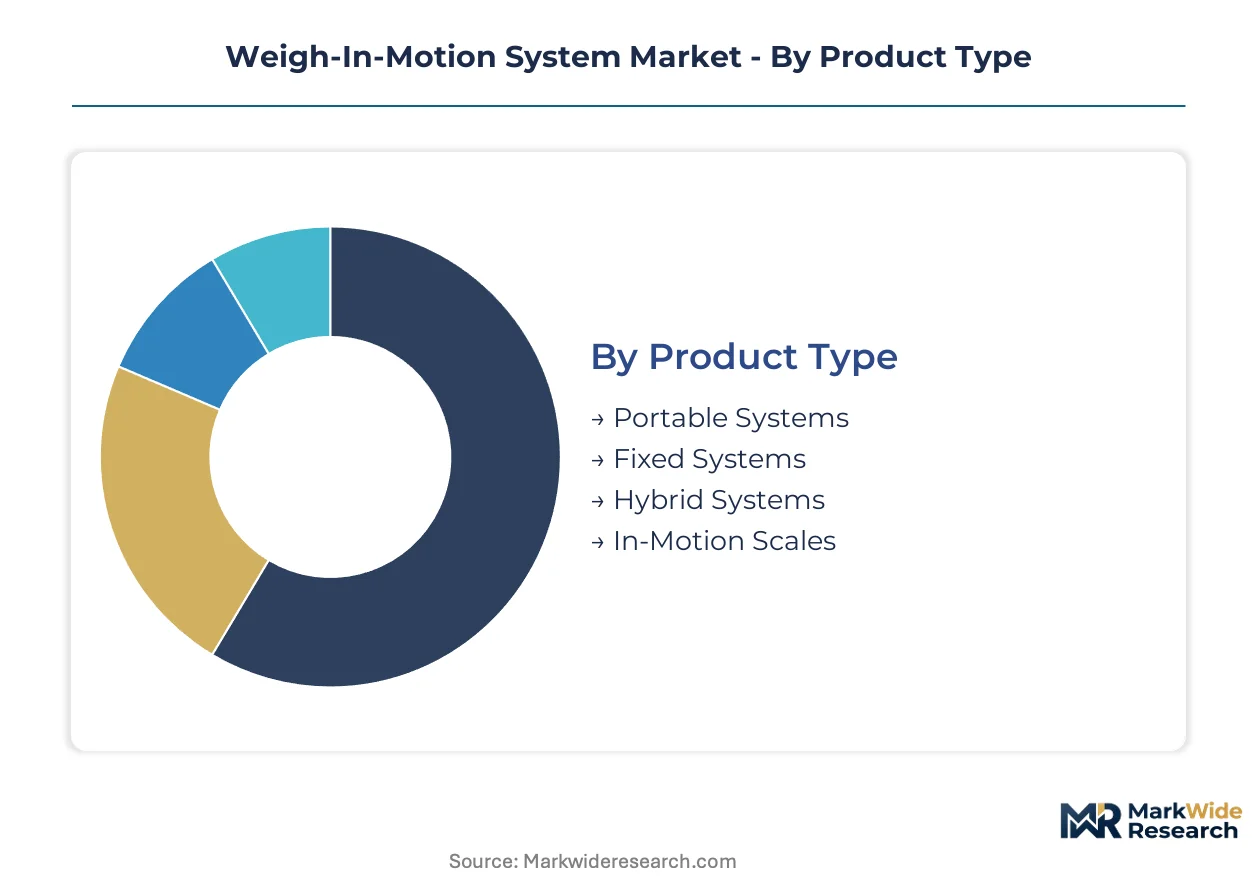
Product architecture and sensor technology choices determine deployment economics for highway operators balancing accuracy mandates against infrastructure lifecycle costs. Segmentation reveals where vendor margins concentrate and which specification tiers command procurement priority.
Product Type:
Structural permanence and installation depth separate cost tiers across highway agency procurement portfolios.
- Fixed Systems:Permanent installations embed piezoelectric arrays or strain gauge platforms directly into roadway substrate. German autobahn corridors and U.S. interstate weigh stations prioritize these for enforcement-grade accuracy certification.
- Portable Systems:Modular units deploy temporarily for spot-check enforcement or construction zone monitoring. State transportation departments in Texas and California favor these for flexible compliance operations without capital-intensive road cuts.
- Hybrid Systems:Phased architectures combine fixed backbone infrastructure with portable augmentation nodes. North American agencies pursuing incremental upgrade paths are driving specification convergence here.
- In-Motion Scales:Self-contained weighing platforms integrated into toll plaza lanes. European toll-road operators specify these for combined weight-enforcement and billing automation.
Mature deployment sits with Fixed Systems. Newer deployment is concentrated in Hybrid Systems.
End User:
Budget authority and data integration requirements fragment procurement behavior across institutional buyer types.
- Road Authorities:Federal and state highway departments hold primary enforcement jurisdiction and capital allocation authority. The U.S. FHWA mandates drive specification standardization across state-level replacement programs.
- Transportation Agencies:Regional and municipal operators manage traffic flow optimization and bridge protection. German KBA certification requirements shape their accuracy specifications.
- Freight Carriers:Private fleet operators deploy WIM for self-monitoring compliance and axle load optimization. Large North American trucking companies are piloting onboard-to-roadside data integration.
- Logistics Providers:Third-party operators and distribution centers use WIM for outbound load verification. Warehouse-adjacent installations prioritize speed over enforcement-grade precision.
Procurement volume concentrates with Road Authorities. Margin expansion is climbing the fastest with Freight Carriers.
Technology:
Sensor material science and signal processing sophistication determine accuracy certification tiers and replacement economics.
- Piezoelectric Sensors:Ceramic or polymer elements generate voltage proportional to dynamic axle pressure. Silicon carbide substrate advances are extending operational lifespan under repetitive heavy-axle stress across German autobahn installations.
- Strain Gauges:Metallic foil or semiconductor elements measure substrate deformation under load. TE Connectivity's captive North American production secures supply chain positioning for state highway department contracts.
- Load Cells:Compression or shear beam transducers deliver high-precision static and low-speed weighing. Weighbridge applications at toll plazas specify these for legal-for-trade certification.
- Electromagnetic Sensors:Non-intrusive inductive loops or magnetic arrays detect vehicle presence and estimate mass. Agencies seeking minimal road disruption are piloting these for traffic monitoring where enforcement accuracy is secondary.
Installed base dominance rests with Piezoelectric Sensors. Specification interest is expanding most quickly in Electromagnetic Sensors.
Application:
Data utility and regulatory compliance intensity separate pricing tiers across use case specifications.
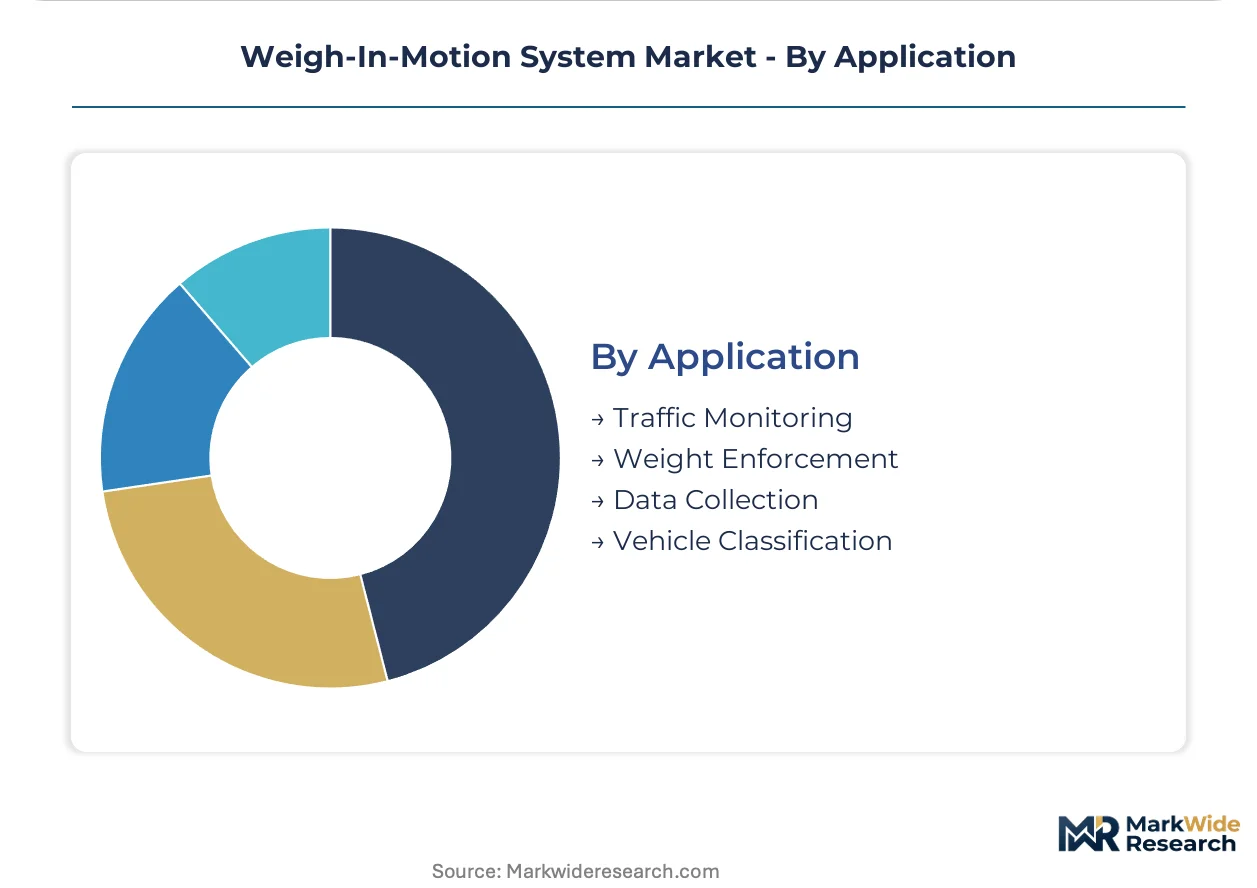
- Traffic Monitoring:Continuous vehicle flow analysis for congestion management and infrastructure planning. Steadiest revenue stream with lowest accuracy certification burden.
- Weight Enforcement:Automated overload detection triggering legal penalties or vehicle detention. Premium pricing reflects legal metrology certification and evidentiary data standards.
- Data Collection:Aggregate weight statistics for pavement engineering and freight flow analysis. Research partnerships with universities and federal laboratories sustain this segment.
- Vehicle Classification:Axle counting and spacing measurement for tolling and road wear attribution. EU Green Deal emissions tracking mandates are integrating WIM data into carbon accounting frameworks.
Revenue stability concentrates in Traffic Monitoring. Regulatory momentum is gaining share fastest in Vehicle Classification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highway freight enforcement mandates concentrate procurement authority in three regulatory jurisdictions. Germany's autobahn modernization and U.S. interstate weight compliance programs absorb the majority of installed system volume.
United States
State transportation departments in Texas and California pilot hybrid WIM architectures combining fixed backbone infrastructure with portable augmentation nodes. The FHWA's updated truck weight enforcement mandates accelerate replacement cycles across interstate corridors. Installation clusters concentrate in the Southwest and Pacific Coast states where freight volume intersects with bridge protection priorities.
Germany
Autobahn corridor operators prioritize dynamic weighing installations with precision calibration protocols for toll-road billing integration. The KBA enforces accuracy certification standards that shape vendor product development roadmaps. Bavaria and Baden-Württemberg host the densest sensor deployments where EU Green Deal emissions tracking mandates converge with enforcement requirements.
China
Provincial highway authorities deploy piezoelectric arrays for automated overload detection on national freight corridors. The MIIT coordinates smart transportation infrastructure standards that incorporate weigh-in-motion data streams. Yangtze River Delta logistics hubs are integrating WIM sensors into port-to-inland distribution networks.
Switzerland
Alpine transit routes require high-speed weighbridge applications with certified service contracts for precision maintenance. Swiss manufacturing bases sustain premium positioning in sensor substrate production. The Gotthard and Brenner corridor operators specify enforcement-grade systems for heavy-axle commercial traffic.
Canada
Provincial transportation ministries adopt portable WIM units for flexible enforcement operations across remote highway segments. Health Canada coordinates cross-border weight compliance data sharing with U.S. authorities. Ontario and British Columbia lead deployment volumes where cross-border freight corridors require harmonized certification standards.
Weigh-In-Motion System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with precision calibration providers commanding premium positioning in enforcement-grade installations while volume-oriented suppliers anchor traffic monitoring deployments. The vendor base organizes around three strategic archetypes: Swiss-German precision instrumentation houses, North American integrated sensor-to-cloud platform providers, and Nordic traffic management system integrators. Consolidation pressures favor single-source procurement contracts over fragmented component purchasing. Geographic expansion and technology licensing represent the dominant competitive moves as vendors seek to bridge divergent regulatory certification requirements.
Within the precision instrumentation tier, Kistler Group and Mettler-Toledo exemplify archetypes anchored in European manufacturing traditions. Kistler's Swiss base supports premium positioning in high-speed weighbridge applications through certified service contract models. Mettler-Toledo occupies a comparable position in precision calibration protocols that differentiate toll-road installations requiring legal metrology standards. TE Connectivity represents the North American integrated supply chain archetype, with captive strain gauge production securing state highway department relationships. These three companies illustrate how vendor strategies diverge between precision-service revenue models and volume-scale platform consolidation.
| Leading Market Players |
|---|
| International Road Dynamics |
| TE Connectivity |
| Kistler Group |
| Sensys Networks |
| Mettler-Toledo |
| Kapsch TrafficCom |
| SWARCO AG |
| FLIR Systems |
| Q-Free ASA |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's heavy-duty vehicle emissions tracking mandates gate qualified supply access for vendors seeking premium-tier pricing in European toll-road installations. Compliance-certified piezoelectric arrays with silicon carbide substrates command substantial premiums over standard-grade alternatives, while uncertified suppliers face exclusion from German autobahn procurement programs.
Pricing Analysis
Volume concentrates in fixed-system installations for state highway departments, while margin expansion flows to precision calibration services and predictive maintenance subscriptions. Three-tier pricing structure across enforcement-grade, traffic-monitoring, and portable configurations reflects certification burden and after-sales bundling. Cost compression in standard piezoelectric tiers intensifies as Chinese manufacturers expand capacity. Road authorities exhibit lowest price sensitivity due to federal mandate compliance requirements, whereas logistics providers prioritize speed over precision and drive economy-tier procurement.
Supply Chain Analysis
Specialized workforce availability in Swiss and German precision manufacturing geographies anchors high-purity silicon carbide wafer production for sensor substrates. Supply draws from Switzerland, Germany, and select East Asian facilities for ceramic element fabrication. Raw material dependencies center on high-grade silicon carbide feedstock, platinum-group metallization layers, and specialized polymer encapsulants. Single-source vulnerability concentrates in substrate wafer supply, where limited qualified manufacturers create input bottlenecks. Distribution runs through direct vendor-state procurement contracts and integrated sensor-to-cloud platform agreements displacing fragmented component purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around single-source procurement contracts as state transportation departments abandon fragmented component purchasing. Divergent U.S. FHWA and German KBA certification standards are forcing weaker vendors without dual-jurisdiction capabilities toward exit.
For Market Incumbents: Cement dual-certification capabilities spanning U.S. FHWA and German KBA standards to capture cross-border procurement consolidation. Lock in captive silicon carbide substrate supply through backward integration or long-term offtake agreements with Swiss-German wafer manufacturers. Electromagnetic sensor substitutes threaten piezoelectric incumbents in traffic-monitoring segments where enforcement-grade accuracy is dispensable. For New Entrants and Emerging Players: Cloud-based calibration-as-a-service platforms offer the lowest barrier route for SaaS-native entrants lacking hardware manufacturing scale. Target portable WIM augmentation nodes for North American state departments pursuing phased hybrid upgrades. Lead with AI-enabled predictive maintenance analytics to differentiate from established vendors' hardware-centric revenue models. For Investors and Strategic Acquirers: California and Texas transportation departments issuing unified sensor-to-cloud procurement tenders is the leading indicator that platform consolidation is accelerating beyond component supply. Five-to-ten year viability favors precision-calibration service providers with certified maintenance networks over pure hardware manufacturers. Watch for AI sensor fusion protocol standardization as the inflection signal triggering multi-vendor procurement collapse toward single-source winners.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Jurisdiction Certification Investment | FHWA-KBA dual compliance unlocks cross-border procurement from Texas to Bavaria. |
| Silicon Carbide Substrate Integration | In-house wafer supply secures margin expansion against Chinese ceramic competitors. |
| AI Sensor Fusion Development | Machine learning integration creates predictive maintenance recurring revenue streams. |
| Hybrid Architecture Platform Launch | Modular fixed-portable combinations capture North American phased upgrade demand. |
| Calibration-as-a-Service Expansion | Certified precision maintenance contracts differentiate European toll-road installations. |
Research Approach
Trade association filings, customs import records, and federal procurement databases formed the secondary backbone for vendor shipment estimates and price benchmarking. Primary interviews with state transportation department procurement officers, toll-road operators, piezoelectric sensor engineering directors, and freight carrier fleet compliance managers validated installation trends and replacement cycle timing. Bottom-up triangulation across state-level contract awards and top-down reconciliation against federal highway infrastructure budgets anchored volume estimates.
Historical trendline analysis of installed base growth, sensor replacement frequencies, and certification standard adoption rates informed projection modeling across the analysis window. Segmentation dimensions spanned product architecture, sensor technology, end-user budget authority, and application compliance intensity. CAGRs derived from regression analysis of highway freight volume growth, enforcement mandate implementation schedules, and infrastructure replacement funding cycles. EU Green Deal emissions integration timelines and AI protocol standardization uncertainty served as scenario-weighting inputs.
The model holds under steady federal and state infrastructure funding commitment; deviation in appropriation delays or certification standard harmonization failure would shift replacement cycle assumptions. Forecasts embed assumptions regarding silicon carbide substrate supply expansion and electromagnetic sensor competitive encroachment limits. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Facial Tracking Solution Market
Sensors
Global RFID Market
Sensors
Underground Utility Mapping Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
North America Eye Tracking Solutions Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Global Position Tracking System Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Low Power Geolocation Market
Sensors
Heat Stress Meter Market
Sensors
Europe RFID Market
Sensors
Global Positioning Systems Market
Sensors
Indoor Positioning and Navigation Market
Sensors
Beacon Market