
 Ultrasonic Technologies Market | 2026-2036
Ultrasonic Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Technologies Market Intelligence
The European Union's F-Gas Regulation, which restricts the use of certain fluorinated greenhouse gases in industrial cleaning, is pivoting manufacturers toward aqueous-based ultrasonic systems. In this environment, Emerson Electric Co. (Branson) leverages its extensive portfolio in plastic welding and cleaning solutions for the automotive and electronics sectors. Telsonic AG specializes in high-power ultrasonic applications for industrial processes, while Crest Ultrasonics Corp. focuses on precision cleaning systems for medical and aerospace customers.
Ultrasonic technologies utilize acoustic waves at frequencies above the human hearing range, typically greater than 20 kHz, to induce physical and chemical effects in materials. These effects are harnessed for industrial purposes ranging from high-precision cleaning to non-destructive material testing. Within the product landscape, ultrasonic cleaners for the healthcare and manufacturing sectors constitute a mature segment. However, demand for ultrasonic welding machines is accelerating, driven by the automotive industry's shift to lightweight plastics and composites.
Regulatory frameworks like the US FDA's requirements for medical device sterilization and cleaning validation directly influence product design and adoption. Concurrently, compliance with international standards such as ISO 13485 and China's GB standards for industrial machinery safety are critical for market access. Equipment providers must therefore navigate a complex matrix of end-use-specific performance mandates and regional safety certifications to secure their market position.
Market Dynamics
The ultrasonic technologies market is defined by a push-pull dynamic between stringent regulatory mandates and the material science limitations of end-use industries. Evolving rules like the EU's MDR are forcing equipment redesigns for enhanced cleaning validation and material compatibility testing.
Growth Catalysts
- Medical Device Regulation:The EU's Medical Device Regulation (MDR) imposes stricter requirements for device cleaning and sterilization validation, directly increasing demand for advanced ultrasonic cleaners in medical technology manufacturing, particularly within German and Swiss production clusters.
- Automotive Lightweighting:The automotive industry's transition to electric vehicles and focus on efficiency accelerates the use of lightweight plastics and composites, which in turn boosts demand for ultrasonic welding machines for assembly.
- Non-Destructive Testing (NDT):In the aerospace and energy sectors, the need to ensure the structural integrity of critical components without causing damage drives adoption of ultrasonic NDT for flaw detection and material characterization.
Market Restraints
- High Capital Investment:The significant upfront cost of high-power ultrasonic welding and industrial-scale cleaning systems presents a substantial barrier to entry for small and medium-sized enterprises in manufacturing sectors.
- Material Compatibility Limits:Certain advanced polymers and composites, particularly those with high-temperature resistance or heavy fiber reinforcement, are difficult to process effectively with current ultrasonic welding technologies, limiting applications.
- Regulatory Fragmentation:Equipment manufacturers must navigate a disparate web of regional and end-use specific standards, from ISO 13485 for medical devices to China's GB standards for machinery safety, increasing compliance costs and time-to-market.
Strategic Opportunities
- Food Processing Applications:Untapped potential exists for ultrasonic technology in food and beverage processing for tasks such as emulsification, extraction of bioactive compounds, and non-thermal pasteurization, offering a new growth vertical.
- AI-Powered Process Control:Integrating artificial intelligence and machine learning algorithms with ultrasonic sensors enables real-time process monitoring, predictive maintenance, and quality control, creating value-added, smart system offerings.
- Emerging Economies' Manufacturing:Expanding sales and service networks into Southeast Asian nations like Vietnam and Thailand can capture demand from their rapidly growing electronics, automotive, and medical device manufacturing bases.
Industry Challenges
- Skilled Technician Shortage:A deficit of qualified engineers and technicians capable of designing, operating, and maintaining sophisticated ultrasonic equipment constrains effective deployment and innovation across end-use industries.
- System Integration Complexity:Integrating new ultrasonic systems into existing, highly automated production lines often presents significant technical challenges related to software compatibility, robotics, and workflow synchronization.
- Process Validation Overhead:For novel materials or complex geometries, particularly in regulated industries like aerospace and medical, the extensive and costly process validation required for each specific application can slow adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Technologies Market |
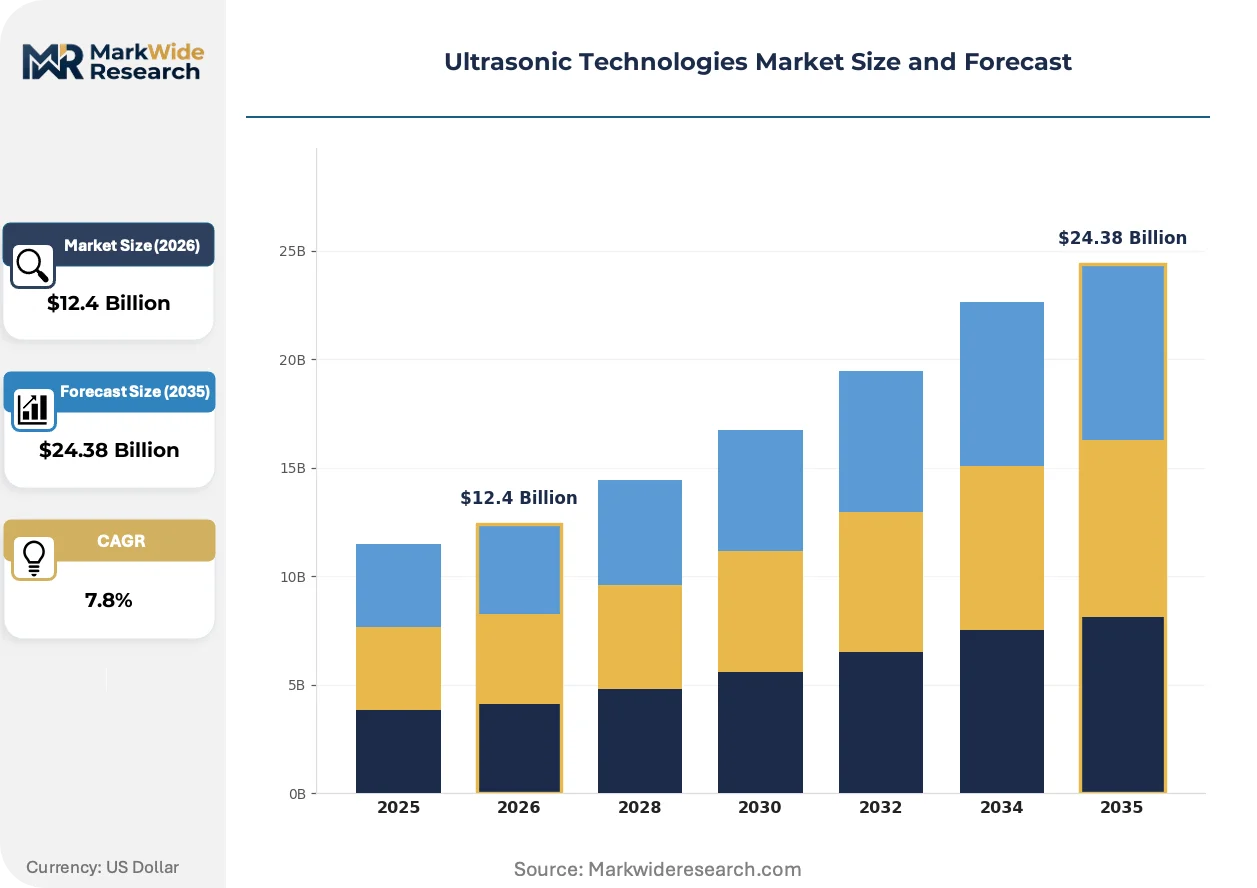
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $24.38 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Ultrasonic Cleaners, Ultrasonic Non-Destructive Testing, Ultrasonic Welding Machines End User: Manufacturing, Healthcare, Automotive, Chemical Processing Technology: Ultrasonic Imaging, Ultrasonic Flow Measurement, Ultrasonic Dispersion, Ultrasonic Homogenization Application: Medical Diagnostics, Material Testing, Liquid Processing, Surface Cleaning |
| Companies Covered | Emerson Electric Co. (Branson), Crest Ultrasonics Corp., Telsonic AG, Advanced Sonics, LLC, DPR Ultrasonic Technologies, International Ultrasonic Technologies, Sonotronic Nagel GmbH, MS Industrie AG, Mosca GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Technologies Market Strategic Shifts & Innovations
Material science advancements and tightening regulatory frameworks are compelling a fundamental shift in ultrasonic technology. The market is moving away from standalone hardware toward integrated, data-rich systems designed for process validation and compliance within specific industrial ecosystems.
Advanced, multi-axis ultrasonic welding systems provide precise, three-dimensional control over the welding process. These systems are seeing rapid adoption in the automotive and electronics sectors for assembling geometrically complex plastic parts and enclosures. This technology is rewriting the possibilities for product design, enabling greater part consolidation and the creation of more intricate, lightweight components that were previously impossible to manufacture efficiently.
The European Union’s F-Gas Regulation is actively phasing out the use of specific fluorinated greenhouse gases commonly used as solvents in industrial vapor degreasing. This regulatory action is forcing a significant technological pivot in the precision cleaning segment. Manufacturers in high-stakes industries like aerospace and medical devices are consequently accelerating their transition to aqueous-based ultrasonic cleaning systems to maintain compliance.
A notable behavioral change is the shift in procurement criteria, where buyers now prioritize comprehensive process validation data over simple equipment specifications. This trend is disrupting traditional sales models that focused on hardware features, creating an advantage for suppliers who can offer complete documentation packages compliant with FDA or ISO 13485 standards. This demand-side shift is most pronounced in the North American and European medical device sectors.
Ultrasonic Technologies Market Segmentation
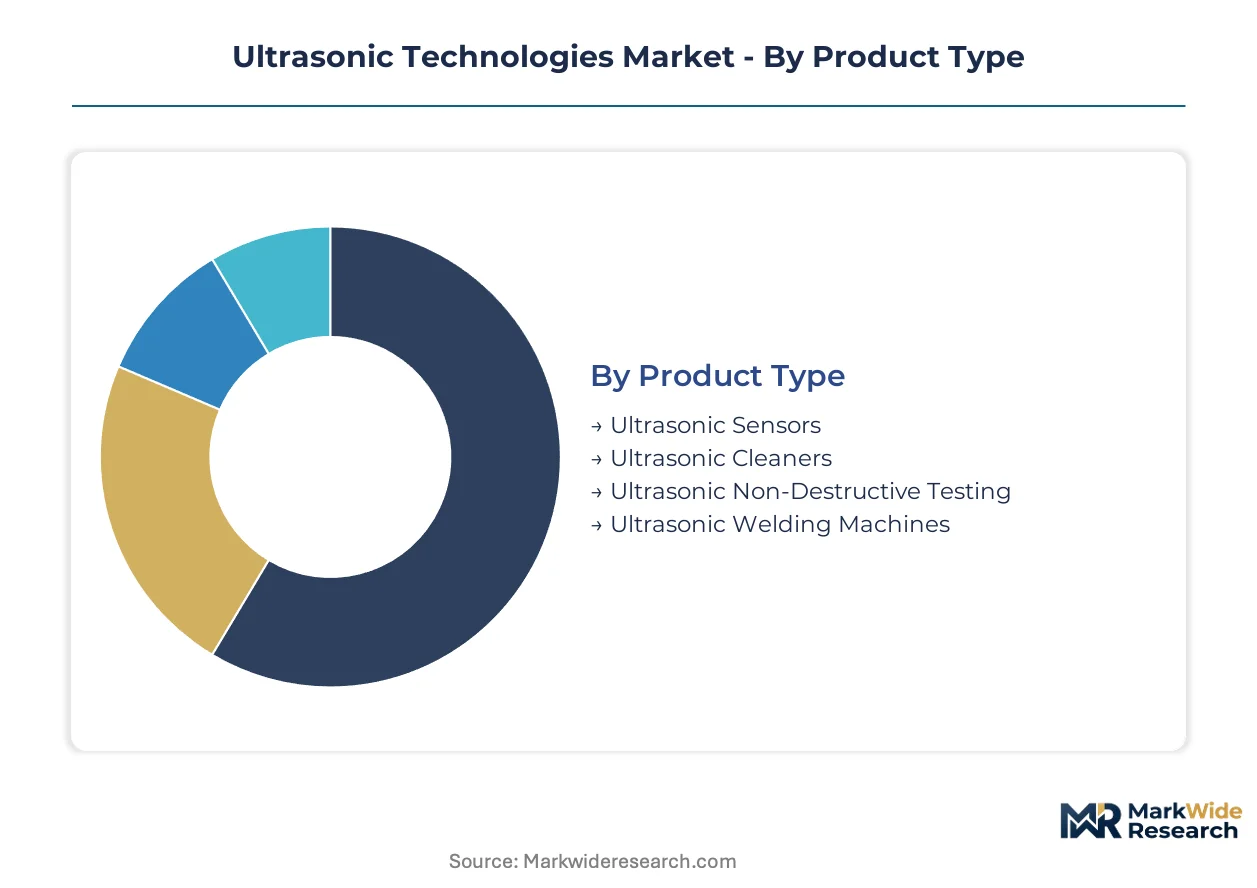
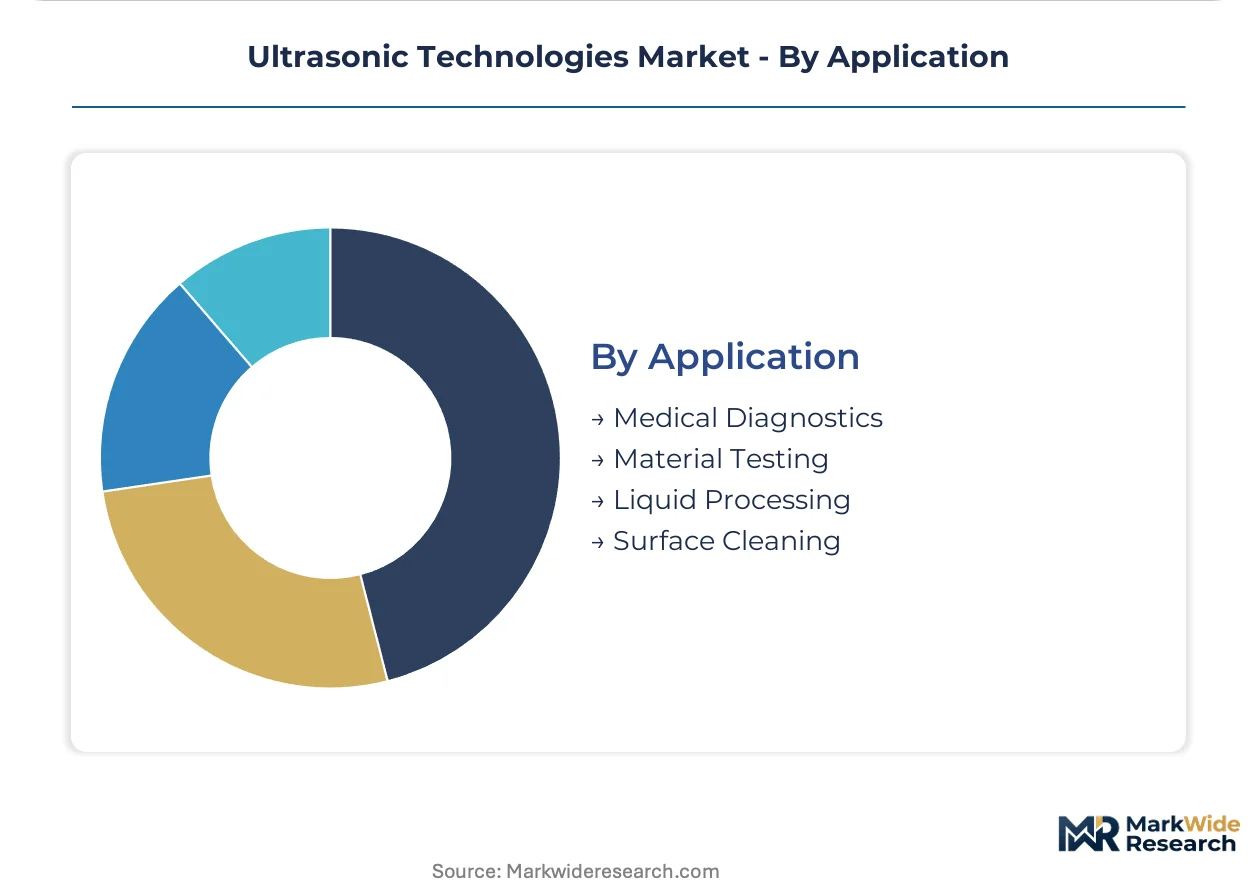
The ultrasonic technologies market is diverse, with distinct segments serving varied industrial requirements and regulatory landscapes. Understanding these segments is critical for equipment providers to tailor solutions and navigate specific compliance mandates effectively. Each segment addresses unique challenges, from precision cleaning to material integrity assessment.
Product Type:
Manufacturers prioritize specific product types based on their operational needs and compliance mandates.
- Ultrasonic Cleaners:These systems utilize high-frequency sound waves to create cavitation bubbles, effectively removing contaminants from surfaces. Demand concentrates in medical technology clusters within Germany and Switzerland due to stringent EU Medical Device Regulation (MDR) requirements.
- Ultrasonic Welding Machines:These machines generate high-frequency vibrations that produce localized heat, bonding thermoplastic materials without adhesives. The automotive industry drives demand for these systems as it transitions to lightweight plastics and composites for electric vehicles.
- Ultrasonic Sensors:These devices convert acoustic waves into electrical signals, enabling non-contact detection, distance measurement, and level sensing across various industrial processes.
- Ultrasonic Non-Destructive Testing:This technology employs high-frequency sound waves to detect internal flaws, measure thickness, and characterize materials without causing damage to components.
Volume sits with Ultrasonic Cleaners; growth tilts toward Ultrasonic Welding Machines.
End User:
The application scope dictates the specific end-user segments requiring ultrasonic solutions.
- Healthcare:This sector utilizes ultrasonic technologies extensively for medical diagnostics, sterilization, and precision cleaning of instruments and devices. North American and European healthcare systems drive significant demand due to stringent FDA and MDR regulations.
- Automotive:The automotive industry employs ultrasonic solutions for welding plastic components, non-destructive testing of critical parts, and cleaning manufacturing tools. Demand is strong in major production hubs across Europe and Asia-Pacific, driven by EV adoption and lightweighting initiatives.
- Manufacturing:This broad segment uses ultrasonic cleaning for precision parts, non-destructive testing for quality control, and various material processing applications across diverse industries.
- Chemical Processing:This industry employs ultrasonic dispersion and homogenization techniques for mixing, emulsification, and particle size reduction in chemical formulations and processes.
Healthcare and Automotive segments exhibit the most pronounced demand expansion.
Technology:
Technology maturity levels influence adoption rates and investment priorities across different industrial applications.
- Ultrasonic Imaging:This technology generates visual representations of internal structures using high-frequency sound waves, widely applied in medical diagnostics and industrial inspection. Medical facilities globally rely on ultrasonic imaging for non-invasive examinations and material analysis.
- Ultrasonic Dispersion:High-intensity ultrasound breaks down agglomerates and disperses particles uniformly within liquid suspensions. The food processing and pharmaceutical industries increasingly adopt this technology for uniform mixing and enhanced product stability.
- Ultrasonic Flow Measurement:This technique calculates fluid velocity and volume by measuring the transit time of ultrasonic pulses transmitted through a liquid or gas.
- Ultrasonic Homogenization:This process uses acoustic cavitation to reduce particle size and create stable emulsions, suspensions, and dispersions in various liquid systems.
Ultrasonic Imaging holds established market share, while Ultrasonic Dispersion is gaining traction in specialized industrial processes.
Application:
The margin potential of an application often drives the strategic allocation of ultrasonic technology investments.
- Medical Diagnostics:This application involves using high-frequency sound for non-invasive imaging, therapeutic procedures, and diagnostic assessments in healthcare. North American and European healthcare systems drive continuous innovation for early disease detection and treatment monitoring.
- Surface Cleaning:This application removes contaminants from component surfaces through cavitation generated by ultrasonic waves in an aqueous or solvent medium. The aerospace and medical device manufacturing sectors show high demand due to the EU F-Gas Regulation and MDR compliance.
- Material Testing:This application employs ultrasonic waves for non-destructive evaluation, detecting internal flaws, measuring thickness, and characterizing material properties in critical components.
- Liquid Processing:This application utilizes ultrasound for tasks such as emulsification, extraction of bioactive compounds, and non-thermal pasteurization in food and beverage and pharmaceutical industries.
Medical Diagnostics represents the largest revenue segment, with Surface Cleaning represents the fastest-growing trajectory due to regulatory pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical technology manufacturing clusters within Germany and Switzerland drive significant demand for advanced ultrasonic solutions. These regions, particularly around Stuttgart and Zurich, benefit from stringent regulatory environments. Manufacturers there prioritize high-precision cleaning and testing equipment to meet compliance requirements.
Germany
German automotive manufacturers increasingly adopt ultrasonic welding for lightweight plastics in electric vehicles. The EU's F-Gas Regulation pushes industrial cleaning towards aqueous-based systems across the country. Bavarian and Baden-Württemberg clusters specialize in advanced industrial machinery development and deployment.
United States
US medical device manufacturers demand advanced ultrasonic cleaners for sterilization validation. FDA requirements for medical device cleaning protocols directly influence product design and adoption. California's MedTech hubs and aerospace clusters in the Pacific Northwest utilize non-destructive testing extensively.
China
Chinese electronics and automotive sectors drive demand for ultrasonic welding machines for complex assemblies. GB standards for industrial machinery safety are critical for market access across the country. The Yangtze River Delta region hosts extensive manufacturing operations requiring varied ultrasonic applications.
Switzerland
Swiss precision manufacturing, especially in medical technology, relies on high-accuracy ultrasonic cleaning systems. Compliance with the EU's Medical Device Regulation mandates sophisticated material testing capabilities. The Zurich and Geneva regions concentrate specialized ultrasonic equipment development and deployment.
Japan
Japanese automotive companies integrate ultrasonic welding for vehicle lightweighting and component assembly. JIS standards guide the design and implementation of industrial ultrasonic machinery. Manufacturing hubs in the Chubu region adopt advanced non-destructive testing for quality assurance and material characterization.
Ultrasonic Technologies Market Key Industry Players
Premium-margin players sit above commodity-margin players across precision and regulatory compliance within the ultrasonic technologies market. The market structure features a mix of highly specialized technology providers and diversified industrial conglomerates. Strategic archetypes include niche innovators focusing on specific applications and broader solution providers. Companies frequently engage in portfolio diversification and strategic partnerships to expand their market reach.
On the premium-tier vector, Emerson Electric Co. (Branson) exemplifies a diversified industrial conglomerate offering extensive plastic welding and cleaning solutions. Crest Ultrasonics Corp. occupies a position as a specialist in precision cleaning systems, particularly for regulated industries like medical and aerospace. Telsonic AG represents a high-power ultrasonic application provider, anchoring the industrial processes segment with specialized machinery offerings for various industrial applications.
| Leading Market Players |
|---|
| Emerson Electric Co. (Branson) |
| Crest Ultrasonics Corp. |
| Telsonic AG |
| Advanced Sonics, LLC |
| DPR Ultrasonic Technologies |
| International Ultrasonic Technologies |
| Sonotronic Nagel GmbH |
| MS Industrie AG |
| Mosca GmbH |
| Others |
Cost & Logistics Intelligence
Medical device manufacturers in regulated clusters prioritize validated systems, driving a project-based pricing model that emphasizes compliance and long-term performance. This approach rewards suppliers capable of delivering comprehensive documentation and support.
Pricing Analysis
Value-based pricing anchored to enhanced process validation and compliance outcomes dominates advanced ultrasonic system sales. The dominant pricing structure is contract-based, reflecting customized solutions and ongoing service requirements. Price differentiation stems from certification levels, particularly ISO 13485 compliance, and comprehensive after-sales support. Small and medium-sized enterprises exhibit higher price sensitivity, contrasting with regulated medical device manufacturers who prioritize performance over cost.
Supply Chain Analysis
Certification and qualification gating heavily influence the ultrasonic technologies supply chain, particularly for medical and aerospace applications. Geographic supply concentrates in Germany and Switzerland for precision components, with China providing standard transducers and electronic sub-assemblies. The industry relies on specialized piezoelectric ceramics and advanced control electronics. Single-source vulnerability for high-performance transducers presents a structural risk, influencing procurement strategies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasonic technologies market is currently supply-constrained, driven by the specialized manufacturing capacity required for high-power ultrasonic transducers. This bottleneck props up pricing for advanced welding and NDT systems.
For Market Incumbents: To counter regulatory fragmentation and the rise of low-cost entrants, incumbents must deepen their specialization in regulated industries. Invest in AI-powered process control for real-time validation and predictive maintenance, enhancing system value. Expand localized certification capabilities in emerging economies to simplify market access. Control over critical component supply, like piezoelectric materials, can also reinforce market position.
For New Entrants and Emerging Players: Launch via strategic partnerships with system integrators to penetrate emerging manufacturing ecosystems in Southeast Asia. Focus on underpenetrated verticals like food processing for emulsification and non-thermal pasteurization applications. Offer modular, scalable ultrasonic cleaning solutions that simplify integration into existing production lines. Differentiate through superior after-sales support and localized technical training.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term growth in regulated industrial technology. Acquire niche innovators specializing in AI-powered process control or advanced transducer material science. These targets offer proprietary technology and deep application expertise. The signal to watch is increased venture capital funding for ultrasonic startups focused on new food processing or advanced NDT software applications.
| Strategic Initiative | Industry Significance |
|---|---|
Capacity Expansion in Transducer Manufacturing |
Addresses supply constraints for critical components, stabilizing production costs for high-power systems. |
Strategic Partnerships for AI/ML Integration |
Enhances system intelligence for predictive maintenance and real-time quality control, creating value-added offerings. |
Green Manufacturing Transition for Cleaning Systems |
Ensures compliance with environmental regulations like EU F-Gas, capturing demand in regulated industries. |
Geographic Expansion into Southeast Asian Markets |
Captures demand from rapidly growing electronics and automotive manufacturing bases in emerging economies. |
Product Launch for Food Processing Applications |
Diversifies revenue streams by addressing untapped potential in emulsification and non-thermal pasteurization. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and academic research underwrites the qualitative findings. Primary interviews with manufacturing plant managers, R&D directors, procurement specialists, and medical device engineers provided critical insights. This approach combined bottom-up data collection with top-down market validation. Secondary sources included ISO standards databases and national automotive production statistics.
Rate-of-change decomposition modeled market dynamics across the analysis window. Segmentation dimensions included product type, end-user, technology, application, and regional regulatory clusters. Compound annual growth rates were derived from historical data and projected growth drivers. Key forecast inputs included global automotive production forecasts and anticipated medical device regulatory changes.
Geopolitical shifts, material science breakthroughs, and new regulatory mandates are the dominant revision risks. Forecasts reflect current market assumptions regarding technology adoption and economic stability. A model refresh is warranted upon material change in global trade policies or key regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Alcohol Sensor Market
Sensors
Indoor Location Market
Sensors
Indoor Air Quality Monitor Market
Sensors
Traffic Sensor Market
Sensors
Surface Haptic Technology Market
Sensors
Global Heat Stress Monitor (HSM) Market
Sensors
Asia Pacific Container Monitoring Market
Sensors
Transport Monitoring System Market
Sensors
Bluetooth Photo Capture Device Market
Sensors
Safety Motion Control System Market
Sensors
Handheld RFID Readers Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
IO-Link Technology Market
Sensors
Smart Barcode Readers Market
Sensors
NB-IoT Smart Gas Meter Market