
 Small Volume Parenteral Market | 2026-2036
Small Volume Parenteral Market Size, Share, and Industry Trends Forecast 2026-2036
Small Volume Parenteral Market Analytics
Home care buyers are gaining share against hospital procurement as ambulatory infusion protocols expand, and demand is bifurcating between acute institutional purchasers and decentralized outpatient settings. Fresenius Kabi AG anchors European manufacturing capacity for premixed IV solutions. Pfizer Inc. leverages its sterile injectables portfolio across oncology and anti-infective therapeutic areas. B. Braun Melsungen AG dominates European home infusion services through integrated pump and parenteral nutrition offerings.
Small volume parenterals are sterile drug products packaged in containers of 100 mL or less, typically formulated as aqueous solutions or lyophilized powders for reconstitution, then administered by intravenous, intramuscular, or subcutaneous injection. Pre-filled syringes command premium positioning due to their reduction of medication errors and elimination of dosing steps in clinical workflow. Ampoules retain cost-sensitive volume in emerging markets but face displacement by vial and pre-filled syringe formats where USP <797> and EU GMP Annex 1 compliance costs escalate.
The FDA enforces Current Good Manufacturing Practice for sterile drugs through its guidance on container-closure integrity, while the EMA implements the EU GMP Annex 1 revision mandating barrier isolation technology for aseptic processing. These frameworks elevate capital requirements for new entrants and accelerate obsolescence of open-vial filling lines. Stakeholders must weigh facility upgrade timelines against the shift toward pre-filled syringes and closed-system transfer devices.
Market Dynamics
Hospital-at-home program expansion and regulatory mandates for container-closure integrity are restructuring demand toward pre-filled syringes and closed-system transfer devices, compressing legacy ampoule and open-vial formats.
Growth Catalysts
- EU GMP Annex 1 Revision:Barrier isolation technology mandates for aseptic processing are accelerating capital deployment toward advanced filling lines and closed-system manufacturing.
- Home Infusion Protocols:Ambulatory care settings in the United States, Germany, and China are expanding SVP consumption outside traditional hospital procurement channels.
- Pre-filled Syringe Format:Medication error reduction and clinical workflow compression are driving format substitution across oncology and anti-infective therapeutic areas.
Market Restraints
- Glass and Polymer Input Volatility:Borosilicate glass and cyclic olefin polymer supply concentration exposes manufacturers to raw material cost swings and qualification delays.
- Facility Upgrade Capex Burden:USP <797> compliance and FDA sterile drug guidance requirements demand eight-figure capital commitments for legacy open-line obsolescence.
- Lyophilized Powder Complexity:Reconstitution steps and stability requirements limit format substitution in cost-sensitive emerging market segments.
Strategic Opportunities
- Biologic-Compatible Delivery Systems:Convergence of pre-filled syringes with closed-system transfer devices opens high-value positioning in oncology and immunology.
- United States Hospital-at-Home Expansion:CMS reimbursement alignment and acute care decentralization are creating dedicated SVP demand outside institutional purchasing.
- China NMPA Accelerated Pathways:Domestic manufacturing scale-up incentives and import substitution policies favor local sterile fill-finish capacity expansion.
Industry Challenges
- Aseptic Processing Talent Scarcity:Qualified personnel for barrier isolation operation and contamination control strategy implementation remain in short supply across manufacturing networks.
- Legacy System Integration Friction:Retrofitting existing fill-finish lines with isolator technology while maintaining commercial supply creates operational complexity and validation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Volume Parenteral Market |
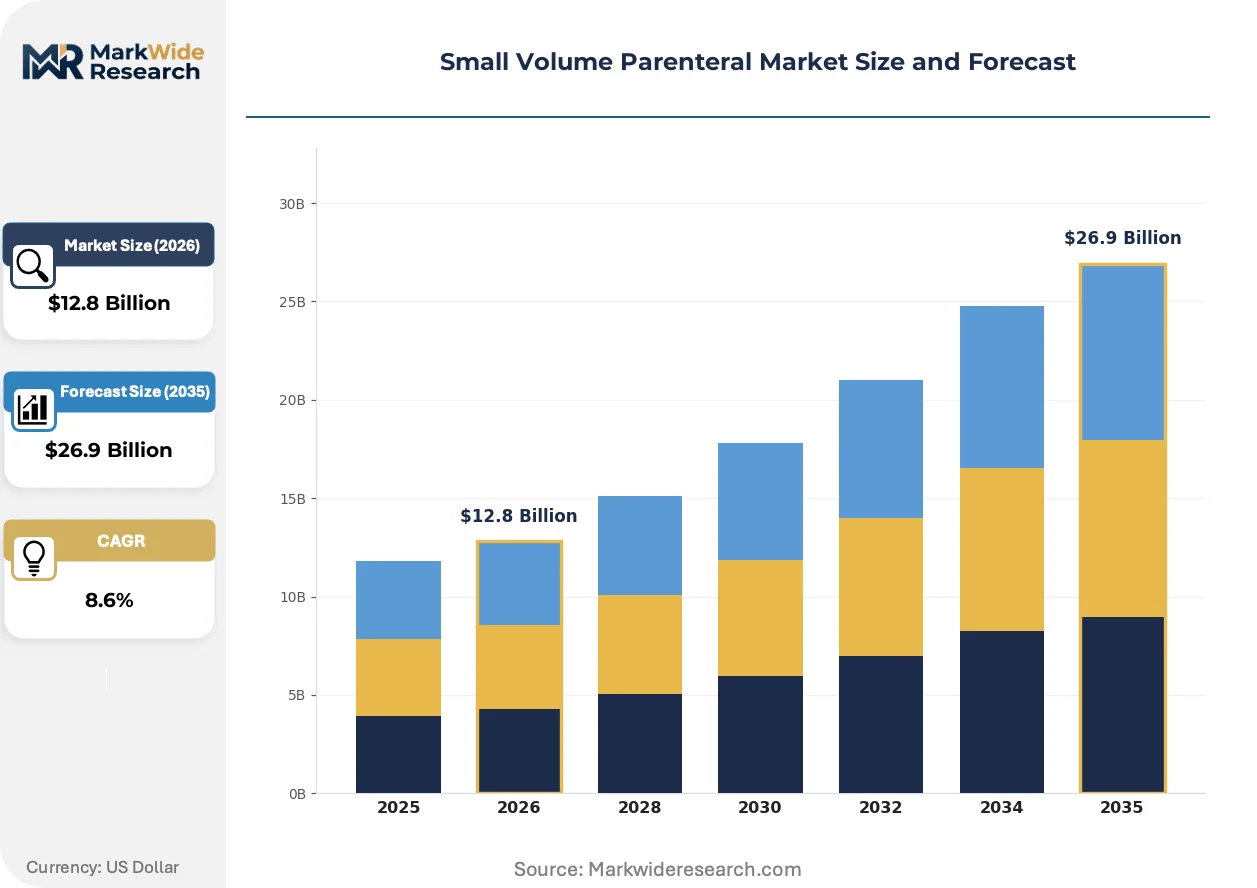
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Pre-filled Syringes, Infusion Bottles End User: Hospitals, Home Care, Specialty Clinics, Long-term Care Facilities Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Continuous Infusion Packaging Type: Single-dose, Multi-dose, Blister Packs, Disposable |
| Companies Covered | Sichuan Kelun Pharmaceutical Co., Ltd., Pfizer Inc., Fresenius Kabi AG, BML Parenteral Drugs, Becton Dickinson and Company, Baxter International Inc., ICU Medical, Inc., Akums Drugs & Pharmaceuticals Ltd., B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Volume Parenteral Market Evolving Landscape
Pre-filled delivery systems, regulatory technology mandates, and decentralized care models are compressing traditional format lifecycles and redrawing competitive boundaries across manufacturing and distribution.
Closed-system transfer device technology is miniaturizing drug compounding and administration workflows for hazardous pharmaceuticals. Oncology and antineoplastic therapy units in the United States and Germany are adopting these systems at accelerated pace to protect healthcare workers from exposure. The format is miniaturizing the role of traditional pharmacy compounding in clinical settings, shifting value capture toward integrated device-drug combinations.
EMA's EU GMP Annex 1 revision mandating barrier isolation technology for aseptic processing took effect across European manufacturing facilities. The regulation elevates capital barriers for new market entrants and accelerates obsolescence of conventional cleanroom filling operations. Small and mid-scale sterile manufacturers in Germany, France, and Italy are responding through facility consolidation and contract manufacturing organization partnerships.
Group purchasing organization consolidation and direct manufacturer contracting are compressing distributor intermediation in United States hospital procurement. Integrated delivery networks and specialty pharmacy channels are capturing volume previously flowing through wholesale distribution. This channel restructuring is most visible in oncology and parenteral nutrition segments where pump and infusion service bundling creates captive supply relationships.
Small Volume Parenteral Market Segmentation
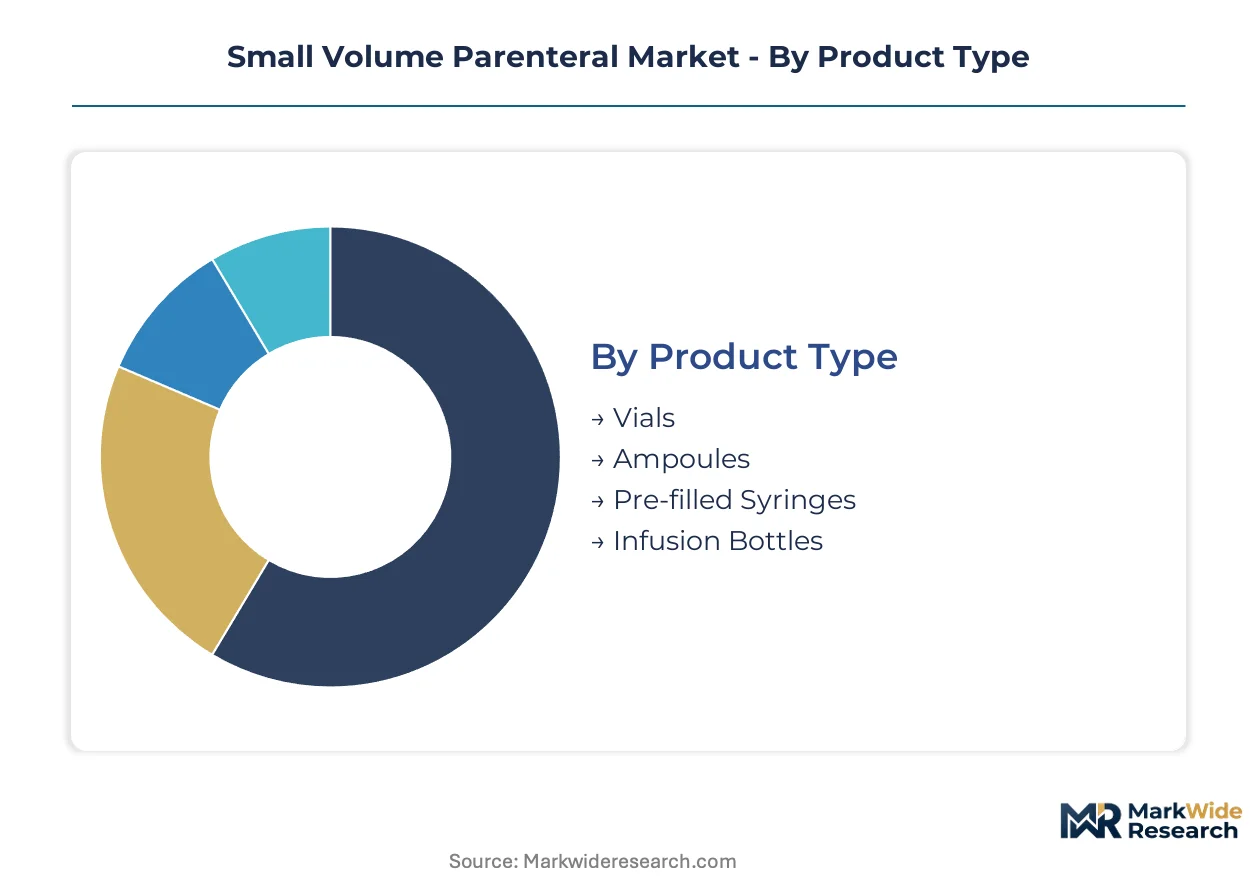
Small volume parenteral segmentation reveals divergent channel economics. Pre-filled syringes command premium positioning through hospital-at-home and specialty pharmacy networks, while ampoules and vials flow through consolidated institutional procurement. Format selection directly determines regulatory compliance burden and margin structure.
Product Type:
Channel mix varies sharply by container format. Pre-filled syringes bypass pharmacy compounding through direct-to-patient distribution, while vials and ampoules concentrate in hospital centralized purchasing.
- Pre-filled Syringes:These sterile, ready-to-inject units integrate drug and delivery device in a single closed system. United States hospital-at-home programs and German ambulatory oncology services are driving demand as CMS reimbursement aligns with decentralized administration protocols.
- Vials:Multi-dose glass or polymer containers requiring aseptic withdrawal before administration. Institutional purchasers in China and the United States favor vials for high-volume anti-infective and anesthesia applications where unit economics outweigh workflow efficiency.
- Ampoules:Single-use glass containers with breakable necks, prevalent in cost-sensitive emerging markets facing EU GMP Annex 1 compliance barriers.
- Infusion Bottles:Flexible or semi-rigid containers for intermittent or continuous infusion, positioned between vial and pre-filled syringe convenience tiers.
By volume, vials lead institutional procurement. By growth pace, pre-filled syringes are expanding most quickly.
End User:
Customer type determines specification requirements and contracting structure. Acute care facilities prioritize reliability and scale, while decentralized settings emphasize portability and error reduction.
- Hospitals:Large-scale institutional purchasers driving consolidated procurement through group purchasing organizations. United States integrated delivery networks and Chinese tertiary hospitals dominate volume, with FDA sterile drug guidance and NMPA GMP standards shaping supplier qualification.
- Home Care:Patients receiving parenteral therapy outside institutional settings through infusion nursing services. Germany's statutory health insurance reimbursement for home parenteral nutrition and United States CMS hospital-at-home waivers are accelerating format shift toward pre-filled, closed-system devices.
- Specialty Clinics:Outpatient oncology and immunology centers requiring hazardous drug handling protocols.
- Long-term Care Facilities:Skilled nursing settings with intermediate acuity and nursing resource constraints.
By installed base, hospitals dominate. By expansion trajectory, home care is gaining share fastest.
Delivery Mode:
Route of administration dictates container specification, stability requirements, and training intensity. Intravenous delivery imposes the most stringent particulate and endotoxin standards.
- Intravenous:Direct vascular administration requiring absolute sterility and pyrogen-free certification. United States oncology units and Chinese emergency departments concentrate demand, with USP <797> compounding regulations and EU GMP Annex 1 barrier isolation mandates elevating quality thresholds.
- Subcutaneous:Tissue-layer injection enabling patient self-administration. German diabetes and immunology patients increasingly manage therapy at home, driving pre-filled syringe and pen injector adoption.
- Intramuscular:Depot injection for vaccines and long-acting formulations.
- Continuous Infusion:Extended delivery via ambulatory pump systems, common in parenteral nutrition and pain management.
By procedure volume, intravenous leads. By patient migration trends, subcutaneous formats are climbing the fastest.
Packaging Type:
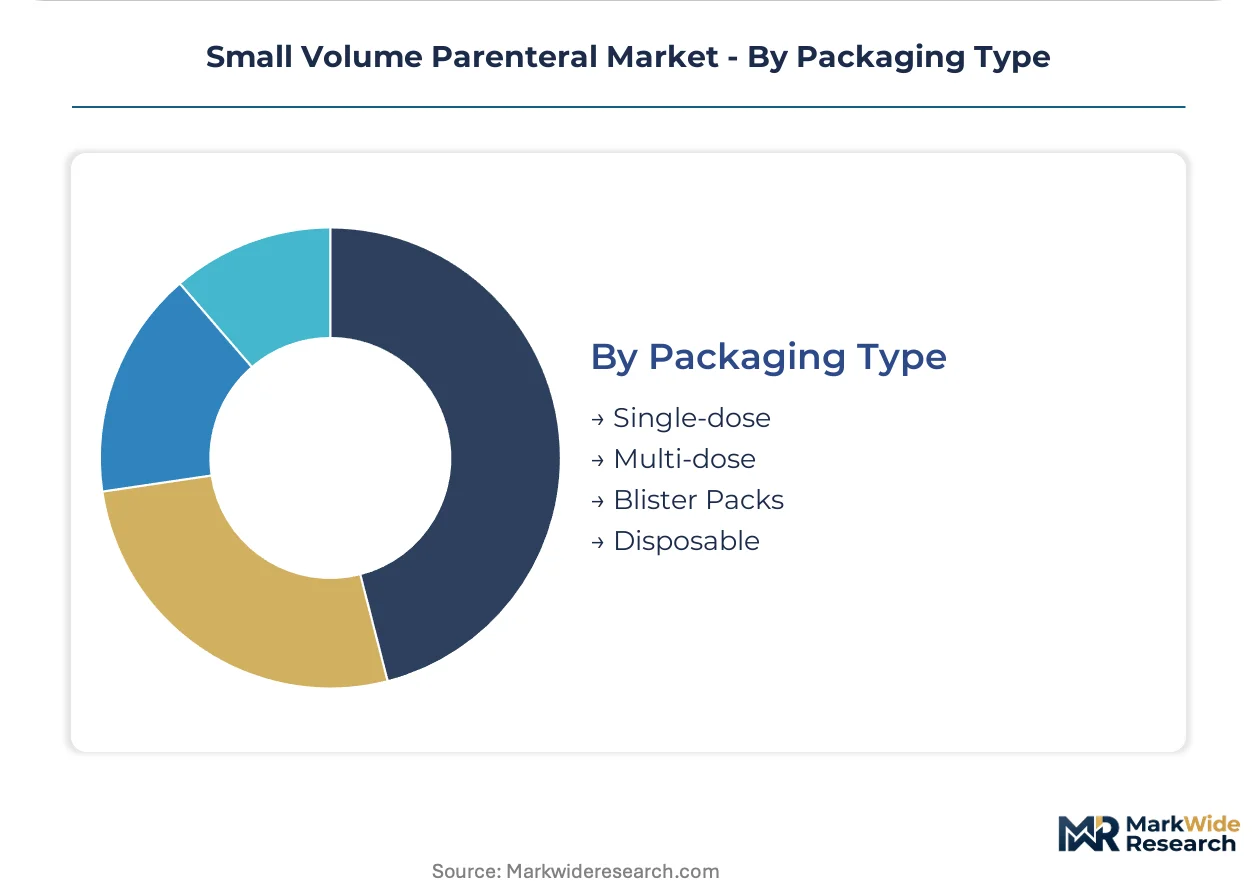
Packaging configuration balances microbial integrity, dosing flexibility, and waste minimization. Single-dose formats eliminate preservative concerns but generate higher per-dose material cost.
- Single-dose:Unit-of-use packaging eliminating cross-contamination risk and preservative requirements. United States 503B compounding outsourcing facilities and German hospital pharmacies favor single-dose vials for high-risk patient populations under USP <797> and EU GMP Annex 1 contamination control strategies.
- Multi-dose:Containers with preservative systems enabling multiple withdrawals. Cost-sensitive institutional purchasers in China and India leverage multi-dose formats for high-volume anti-infective and anesthesia applications.
- Blister Packs:Individual cavity packaging for ampoules or small vials, common in emergency and field medicine kits.
- Disposable:Integrated drug-device combinations for single-use administration.
By unit volume, multi-dose leads. By regulatory momentum, single-dose formats show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors European sterile drug distribution, while direct rail links from Shanghai Pudong International Airport feed fill-finish capacity across the Yangtze River Delta. These logistics assets concentrate SVP manufacturing and distribution in three primary markets.
United States
Hospital-at-home program expansion and CMS reimbursement waivers are redirecting SVP consumption toward ambulatory settings. FDA enforcement of Current Good Manufacturing Practice for sterile drugs elevates compliance costs for domestic manufacturers. The Boston-Cambridge biopharma corridor and Research Triangle Park in North Carolina host concentrated fill-finish operations serving oncology and anti-infective therapeutic areas.
Germany
Statutory health insurance reimbursement for home parenteral nutrition is accelerating format shift toward pre-filled, closed-system devices. EMA implementation of EU GMP Annex 1 mandates barrier isolation technology across aseptic processing facilities. The Rhine-Main region around Frankfurt and the Munich metropolitan area concentrate sterile manufacturing capacity for premixed IV solutions and infusion services.
China
Domestic manufacturing scale-up incentives and NMPA accelerated approval pathways are expanding local fill-finish capacity for import substitution. The country's national pharmaceutical regulator is aligning GMP standards with international barrier isolation requirements. Shanghai Zhangjiang Hi-Tech Park and Suzhou Industrial Park host concentrated sterile injectables operations serving domestic and export markets.
India
Contract manufacturing organization partnerships are absorbing facility consolidation pressures from EU GMP Annex 1 compliance barriers in Europe. The Central Drugs Standard Control Organization is strengthening active pharmaceutical ingredient and formulation oversight through revised Schedule M guidelines. Hyderabad's Genome Valley and Ahmedabad's pharmaceutical manufacturing belt are expanding sterile fill-finish operations for global supply.
Small Volume Parenteral Market Competitive Landscape
Concentration sits with diversified healthcare conglomerates and specialized parenteral drug manufacturers. The market structure reflects tiered competition between integrated pharmaceutical majors, dedicated sterile injectables specialists, and regional contract manufacturing organizations. Three archetypes dominate: European engineering-driven conglomerates with pump-device integration, North American biopharma majors leveraging oncology portfolios, and Asian scale manufacturers serving cost-sensitive institutional procurement. Competitive moves center on facility retrofit partnerships for isolator technology compliance and direct contracting with integrated delivery networks bypassing wholesale distribution.
Among European-based healthcare conglomerates, Fresenius Kabi AG and B. Braun Melsungen AG exemplify the engineering-driven archetype with integrated device-drug offerings. Pfizer Inc. represents the North American biopharma major leveraging sterile injectables across therapeutic areas. Sichuan Kelun Pharmaceutical Co., Ltd. anchors the Asian scale manufacturer tier serving institutional procurement channels.
| Leading Market Players |
|---|
| Sichuan Kelun Pharmaceutical Co., Ltd. |
| Pfizer Inc. |
| Fresenius Kabi AG |
| BML Parenteral Drugs |
| Becton Dickinson and Company |
| Baxter International Inc. |
| ICU Medical, Inc. |
| Akums Drugs & Pharmaceuticals Ltd. |
| B. Braun Melsungen AG |
| Others |
Value Network & Pricing Analysis
Pre-filled syringe substitution for glass ampoules simultaneously concentrates manufacturing in Germany and the United States while compressing per-unit economics across cost-sensitive procurement tiers. This format migration rewards integrated device-drug manufacturers with pricing power over institutional buyers facing EU GMP Annex 1 compliance deadlines.
Pricing Analysis
Volume-discount tiering structures separate pre-filled syringe premiums from vial standard pricing and ampoule economy tiers across group purchasing organization contracts. Price differentiation hinges on FDA sterile drug guidance certification grades and barrier isolation technology deployment in manufacturing facilities. Pricing pressure stems from raw material cost compression in borosilicate glass and cyclic olefin polymer feedstocks. Home care settings demonstrate lowest price sensitivity due to bundled reimbursement protocols, while emerging market institutional procurement maintains acute cost discipline.
Supply Chain Analysis
Borosilicate glass furnace capacity in Germany and China anchors upstream material security for sterile container manufacturing. Cyclic olefin polymer resin production draws from South Korean and Japanese petrochemical complexes. Supply chain risk concentrates in single-source qualification timelines for barrier isolation equipment. Distribution runs through integrated delivery networks in the United States, statutory health insurance channels in Germany, and tertiary hospital procurement systems in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Format fragmentation across pre-filled syringes, closed-system transfer devices, and legacy vial formats creates specialized manufacturing niches as hospital-at-home programs demand differentiated delivery economics.
For Market Incumbents: Compound isolator technology deployment through facility retrofit partnerships in the Rhine-Main region and Research Triangle Park to preempt EU GMP Annex 1 obsolescence risk. Deepen backward integration into cyclic olefin polymer compounding to secure margin position against raw material volatility. Capture home infusion service bundling to lock integrated delivery network contracts before distributor consolidation accelerates.
For New Entrants and Emerging Players: Contract manufacturing service gaps in barrier isolation qualification and validation create entry points for mid-scale sterile fill-finish specialists. Target United States 503B compounding outsourcing facilities and German hospital pharmacy networks as most penetrable demand pools. Lead with isolator-as-a-service operating models to bypass eight-figure capital barriers.
For Investors and Strategic Acquirers: The market sits at a regulatory-mandated consolidation phase that favors engineering-driven conglomerates with integrated pump-device capabilities over pure-play drug manufacturers. Five-to-ten year viability favors targets with EU GMP Annex 1 compliant capacity and hospital-at-home distribution relationships. Watch CMS reimbursement expansion for hospital-at-home services as inflection signal for ambulatory format demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Isolator Retrofit Partnership | EU GMP Annex 1 compliance accelerates obsolescence of open-vial filling lines across European manufacturing. |
| Closed-System Transfer Device Integration | Oncology and antineoplastic therapy units in Germany and the United States adopt hazardous drug handling protocols. |
| Hospital-at-Home Distribution Contract | CMS reimbursement alignment creates captive supply relationships outside traditional wholesale channels. |
| Backward Integration into Polymer Compounding | Cyclic olefin polymer supply concentration exposes manufacturers to qualification delays and cost volatility. |
| 503B Compounding Outsourcing Partnership | United States hospital pharmacies seek USP 797 compliant single-dose capacity for high-risk patient populations. |
Research Methodology
The analysis maps pre-filled syringe, vial, ampoule, and infusion bottle sub-sectors, each validated through primary interviews with sterile manufacturing executives, regulatory affairs leads, hospital procurement managers, and GPO contracts directors. Secondary validation draws from FDA sterile drug guidance filings, EMA GMP inspection reports, CMS reimbursement databases, and hospital procurement system records. Bottom-up facility capacity modeling triangulates against top-down therapeutic area demand projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions span container format, end-user setting, delivery mode, and packaging configuration alongside regional regulatory cluster differentiation. CAGRs derive from facility utilization rates, format substitution elasticities, and reimbursement policy trajectories. Forecast inputs incorporate barrier isolation technology deployment timelines and hospital-at-home program expansion curves.
Forecasts assume regulatory continuity in FDA sterile drug guidance and EU GMP Annex 1 regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as CMS reimbursement waivers and NMPA accelerated pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Global Erythropoietin Stimulating Agents Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Italy Pharmaceutical Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Canagliflozin Market