
 Canagliflozin Market | 2026-2036
Canagliflozin Market Size, Share, and Industry Trends Forecast 2026-2036
Canagliflozin Market Insights
Asset-light licensing and royalty-based manufacturing partnerships is rewriting competitive economics for generic canagliflozin producers. Janssen Pharmaceuticals leverages its originator data package to sustain brand loyalty in cardiorenal indications. Dr. Reddy's Laboratories anchors its position through backward integration into API production. Laurus Labs competes on cost structure by controlling fermentation-to-finish manufacturing in India.
Canagliflozin is a selective sodium-glucose cotransporter 2 (SGLT2) inhibitor with a molecular weight of 444.5 g/mol, formulated primarily as 100 mg and 300 mg film-coated tablets for oral administration. It blocks glucose reabsorption in the proximal renal tubule, promoting urinary glucose excretion and reducing hyperglycemia in adults with type 2 diabetes mellitus. The therapy area segmentation reveals diabetes type 2 as the established revenue base, while chronic kidney disease represents the fastest-expanding indication as nephrology societies update treatment algorithms. Among end users, hospitals capture the highest prescription volumes for initiation therapy, though homecare channels are extending reach for maintenance dosing as mail-order pharmacy networks deepen.
The FDA maintains stringent post-marketing surveillance requirements for SGLT2 inhibitors, including boxed warnings on lower-limb amputation risk that shape physician prescribing thresholds. The EMA's pharmacovigilance framework and India's CDSCO bioequivalence standards for generic approvals create layered compliance obligations for multinational manufacturers. Stakeholders must monitor evolving reimbursement criteria for cardiorenal indications across Medicare, NHS England, and India's National Health Mission as these determine which therapy areas manufacturers prioritize for clinical evidence generation.
Market Dynamics
Medicare coverage decisions for cardiorenal indications are restructuring prescribing economics and redirecting clinical trial investment toward renal outcome endpoints rather than glycemic control alone.
Growth Catalysts
- Cardiorenal outcome trials:Nephrology societies in the United States and European Union are updating treatment algorithms to prioritize SGLT2 inhibitors for chronic kidney disease progression delay, expanding addressable patient populations beyond diabetes.
- Hospital formulary adoption:Payer contracts in the United States increasingly bundle cardiovascular-renal risk reduction metrics into oral antidiabetic procurement criteria, accelerating institutional prescribing.
- API manufacturing scale-up:Fermentation-to-finish production capabilities in India are compressing generic cost structures and enabling volume penetration into national health missions.
Market Restraints
- Boxed warning compliance:FDA-mandated lower-limb amputation risk labeling elevates physician liability thresholds and restricts initiation in peripheral vascular disease patients.
- API supply concentration:Active pharmaceutical ingredient production clusters in specific Indian states create geographic vulnerability to environmental regulatory shutdowns.
- Biosimilar substitution pressure:GLP-1 receptor agonists for type 2 diabetes are capturing physician mindshare and formulary slots in obese patient segments.
Strategic Opportunities
- Heart failure with preserved ejection fraction:Regulatory submissions for this indication in the United States would unlock Medicare reimbursement for a population exceeding type 2 diabetes prevalence in older adults.
- Mail-order pharmacy networks:Homecare channel expansion for maintenance dosing reduces hospital readmission penalties and aligns with Medicare Advantage quality metrics.
- CDSCO abbreviated approval pathway:India's streamlined bioequivalence standards for SGLT2 inhibitors enable faster generic entry into government procurement tenders.
Industry Challenges
- Post-marketing surveillance infrastructure:FDA adverse event reporting requirements for lower-limb amputations demand dedicated pharmacovigilance teams that strain mid-cap generic manufacturers.
- Cardiorenal trial recruitment:Competing SGLT2 inhibitors crowd renal outcome study enrollment, extending trial timelines and inflating per-patient costs.
- Legacy diabetes prescribing habits:Endocrinology practices with established metformin-first protocols require intensive medical education investment to shift initiation patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canagliflozin Market |
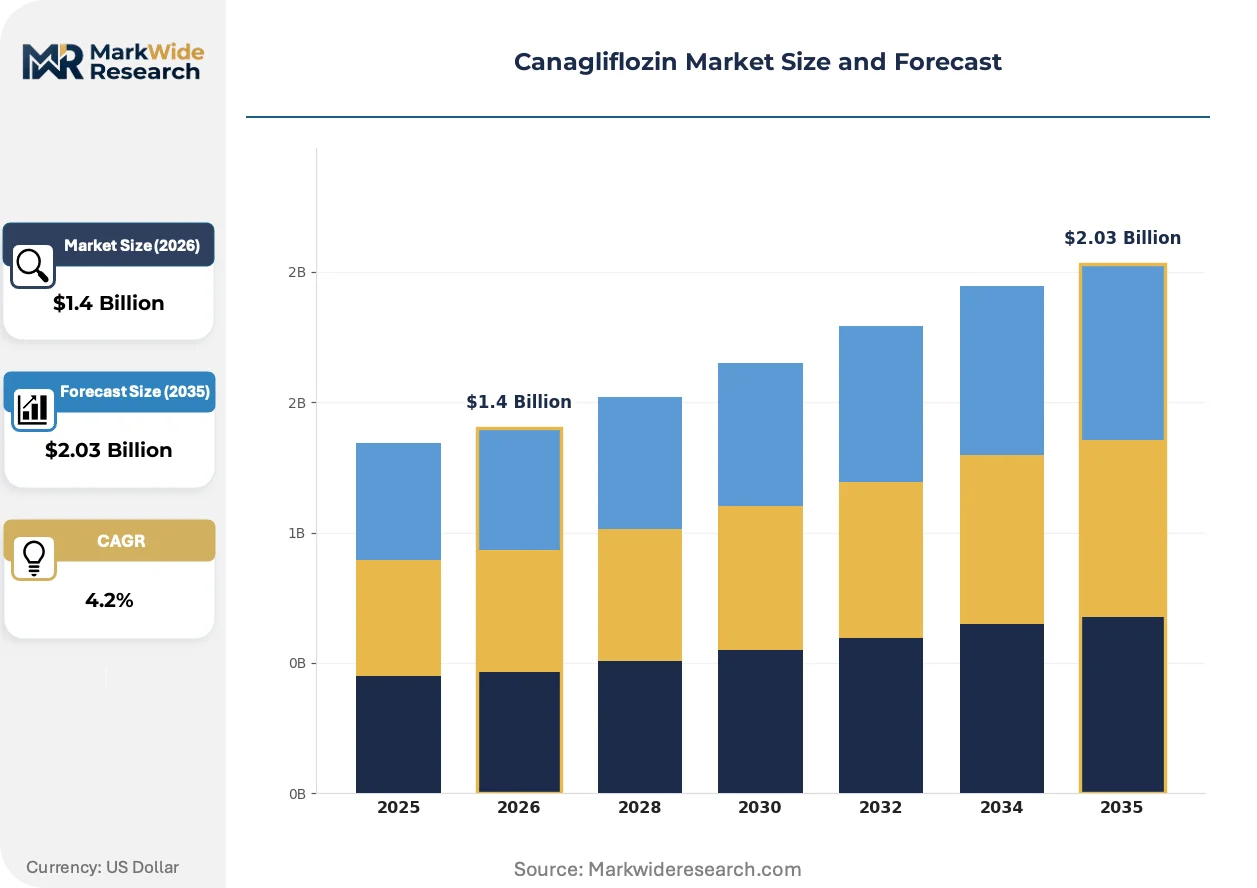
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injections, Solutions, Oral Suspensions Therapy Area: Diabetes Type 2, Obesity, Cardiovascular Diseases, Chronic Kidney Disease End User: Hospitals, Clinics, Homecare, Pharmacies Delivery Mode: Oral, Subcutaneous, Intravenous, Patch |
| Companies Covered | Janssen Pharmaceuticals, Johnson & Johnson, AstraZeneca, Dr. Reddy's Laboratories, Macleods, Sandoz, Teva Active Pharmaceutical Ingredients, Laurus Labs, Apotex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canagliflozin Market Trends and Innovations
Fixed-dose combination formulations are compressing the competitive landscape by merging SGLT2 inhibition with complementary mechanisms into single-pill regimens that simplify adherence protocols.
Continuous manufacturing technology is collapsing batch-to-batch variability in film-coated tablet production. Contract development organizations serving United States and European Union markets are adopting modular production lines that reduce changeover times. This compression enables just-in-time inventory models that align with hospital procurement consolidation.
EMA's evolving pharmacovigilance framework for SGLT2 inhibitors is mandating real-world evidence collection through patient registries. Manufacturers must now fund longitudinal outcome studies across European member states. The renal indication segment bears the heaviest compliance burden as nephrology societies demand granular dialysis progression data.
Hospital pharmacy buying groups are consolidating oral antidiabetic tenders into multi-year sole-source agreements. Group purchasing organizations in the United States now bundle cardiovascular-renal metrics into contract performance clauses. This concentration shifts negotiation leverage toward institutions and away from individual physician preference.
Canagliflozin Market Segmentation
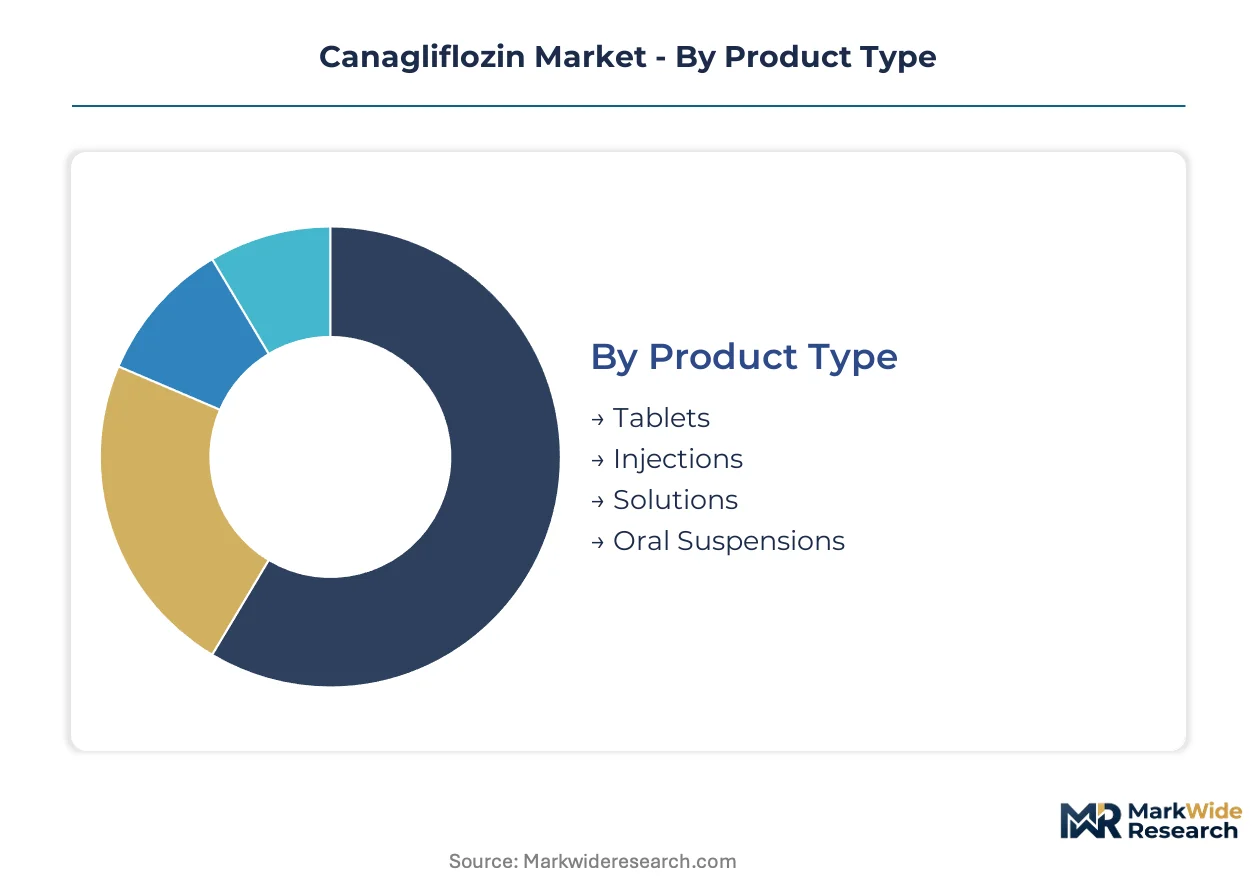
Canagliflozin's commercial architecture fragments across four critical dimensions. Product formulation dictates manufacturing complexity and regulatory pathway. Therapy area determines reimbursement codes and clinical evidence requirements. End-user channel shapes distribution economics and patient adherence monitoring. Delivery mode constrains partnership opportunities with device manufacturers.
Product Type:
Formulation diversity spans solid oral dosage through parenteral delivery, each commanding distinct capital intensity and quality control protocols.
- Tablets:Film-coated 100 mg and 300 mg configurations dominate commercial volumes. Hospital procurement contracts in the United States prioritize tablet stability profiles that withstand automated dispensing systems. The FDA's dissolution testing requirements for SGLT2 inhibitors elevate manufacturing precision thresholds.
- Injections:Subcutaneous depot formulations remain investigational for canagliflozin specifically. Clinical trial sponsors in the European Union are exploring extended-release injectable platforms to differentiate from oral SGLT2 competitors. EMA guidelines on biocompatibility testing for novel excipients prolong development timelines.
- Solutions:Liquid formulations serve pediatric and geriatric populations with swallowing difficulties. India's CDSCO requires additional stability data for aqueous canagliflozin preparations.
- Oral Suspensions:Reconstitutable powders address dose titration flexibility in renal impairment adjustments. Compounding pharmacies in the United States utilize suspensions for individualized glycemic protocols.
The dominant share belongs to Tablets, while Injections are closing the gap fastest through depot formulation innovation.
Therapy Area:
Indication breadth determines pricing power and regulatory exclusivity horizons across cardiorenal medicine.
- Diabetes Type 2:Established glycemic control indication anchors formulary placement. Medicare Advantage plans in the United States increasingly require documented cardiovascular risk to authorize SGLT2 initiation. The boxed warning on lower-limb amputations constrains prescribing in peripheral vascular disease patients.
- Chronic Kidney Disease:Renal outcome indication commands premium reimbursement independent of diabetes status. Nephrology societies in the European Union updated treatment algorithms to prioritize SGLT2 inhibitors for dialysis delay. EMA pharmacovigilance frameworks mandate granular progression data collection.
- Obesity:Weight loss effects are secondary to glycemic indication without standalone regulatory approval. GLP-1 receptor agonists capture physician mindshare in this segment.
- Cardiovascular Diseases:Heart failure with reduced ejection fraction carries specific labeling in the United States. FDA review timelines for preserved ejection fraction submissions will determine competitive positioning against dapagliflozin.
Diabetes Type 2 maintains volume leadership, though Chronic Kidney Disease is gaining share fastest as renal societies revise treatment hierarchies.
End User:
Channel configuration determines patient monitoring infrastructure and adherence intervention capabilities.
- Hospitals:Institutional settings capture initiation therapy for acute presentations. United States group purchasing organizations bundle cardiovascular-renal metrics into oral antidiabetic tender performance clauses.
- Homecare:Mail-order pharmacy networks extend maintenance dosing reach. Medicare Advantage quality metrics reward reduced readmission penalties through home delivery models.
- Clinics:Outpatient endocrinology practices require intensive medical education investment to shift from metformin-first protocols.
- Pharmacies:Retail dispensing faces substitution pressure from preferred SGLT2 inhibitors on commercial formularies.
Hospitals command the highest prescription volumes for initiation, while Homecare is expanding most quickly through integrated delivery network partnerships.
Delivery Mode:
Administration route constrains partnership architectures with device and infusion service providers.
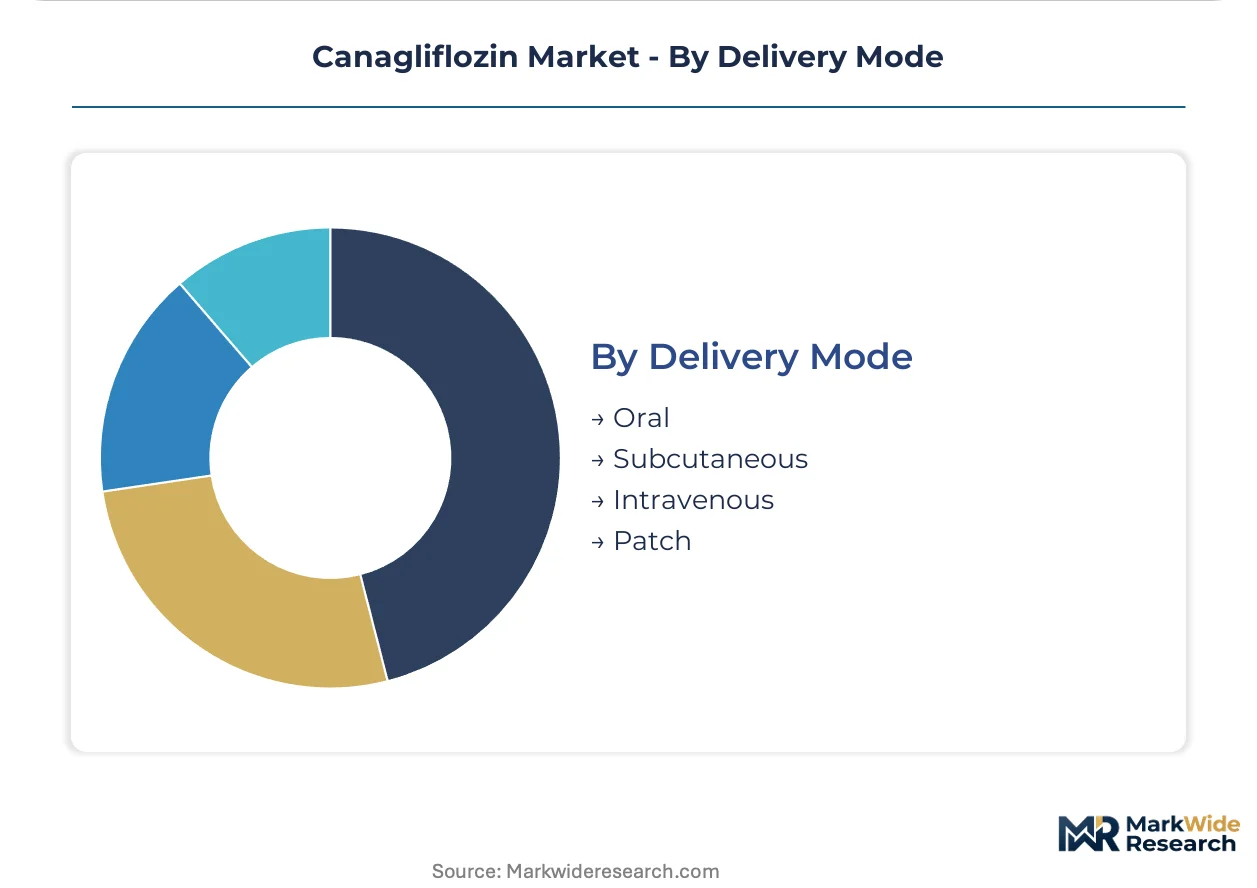
- Oral:Film-coated tablet administration dominates patient preference and compliance metrics. Continuous manufacturing technology is collapsing batch-to-batch variability in United States and European Union contract development organizations.
- Subcutaneous:Investigational depot formulations would require companion device development. India's fermentation-to-finish API producers are evaluating partnership structures for injectable platform licensing.
- Intravenous:No approved canagliflozin indication utilizes intravenous delivery. Academic medical centers have explored IV bioavailability in critical care glucose management protocols.
- Patch:Transdermal delivery remains preclinical for SGLT2 inhibitors generally. Skin permeation challenges for this molecular weight class have stalled pharmaceutical development investment.
Oral delivery retains absolute dominance, while Subcutaneous is advancing fastest through extended-release formulation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement criteria for cardiorenal indications in the United States are redirecting clinical trial investment toward renal outcome endpoints. The FDA's evolving guidance on SGLT2 inhibitor labeling is compressing development timelines for generic manufacturers seeking abbreviated approval pathways. India's CDSCO bioequivalence standards are enabling faster market entry for fermentation-to-finish API producers.
United States
Hospital formulary adoption concentrates prescription volumes for initiation therapy. Medicare Advantage plans bundle cardiovascular-renal metrics into oral antidiabetic procurement contracts. The Boston-Cambridge corridor anchors cardiorenal outcome trial infrastructure as academic medical centers recruit for renal progression studies.
Germany
Nephrology societies updated treatment algorithms to prioritize SGLT2 inhibitors for chronic kidney disease progression delay. EMA pharmacovigilance frameworks mandate real-world evidence collection through patient registries. The Rhine-Ruhr industrial cluster hosts contract development organizations adopting continuous manufacturing technology for film-coated tablet production.
India
Fermentation-to-finish API production capabilities compress generic cost structures for national health mission tenders. CDSCO streamlined bioequivalence standards accelerate abbreviated approval pathways for SGLT2 inhibitors. Hyderabad and Visakhapatnam pharmaceutical corridors concentrate backward-integrated manufacturing for export markets.
United Kingdom
NHS England reimbursement criteria for cardiorenal indications determine manufacturer prioritization of clinical evidence generation. EMA post-marketing surveillance requirements for lower-limb amputation risk elevate pharmacovigilance compliance costs. The Golden Triangle research cluster between London, Oxford, and Cambridge drives renal outcome study recruitment.
Japan
PMDA review timelines for heart failure with preserved ejection fraction submissions will determine competitive positioning against dapagliflozin. METI industrial policy supports domestic API production to reduce import dependence. The Kansai pharmaceutical manufacturing belt around Osaka maintains formulation expertise for film-coated tablet exports.
Canagliflozin Market Competitive Landscape
On the supply side, the industry is consolidating around originator data packages and generic cost-structure optimization. Large pharmaceutical conglomerates leverage cardiorenal trial infrastructure to sustain brand loyalty in institutional channels. Mid-cap generic specialists anchor positions through backward integration into API production. Fermentation-to-finish manufacturers compete on volume penetration into government procurement tenders. Dominant competitive moves include strategic partnerships for royalty-based manufacturing and capacity expansion in Indian pharmaceutical corridors.
Within the originator tier, Janssen Pharmaceuticals exemplifies sustained brand positioning through cardiorenal indication expansion. Among generic API-integrated specialists, Dr. Reddy's Laboratories and Laurus Labs occupy positions defined by backward integration into fermentation-based production. These anchors represent divergent strategic archetypes: proprietary clinical data leverage versus cost-structure compression through captive supply chains.
| Leading Market Players |
|---|
| Janssen Pharmaceuticals |
| Johnson & Johnson |
| AstraZeneca |
| Dr. Reddy's Laboratories |
| Macleods |
| Sandoz |
| Teva Active Pharmaceutical Ingredients |
| Laurus Labs |
| Apotex |
| Others |
Pricing and Supply Chain Analysis
Hyderabad's fermentation-to-finish API corridors concentrate canagliflozin manufacturing capacity, compressing generic cost structures and amplifying pricing power for backward-integrated producers bidding into United States hospital procurement tenders.
Pricing Analysis
Certification level (FDA-grade versus CDSCO-abbreviated) creates the primary spread across canagliflozin supply tiers. Three-tier pricing structure separates originator cardiorenal data packages from bioequivalent generics and economy API-sourced volumes. Cost compression in the generic tier is intensifying because Indian fermentation scale-up has collapsed per-kilogram production costs. Hospital pharmacy buying groups exhibit the highest price sensitivity, while originator manufacturers serving Medicare Advantage cardiorenal bundles maintain the lowest.
Supply Chain Analysis
Upstream glucose-derived fermentation feedstocks and specialized biocatalyst enzymes anchor canagliflozin API production. Manufacturing gravity centers on India, China, and select European Union contract development sites. The supply chain draws from concentrated fermentation capacity in Telangana and Andhra Pradesh, creating single-source vulnerability to environmental regulatory shutdowns. Distribution runs through United States group purchasing organization networks and India's National Health Mission tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canagliflozin's competitive architecture rewards regulatory entrenchment, where FDA cardiorenal labeling and EMA pharmacovigilance frameworks erect switching costs that protect incumbent data packages from generic erosion.
For Market Incumbents: Build regulatory data moats through cardiorenal outcome trial completion before generic dapagliflozin competitors secure heart failure with preserved ejection fraction labeling. Invest in continuous manufacturing certification at Rhine-Ruhr contract development sites to defend margin position against Indian API-integrated challengers. Prioritize Medicare Advantage quality metric bundling to lock hospital formulary placement against GLP-1 substitution pressure.
For New Entrants and Emerging Players: Chronic kidney disease maintenance dosing through United States mail-order pharmacy networks represents the most penetrable entry point for generic manufacturers with CDSCO abbreviated approval pathways. India's National Health Mission tenders for SGLT2 inhibitors offer volume penetration without originator clinical trial investment. Pursue royalty-based licensing from Hyderabad API producers to bypass fermentation capacity buildout timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-to-finish API specialists with captive backward integration into biocatalyst supply. Long-term viability rests on cardiorenal indication expansion beyond diabetes, where renal outcome data sustains pricing power through Medicare reimbursement cycles. Watch FDA review timelines for heart failure with preserved ejection fraction submissions as the inflection signal for competitive reordering.
| Strategic Initiative | Industry Significance |
|---|---|
| Cardiorenal Outcome Trial Advancement | FDA submissions for renal progression endpoints unlock Medicare reimbursement independent of glycemic indication. |
| Continuous Manufacturing Adoption | Rhine-Ruhr contract development organizations reduce batch variability to meet hospital automated dispensing specifications. |
| Backward Integration into API Production | Hyderabad fermentation corridors enable cost compression for National Health Mission tender competitiveness. |
| Mail-Order Pharmacy Network Expansion | Medicare Advantage quality metrics reward homecare channel reach for maintenance dosing adherence. |
| CDSCO Abbreviated Approval Pathway | Streamlined bioequivalence standards accelerate generic entry into government procurement tenders. |
Research Methodology
The analysis maps SGLT2 inhibitor therapy areas, dosage formulations, and regional regulatory clusters, each validated through formulary directors, hospital procurement managers, and payer access specialists. Primary interviews with drug development executives and regulatory affairs leads combine with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulate demand estimates across the projection horizon.
Forecast assumptions hold fixed the current FDA boxed warning framework and EMA pharmacovigilance requirements while varying cardiorenal indication expansion scenarios. Segmentation dimensions include therapy area, product formulation, end-user channel, and regional regulatory cluster. CAGRs derive from patient population epidemiology, treatment algorithm adoption curves, and pricing elasticity by certification tier. Forecast inputs incorporate nephrology society guideline revision timelines and Medicare Advantage quality metric evolution.
Practitioners should monitor FDA advisory committee outcomes for lower-limb amputation risk labeling changes and CDSCO environmental compliance actions in Telangana as early revision signals. Forecasts reflect assumptions about cardiorenal trial enrollment completion and generic API manufacturing scale-up that industry-specific risks could alter. Cross-checking against CMS Medicare Part D utilization benchmarks and NHS England prescribing analytics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Ocular Excipients Market