
 Synthetic Drugs Market | 2026-2036
Synthetic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Drugs Market Analysis
Subscription-based pharmacovigilance monitoring and REMS compliance services is hardening into a mandatory cost layer for manufacturers. AbbVie leverages its immunology franchise to sustain high-margin synthetic drug portfolios across hospital networks. Teva Pharmaceutical Industries anchors its position through generic injectable capacity, while Dr. Reddy's Laboratories competes on API-to-finished-dose integration for cost-sensitive markets.
Synthetic drugs comprise chemically manufactured pharmaceutical compounds produced through organic synthesis rather than biological extraction, with precise molecular weights, purity thresholds exceeding 99.5%, and batch-to-batch consistency enforced by ICH Q3D guidelines on elemental impurities; these agents serve as the backbone of standardized, scalable therapies in pain management, psychiatric care, and surgical anesthesia. Oral formulations dominate volume across pain management and mental health applications due to patient compliance advantages and lower cold-chain requirements, while injectable delivery modes capture premium pricing in anesthesia and emergency settings where rapid bioavailability determines clinical outcomes. The stimulants and opioids product categories face diverging regulatory fates, with depressants and hallucinogens finding narrower but protected niches in treatment-resistant populations.
The FDA enforces REMS and DEA scheduling that restricts distribution channels and mandates prescriber certification for controlled synthetics, while the EU's MDR and EMA pharmacovigilance framework impose post-market surveillance obligations that elevate compliance costs for European market access. India's CDSCO aligns with ICH standards through its New Drugs and Clinical Trials Rules, creating a pathway for domestic manufacturers to supply regulated markets. Stakeholders must monitor scheduling reclassifications and real-world evidence requirements as the primary variables that will reshape product portfolios and geographic prioritization.
Market Dynamics
REMS certification requirements and DEA scheduling protocols are compressing distribution channels for controlled synthetics, forcing manufacturers to absorb compliance infrastructure costs that now exceed raw material expenditures in high-potency opioid categories.
Growth Catalysts
- Oncology analgesic protocols:Academic medical centers in the United States are expanding synthetic opioid use in palliative care regimens, creating institutional demand pull-through for high-purity injectable formulations.
- EMA pharmacovigilance framework:Post-market surveillance mandates under the EU MDR are generating recurring revenue streams for third-party REMS compliance service providers serving European manufacturers.
- Continuous flow chemistry:API manufacturers in India are adopting modular reactor platforms that slash batch cycle times and elemental impurity variability below ICH Q3D thresholds.
Market Restraints
- Precursor chemical volatility:N-phenethyl-4-piperidone and other scheduled starting materials face import quota restrictions that spike working capital requirements for generic injectable producers.
- Single-source API concentration:China dominates intermediate supply for fentanyl-class compounds, creating geographic chokepoints that amplify disruption risk from customs inspections or environmental enforcement actions.
- Bioequivalence demonstration costs:Complex synthetic molecules with polymorphic instability require extended stability studies that extend ANDA timelines for generic entrants.
Strategic Opportunities
- Treatment-resistant depression protocols:Ketamine-derived psychotropics are securing breakthrough therapy designations that accelerate FDA review timelines for novel delivery mechanisms.
- Subscription pharmacovigilance models:Real-world evidence collection platforms are displacing periodic safety reports, enabling recurring revenue capture from mid-cap manufacturers lacking in-house REMS infrastructure.
- CDSCO harmonization pathway:India's alignment with ICH standards through the New Drugs and Clinical Trials Rules creates export-ready manufacturing capacity for regulated markets without redundant facility audits.
Industry Challenges
- Analytical method development bottlenecks:Genotoxic impurity identification at parts-per-billion levels requires mass spectrometry specialists whose scarcity extends validation timelines.
- Cold-chain infrastructure gaps:Temperature-sensitive peptide-synthetic hybrids demand validated distribution networks that exceed the capabilities of traditional generic wholesalers.
- Cross-scheduling complexity:Dual DEA and state-level controlled substance licenses create jurisdictional friction that delays product launches by 6-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Drugs Market |
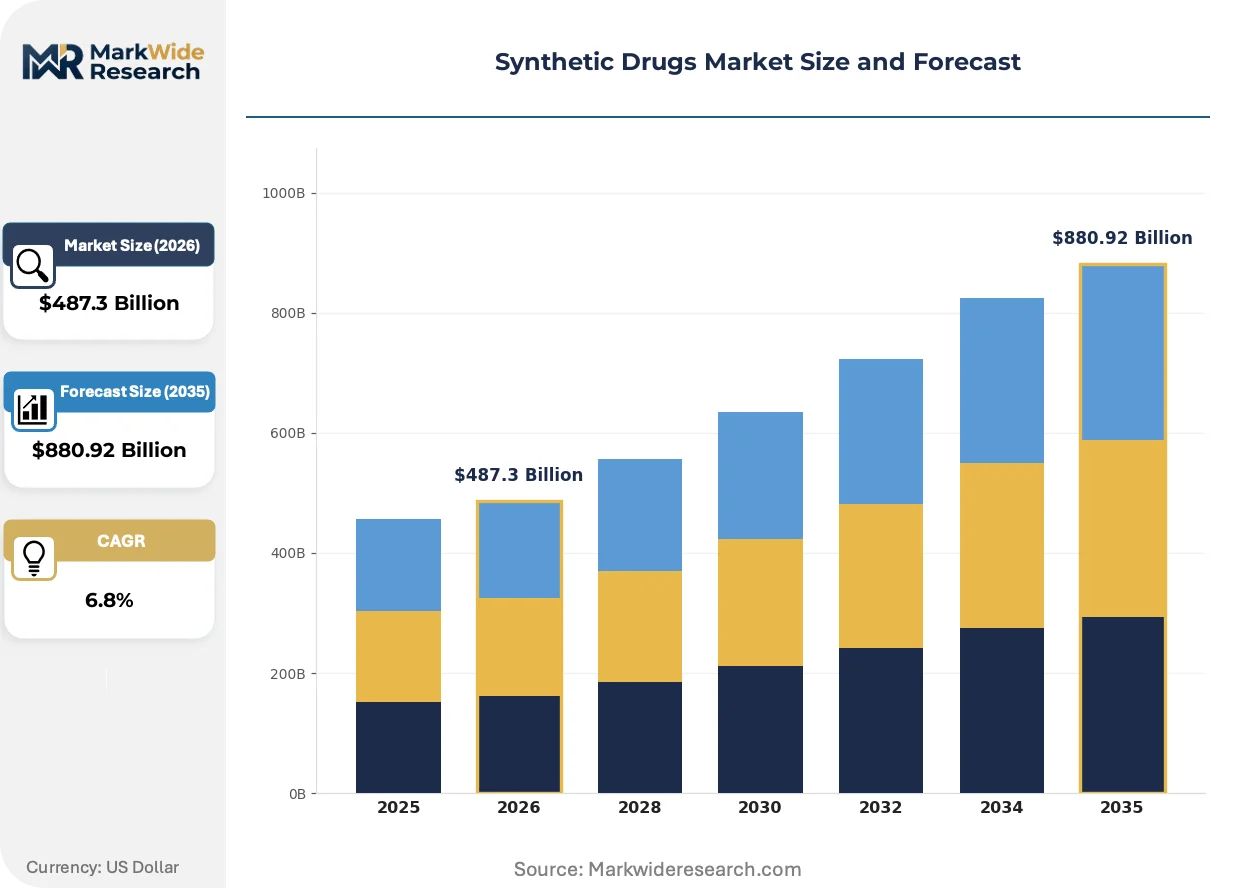
| Market Size in 2026 | $487.3 Billion |
| Market Size in 2035 | $880.92 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulants, Depressants, Hallucinogens, Opioids Application: Pain Management, Anesthesia, Treatment of Disorders, Mental Health Delivery Mode: Oral, Injectable, Transdermal, Inhalation End User: Hospitals, Clinics, Pharmacies, Rehabilitation Centers |
| Companies Covered | AbbVie, Merck & Co., Bristol-Myers Squibb Company, Cipla, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Dr. Reddy's Laboratories, Aurobindo Pharma, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Drugs Market Emerging Trajectories
Manufacturing technology convergence and regulatory data requirements are compressing development cycles while elevating the capital threshold for market participation. Three developments are restructuring competitive position.
Continuous manufacturing platforms are replacing batch synthesis for high-volume analgesics. Pfizer and Novartis manufacturing networks are retrofitting legacy facilities with PAT-enabled flow reactors that slash solvent waste and crystallization variability. This hardware transition is expanding into mid-tier generic houses that previously lacked process analytical chemistry capabilities.
The FDA's enhanced REMS documentation requirements for extended-release opioids now mandate prescriber certification renewal every two years. This policy shift forces manufacturers to maintain dedicated compliance liaison staff within hospital pharmacy departments. Pain management clinics in the United States are responding by consolidating formulary decisions through integrated delivery networks that reduce prescriber fragmentation.
Hospital procurement consortia are displacing individual pharmacy purchasing for synthetic anesthetics and controlled psychotropics. These buying coalitions extract volume-based rebates that compress distributor margins. Germany's university hospital networks and India's AIIMS-affiliated institutions are consolidating tender processes through digital procurement platforms that standardize quality specifications above minimum regulatory thresholds.
Synthetic Drugs Market Segmentation
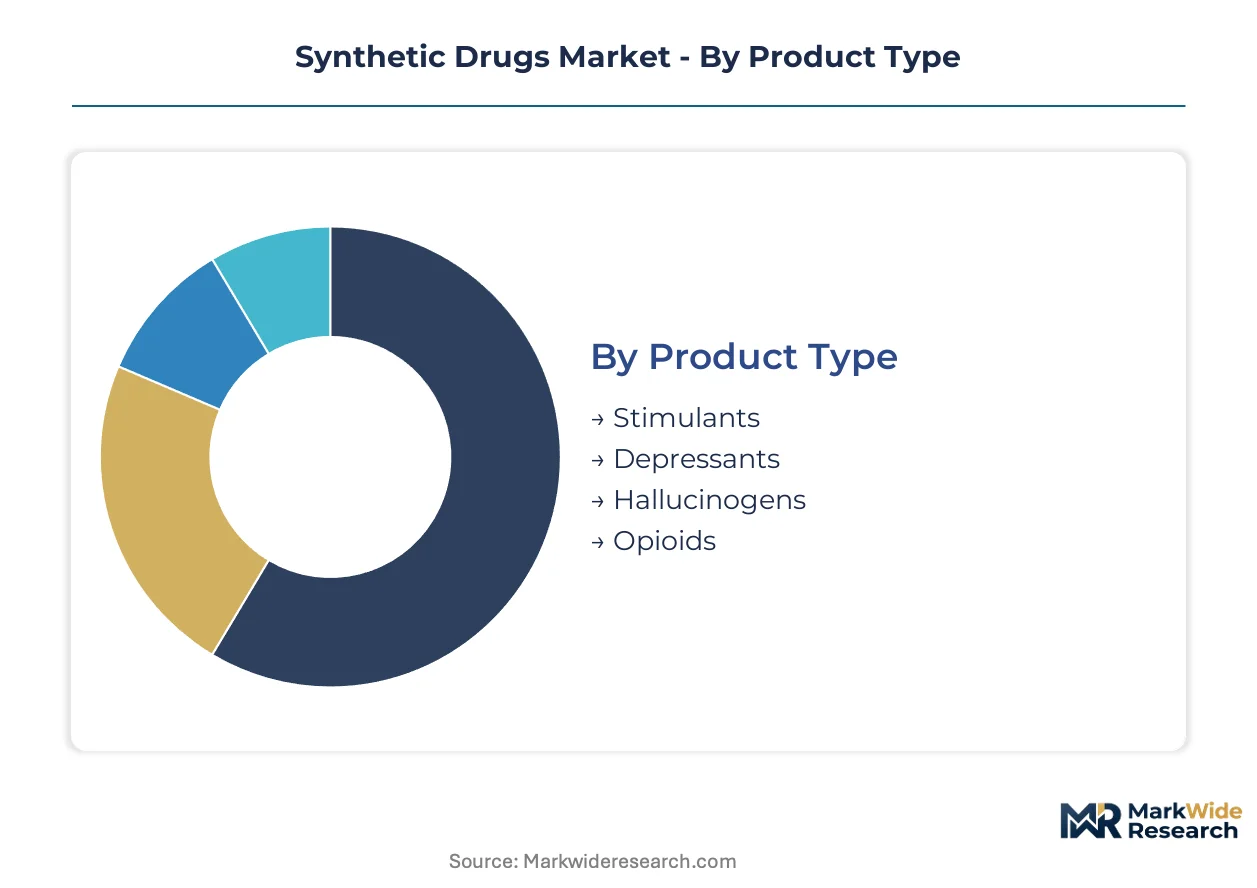
Synthetic drug manufacturers configure production assets around molecular complexity and regulatory burden. Segment-level capital requirements determine which product lines attract investment and which remain specialty niches.
Product Type:
Capital intensity escalates sharply with controlled-substance scheduling tier and synthesis complexity.
- Stimulants:Amphetamine-class compounds require dedicated DEA-licensed facilities with vault storage and dual-person integrity protocols. Hospital procurement networks in the United States concentrate demand for ADHD therapeutics through integrated delivery systems that extract volume rebates.
- Opioids:Fentanyl derivatives demand the highest upfront investment due to containment infrastructure and REMS compliance systems. Academic medical centers in Germany and the United States anchor institutional demand for high-purity injectable formulations in palliative care protocols.
- Depressants:Benzodiazepine synthesis operates at moderate capital thresholds with established generic competition. Barbiturate manufacturing has consolidated to three domestic suppliers serving niche anesthesia applications.
- Hallucinogens:Psilocybin and ketamine-derived compounds require specialized containment and batch isolation. Treatment-resistant depression protocols at research hospitals are creating protected demand niches.
Most installed capacity flows through Opioids. Expansion is steepest in Hallucinogens.
Application:
Reimbursement velocity and clinical evidence requirements separate high-margin from commoditized segments.
- Pain Management:Extended-release formulations command premium pricing through REMS-protected distribution channels. Medicare Part D coverage determinations in the United States drive formulary placement for synthetic analgesics.
- Anesthesia:Rapid-onset intravenous agents require cold-chain validation and hospital pharmacy integration. German university hospital networks standardize procurement specifications above minimum regulatory thresholds.
- Treatment of Disorders:Orphan indications and breakthrough therapy designations accelerate FDA review timelines for novel synthetic psychotropics.
- Mental Health:Oral antidepressant and anxiolytic volumes face generic erosion with limited differentiation beyond bioequivalence certification.
Revenue concentrates in Pain Management. Margin expansion is sharpest in Anesthesia.
Delivery Mode:
Patient compliance economics and distribution infrastructure shape segment viability across geographies.
- Oral:Tablet and capsule formulations dominate prescription volumes with minimal cold-chain requirements. Indian generic manufacturers leverage API-to-finished-dose integration to supply cost-sensitive markets.
- Injectable: Vial and prefilled syringe formats capture premium pricing in emergency and surgical settings where bioavailability determines clinical outcomes. Sterile manufacturing capacity constraints limit new entrants.
- Transdermal:Patch delivery systems require specialized adhesive chemistry and permeation testing. Chronic pain clinics in the United States favor extended-wear formulations for opioid rotation protocols.
- Inhalation:Nebulized and dry-powder devices demand device-drug combination approvals with elevated regulatory burden. Anesthesia departments utilize inhalational agents for titratable sedation depth.
Volume leadership sits with Oral. Value capture is climbing fastest in Injectable.
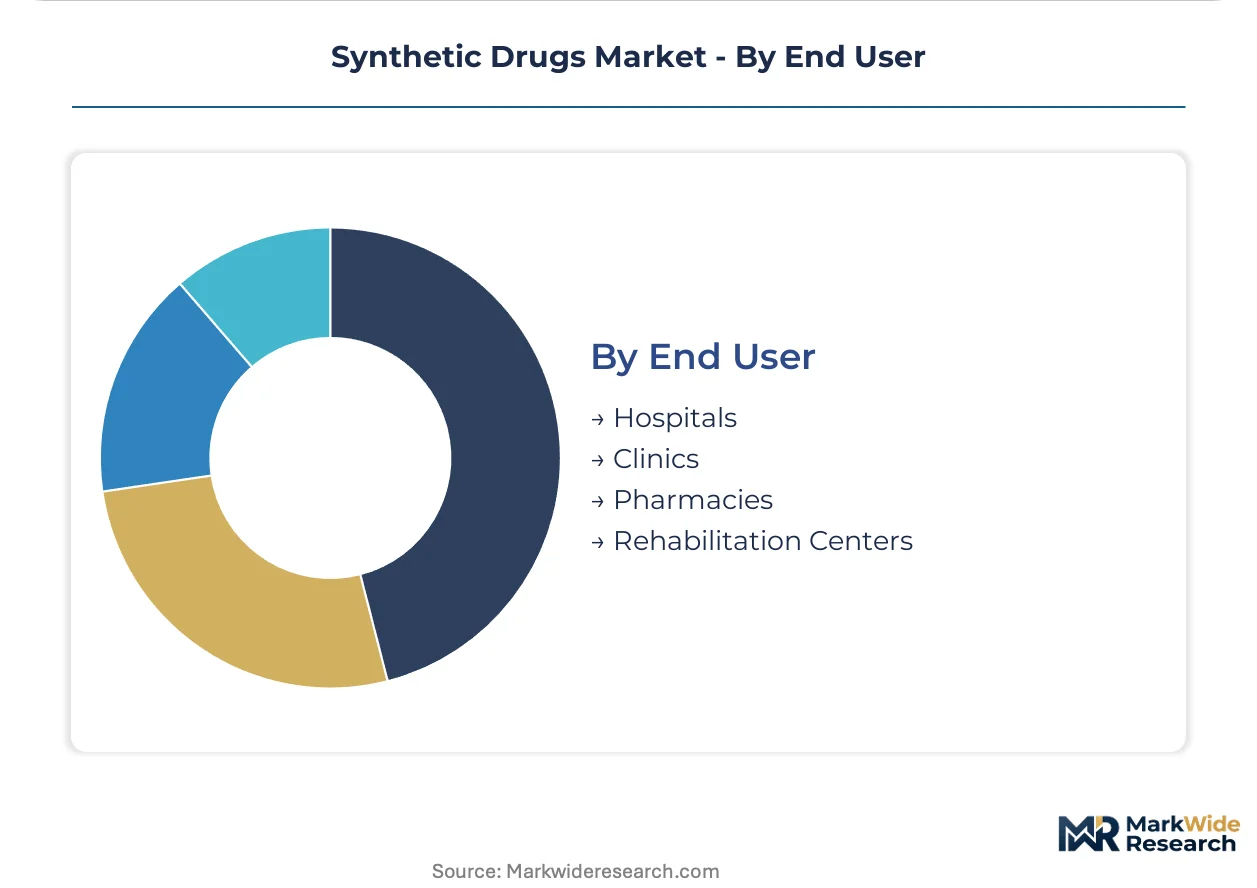
End User:
Purchasing concentration and credentialing requirements fragment access across institutional categories.
- Hospitals:Integrated delivery networks consolidate formulary decisions for controlled synthetics through digital procurement platforms. REMS compliance liaison staff maintain prescriber certification databases within pharmacy departments.
- Clinics:Pain management and psychiatric practices face prescriber fragmentation that complicates manufacturer account management. Consolidation through health system affiliation is compressing independent purchasing autonomy.
- Pharmacies:Retail chains navigate dual DEA and state-level controlled substance licenses that create jurisdictional friction. Automated dispensing systems track inventory at the dose level.
- Rehabilitation Centers:Medication-assisted therapy protocols generate recurring demand for synthetic opioid antagonists and partial agonists. Medicaid reimbursement rates constrain product selection.
Procurement gravity centers on Hospitals. Account complexity is intensifying fastest in Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting synthetic drug manufacturing toward jurisdictions where compliance costs align with margin structures. Producers migrate capacity based on the gap between pharmacovigilance infrastructure investment and market access returns.
United States
Academic medical centers in Massachusetts and California are expanding palliative care protocols that institutionalize high-purity injectable demand. FDA's REMS program mandates prescriber certification renewal every two years, elevating compliance infrastructure costs above raw material expenditures. The Philadelphia-Wilmington corridor anchors sterile manufacturing clusters serving hospital procurement networks.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia are consolidating tender processes through digital procurement platforms. EMA pharmacovigilance framework under EU MDR imposes post-market surveillance obligations that generate recurring revenue for third-party compliance services. The Frankfurt-Rhine-Main region concentrates API finishing capacity for regulated European distribution.
India
Generic injectable manufacturers in Telangana and Gujarat are adopting continuous flow chemistry platforms that reduce batch cycle times. CDSCO alignment with ICH standards through New Drugs and Clinical Trials Rules creates export-ready capacity without redundant facility audits. The Hyderabad-Visakhapatnam corridor hosts API-to-finished-dose integration clusters serving cost-sensitive markets.
China
Intermediate suppliers in Jiangsu and Zhejiang provinces dominate starting material production for fentanyl-class compounds. NMPA enforcement of environmental standards at chemical parks is disrupting legacy batch synthesis operations. The Yangtze River Delta concentrates precursor chemical capacity that feeds downstream formulation networks.
Switzerland
Specialty psychotropic developers in Basel and Zurich are securing breakthrough therapy designations for ketamine-derived compounds. Swissmedic's alignment with FDA review timelines accelerates dual-approval strategies for novel delivery mechanisms. The Basel-Liestal corridor anchors containment infrastructure for hallucinogen research programs.
Synthetic Drugs Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in controlled substances and fragmented competition in oral generics. The vendor base organizes around three archetypes: immunology-franchise incumbents sustaining high-margin portfolios, generic injectable houses anchoring volume through sterile capacity, and API-integrated Indian manufacturers competing on cost-sensitive tenders. Dominant competitive moves include M&A to acquire REMS compliance infrastructure and strategic partnerships to secure precursor chemical supply.
Within the branded-specialist tier, AbbVie and Bristol-Myers Squibb occupy positions sustained by hospital network penetration and therapeutic franchise depth. Among generic-scale manufacturers, Teva Pharmaceutical Industries and Dr. Reddy's Laboratories exemplify divergent geographic strategies—Teva anchoring sterile injectable capacity for regulated markets, Dr. Reddy's leveraging API integration for emerging market tenders. Sun Pharmaceutical Industries and Aurobindo Pharma represent the Indian manufacturing archetype, with Cipla occupying a hybrid position between branded and generic positioning. Boehringer Ingelheim International GmbH and Merck & Co. sit within the research-intensive segment where breakthrough designations protect margin structures.
| Leading Market Players |
|---|
| AbbVie |
| Merck & Co. |
| Bristol-Myers Squibb Company |
| Cipla |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Dr. Reddy's Laboratories |
| Aurobindo Pharma |
| Boehringer Ingelheim International GmbH |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consortia in the United States and Germany extract volume-based rebates that compress distributor margins and enforce three-tier pricing stratification across premium REMS-certified, standard bioequivalent, and economy unbranded tiers.
Pricing Analysis
Capacity additions in India are reshaping price floors for oral generic formulations while sterile injectable capacity constraints in regulated markets sustain premium capture. Pricing stratifies across REMS-certified premium, standard bioequivalent, and economy unbranded tiers, with FDA certification grade and volume scale as primary differentiation drivers. Cost compression in high-potency opioid categories intensifies because REMS compliance infrastructure now exceeds raw material expenditures. Generic API-integrated manufacturers exhibit highest price sensitivity; breakthrough-designation holders show lowest.
Supply Chain Analysis
Regional distribution centers in the Philadelphia-Wilmington corridor and Hyderabad-Visakhapatnam corridor anchor hub-and-spoke patterns for controlled substance distribution. API supply concentrates in China, India, and Switzerland, with intermediate production for fentanyl-class compounds drawing from Jiangsu and Zhejiang provinces. N-phenethyl-4-piperidone and other scheduled starting materials face import quota restrictions that amplify single-source vulnerability. Distribution runs through DEA-licensed vault networks with dual-person integrity protocols mandatory at each node.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
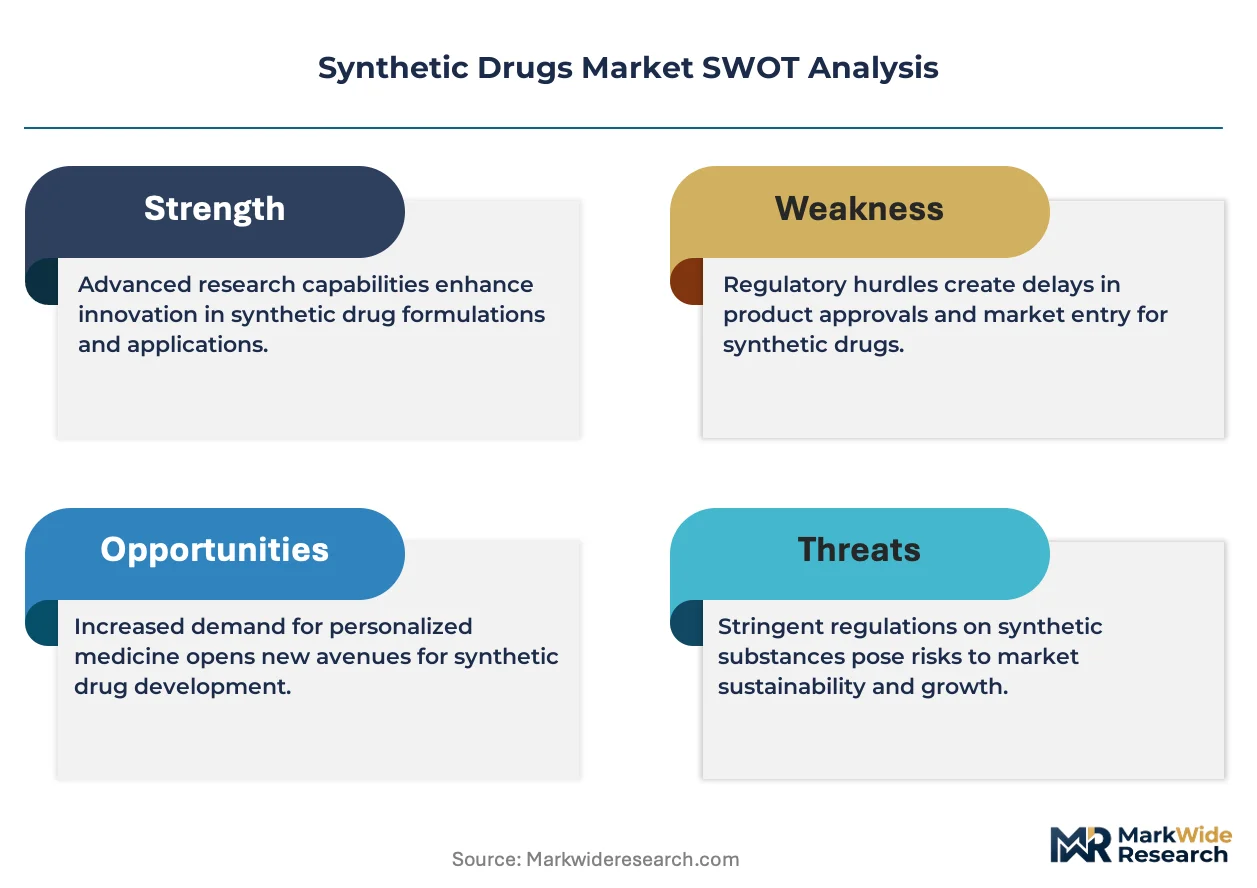
The synthetic drugs market compounds steadily as treatment-resistant depression protocols institutionalize demand for novel psychotropics across academic medical centers.
For Market Incumbents: Hedge against biosimilar erosion by acquiring REMS compliance infrastructure and securing captive supply of N-phenethyl-4-piperidone through backward integration into Chinese intermediate suppliers. Prioritize certification investment in continuous flow chemistry platforms that reduce batch cycle variability below ICH Q3D thresholds.
For New Entrants and Emerging Players: Enter via treatment-resistant depression protocols at research hospitals in Switzerland and the United States, where breakthrough therapy designations accelerate regulatory timelines. Target ketamine-derived psychotropics with novel delivery mechanisms as the most penetrable segment. Pursue strategic licensing agreements with established REMS compliance service providers rather than building in-house infrastructure.
For Investors and Strategic Acquirers: Generic injectable manufacturers with API-to-finished-dose integration are the most active acquirer targets in this space. The five-to-ten year viability window favors platforms with demonstrated EU MDR compliance and established hospital procurement network relationships. Monitor DEA scheduling reclassifications as the primary inflection signal for portfolio repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| REMS Compliance Infrastructure Acquisition | Hospital procurement networks mandate certified distribution channels for extended-release opioids under FDA renewal protocols. |
| Continuous Flow Chemistry Platform Deployment | Modular reactor installations at Telangana and Gujarat facilities reduce elemental impurity variability below ICH Q3D thresholds. |
| Breakthrough Therapy Designation Pursuit | Ketamine-derived compounds at Basel and Zurich research centers secure accelerated Swissmedic and FDA review timelines. |
| Precursor Chemical Supply Agreement | Long-term offtake contracts with Jiangsu and Zhejiang intermediate suppliers mitigate import quota disruption risk. |
| Subscription Pharmacovigilance Service Launch | Real-world evidence platforms displace periodic safety reports for mid-cap manufacturers lacking in-house REMS infrastructure. |
Methodological Framework
Multiple input streams — regulatory affairs leads at EMA and FDA, hospital formulary directors in Massachusetts and Bavaria, API procurement managers at Indian generic houses, and controlled substance distribution specialists — were reconciled through structured primary interviews and secondary validation against FDA REMS documentation, EMA pharmacovigilance filings, CDSCO New Drugs and Clinical Trials Rules, and DEA scheduling registers. Bottom-up capacity assessments at Hyderabad-Visakhapatnam and Philadelphia-Wilmington manufacturing clusters were cross-referenced against top-down demand modeling from hospital procurement consortia and academic medical center expansion plans.
Historical capacity utilization rates and panel-based input from sterile manufacturing executives were cross-referenced to anchor projections across the analysis window. Segmentation dimensions modeled include product scheduling tier, delivery mode complexity, end-user purchasing concentration, and regional regulatory cluster alignment. CAGRs were derived through iterative reconciliation of supply-side capacity expansion timelines with demand-pull indicators from palliative care protocol adoption. Forecast inputs incorporated continuous manufacturing adoption curves and REMS certification renewal frequency mandates.
Inputs from EMA post-market surveillance databases and CDSCO facility audit records were available through the study window; gaps in real-world evidence collection platform penetration rates introduce uncertainty bands around subscription pharmacovigilance revenue projections. Forecasts reflect documented assumptions regarding DEA scheduling stability and ICH Q3D guideline enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Asia-Pacific Cancer Vaccines Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Farm Animal Drugs Market