
 Granulocyte Macrophage Colony Stimulating Factor Market | 2026-2036
Granulocyte Macrophage Colony Stimulating Factor Market Size, Share, and Industry Trends Forecast 2026-2036
Granulocyte Macrophage Colony Stimulating Factor Market Intelligence
The bundling of Granulocyte Macrophage Colony Stimulating Factor (GM-CSF) therapies with specific oncology treatment protocols is restructuring procurement decisions by hospitals and cancer research institutes. Amgen Inc. leverages its foundational position in recombinant protein manufacturing to maintain a significant footprint. Sanofi competes through its extensive oncology portfolio and established distribution networks in Europe. Novartis differentiates with a focus on biosimilar development to capture cost-sensitive market segments.
Granulocyte Macrophage Colony Stimulating Factor is a glycoprotein cytokine that functions as a hematopoietic growth factor. Produced via recombinant DNA technology, it stimulates the proliferation and differentiation of granulocytes and macrophages to restore immune function. Recombinant proteins remain the dominant product type, though biosimilars are gaining traction due to cost advantages. Within applications, neutropenia treatment constitutes the largest segment, driven by its use as a supportive therapy in cancer patients undergoing chemotherapy.
Market access is governed by stringent regulatory frameworks, including clinical trial requirements set by the U.S. FDA and the European Medicines Agency (EMA). Japan's PMDA also imposes rigorous standards for drug approval and post-market surveillance, influencing development timelines. Consequently, manufacturers face a critical strategic choice: investing in novel, long-acting formulations or competing on price and market access with an expanding portfolio of biosimilars.
Market Dynamics
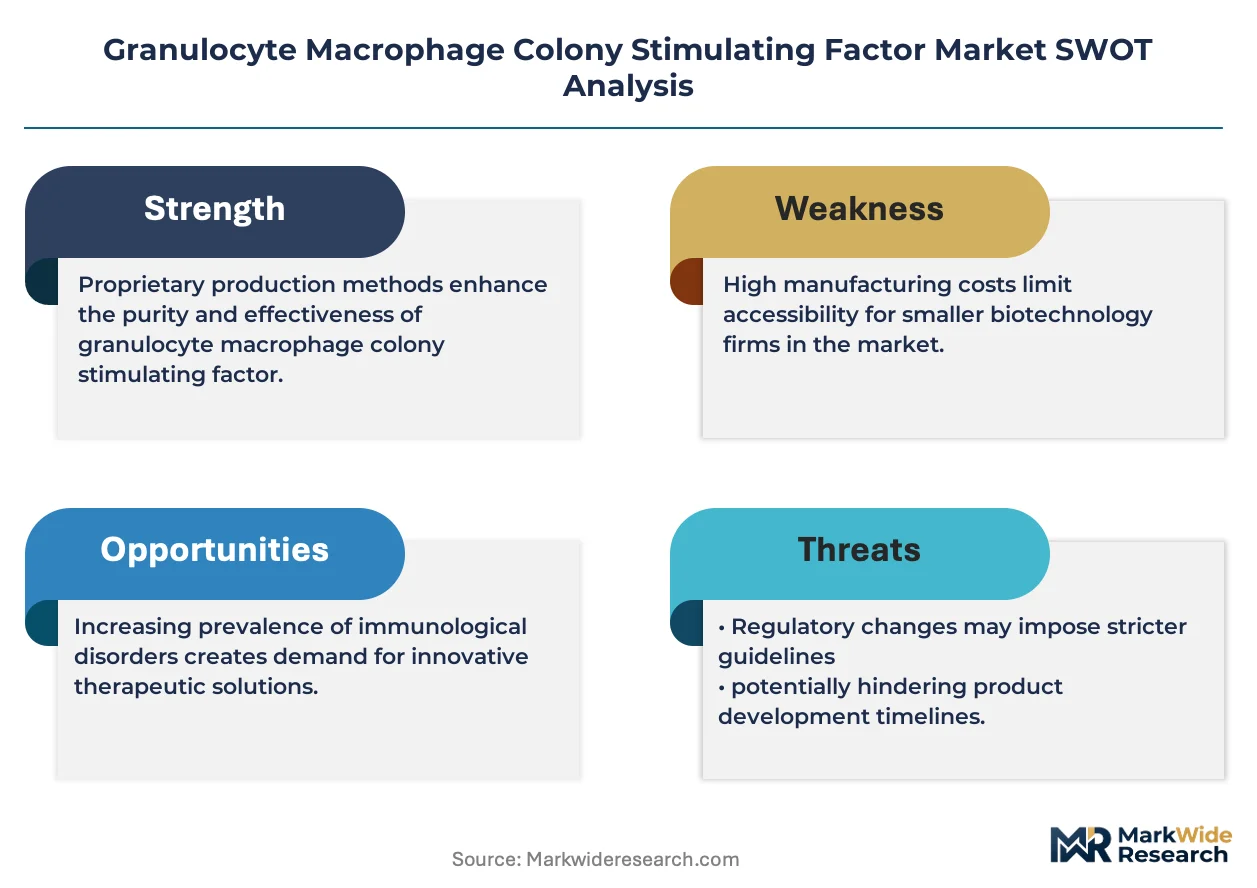
The fundamental market dynamic is the strategic tension between investing in novel, long-acting formulations that offer improved patient convenience and competing on price with an expanding portfolio of biosimilars, forcing manufacturers to choose between innovation-driven margins and volume-driven access.
Growth Catalysts
- Supportive Regulatory Pathways:The U.S. FDA's accelerated approval programs for supportive care oncology drugs reduce development timelines and costs, encouraging investment in new GM-CSF therapies for chemotherapy-induced neutropenia.
- Expanding Oncology Applications:The core use of GM-CSF to manage neutropenia continues to expand in line with the rising incidence of cancer and the increasing use of myelosuppressive chemotherapy regimens globally.
- Recombinant Technology Advances:Continuous improvements in recombinant DNA technology and cell culture techniques are enhancing manufacturing yields and reducing production costs, which can improve the affordability and accessibility of GM-CSF products.
Market Restraints
- High Manufacturing Complexity:The production of recombinant glycoproteins like GM-CSF is a complex, capital-intensive process, creating high barriers to entry and contributing to the therapy's elevated cost structure.
- Stringent Clinical Requirements:Regulatory bodies, including the EMA and Japan's PMDA, mandate extensive and costly clinical trials to demonstrate safety and efficacy, prolonging the time-to-market for new entrants and formulations.
- Therapeutic Substitution:Competition from other hematopoietic growth factors, particularly Granulocyte Colony-Stimulating Factor (G-CSF), for similar indications can limit market penetration in certain clinical settings.
Strategic Opportunities
- Long-Acting Formulations:Developing next-generation, long-acting GM-CSF products offers a significant opportunity to improve patient compliance and quality of life by reducing the frequency of injections required during treatment cycles.
- Exploration of New Indications:Research into the immunomodulatory properties of GM-CSF presents opportunities in novel therapeutic areas, such as in vaccine adjuvants or for treating certain rare diseases beyond hematology and oncology.
- Biosimilar Market Entry:The expiration of key patents on originator biologics creates a substantial opportunity for manufacturers to develop and launch biosimilar versions, capturing market share in cost-sensitive healthcare systems.
Industry Challenges
- Intellectual Property Disputes:The rise of biosimilars intensifies the risk of patent litigation between originator companies and new entrants, creating legal uncertainty and potentially delaying product launches.
- Cold Chain Logistics:Maintaining the integrity of the cold chain for temperature-sensitive biologics like GM-CSF across global supply routes poses significant logistical and financial challenges for manufacturers and distributors.
- Payer Pricing Pressure:Health systems and insurance payers are exerting significant downward pressure on drug prices, particularly with the availability of biosimilars, challenging the profitability of both originator and follow-on products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granulocyte Macrophage Colony Stimulating Factor Market |
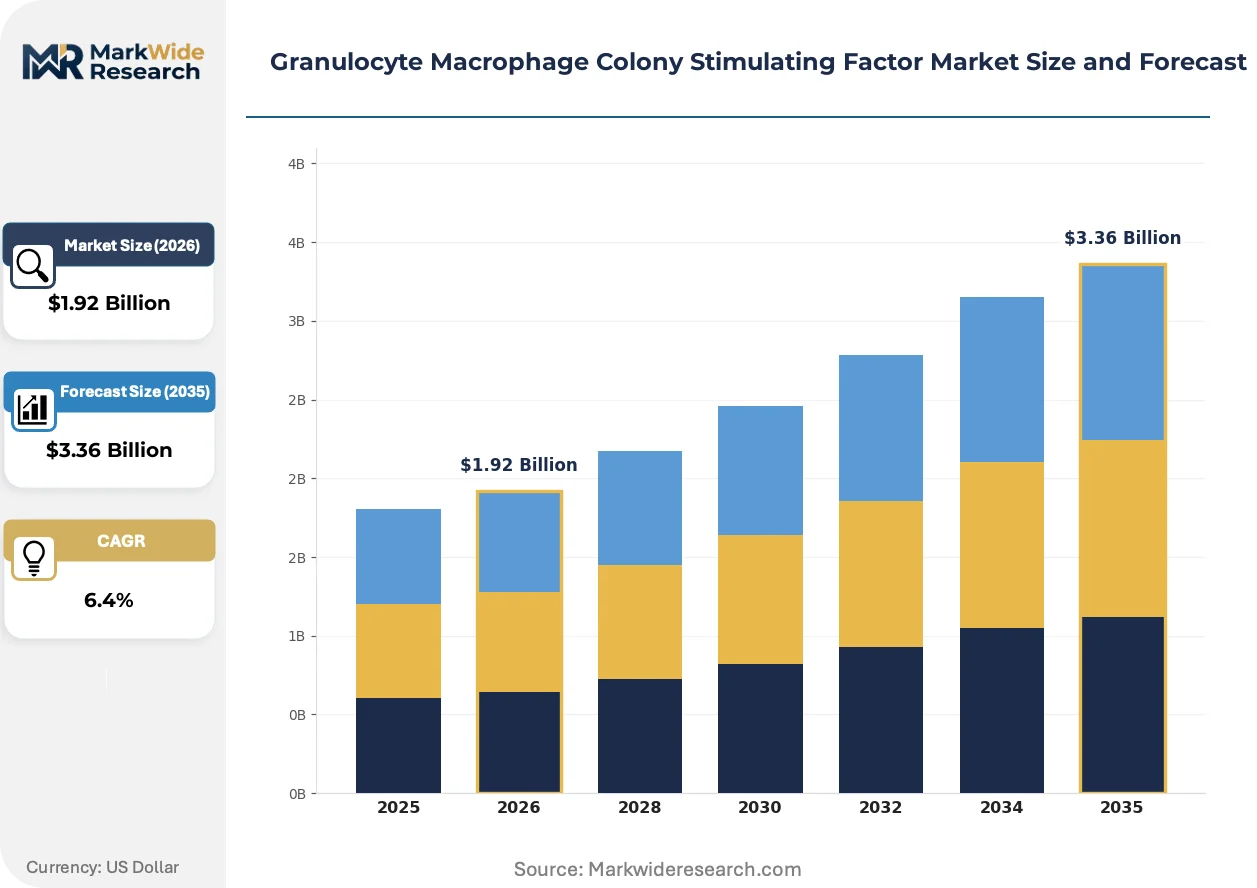
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injections, Recombinant Proteins, Biosimilars, Lyophilized Formulations Application: Immunodeficiency Disorders, Bone Marrow Stimulation, Neutropenia Treatment, Stem Cell Mobilization End User: Hospitals, Cancer Research Institutes, Dialysis Centers, Specialty Clinics Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Autoinjectors |
| Companies Covered | Roche, Merck & Co., Amgen Inc., Pfizer, Eli Lilly and Company, Bristol-Myers Squibb, Sanofi, GlaxoSmithKline, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granulocyte Macrophage Colony Stimulating Factor Market Strategic Shifts & Innovations
A clear shift toward therapies that deliver enhanced patient convenience and greater economic value is defining the market's trajectory. This dual focus on clinical efficacy and cost-effectiveness is influencing product development pipelines and commercialization strategies for both novel biologics and biosimilars.
Long-acting formulations, often developed using pegylation technology, are designed to extend the protein's circulating half-life. Oncology clinics and hospital systems are adopting these therapies to reduce the burden of frequent injections on patients undergoing chemotherapy. The preference for simplified dosing schedules is consolidating demand around these premium, extended-duration products, which challenge the market position of standard daily-dose therapies.
Regulatory frameworks, notably the BPCIA in the United States and parallel guidelines from the EMA, have established abbreviated approval pathways for biosimilar products. These policies significantly reduce the time and cost required for lower-priced alternatives to gain market access. Consequently, the neutropenia treatment segment is most affected as payers and health systems increasingly favor biosimilars to manage oncology-related healthcare expenditures.
Value-based procurement models are becoming more influential in how hospital systems acquire GM-CSF therapies. Rather than focusing solely on per-unit cost, group purchasing organizations are assessing products based on their impact on total cost of care, including factors like reduced hospitalizations for febrile neutropenia. This purchasing behavior is most visible in the United States and parts of Western Europe with integrated delivery networks.
Granulocyte Macrophage Colony Stimulating Factor Market Segmentation
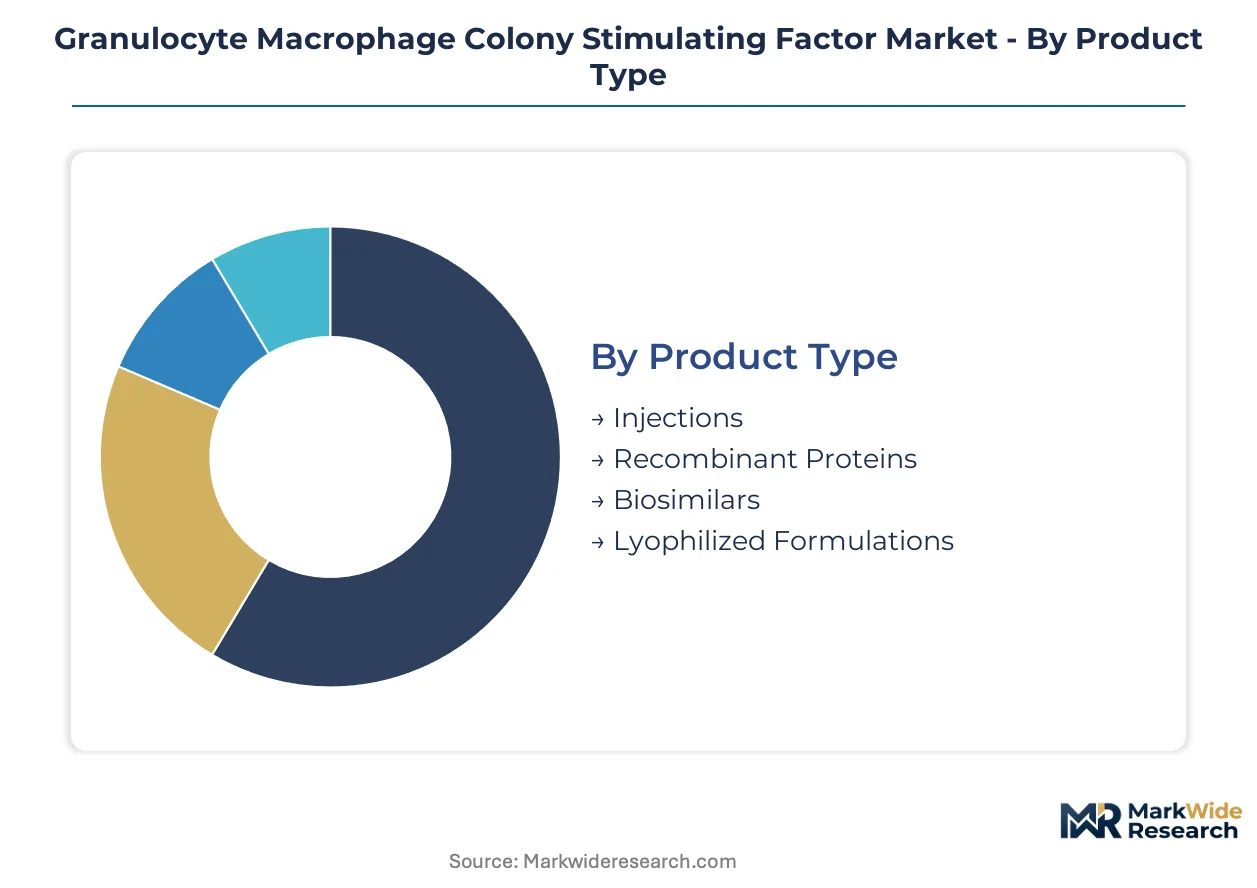
The Granulocyte Macrophage Colony Stimulating Factor market segmentation reveals distinct demand patterns influenced by product characteristics, patient needs, and healthcare infrastructure. Understanding these segments is crucial for manufacturers developing new formulations and for healthcare providers optimizing procurement strategies. This detailed breakdown highlights areas of current market dominance and future growth trajectories.
Product Type:
Product characteristics, including manufacturing process and cost efficiency, significantly differentiate buyer preferences in this category.
- Recombinant Proteins:These products are manufactured using advanced recombinant DNA technology, ensuring high purity and consistent biological activity. Demand for these originator biologics is concentrated in established markets like the United States, driven by their proven clinical efficacy in neutropenia treatment.
- Biosimilars:Biosimilars are highly similar to an approved reference biologic, offering comparable safety and efficacy at a potentially lower cost. Their demand is expanding rapidly in cost-sensitive healthcare systems across Europe, influenced by payer pressure and increasing market access.
- Injections:This traditional format involves administering GM-CSF via syringe, requiring careful handling and patient education.
- Lyophilized Formulations:These freeze-dried powders offer enhanced stability and longer shelf life compared to liquid forms, requiring reconstitution before administration.
Volume sits with Recombinant Proteins; growth tilts toward Biosimilars.
Application:
Application-specific patient needs drive distinct product requirements for GM-CSF therapies, influencing clinical adoption and market penetration.
- Neutropenia Treatment:This segment represents the largest application, focusing on managing low neutrophil counts in cancer patients undergoing myelosuppressive chemotherapy. The U.S. FDA's accelerated approval pathways support continuous innovation in this critical supportive care area.
- Stem Cell Mobilization:GM-CSF is used to increase the number of hematopoietic stem cells in the peripheral blood before collection for transplantation procedures. This application is vital in oncology and hematology, particularly in advanced cancer care infrastructure found in countries like Japan.
- Immunodeficiency Disorders:GM-CSF supports immune function in patients with certain congenital or acquired immunodeficiencies, improving their resistance to infections.
- Bone Marrow Stimulation:This application involves promoting the growth and differentiation of bone marrow cells, often used in conjunction with other therapies for various hematological conditions.
The market's expansion is primarily driven by Neutropenia Treatment, while Stem Cell Mobilization presents an area of significant clinical interest.
End User:
Customer type dictates procurement scale and service level expectations, shaping distribution channels and product support requirements.
- Hospitals:These institutions represent the primary end-users, integrating GM-CSF into comprehensive cancer treatment protocols and managing a high volume of patient cases. Their purchasing decisions are increasingly influenced by value-based procurement models in Western Europe.
- Cancer Research Institutes:These specialized centers drive demand for GM-CSF in clinical trials and advanced research, focusing on novel applications and combination therapies. High research investment in the United States supports their significant role.
- Specialty Clinics:These outpatient facilities administer GM-CSF for specific indications, often focusing on patient convenience and streamlined care delivery.
- Dialysis Centers:GM-CSF is sometimes used in dialysis patients to manage anemia or neutropenia, though this represents a niche application.
Procurement scale is concentrated within Hospitals, with specialized demand emerging from Cancer Research Institutes.
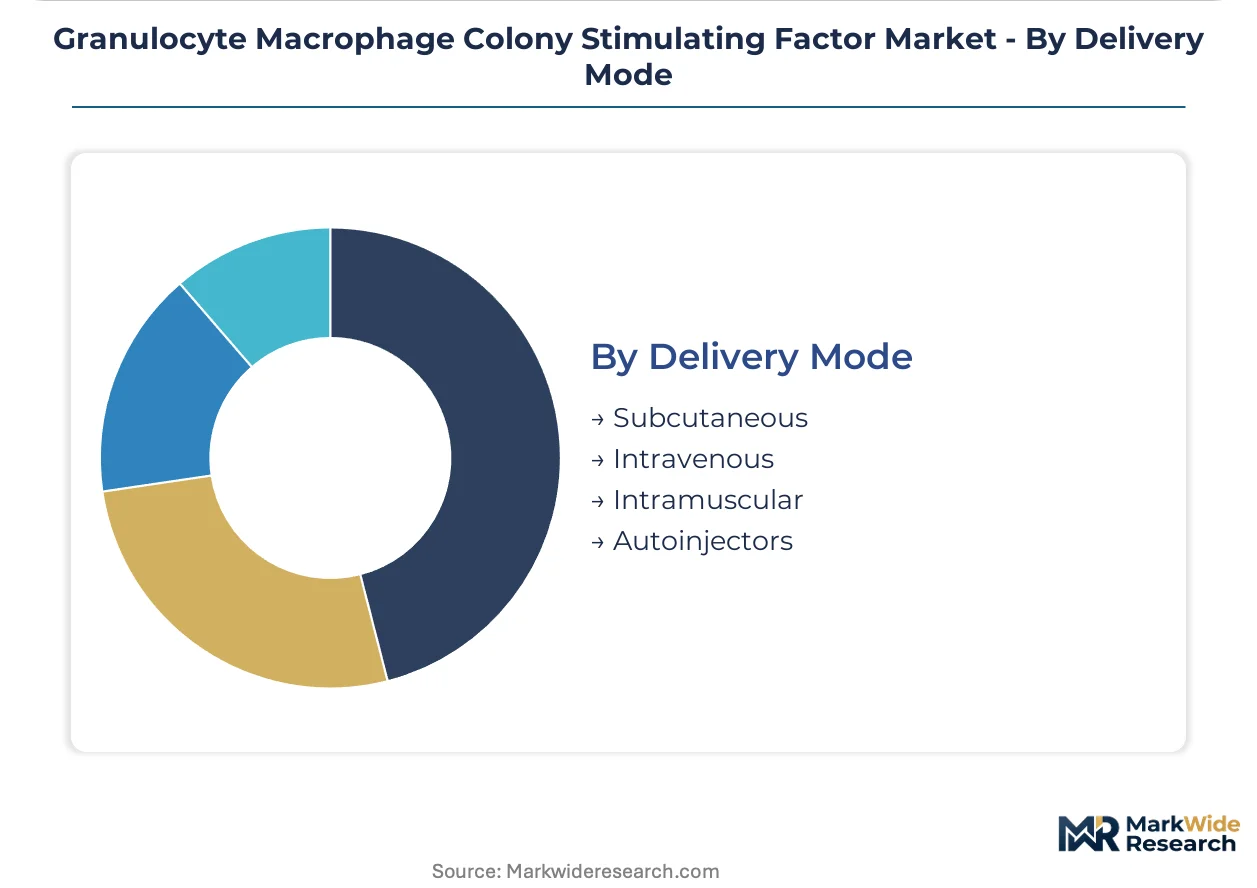
Delivery Mode:
Patient convenience and administration efficiency define preferences across delivery modes, impacting adherence and overall treatment experience.
- Subcutaneous:This delivery method involves injecting GM-CSF under the skin, allowing for easier self-administration by patients or caregivers. Its widespread adoption is driven by convenience for long-term supportive care.
- Autoinjectors:These pre-filled, spring-loaded devices simplify the injection process, enhancing patient compliance and reducing administration errors. Demand for autoinjectors is growing in markets prioritizing patient quality of life.
- Intravenous:Administering GM-CSF directly into a vein requires clinical supervision and is typically used in hospital settings for immediate effect or specific patient conditions.
- Intramuscular:This method involves injecting GM-CSF into a muscle, offering an alternative to subcutaneous delivery but less commonly used for routine administration.
The most common administration pathway remains Subcutaneous, with Autoinjectors gaining traction for patient-centric care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Granulocyte Macrophage Colony Stimulating Factor market exhibits a distinct divide between regions driving innovative production and those primarily focused on consumption and cost-effective access. This global dynamic shapes investment in new formulations and the adoption of biosimilars across diverse healthcare systems. Market access varies significantly based on regulatory frameworks, healthcare expenditure, and local manufacturing capabilities.
United States
Demand for GM-CSF therapies in the United States remains high, driven by advanced cancer treatment protocols and significant research investment. The U.S. FDA's accelerated approval pathways for supportive oncology drugs encourage continuous innovation in the market. Major pharmaceutical clusters in states like California and Massachusetts lead in developing next-generation biologics and biosimilars.
Germany
Germany represents a significant market for GM-CSF, particularly with its strong focus on biosimilar adoption and cost-effective healthcare solutions. The European Medicines Agency (EMA) regulations influence market entry and product commercialization across the country. Pharmaceutical manufacturing hubs in regions such as Bavaria and North Rhine-Westphalia contribute to both novel and biosimilar production.
Japan
Japan's market for GM-CSF is characterized by robust demand for stem cell mobilization applications and stringent quality standards. The Pharmaceuticals and Medical Devices Agency (PMDA) imposes rigorous requirements for drug approval and post-market surveillance. Advanced oncology research and treatment centers in cities like Tokyo and Osaka drive the adoption of high-quality therapies.
India
India presents a growing market for GM-CSF, fueled by an expanding patient base undergoing chemotherapy and increasing healthcare access. The Central Drugs Standard Control Organization (CDSCO) regulates drug approvals, with a growing emphasis on affordable biosimilar options. Pharmaceutical manufacturing clusters in states like Maharashtra and Gujarat are emerging as key production centers for biosimilars.
China
The Chinese market for GM-CSF is expanding rapidly due to rising cancer incidence and government initiatives to improve cancer care infrastructure. The National Medical Products Administration (NMPA) oversees drug approvals, increasingly prioritizing domestic innovation and production. Major biopharmaceutical parks in the Yangtze River Delta region are becoming centers for both research and manufacturing activities.
Granulocyte Macrophage Colony Stimulating Factor Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure. Large pharmaceutical companies leverage extensive research and development capabilities and global distribution networks. Smaller biotech firms often specialize in specific therapeutic areas or novel formulation technologies. Strategic partnerships and portfolio diversification are common competitive moves.
Within the established pharmaceutical sector, Amgen Inc. exemplifies a foundational position in recombinant protein manufacturing. Sanofi, a French multinational, competes through its extensive oncology portfolio and established distribution networks across Europe. Novartis, a Swiss multinational, differentiates with a strategic focus on biosimilar development to capture cost-sensitive market segments.
| Leading Market Players |
|---|
| Roche |
| Merck & Co. |
| Amgen Inc. |
| Pfizer |
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| Sanofi |
| GlaxoSmithKline |
| Novartis |
| Others |
Cost & Logistics Intelligence
Hospital systems, as concentrated buyers, increasingly influence GM-CSF pricing through value-based procurement models that assess total cost of care. This purchasing behavior directly impacts manufacturer strategies, driving a dual focus on clinical efficacy and economic value in product development pipelines.
Pricing Analysis
Cost-down pressure on biosimilars accelerates as payers and health systems prioritize budget management in oncology care. Pricing stratifies across originator biologics, which command a premium for established efficacy and long-acting formulations, and biosimilars, which compete on cost. Price differentiation stems from clinical outcomes, patient convenience features like autoinjectors, and regulatory approval pathways. Payers in Europe and health systems with integrated delivery networks exhibit high price sensitivity, while specialized cancer research institutes prioritize novel formulations regardless of initial cost.
Supply Chain Analysis
Mandated dual-sourcing requirements for critical biologics reduce single-point failure risks within the GM-CSF supply chain. Supply concentration centers in established pharmaceutical manufacturing hubs like the United States and Germany for originator products, with India and China emerging for biosimilar production. Raw material dependencies include specialized cell culture media and recombinant DNA technology components. Cold chain logistics pose a significant structural risk, requiring precise temperature control from manufacturing to patient administration. Distribution runs through a network of pharmaceutical wholesalers and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a consolidation play, as intensifying payer pressure and biosimilar competition force smaller, undifferentiated players to exit or be acquired. Strategic positioning requires a clear focus on either innovation-driven margins or volume-driven access.
For Market Incumbents: Lock in market share by investing heavily in next-generation, long-acting formulations using pegylation technology. This strategy mitigates the threat from biosimilar erosion in the standard-acting segment. Strengthen global distribution networks and secure long-term supply agreements with major hospital groups, leveraging existing relationships to defend against new entrants and maintain a brand premium.
For New Entrants and Emerging Players: Biosimilar development offers a technology-first wedge into the cost-sensitive neutropenia treatment segment, particularly in European markets. Target niche applications such as specific immunodeficiency disorders or use as a vaccine adjuvant, which may have less entrenched competition. A value-based pricing model, demonstrating cost-effectiveness over the total treatment cycle, provides a compelling go-to-market angle for gaining formulary acceptance.
For Investors and Strategic Acquirers: The window for entry favors those seeking to acquire specialized biosimilar manufacturers or companies with proprietary long-acting drug delivery platforms. Long-term viability in GM-CSF hinges on sustained demand in oncology supportive care and the potential for immunomodulatory applications. A signal to watch is the regulatory approval of GM-CSF for novel indications beyond hematology, indicating broader market potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates development of novel GM-CSF formulations for expanded indications. |
| Manufacturing Scale-Up | Reduces production costs for biosimilars, improving market accessibility. |
| Strategic Partnership | Leverages established distribution networks for broader market penetration. |
| Pipeline Diversification | Explores new therapeutic areas, reducing reliance on neutropenia treatment. |
| Regulatory Approval Pathway | Secures market access for new products in key geographies like the United States. |
Research Approach
Independent corroboration across primary interviews, secondary publications, and internal data models underwrites the qualitative findings and quantitative projections within this analysis. This approach ensures a robust and validated understanding of market dynamics and future trajectories.
The rate-of-change decomposition framework projects market volume and value across the analysis window by segmenting demand across product type, application, end user, delivery mode, and regional regulatory cluster. Compound annual growth rates derive from historical trends, current market dynamics, and expert projections. Key forecast inputs include global cancer incidence rates, evolving chemotherapy regimens, and biosimilar uptake patterns in different healthcare systems.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or radical shifts in cancer treatment paradigms. Forecasts reflect assumptions regarding regulatory stability and technological evolution within the biopharmaceutical sector. Deviation in major patent expirations or the introduction of entirely new supportive care therapies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Ciclopirox Olamine Market
Pharmaceuticals
Japan Pharmaceutical 3PL Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market