
 Italy Pharmaceutical Market | 2026-2036
Italy Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Pharmaceutical Market Outlook
Multi-source API procurement is rebalancing toward European qualified suppliers as Italian manufacturers reduce dependency on Asian intermediates. Menarini Group anchors domestic formulation capacity through its Florence headquarters and Pomezia manufacturing campus. Chiesi Farmaceutici specializes in respiratory and rare disease portfolios with integrated R&D in Parma. Recordati leverages its Milan-based operations to control niche cardiovascular and urology segments across Southern Europe.
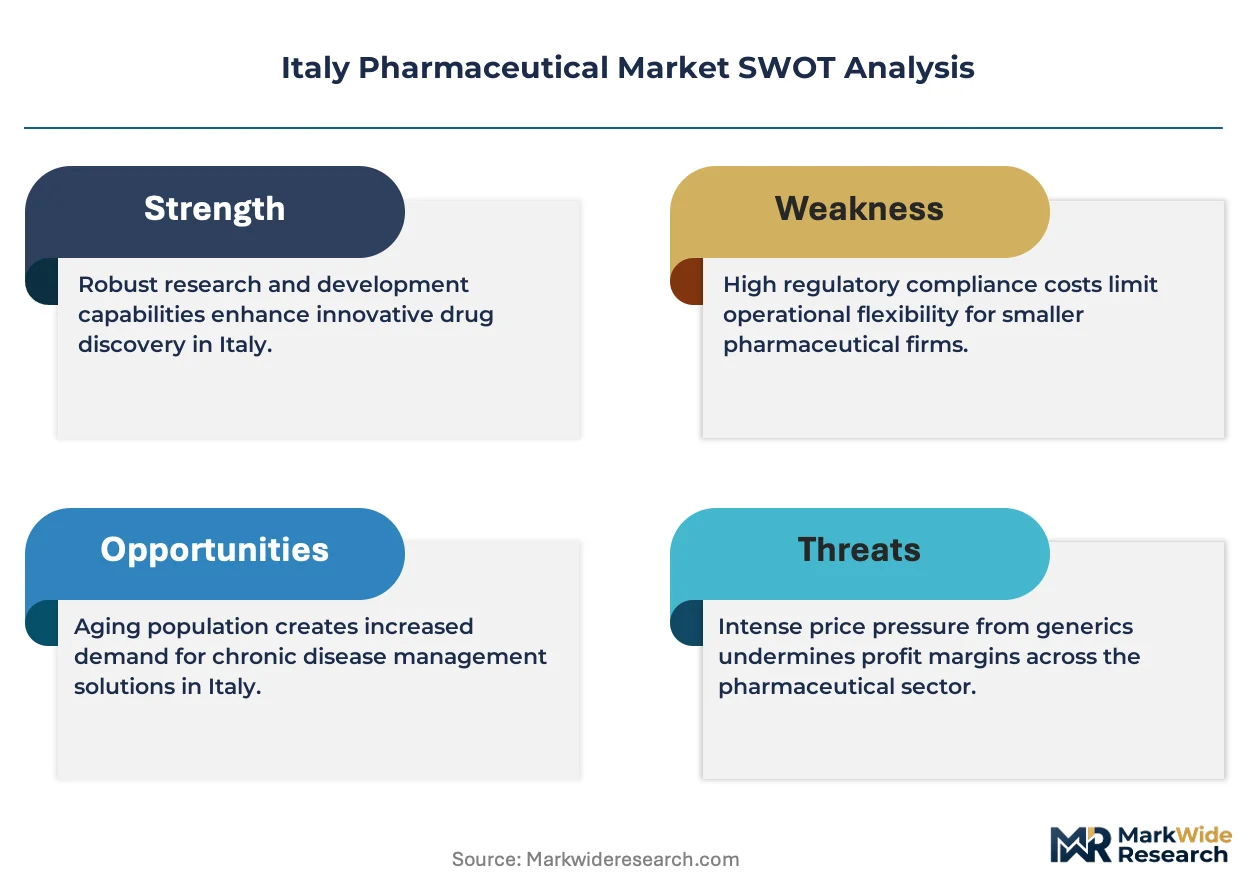
Italy's pharmaceutical sector encompasses the research, development, manufacturing, and distribution of chemically synthesized and biologically derived medicinal products, with active pharmaceutical ingredients typically requiring purity thresholds exceeding 99.5% and stability validation across ICH climatic zones. Prescription drugs occupy the dominant value position due to chronic disease prevalence and specialist-driven prescribing patterns, while biologics represent the fastest-expanding margin pool as hospital-based infusion therapies displace conventional small-molecule protocols. Generics face compressed reimbursement under AIFA reference pricing, though injectables sustain premium positioning through complex manufacturing barriers and cold-chain logistics requirements.
AIFA, the national pharmaceutical regulator, governs market authorization and pricing negotiations, while EMA centralized procedures facilitate parallel access across EU member states for innovative therapies. The EU AI Act and forthcoming clinical trial data transparency mandates will intensify documentation burdens for sponsors seeking Italian reimbursement inclusion. Stakeholders must monitor AIFA's evolving HTA criteria for gene and cell therapies to anticipate hospital budget allocation shifts.
Market Dynamics
AIFA's reimbursement reform is compressing margins for small-molecule generics while redirecting hospital procurement budgets toward high-cost biologics and cell therapies. This pricing pivot is forcing manufacturers to restructure portfolio priorities around infusion-based oncology and rare disease assets.
Growth Catalysts
- EMA Centralized Procedures:Parallel market authorization across EU member states accelerates patient access for gene therapies developed in Lombardy research clusters.
- Hospital-Based Infusion Centers:Specialized oncology units in Milan and Bologna are expanding capacity for monoclonal antibody administration.
- API Reshoring Incentives:Italian manufacturers are qualifying European suppliers to replace Asian intermediate dependencies for critical starting materials.
Market Restraints
- Reference Pricing Compression:AIFA's reimbursement ceilings for off-patent molecules erode manufacturing margins below sustainable thresholds for domestic producers.
- Cold-Chain Infrastructure Gaps:Southern Italy lacks sufficient temperature-controlled distribution capacity for mRNA and cell therapy logistics.
- Clinical Trial Recruitment Bottlenecks:Fragmented patient registries across regional health systems delay pivotal study enrollment timelines.
Strategic Opportunities
- Emilia-Romagna Manufacturing Clusters:Underutilized biologics fill-finish capacity in Parma and Modena offers contract manufacturing expansion potential.
- EU AI Act Compliance Services:Algorithmic validation frameworks for clinical decision support tools create advisory revenue streams for domestic consultancies.
- Gene Therapy Hospital Exemptions:AIFA's early access pathways for unregistered advanced therapies enable premium pricing before formal reimbursement listing.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Italian universities produce insufficient upstream cell culture specialists for expanding biologics manufacturing demand.
- Legacy ERP Integration:Serialization and track-and-trace mandates require costly upgrades to decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Pharmaceutical Market |
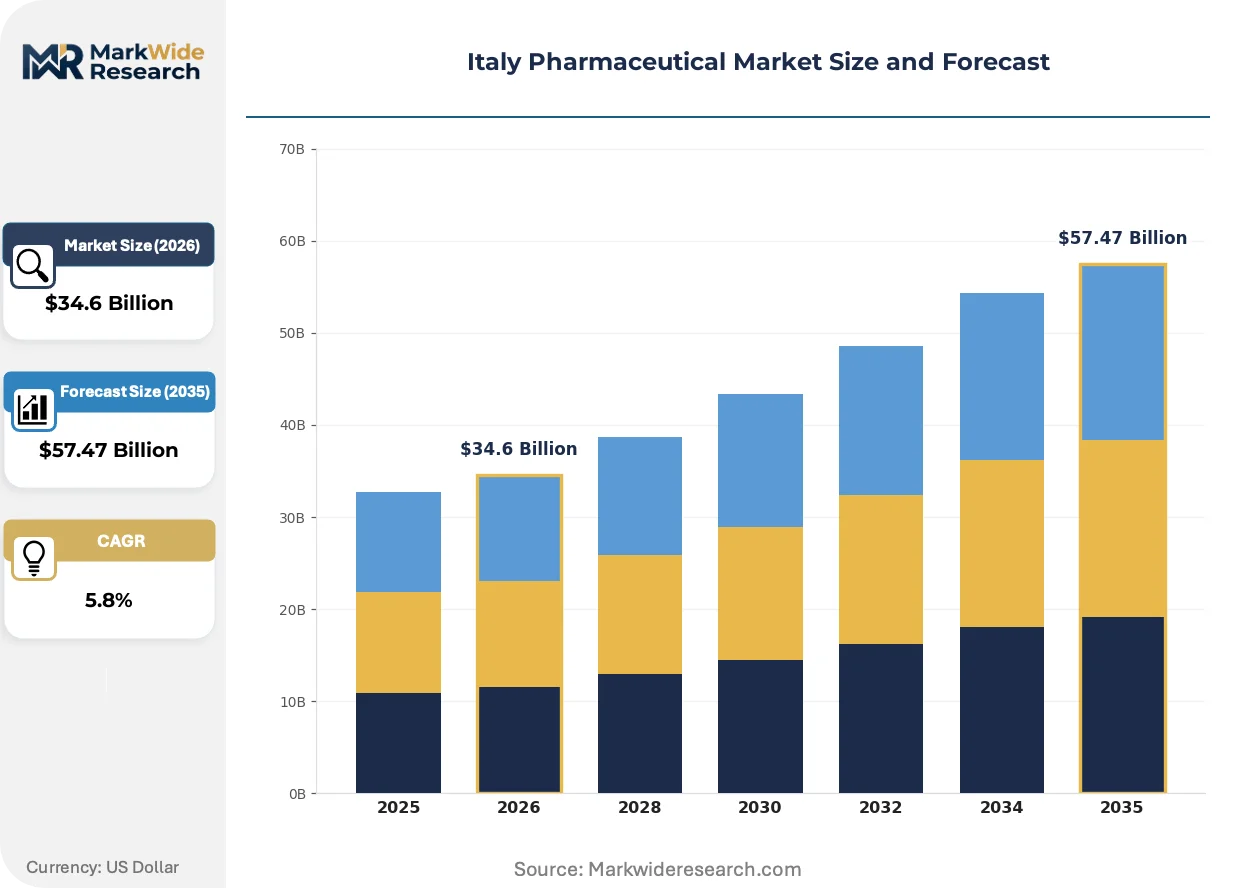
| Market Size in 2026 | $34.6 Billion |
| Market Size in 2035 | $57.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter, Biologics, Generics Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases Delivery Mode: Injectables, Oral Tablets, Topicals, Inhalers End User: Hospitals, Pharmacies, Clinics, Homecare |
| Companies Covered | Menarini Group, Chiesi Farmaceutici, Recordati, Angelini Pharma, Alfasigma, Zambon Group, AstraZeneca, Pfizer, Novartis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Pharmaceutical Market Strategic Shifts
Continuous manufacturing platforms and real-time release testing are compressing production cycles for solid oral doses. Italian facilities are piloting these modalities to maintain cost competitiveness against Eastern European contract manufacturers.
Single-use bioreactor systems are absorbing downstream purification bottlenecks in mammalian cell culture operations. Menarini's Pomezia campus and Chiesi's Parma R&D center are adopting these disposable technologies for Phase III material supply. This shift is absorbing capital that previously supported stainless steel infrastructure, redirecting investment toward modular facility designs.
The EU AI Act's risk classification framework for medical device software is forcing algorithm developers to restructure clinical validation protocols. Sponsors integrating machine learning into diagnostic workflows must now submit conformity assessments under notified body oversight. This regulatory burden is concentrating development resources in Northern Italy's established medical device corridors.
Specialized oncology centers are consolidating purchasing authority through regional procurement consortia. Lombardy's hospital networks now negotiate biologics contracts as unified blocks, displacing individual hospital formulary autonomy. This buyer concentration is visible across the Po Valley, where Emilia-Romagna and Veneto are replicating the model for high-cost infused therapies.
Italy Pharmaceutical Market Segmentation
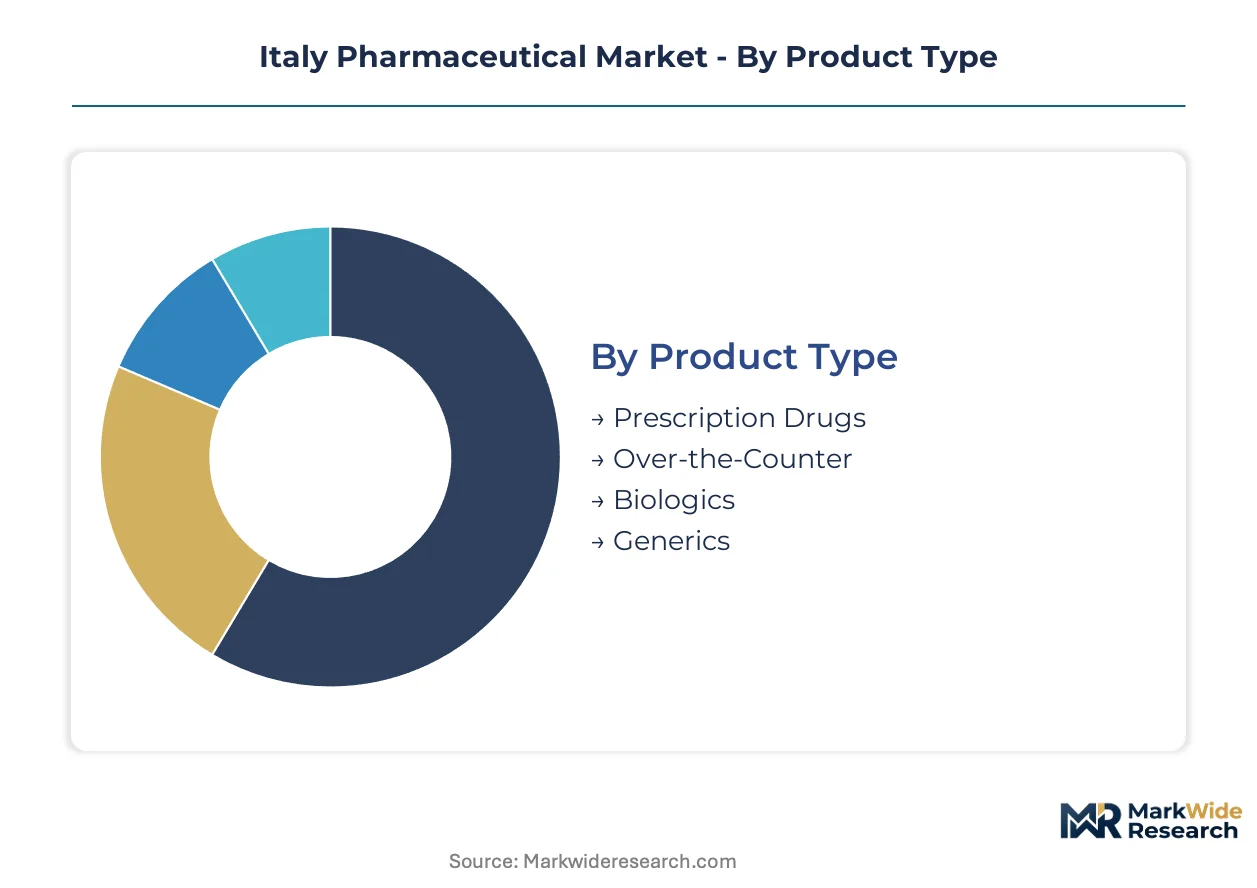
Segmentation reveals how AIFA reimbursement tiers and hospital procurement concentration reshape competitive positioning across Italy's pharmaceutical landscape. Understanding these divisions exposes where margin pools concentrate and where volume shifts threaten incumbent structures.
Product Type:
Supply concentration in biologics manufacturing clusters across Lombardy and Emilia-Romagna determines competitive intensity within each product category.
- Prescription Drugs:Small-molecule formulations requiring AIFA reimbursement authorization dominate hospital formularies and pharmacy dispensing networks. Demand concentrates in Northern Italy's specialized centers for chronic disease management, though reference pricing compression erodes manufacturing margins below sustainable thresholds for domestic producers.
- Biologics:Mammalian cell culture-derived therapeutic proteins and monoclonal antibodies manufactured under GMP Annex 1 standards. Milan and Bologna oncology units are expanding infusion capacity for these high-value therapies, capturing premium positioning before formal AIFA reimbursement listing through hospital exemption pathways.
- Over-the-Counter:Self-medication products distributed through Italy's 20,000+ pharmacy network without prescription requirements.
- Generics:Bioequivalent copies of off-patent molecules facing AIFA reference pricing ceilings that compress margins.
Today's leader: Prescription Drugs. Tomorrow's challenger: Biologics.
Therapy Area:
Cost tier stratification across therapy areas reflects the divergence between mass-market chronic treatments and precision oncology investments.
- Oncology:Cytotoxic agents, targeted small molecules, and immuno-oncology biologics administered in hospital settings. Lombardy's regional procurement consortia now negotiate oncology contracts as unified blocks, displacing individual hospital formulary autonomy and compressing net prices for manufacturers.
- Cardiovascular:Antihypertensives, anticoagulants, and lipid-lowering agents representing the largest volume category by patient count. Demand concentrates in Emilia-Romagna's aging population clusters where specialist-driven prescribing patterns sustain branded preference despite generic availability.
- Neurology:Treatments for epilepsy, Parkinson's disease, and multiple sclerosis requiring long-term patient monitoring.
- Infectious Diseases:Antibiotics and antiviral therapies facing stewardship restrictions in hospital settings.
Volume concentrates in Cardiovascular. Margin expansion concentrates in Oncology.
Delivery Mode:
Application requirements dictate manufacturing complexity and distribution infrastructure investment across delivery modalities.
- Injectables:Parenteral formulations including vials, pre-filled syringes, and lyophilized powders requiring aseptic processing. Complex manufacturing barriers and cold-chain logistics requirements sustain premium positioning even for generic molecules, with Southern Italy's infrastructure gaps creating distribution bottlenecks for temperature-sensitive biologics.
- Oral Tablets:Solid dosage forms manufactured through direct compression or granulation processes. Continuous manufacturing platforms and real-time release testing are compressing production cycles as Italian facilities pilot these modalities to maintain cost competitiveness against Eastern European contract manufacturers.
- Topicals:Dermatological creams, ointments, and transdermal patches for localized treatment.
- Inhalers:Pressurized metered-dose and dry powder devices for respiratory delivery.
Manufacturing sophistication peaks with Injectables. Cost efficiency concentrates in Oral Tablets.
End User:
Customer type determines purchasing authority structure and pricing negotiation leverage across the distribution chain.
- Hospitals:Inpatient and day-hospital settings administering high-cost infused therapies under regional budget allocation. Consolidating purchasing authority through Lombardy, Emilia-Romagna, and Veneto procurement consortia is displacing individual hospital formulary autonomy for biologics.
- Pharmacies:Community dispensaries operating under Italy's public-private contractual framework with regional health services. These 20,000+ outlets handle the majority of outpatient prescription volume and all OTC distribution, with pricing governed by AIFA reimbursement ceilings.
- Clinics:Outpatient specialist centers for diagnostic and therapeutic procedures.
- Homecare:Home infusion and self-administration services for chronic disease patients.
Purchasing power concentrates in Hospitals. Volume scale concentrates in Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's pharmaceutical corridor anchors Italian production capacity, with Milan's specialized oncology centers and Pavia's research clusters absorbing the majority of biologics investment flows across the national market.
Lombardy
Hospital procurement consortia in Milan and Bergamo negotiate biologics contracts as unified purchasing blocks, displacing individual hospital formulary autonomy. AIFA's regional reimbursement allocations favor Lombardy's infusion centers for early-access gene therapies. The Pavia-Turin research axis concentrates mammalian cell culture operations for Phase III material supply.
Emilia-Romagna
Parma and Modena host underutilized biologics fill-finish capacity that contract manufacturers are qualifying for monoclonal antibody production. The region's aging population clusters sustain specialist-driven prescribing patterns for cardiovascular therapies despite generic availability. Bologna's expanding oncology units are absorbing capital investment for hospital-based infusion infrastructure.
Veneto
Padua and Verona are replicating Lombardy's procurement consortium model for high-cost infused therapies across regional hospital networks. AIFA pricing reforms are redirecting hospital budgets toward cell therapies in these northern procurement blocks. The Veneto cluster lacks sufficient bioprocess engineering talent for expanding upstream cell culture demand.
Piedmont
Turin's pharmaceutical heritage supports active pharmaceutical ingredient reshoring initiatives as manufacturers qualify European suppliers to replace Asian intermediates. The region's chemical engineering base feeds continuous manufacturing pilot programs for solid oral dose competitiveness. Novara's specialized logistics providers are bridging cold-chain gaps for temperature-sensitive biologics distribution.
Lazio
Rome's regulatory proximity to AIFA headquarters concentrates market authorization consulting and HTA submission services. The region's hospital networks lag northern procurement consolidation, fragmenting purchasing leverage for biologics. Latina's manufacturing zone attracts serialization and track-and-trace system upgrades for legacy ERP integration mandates.
Italy Pharmaceutical Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cell therapy and gene editing platforms through specialized licensing arrangements. The vendor base stratifies across three tiers: integrated multinationals with EMA centralized procedures, domestic mid-caps with regional hospital relationships, and niche specialists in rare disease modalities. Strategic archetypes include API reshoring qualifiers, biologics fill-finish contractors, and AI-driven clinical validation service providers. Dominant competitive moves center on regional procurement consortium participation and modular facility investments for single-use bioreactor adoption.
Among Italy-based pharmaceutical groups, Menarini Group, Chiesi Farmaceutici, and Recordati exemplify distinct strategic positioning within this tiered structure. Menarini occupies a position representing integrated formulation capacity with headquarters and manufacturing campus concentration in central Italy. Chiesi sits within the rare disease specialist archetype, anchoring respiratory portfolio development through its northern research base. Recordati represents the niche segment control model, leveraging metropolitan operations for cardiovascular and urology positioning across adjacent European markets. These domestic anchors face competitive pressure from multinational EMA centralized procedure beneficiaries including AstraZeneca, Pfizer, and Novartis, which parallel-track market authorization across EU member states.
| Leading Market Players |
|---|
| Menarini Group |
| Chiesi Farmaceutici |
| Recordati |
| Angelini Pharma |
| Alfasigma |
| Zambon Group |
| AstraZeneca |
| Pfizer |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient costs cascade through three distinct pricing tiers as European-sourced intermediates replace Asian supply chains under AIFA's evolving reimbursement framework. Italian manufacturers absorb upstream qualification expenses while hospital procurement consortia in Lombardy and Emilia-Romagna negotiate biologics contracts as unified blocks, compressing net prices for infused therapies.
Pricing Analysis
Input-cost pass-through from reshoring European API suppliers is intensifying margin pressure on generic small-molecule producers. AIFA's reference pricing ceilings for off-patent molecules now separate premium biologics from standard infused therapies and economy-tier oral generics, with price differentiation driven by manufacturing complexity and cold-chain certification requirements. Cost compression in the generics segment runs through hospital procurement consolidation, while oncology biologics sustain pricing power. Community pharmacies exhibit highest price sensitivity due to fixed reimbursement margins, whereas regional hospital consortia prioritize supply security over unit cost for cell therapies.
Supply Chain Analysis
Biologics manufacturing feedstocks rest on German and Swiss specialty chemical producers for cell culture media and downstream purification resins. Critical starting materials draw from Indian API manufacturers and Chinese intermediate suppliers, creating single-source vulnerability for certain monoclonal antibody precursors. Distribution runs through temperature-controlled logistics networks anchored in Milan and Bologna, with Southern Italy's infrastructure gaps forcing reliance on Novara-based cold-chain specialists for mRNA and cell therapy last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy pharmaceutical market compounds steadily as chronic disease prevalence and biologics substitution sustain volume growth across the forecast window. AIFA's reimbursement reforms and hospital procurement consolidation create predictable, if compressed, margin structures for participants who adapt to infusion-centered care models.
For Market Incumbents: To counter reference pricing compression in oral generics, Menarini and Chiesi should accelerate modular facility investments for single-use bioreactor adoption in Pomezia and Parma, capturing biologics fill-finish capacity before Emilia-Romagna contract manufacturers qualify competing sites. Backward integration into European API supply chains reduces tariff exposure from Asian intermediate dependencies.
For New Entrants and Emerging Players: Digital therapeutics platforms offer the most penetrable route for algorithm developers seeking EU AI Act compliance services, as Northern Italy's medical device corridors concentrate clinical validation expertise. Gene therapy hospital exemption pathways enable premium pricing before formal AIFA reimbursement listing, with Bologna and Milan oncology units as initial access points.
For Investors and Strategic Acquirers: Consolidation pressure builds where bioprocess engineering talent scarcity constrains expanding cell culture demand across Veneto and Piedmont manufacturing clusters. Targets with captive mammalian cell culture operations and established regional hospital relationships offer five-to-ten-year viability as infusion therapies displace small-molecule protocols. Watch AIFA's HTA criteria evolution for gene and cell therapies as the inflection signal for hospital budget reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Bioreactor Adoption | Menarini's Pomezia campus redirects capital from stainless steel infrastructure toward modular facility designs. |
| API Reshoring Qualification | Piedmont manufacturers replace Asian intermediate dependencies with European qualified suppliers under AIFA traceability mandates. |
| Regional Procurement Consortium Participation | Lombardy hospital networks negotiate biologics contracts as unified blocks, displacing individual formulary autonomy. |
| EU AI Act Compliance Services | Algorithm developers in Northern Italy medical device corridors restructure clinical validation protocols under notified body oversight. |
| Gene Therapy Hospital Exemption Pathways | AIFA's early access mechanisms enable premium pricing for unregistered advanced therapies before formal reimbursement listing. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against EMA submissions, ClinicalTrials.gov records, AIFA reimbursement databases, and regional health service budget disclosures. Bottom-up patient population modeling and top-down pharmaceutical expenditure tracking were triangulated to ensure convergence.
Segment-weighting approaches applied treatment line stratification, dosage form categories, administration route distinctions, and regional regulatory cluster differences across the projection horizon. CAGRs were derived from volume-demand elasticity modeling and price-trajectory assumptions for each segment, incorporating biologics infusion capacity expansion timelines and AIFA pricing reform implementation pacing as industry-specific forecast inputs.
The model assumes a particular technology adoption path for continuous manufacturing platforms; alternative pathways for real-time release testing or single-use system standardization would alter the outlook. Forecasts reflect assumptions about EMA centralized procedure throughput rates and AIFA HTA evaluation timelines, with regulatory delay risk and bioprocess talent availability as primary revision triggers. A small set of named triggers—AIFA gene therapy reimbursement decisions, Lombardy procurement consortium contract awards, and EU AI Act enforcement precedents—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Global Encephalitis Vaccine Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Telmisartan Market