
 RF Spectrum Analyzer Market | 2026-2036
RF Spectrum Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
RF Spectrum Analyzer Market Outlook
Equipment leasing and subscription-based access models is reconfiguring capital deployment across the competitive landscape, lowering barriers for mid-tier laboratories and regional telecom operators. Keysight Technologies leverages its in-house semiconductor fabrication to sustain margin advantages in high-frequency benchtop systems. Rohde & Schwarz anchors European defense contracts through specialized calibration services and national security clearances. RIGOL Technologies competes aggressively on price-performance ratios in the education and entry-level research segments.
An RF spectrum analyzer measures electromagnetic signal power distribution across frequency ranges, typically spanning kilohertz to hundreds of gigahertz with resolution bandwidth settings that determine measurement precision. The instrument serves critical functions in telecommunications compliance testing, radar signature analysis, and radio frequency interference troubleshooting. Portable analyzers command expanding share as field engineers prioritize battery-operated units with real-time spectrum processing for 5G base station commissioning. Software-defined architectures represent the fastest-expanding technology category, decoupling hardware front-ends from signal processing algorithms and enabling post-purchase capability upgrades. Benchtop systems retain concentrated margin pools in aerospace and satellite ground station applications where phase noise specifications below -110 dBc/Hz remain mandatory.
The FCC governs spectrum allocation and emission limits that directly mandate analyzer deployment for compliance verification across commercial and government installations. ETSI harmonizes European testing methodologies through EN standards that shape product certification requirements for CE marking. The IRA's clean energy manufacturing incentives indirectly stimulate analyzer demand through expanded domestic semiconductor and battery production lines requiring electromagnetic compatibility validation. Stakeholders must monitor evolving 6G research band designations and corresponding test specification drafts to anticipate next-generation instrument capability requirements.
Market Dynamics
Software-defined architectures are compressing hardware replacement cycles across the RF spectrum analyzer market, decoupling signal processing from fixed front-end designs and forcing incumbents to restructure R&D roadmaps around firmware monetization rather than box sales.
Growth Catalysts
- Defense procurement modernization:Field-deployable electronic warfare testing programs in the United States are mandating portable analyzer specifications that prioritize battery operation and real-time processing over laboratory-grade phase noise performance.
- FCC spectrum auction rules:Updated interference detection mandates are compelling commercial telecom operators to maintain analyzer fleets for base station commissioning and coexistence verification across newly allocated bands.
- Semiconductor fab expansion:The IRA's clean energy manufacturing incentives are driving electromagnetic compatibility validation requirements across domestic battery and chip production lines.
Market Restraints
- High-frequency component concentration:Gallium nitride and indium phosphide substrate supply chains concentrate among Japanese and German specialty chemical suppliers, exposing analyzer manufacturers to input volatility.
- Calibration infrastructure scarcity:Accredited metrology laboratories capable of traceable calibration above 50 GHz remain limited to fewer than twelve facilities worldwide, extending service turnaround times.
- Qualified engineer pipeline constraints:University programs producing RF measurement specialists have contracted across North America and Western Europe, constraining end-user operational scaling.
Strategic Opportunities
- 6G research band designation:Pre-standardization activity in sub-terahertz frequencies is creating demand for analyzers with 140 GHz+ capability before commercial specifications finalize.
- Subscription access models:Equipment-as-a-service platforms are penetrating mid-tier laboratories and regional telecom operators previously priced out of capital purchases.
- India PLI scheme:Domestic telecom equipment manufacturing incentives are mandating local test and measurement infrastructure deployment for import substitution compliance.
Industry Challenges
- Legacy system integration friction:Software-defined analyzer deployments require API harmonization with existing test automation frameworks built around GPIB and proprietary SCPI implementations.
- Certification timeline compression:CE marking and FCC equipment authorization cycles for new analyzer models have lengthened due to expanded electromagnetic immunity testing requirements under updated ETSI EN standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Spectrum Analyzer Market |
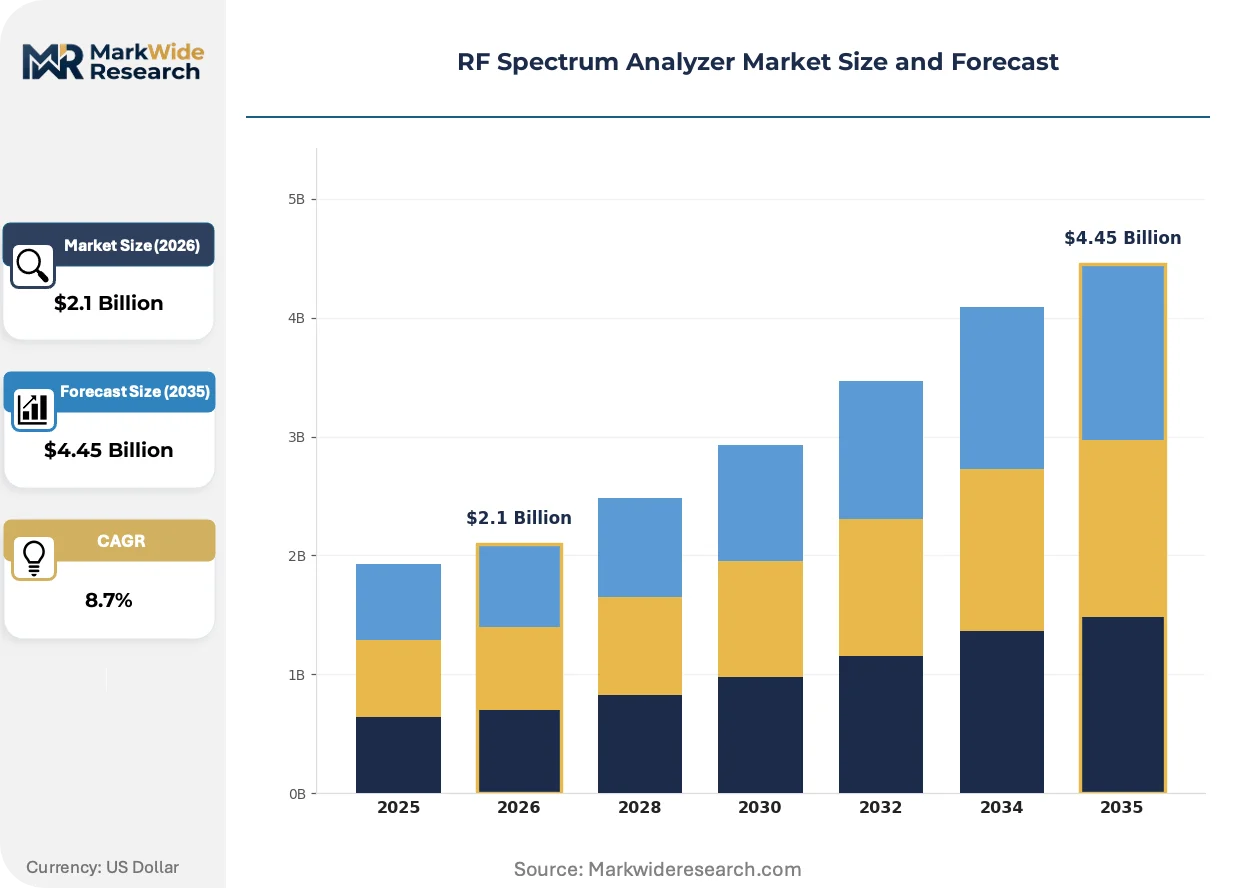
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Benchtop, Handheld, PC-based Technology: Digital, Analog, Hybrid, Software Defined End User: Telecommunications, Aerospace, Defense, Education Application: Signal Analysis, Spectrum Monitoring, Interference Detection, R&D |
| Companies Covered | Tektronix, Fortive Corporation, Keysight Technologies, Yokogawa Electric Corporation, Cobham PLC, Rohde & Schwarz, National Instruments Corporation, RIGOL Technologies, Anritsu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Spectrum Analyzer Market Strategic Shifts
Real-time spectrum processing architectures are redistributing competitive advantage away from raw hardware specifications toward firmware differentiation and post-sale capability expansion.
Software-defined radio platforms with FPGA-based digital downconversion are rendering obsolete traditional swept-tuned analyzer architectures in 5G base station commissioning workflows. Field engineers at tier-one telecom operators are specifying these units for interference hunting and beam alignment verification. The shift is compressing vendor margin structures by extending product lifecycles through firmware licensing rather than hardware refresh cycles.
ETSI's updated EN 303 213 standard for 5G base station electromagnetic compatibility is mandating expanded spurious emission test bandwidths that exceed the native capabilities of analyzers purchased before 2022. Aerospace and satellite ground station operators in Germany and France are accelerating instrument replacement to maintain CE marking eligibility for exported equipment. The regulation is forcing calibration service providers to invest in extended frequency reference chains.
Leasing and pay-per-test arrangements are displacing outright purchase contracts among regional telecom operators and university research groups with intermittent measurement requirements. Channel partners in the United States are bundling analyzer access with training and certification programs to capture recurring revenue streams. The model is most visible in 5G private network deployments where capital constraints intersect with uncertain utilization forecasts.
RF Spectrum Analyzer Market Segmentation
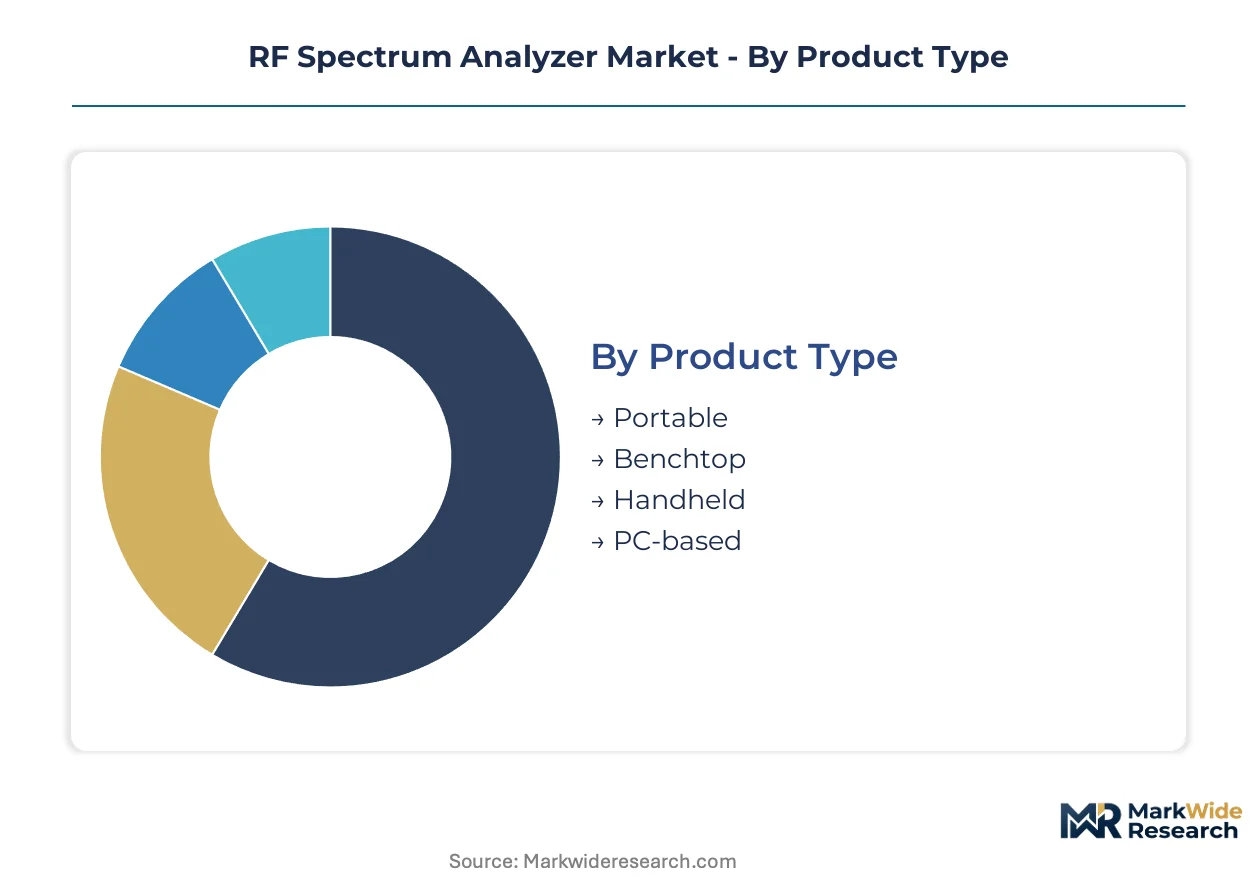
RF spectrum analyzer segmentation reveals divergent equipment lifecycles across form factors and technology architectures. Procurement patterns in telecommunications favor rapid refresh cycles for software-upgradable units, while aerospace programs lock in benchtop systems for decade-long service intervals. Understanding these temporal dynamics shapes vendor portfolio strategy and aftermarket service design.
Product Type:
Portable analyzers turn over fastest as field engineers demand lighter units with extended battery life, while benchtop systems persist through multi-year calibration contracts and embedded test fixtures.
- Portable:Battery-operated units with real-time spectrum processing dominate 5G base station commissioning workflows across United States telecom networks. Field-deployable electronic warfare testing programs in the Department of Defense are mandating specifications that prioritize operational mobility over laboratory-grade phase noise metrics.
- Benchtop:Laboratory-grade systems with phase noise specifications below -110 dBc/Hz anchor aerospace and satellite ground station applications in Germany and France. These units retain concentrated margin pools where electromagnetic compatibility validation requires traceable metrology chains extending above 50 GHz.
- Handheld:Compact units serve intermittent interference hunting requirements among regional network operators with constrained capital budgets.
- PC-based:Software-fronted architectures leverage external computing resources for post-processing-intensive measurement routines in university research settings.
Benchtop systems dominate installed base value. Portable units are where expansion concentrates fastest.
Technology:
Cost tiers separate fixed-function legacy architectures from firmware-extensible platforms, with subscription-capable systems commanding premium positioning.
- Software Defined:FPGA-based digital downconversion architectures decouple hardware front-ends from signal processing algorithms, enabling post-purchase capability upgrades through firmware licensing. Tier-one telecom operators in the United States are specifying these units for 5G beam alignment verification, compressing vendor margin structures by extending product lifecycles beyond traditional hardware refresh cycles.
- Digital:Digitally synthesized local oscillator architectures provide frequency agility for automated test environments across semiconductor fabrication lines receiving IRA clean energy manufacturing incentives.
- Analog:Swept-tuned superheterodyne designs persist in cost-sensitive education markets where measurement bandwidth requirements remain modest.
- Hybrid:Mixed-signal architectures bridge legacy GPIB-controlled test fixtures with modern API-driven automation frameworks.
Analog systems retain legacy installed base. Software-defined architectures are climbing the fastest.
End User:
Volume concentration varies sharply across customer types, with defense procurement programs sustaining low-volume, high-specification production runs.
- Telecommunications:Commercial operators maintain analyzer fleets for FCC-mandated interference detection across newly auctioned spectrum bands, with 5G network densification driving sustained instrument replacement cycles in the United States.
- Defense:Electronic warfare testing programs specify ruggedized portable units with real-time processing capabilities, with procurement concentrated through specialized calibration service providers holding national security clearances.
- Aerospace:Satellite ground station operators in France and Germany accelerate replacement to maintain CE marking eligibility under ETSI's updated EN 303 213 standard for spurious emission testing.
- Education:University programs with intermittent measurement requirements are shifting toward equipment-as-a-service arrangements to circumvent capital constraints.
Telecommunications dominates unit volume. Defense programs anchor premium specification development.
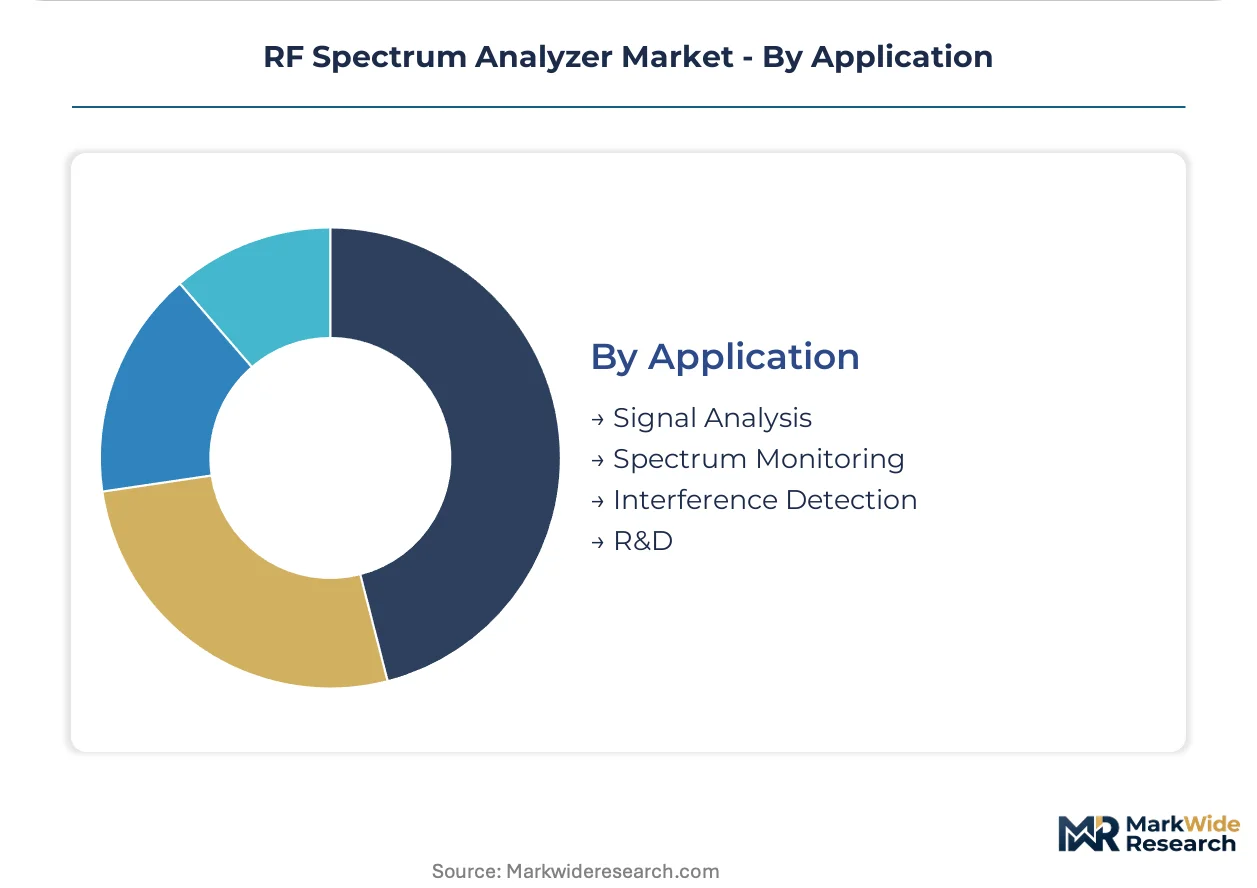
Application:
Customer maturity separates commodity interference detection from specialized R&D applications requiring extended frequency coverage.
- Interference Detection:Real-time spectrum monitoring for coexistence verification commands priority placement in FCC spectrum auction compliance workflows, with field engineers specifying portable units for rapid deployment.
- R&D:Pre-standardization activity in sub-terahertz frequencies for 6G research is creating demand for analyzers with 140 GHz+ capability before commercial specifications finalize, concentrating among national laboratory facilities in the United States and Germany.
- Signal Analysis:Modulation quality measurement supports base station manufacturing test lines in India under PLI scheme domestic production incentives.
- Spectrum Monitoring:Continuous emission surveillance serves broadcast and satellite operators with regulatory filing obligations.
Signal analysis represents the most mature application segment. R&D is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where defense procurement and aerospace certification requirements sustain premium-tier margins, while price-sensitive demand in India and Southeast Asia compresses returns on entry-level portable units.
United States
5G network densification and military modernization programs drive sustained instrument replacement cycles across commercial and defense sectors. The FCC's updated spectrum auction rules mandate analyzer deployment for interference detection compliance verification. Boston and San Diego host concentrated clusters of electronic warfare testing facilities specifying ruggedized portable units.
Germany
Aerospace and satellite ground station operators accelerate benchtop system replacement to maintain CE marking eligibility under ETSI's updated EN 303 213 standard. The country's national standards body enforces traceable metrology chains extending above 50 GHz for electromagnetic compatibility validation. Munich and Stuttgart anchor specialized calibration service providers holding national security clearances.
China
Domestic semiconductor fabrication expansion under MIIT industrial policy stimulates electromagnetic compatibility validation demand across battery and chip production lines. The country's national standards administration mandates GB standard compliance for imported test equipment certification. Shanghai and Shenzhen concentrate software-defined analyzer assembly operations serving regional telecom operators.
India
Domestic telecom equipment manufacturing incentives under the PLI scheme mandate local test and measurement infrastructure deployment for import substitution compliance. TRAI spectrum allocation frameworks require analyzer fleets for base station commissioning across newly licensed bands. Bangalore and Hyderabad host emerging calibration laboratories serving mid-tier regional operators.
Japan
Pre-standardization activity in sub-terahertz frequencies for 6G research creates demand for analyzers with 140 GHz+ capability at national laboratory facilities. METI technology roadmaps shape instrument capability requirements before commercial specifications finalize. Tokyo and Osaka concentrate R&D procurement from tier-one measurement equipment providers.
RF Spectrum Analyzer Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying high-frequency front-ends and precision reference sources. The vendor base organizes around three strategic archetypes: semiconductor-integrated platform builders sustaining margin advantages through in-house fabrication, calibration-anchored service providers capturing recurring revenue through national security clearances, and price-performance competitors penetrating education and entry-level research segments. Dominant competitive moves include firmware monetization strategies decoupling capability upgrades from hardware refresh cycles, and strategic partnerships with accredited metrology laboratories extending service coverage above 50 GHz.
Among US-based platform integrators, Keysight Technologies and Tektronix occupy positions exemplifying semiconductor-integrated and software-defined architecture strategies respectively. Rohde & Schwarz anchors the European defense-contract tier through specialized calibration services. RIGOL Technologies represents the price-performance archetype competing aggressively in education and entry-level research segments. National Instruments Corporation sits within the modular instrumentation category emphasizing API-driven automation frameworks.
| Leading Market Players |
|---|
| Tektronix |
| Fortive Corporation |
| Keysight Technologies |
| Yokogawa Electric Corporation |
| Cobham PLC |
| Rohde & Schwarz |
| National Instruments Corporation |
| RIGOL Technologies |
| Anritsu Corporation |
| Others |
Value Chain & Pricing Dynamics
Gallium nitride and indium phosphide substrate supply chains concentrate among Japanese and German specialty chemical suppliers, anchoring margin pools in benchtop systems with phase noise specifications below -110 dBc/Hz while compressing returns on entry-level portable units.
Pricing Analysis
The customization-premium spread separates configured-to-order benchtop systems from standard portable units, with firmware-extensible software-defined architectures commanding subscription-tier pricing through post-purchase capability upgrades. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and traceable metrology chain length. Cost compression in portable segments is intensifying because field engineers prioritize battery operation over laboratory-grade specifications. Regional telecom operators and university research groups exhibit highest price sensitivity, while aerospace and satellite ground station operators show lowest sensitivity due to CE marking compliance mandates.
Supply Chain Analysis
Upstream feedstock for high-frequency front-ends draws from Japan, Germany, and the United States, with gallium nitride substrates, indium phosphide wafers, and precision reference oscillators forming critical input tiers. Specialty chemical suppliers in Osaka and Munich control substrate manufacturing, while precision machining for waveguide assemblies rests on Swiss and U.S. tooling providers. Single-source vulnerability concentrates in accredited metrology laboratories capable of traceable calibration above 50 GHz, with fewer than twelve facilities worldwide. Distribution runs through authorized channel partners bundling hardware access with training and certification programs to capture recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against software-defined radio platforms with FPGA-based digital downconversion that are displacing traditional swept-tuned analyzer architectures in 5G base station commissioning workflows.
For Market Incumbents: Insulate installed base value through firmware monetization strategies that decouple capability upgrades from hardware refresh cycles, while deepening backward integration into semiconductor fabrication to sustain margin advantages against price-performance competitors. Prioritize calibration service investments extending traceable metrology chains above 50 GHz to defend against emerging entrants lacking accredited infrastructure. For New Entrants and Emerging Players: India and Southeast Asia present geographic underpenetration where domestic telecom equipment manufacturing incentives under the PLI scheme mandate local test and measurement infrastructure deployment. Target mid-tier regional operators with intermittent measurement requirements through equipment-as-a-service arrangements that circumvent capital constraints. Bundle analyzer access with training and certification programs to establish recurring revenue footholds. For Investors and Strategic Acquirers: Capital is best deployed toward calibration-anchored service providers holding national security clearances and specialized metrology capabilities, as these assets generate defensive moats through regulatory compliance requirements. Long-term viability hinges on positioning for 6G pre-standardization activity in sub-terahertz frequencies. Monitor ETSI and FCC band designation drafts as inflection indicators for next-generation instrument capability demand.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Monetization Transition | Decouples capability upgrades from hardware refresh cycles, extending product lifecycles through software licensing revenue streams. |
| Calibration Infrastructure Expansion | Accredited metrology chains above 50 GHz defend against competitors lacking traceable service capabilities for aerospace certification. |
| Subscription Access Model Deployment | Equipment-as-a-service platforms penetrate mid-tier laboratories and regional telecom operators previously priced out of capital purchases. |
| Semiconductor Fabrication Integration | In-house gallium nitride and indium phosphide production sustains margin advantages in high-frequency benchtop system categories. |
| 6G Capability Pre-Positioning | Sub-terahertz frequency coverage above 140 GHz captures national laboratory procurement before commercial specifications finalize. |
Study Parameters
The analysis maps portable, benchtop, handheld, and PC-based form factors, each validated through test engineering directors at tier-one telecom operators, RF measurement specialists at aerospace contractors, procurement leads at defense electronic warfare facilities, and calibration service providers holding national security clearances. Primary interview findings triangulate against FCC equipment authorization databases, ETSI EN standard drafts, SEC 10-K instrument revenue disclosures, and customs records of high-frequency component imports. Bottom-up unit deployment estimates cross-check with top-down addressable market sizing across telecommunications, defense, aerospace, and education verticals.
The assumption-set holds IRA clean energy manufacturing incentives, FCC spectrum auction timelines, and 6G research band designations at announced policy positions while varying defense procurement velocity and semiconductor fab buildout rates. Segmentation dimensions modeled include form factor, technology architecture, end-user industry, and application type across the projection horizon. CAGRs derive from instrument replacement cycle analysis and capability upgrade penetration curves. Forecast inputs incorporate ETSI electromagnetic compatibility standard evolution and India PLI scheme domestic production incentive disbursement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed instrument manufacturers or unexpected 6G standard acceleration would shift outcomes. Cross-checking against national laboratory procurement announcements and defense contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Global Small Cell Power Amplifier Market
RF Components
Digital Radio Frequency Memory Market
RF Components
Analog Phase Shifter Market
RF Components
RF Semiconductor Market
RF Components
US RFID Tags Market
RF Components
Monolithic Microwave Integrated Circuit (MMIC) Market
RF Components
Wi-Fi Module Market
RF Components
RF and Microwave Diodes Market
RF Components
Coaxial Connectors (RF) Market
RF Components
Silicon Tuners Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
Global RF Transceiver Market
RF Components
Small Signal Mosfets Market
RF Components
Millimeter Wave Equipment Market
RF Components
UHF RFID Inlays Market
RF Components
433MHz Active RFID Reader Market