
 RF Mixers Market | 2026-2036
RF Mixers Market Size, Share, and Industry Trends Forecast 2026-2036
RF Mixers Market Analysis
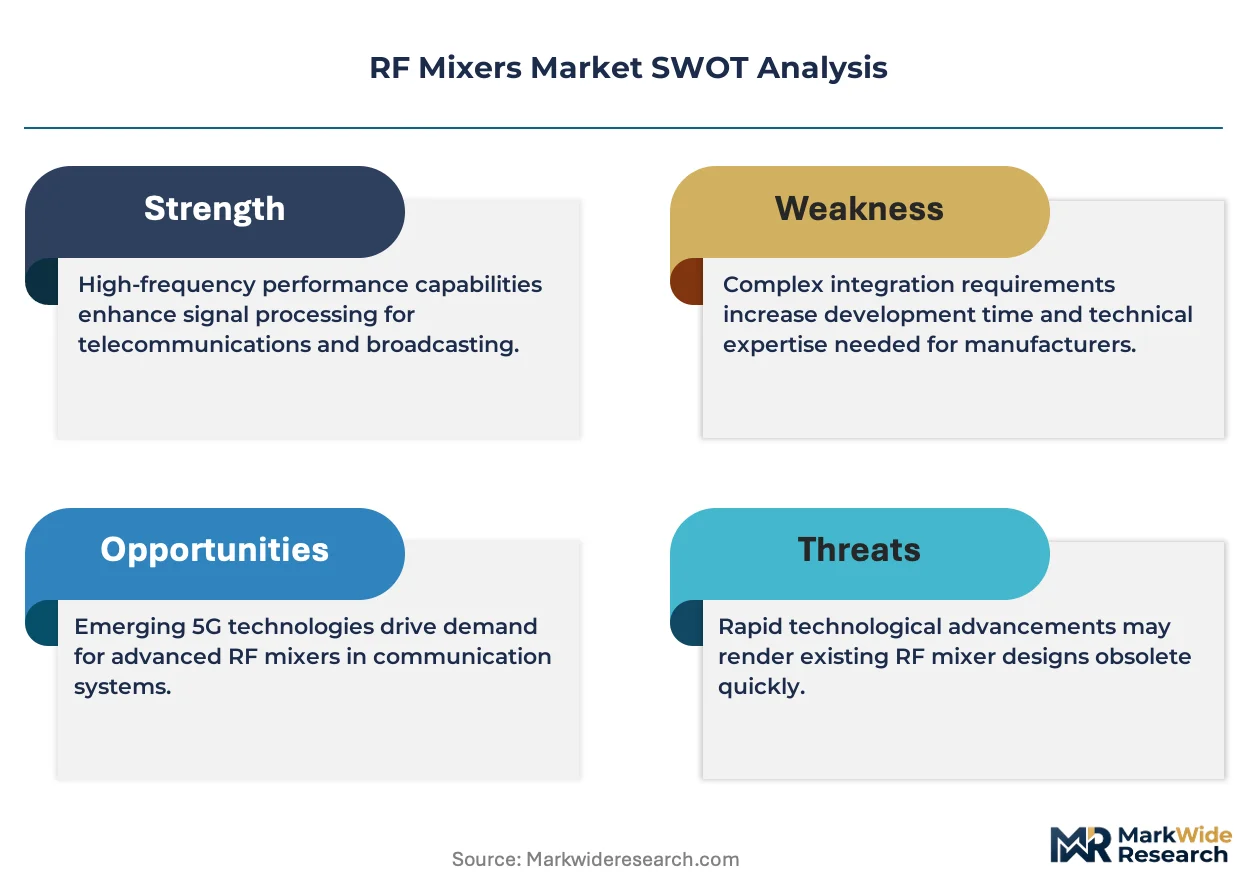
Defense electronics procurement is recalibrating the buyer landscape for RF mixers, with prime contractors demanding higher intercept points and wider instantaneous bandwidth for electronic warfare suites. Analog Devices leverages its integrated transceiver portfolios to anchor military program design-ins, while Qorvo sustains GaAs foundry dominance for high-frequency defense applications. Marki Microwave specializes in broadband diode-based mixers that occupy niche performance tiers above commodity silicon offerings.
An RF mixer is a nonlinear circuit that combines two input signals to produce sum and difference frequencies, typically employing Schottky diodes or FET-based switching cores with LO drive levels between +7 dBm and +23 dBm depending on architecture. Active mixer variants built on SiGe and CMOS processes now dominate cost-sensitive telecommunications infrastructure, while passive double-balanced architectures retain margin concentration in aerospace test equipment and signal intelligence platforms where spurious suppression below 60 dBc remains mandatory.
FCC Part 15 emissions rules in the United States, CE marking under the EU Radio Equipment Directive, and China's MIIT radio transmission type-approval framework collectively shape product certification roadmaps and frequency allocation compliance for mixer manufacturers. The EU AI Act and emerging spectrum harmonization protocols from ETSI are adding algorithmic transparency requirements to cognitive radio subsystems that embed mixer front-ends. Stakeholders must monitor how national spectrum auctions and defense export control lists reshape addressable frequency bands and qualified supplier pools.
Market Dynamics
Defense procurement cycles are compressing design-to-deployment timelines for millimeter-wave mixer modules, forcing foundries to pre-qualify GaN-on-SiC process variants ahead of program awards rather than responding to individual solicitations.
Growth Catalysts
- 5G Infrastructure Mandates:China's MIIT radio transmission type-approval framework is accelerating domestic base station builds, pulling image-reject mixer architectures into volume production.
- Electronic Warfare Modernization:United States defense programs are expanding procurement of high-intercept-point modules for radar and signal intelligence platforms.
- GaN-on-SiC Process Maturation:Foundry investments in Japan and Germany are improving linearity benchmarks for Ka-band and E-band satellite communications terminals.
Market Restraints
- Substrate Supply Concentration:Silicon carbide wafer production clusters in a limited set of merchant foundries, exposing mixer manufacturers to allocation risk during defense procurement surges.
- LO Drive Power Requirements:Passive double-balanced architectures demand +17 dBm to +23 dBm local oscillator inputs, complicating integration with low-power CMOS transceiver chains.
- Spurious Emissions Compliance:FCC Part 15 rules in the United States and CE marking under the EU Radio Equipment Directive impose testing burdens that extend qualification cycles for broadband diode-based designs.
Strategic Opportunities
- LEO Constellation Builds:Satellite operators in China are procuring double-balanced mixers for phased-array user terminals, creating volume demand outside traditional geostationary markets.
- Cognitive Radio Subsystems:The EU AI Act is adding algorithmic transparency requirements that favor mixer front-ends with embedded calibration and self-diagnostic capabilities.
- Test Equipment Refresh:Aerospace instrumentation buyers are replacing legacy coaxial assemblies with surface-mount mixer modules that reduce board area for automated test systems.
Industry Challenges
- Millimeter-Wave Design Talent Scarcity:Electromagnetic simulation expertise for E-band and W-band mixer optimization remains concentrated among a small pool of specialists, constraining product development velocity.
- Multi-Band Certification Complexity:Harmonized spectrum allocations across national regulators require mixer manufacturers to maintain parallel test matrices for type-approval in the United States, European Union, and China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Mixers Market |
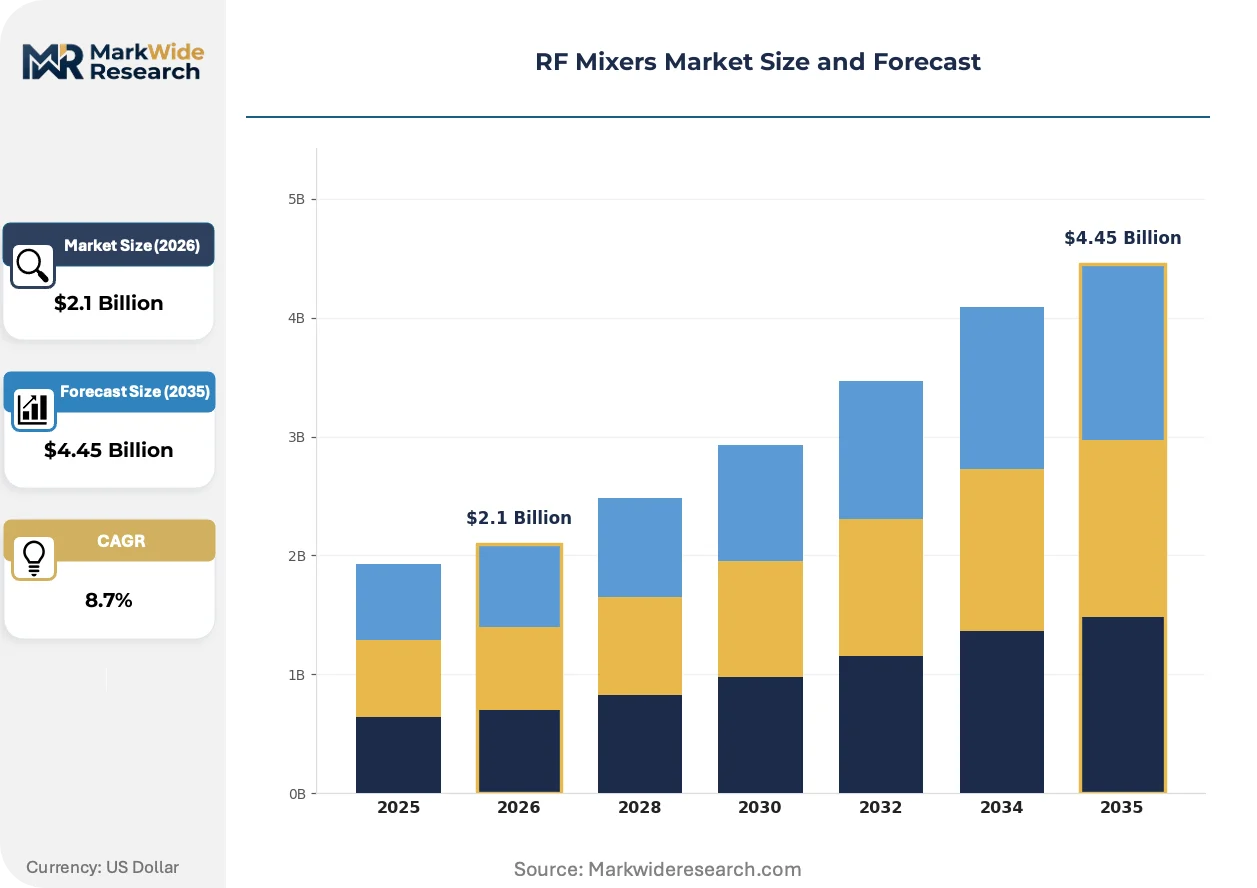
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Mixers, Active Mixers, Image Reject Mixers, Double-Balanced Mixers Technology: GaAs, SiGe, CMOS, Bipolar End User: Telecommunications, Aerospace, Defense, Consumer Electronics Frequency Range: Low Frequency, Medium Frequency, High Frequency, Ultra High Frequency |
| Companies Covered | Analog Devices, Qorvo, Texas Instruments, Skyworks Solutions, Mini-Circuits, NXP Semiconductors, Marki Microwave, Infineon Technologies, MACOM Technology Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Mixers Market Emerging Trajectories
Silicon-germanium BiCMOS processes are collapsing the traditional boundary between discrete mixers and integrated transceivers, enabling system-on-chip architectures that absorb RF conversion functions into larger semiconductor footprints.
Silicon-germanium HBT-based active mixers are unifying gain, linearity, and noise figure specifications within single-die transceivers for sub-6 GHz telecommunications infrastructure. Base station OEMs in China are adopting these integrated architectures to reduce bill-of-materials complexity. This unification is compressing the addressable market for standalone passive mixer modules in cost-sensitive macro cell deployments.
The EU AI Act is imposing algorithmic transparency mandates on cognitive radio subsystems that embed mixer front-ends with automated spectrum sensing. Equipment manufacturers must now document decision pathways for frequency-agile transceivers seeking CE marking. Defense and public safety segments in Germany and France are responding by pre-qualifying mixer-integrated modules with embedded logging capabilities ahead of formal enforcement timelines.
Prime contractors in the United States are consolidating vendor lists for electronic warfare programs, shifting from transactional component procurement toward multi-year strategic supply agreements that lock in foundry capacity. This concentration is displacing spot-market purchasing for high-frequency mixer modules. The pattern is most visible in radar modernization programs where sole-source qualification timelines now exceed eighteen months.
RF Mixers Market Segmentation
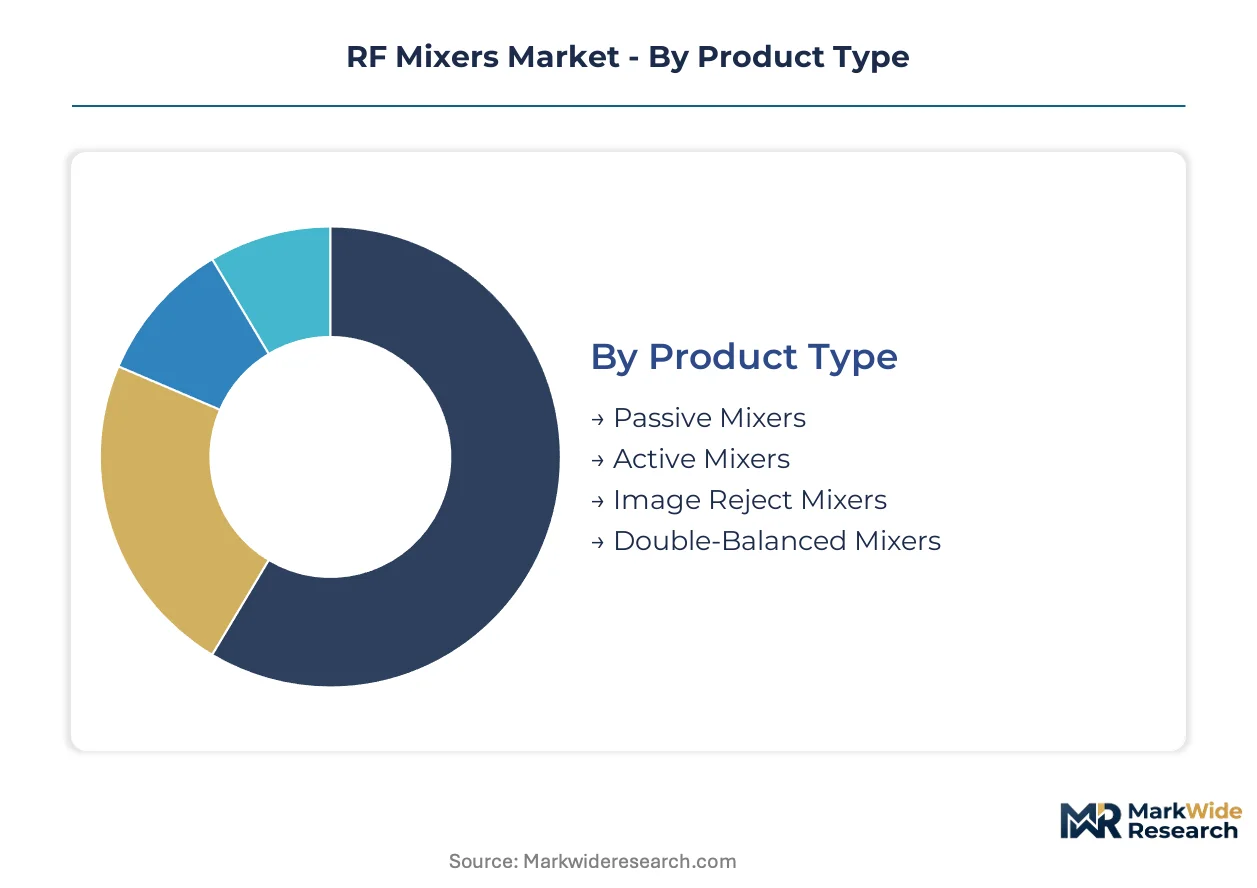
RF mixer procurement decisions hinge on trade-offs between linearity, power consumption, and integration density that vary sharply across application contexts. Segmentation reveals how passive architectures retain margin in defense programs while active variants capture volume in telecommunications infrastructure.
Product Type:
Buyers select mixer architectures based on spurious suppression requirements and local oscillator drive availability rather than unit cost alone.
- Passive Mixers:Schottky diode-based double-balanced topologies deliver intercept points above +20 dBm with no DC power draw. Defense contractors in the United States specify these for electronic warfare front-ends where LO drive levels of +17 dBm to +23 dBm are readily available from dedicated synthesizer chains.
- Active Mixers:SiGe and CMOS implementations integrate gain stages that reduce LO drive requirements to below +10 dBm. Telecommunications OEMs in China favor these for 5G base station transceivers where power budgets and board area constrain passive alternatives.
- Image Reject Mixers:Quadrature architectures suppress unwanted sidebands through phase cancellation, critical for direct-conversion receivers.
- Double-Balanced Mixers:Transformer-coupled diode rings provide port isolation exceeding 40 dB for spectrum analyzer and signal intelligence applications.
Volume sits with active mixers; growth tilts toward image-reject architectures.
Technology:
Process selection determines whether mixer functions remain discrete or collapse into larger transceiver integrations.
- GaAs:High electron mobility transistor processes sustain dominance above 20 GHz where noise figure and linearity specifications are non-negotiable. Japanese foundries supply pHEMT variants for Ka-band satellite terminals.
- SiGe:Heterojunction bipolar technologies bridge performance gaps between III-V compounds and silicon CMOS. German automotive radar suppliers source SiGe mixers for 77 GHz frequency-modulated continuous-wave modules.
- CMOS:Bulk silicon processes enable single-die integration of mixer, synthesizer, and baseband functions at sub-6 GHz frequencies.
- Bipolar:Traditional junction technologies persist in cost-constrained legacy infrastructure where design reuse outweighs performance optimization.
Revenue concentrates in GaAs for millimeter-wave defense; SiGe expands most quickly in automotive and telecommunications.
End User:
Application-specific certification timelines and qualification standards fragment procurement patterns across verticals.
- Telecommunications:Base station OEMs in China drive procurement of integrated transceiver-mixer combinations under MIIT type-approval frameworks. Volume scales with 5G macro cell and small cell deployment schedules.
- Aerospace:Satellite constellation operators demand radiation-tolerant mixer modules for phased-array user terminals. Procurement runs through prime contractors with eighteen-month sole-source qualification timelines.
- Defense:Electronic warfare modernization programs in the United States specify high-intercept-point modules with spurious suppression below 60 dBc.
- Consumer Electronics:Smartphone and Wi-Fi router manufacturers absorb mixer functions into connectivity combo chips, eliminating discrete component demand.
Defense commands premium pricing; telecommunications generates unit volume.
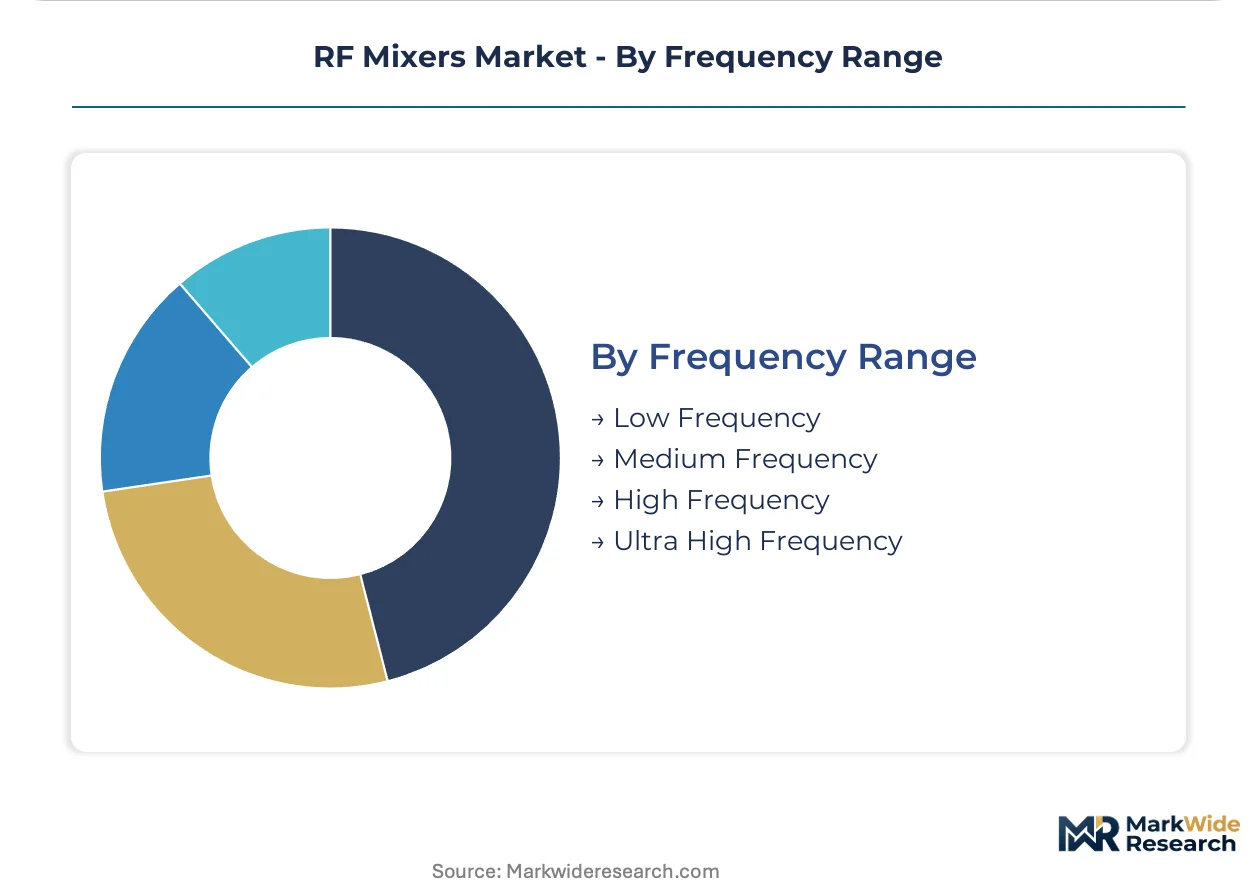
Frequency Range:
Spectrum allocation decisions by national regulators directly shape addressable frequency bands and corresponding technology requirements.
- Low Frequency:Sub-1 GHz operation supports legacy broadcast and narrowband Internet-of-Things applications with minimal semiconductor complexity.
- Medium Frequency:1-6 GHz coverage spans cellular sub-6 GHz, Wi-Fi, and unlicensed industrial-scientific-medical bands. SiGe BiCMOS processes dominate this range.
- High Frequency:6-30 GHz operation encompasses C-band and Ka-band satellite downlinks. GaAs pHEMT and mHEMT technologies retain performance advantages.
- Ultra High Frequency:Millimeter-wave bands above 30 GHz require GaN-on-SiC or advanced GaAs processes for E-band and W-band telecommunications backhaul.
Medium frequency commands current shipment volumes; ultra high frequency exhibits steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT type-approval zones and Japan's semiconductor industrial parks concentrate RF mixer demand through targeted tax incentives and foundry subsidies. These special-economic-zone mechanisms accelerate procurement cycles for telecommunications and defense applications.
United States
Defense procurement programs at the Pentagon drive high-intercept-point mixer specifications for radar modernization and electronic warfare suites. FCC Part 15 emissions rules govern commercial certification timelines for broadband designs. Boston-area electromagnetic simulation specialists and Silicon Valley GaAs foundries anchor millimeter-wave development clusters.
China
Domestic 5G base station deployment and satellite constellation builds accelerate procurement of image-reject architectures. MIIT radio transmission type-approval frameworks compress qualification cycles for domestic OEMs. Shenzhen and Shanghai house integrated transceiver design centers serving telecommunications infrastructure.
Japan
GaN-on-SiC process innovations from merchant foundries improve linearity benchmarks for Ka-band satellite terminals. METI industrial policy supports compound semiconductor manufacturing through targeted R&D subsidies. Kyushu-based fabrication clusters supply pHEMT variants for automotive radar and telecommunications backhaul.
Germany
Automotive radar suppliers source SiGe mixers for 77 GHz frequency-modulated continuous-wave modules under EU automotive safety mandates. CE marking under the EU Radio Equipment Directive shapes product certification roadmaps. Bavarian semiconductor design houses concentrate on integrated transceiver-mixer combinations.
South Korea
5G infrastructure export programs drive volume procurement of active mixer architectures for base station transceivers. National spectrum harmonization protocols align with ETSI emerging standards for cognitive radio subsystems. Seoul Capital Area design centers specialize in CMOS-integrated RF conversion functions.
RF Mixers Market Vendor Landscape
Top-tier vendors anchor defense and aerospace procurement channels, while mid-tier specialists occupy telecommunications and test equipment niches. The market structure concentrates around compound semiconductor foundries with pre-qualified process variants and integrated device manufacturers with captive fabrication. Three archetypes dominate: GaAs/GaN foundry-dependent module suppliers, SiGe BiCMOS integrated transceiver providers, and broadband diode-based discrete specialists. Competitive moves center on multi-year strategic supply agreements locking in foundry capacity and portfolio diversification into millimeter-wave satellite terminals.
Within the defense-tier supplier group, Analog Devices and Qorvo occupy positions as archetypal examples of contrasting strategic approaches. Analog Devices exemplifies the integrated transceiver portfolio anchor, while Qorvo represents GaAs foundry dominance for high-frequency applications. Marki Microwave sits within the broadband diode-based specialist tier, occupying niche performance tiers above commodity silicon offerings.
| Leading Market Players |
|---|
| Analog Devices |
| Qorvo |
| Texas Instruments |
| Skyworks Solutions |
| Mini-Circuits |
| NXP Semiconductors |
| Marki Microwave |
| Infineon Technologies |
| MACOM Technology Solutions |
| Others |
Supply Flow & Price Mechanics
GaN-on-SiC process maturation from Japanese and German foundries is compressing unit economics for millimeter-wave mixer modules while simultaneously concentrating supply among pre-qualified fabrication facilities. This technological transition rewards defense contractors with sole-source agreements but exposes spot-market buyers to allocation premiums during procurement surges.
Pricing Analysis
Lead-time-driven pricing stratification separates defense program participants from commercial telecommunications buyers. Premium pricing attaches to sub-twelve-week delivery schedules for GaAs pHEMT variants, while spot inventory of commodity SiGe active mixers trades at discounts. Price differentiation rests on certification grade—CE-marked and FCC Part 15-compliant modules command 15-25% premiums over unqualified equivalents. Pricing pressure stems from Chinese base station OEMs demanding cost-downs on integrated transceiver-mixer combinations. Consumer electronics manufacturers exhibit highest price sensitivity; defense prime contractors demonstrate lowest.
Supply Chain Analysis
Freight cost volatility for silicon carbide substrates from Japan and gallium arsenide wafers from Taiwan amplifies landed cost uncertainty for mixer manufacturers. Raw material dependencies center on SiC boules, GaAs epiwafers, and gold wirebond materials. Single-source vulnerability concentrates in merchant GaN-on-SiC foundries serving Ka-band satellite terminal producers. Distribution runs through authorized distributors for defense-qualified parts and direct OEM relationships for telecommunications volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where sole-source qualification timelines exceeding eighteen months force subscale competitors into exit or acquisition. Defense procurement concentration and foundry pre-qualification requirements systematically eliminate undercapitalized module suppliers.
For Market Incumbents: Deepen backward integration into GaAs and GaN-on-SiC foundry capacity through multi-year strategic supply agreements that lock in wafer allocation ahead of program awards. Fortify certification portfolios—FCC Part 15, CE marking under the EU Radio Equipment Directive, and China's MIIT type-approval—to defend against emerging SiGe BiCMOS integrated transceiver providers collapsing discrete mixer demand. For New Entrants and Emerging Players: Satellite constellation operators building phased-array user terminals represent the most penetrable buyer archetype outside established defense and telecommunications channels. Target test equipment refresh cycles in aerospace instrumentation where surface-mount mixer modules reduce board area. Pursue fabless design-house positioning with foundry partnerships rather than captive fabrication to bypass capital barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in defense-tier acquisitions by prime contractors seeking vertical integration into RF front-end supply. Long-term viability favors compound semiconductor foundries with pre-qualified process variants and integrated device manufacturers with captive fabrication. Monitor sole-source qualification timeline compression as the inflection signal—acceleration indicates procurement consolidation maturity, extension suggests vendor diversification opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Foundry Capacity Agreement | Locks in GaN-on-SiC wafer supply for Pentagon radar modernization programs ahead of competitor allocation. |
| MIIT Type-Approval Acceleration | Compresses qualification cycles for Chinese 5G base station OEMs against slower-responding foreign rivals. |
| Integrated Transceiver-Mixer Combination | Absorbs RF conversion functions into SiGe BiCMOS single-die architectures for telecommunications infrastructure. |
| Surface-Mount Packaging Transition | Reduces board area for aerospace automated test equipment buyers replacing legacy coaxial assemblies. |
| Embedded Diagnostic Capability Integration | Addresses EU AI Act algorithmic transparency mandates for cognitive radio subsystems seeking CE marking. |
Methodological Framework
SEC filings, customs and trade data, and compound semiconductor foundry capacity disclosures formed the secondary backbone of this analysis. Primary interviews with defense procurement officers at prime contractors, telecommunications base station OEM procurement leads, GaAs foundry operations directors, and electromagnetic simulation specialists validated demand assumptions. Bottom-up and top-down triangulation reconciled module shipment data with end-equipment production forecasts.
Bottom-up modeling aggregated segment-level volume across passive, active, image-reject, and double-balanced mixer architectures, with technology splits for GaAs, SiGe, CMOS, and GaN-on-SiC processes. Top-down validation cross-checked against defense budget appropriations, 5G base station deployment schedules, and satellite constellation launch manifests. CAGRs derived from regression analysis of historical procurement cycles and projected program awards. Frequency range segmentation—sub-1 GHz, 1-6 GHz, 6-30 GHz, and above 30 GHz—captured spectrum allocation impacts on technology selection.
Revisions become necessary when defense export control list modifications, national spectrum auction outcomes, or foundry process qualification failures materialize. Forecasts reflect assumptions about procurement cycle continuity and foundry yield maturation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Wi-Fi Module Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
Phase Shifters Market
RF Components
Tunable Inductors Market
RF Components
Multiband Booster Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
Global RF Transceiver Market
RF Components
China Small Signal Transistor Market
RF Components
RF Microwave MLCC Market
RF Components
433MHz Active RFID Reader Market
RF Components
Toroid Inductor Market
RF Components
Radio Frequency Front End Module Market
RF Components
RFID Tags Market
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
FBAR Devices Market
RF Components
RF Power Detector Market