
 Small Office Home Office (SOHO) Servers Market | 2026-2036
Small Office Home Office (SOHO) Servers Market Size, Share, and Industry Trends Forecast 2026-2036
Small Office Home Office (SOHO) Servers Market Analytics
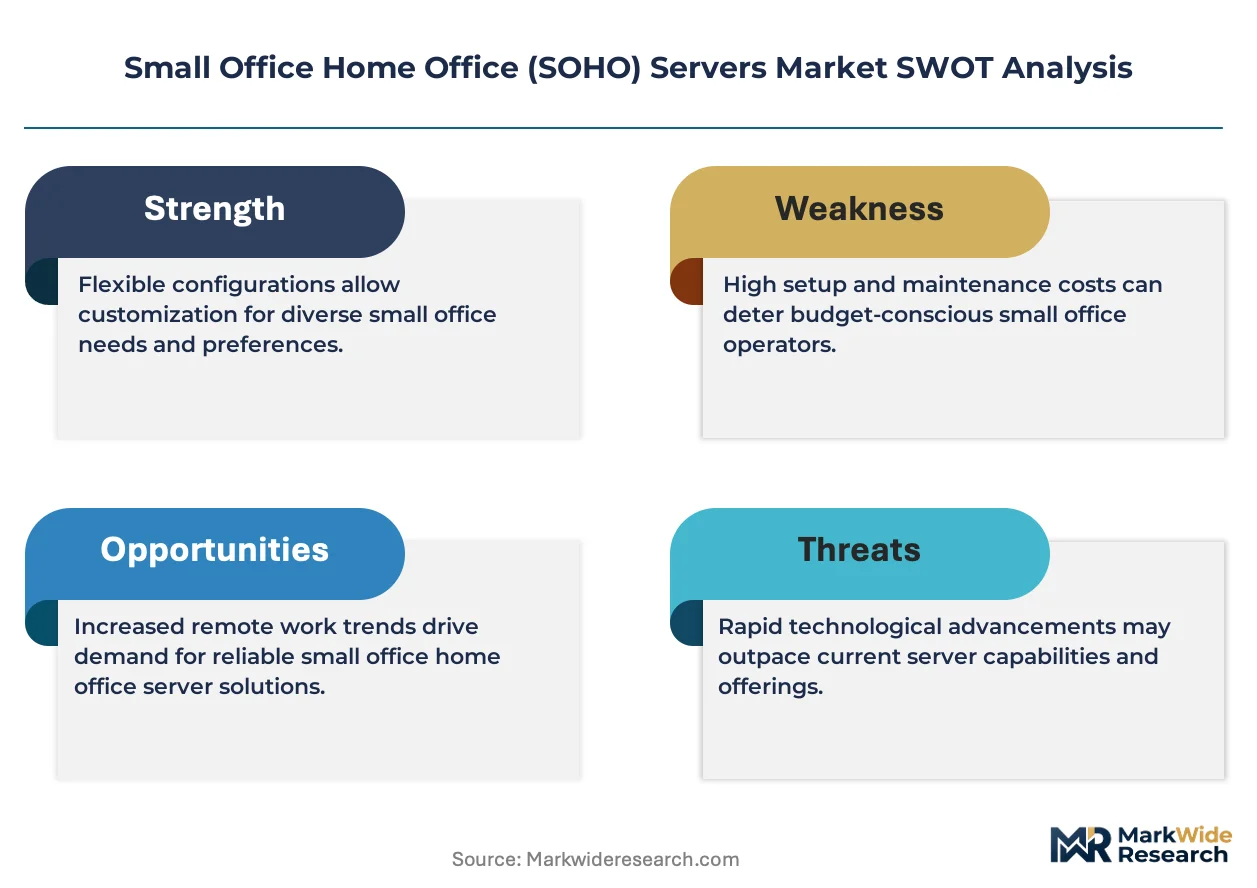
The EU Green Deal is consolidating demand for low-power server hardware across European home offices and micro-enterprises. Synology Inc leverages its proprietary DiskStation Manager ecosystem to dominate software-defined storage at the edge. QNAP Systems Inc competes through broad application containerization, while NETGEAR Inc anchors its position via Orbi-integrated mesh networking with built-in server nodes.
Small Office Home Office servers are compact computing appliances designed for localized data storage, file sharing, and application hosting, typically operating on x86 or ARM architectures with thermal envelopes under 65W to suit residential and micro-business environments without dedicated climate control. Tower servers occupy the largest volume tier due to their acoustic isolation and expandability, while micro servers represent the fastest-growing structural category as ARM-based silicon from Qualcomm and Ampere displaces legacy x86 footprints in space-constrained installations. Cloud-based and hybrid deployment models are capturing margin pools by recurring subscription revenue rather than transactional hardware sales.
The EPA ENERGY STAR program and EU Ecodesign requirements shape minimum efficiency thresholds for SOHO server power supplies, while the FCC in the United States governs electromagnetic emissions for integrated wireless connectivity modules. Japan's METI has introduced top-runner standards that progressively tighten idle-state consumption limits for network-attached equipment. Stakeholders must decide whether to prioritize ARM-native software ecosystems or maintain backward compatibility with x86 virtualization stacks as the installed base bifurcates across instruction-set architectures.
Market Dynamics
ARM-based silicon from Qualcomm and Ampere is converging with software-defined storage architectures, forcing incumbent x86 vendors to reconfigure thermal envelopes and idle-state power budgets for residential deployments without dedicated cooling infrastructure.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants pushes manufacturers toward passive cooling and liquid thermal designs that align with residential acoustic constraints.
- Distributed professional services:Architecture, legal, and accounting partnerships operating from satellite locations drive localized file-collaboration infrastructure with sub-65W power signatures.
- Containerized application hosting:Docker and Kubernetes runtime support at the edge enables micro-enterprises to deploy CRM and ERP instances without cloud egress fees.
Market Restraints
- DDR5 and NAND flash volatility:Memory component pricing swings compress hardware margin pools for system integrators assembling tower and rack configurations.
- Taiwan semiconductor concentration:Advanced node fabrication for ARM SoCs remains concentrated with TSMC, exposing supply continuity risk for volume server deployments.
- x86 software legacy:Virtualization stacks and proprietary business applications compiled for Intel instruction sets create migration friction for ARM-native alternatives.
Strategic Opportunities
- India micro-enterprise digitization:The country's PLI scheme for electronics manufacturing incentivizes local assembly of compact servers for the 63 million MSME segment.
- Subscription-based hybrid orchestration:Recurring revenue models for edge-to-cloud synchronization software capture lifetime value beyond transactional hardware sales.
- EU Ecodesign tier escalation:Tightening standby power limits create first-mover advantage for vendors with sub-2W idle-state engineering.
Industry Challenges
- Embedded systems firmware security:Supply chain attestation for UEFI and BMC code bases demands specialized validation capabilities most regional assemblers lack.
- Acoustic engineering for residential deployment:Thermal management without fan noise requires computational fluid dynamics talent scarce outside major OEM engineering centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Office Home Office (SOHO) Servers Market |
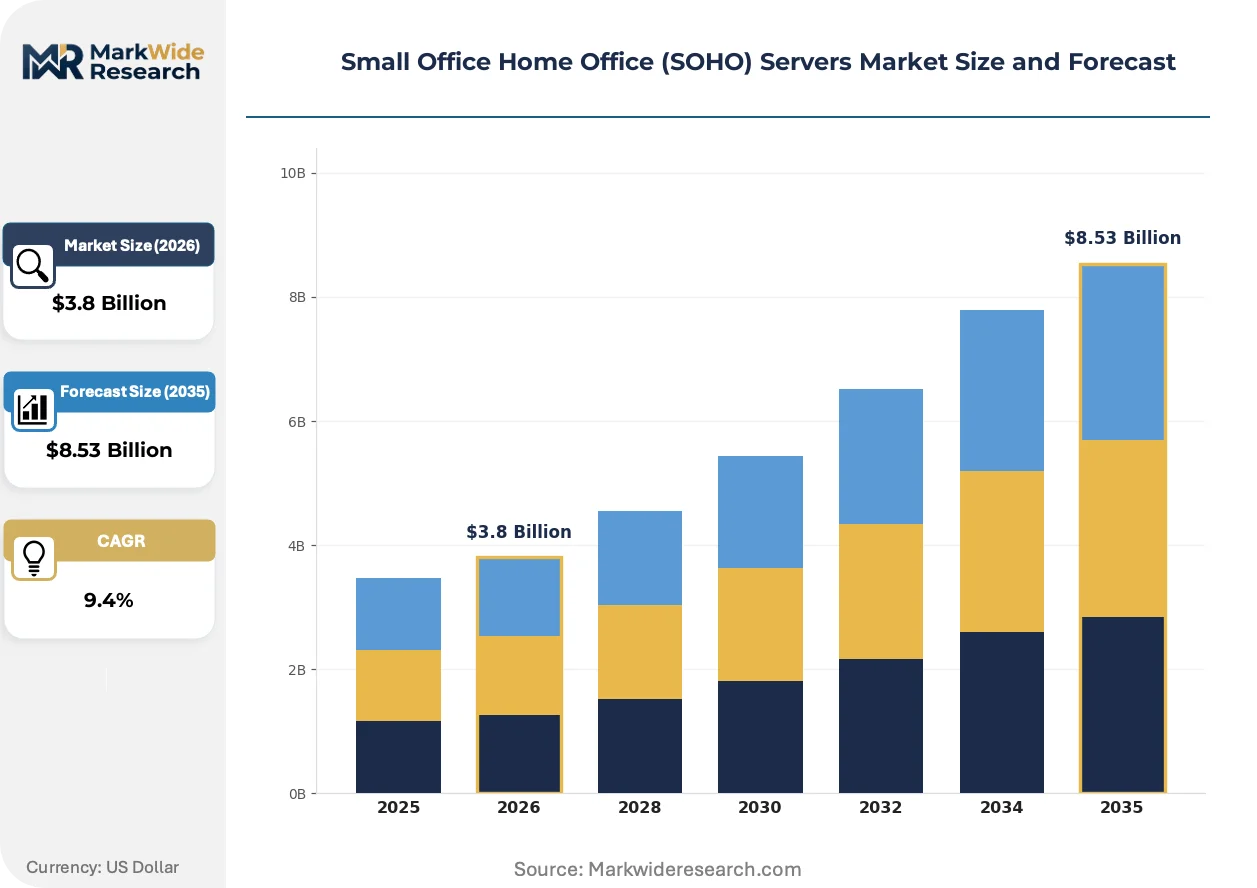
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tower Servers, Rack Servers, Blade Servers, Micro Servers Installation: On-Premises, Cloud-Based, Hybrid, Removable Storage Connectivity: Ethernet, Wi-Fi, Bluetooth, USB, VPN End User: Freelancers, Small Businesses, Home Offices, Remote Workers |
| Companies Covered | Synology Inc, QNAP Systems Inc, NETGEAR Inc, Western Digital Corporation, ASUSTOR Inc, Dell Technologies, Hewlett Packard Enterprise, Lenovo, Apple Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Office Home Office (SOHO) Servers Market Evolving Landscape
Software-defined functionality is migrating from cloud data centers to edge appliances, compressing the traditional distinction between network-attached storage and general-purpose compute nodes.
Computational storage drives integrating ARM processing cores directly into NAND controllers are converging with NVMe-over-Fabrics protocols. Freelance video editors and small production houses adopt these configurations to transcode 4K footage without workstation-class power draw. This convergence is collapsing the separate procurement cycles for storage expansion and compute upgrades.
The EU F-Gas Regulation and companion Ecodesign requirements are mandating fanless or liquid-cooled thermal architectures for equipment below 500W total consumption. Manufacturers serving European home offices redesign chassis around heat-pipe arrays and vapor-chamber spreads. The tower server segment absorbs the highest compliance engineering cost as acoustic isolation competes with thermal performance.
Enterprise buyers now disaggregate hardware acquisition from software licensing, preferring bring-your-own-license models for virtualization and security stacks. Value-added resellers in the United States and Germany unbundle installation and tier-1 support from hardware margins. This pattern concentrates in professional services verticals where IT procurement authority sits with practice partners rather than centralized technology functions.
Small Office Home Office (SOHO) Servers Market Segmentation
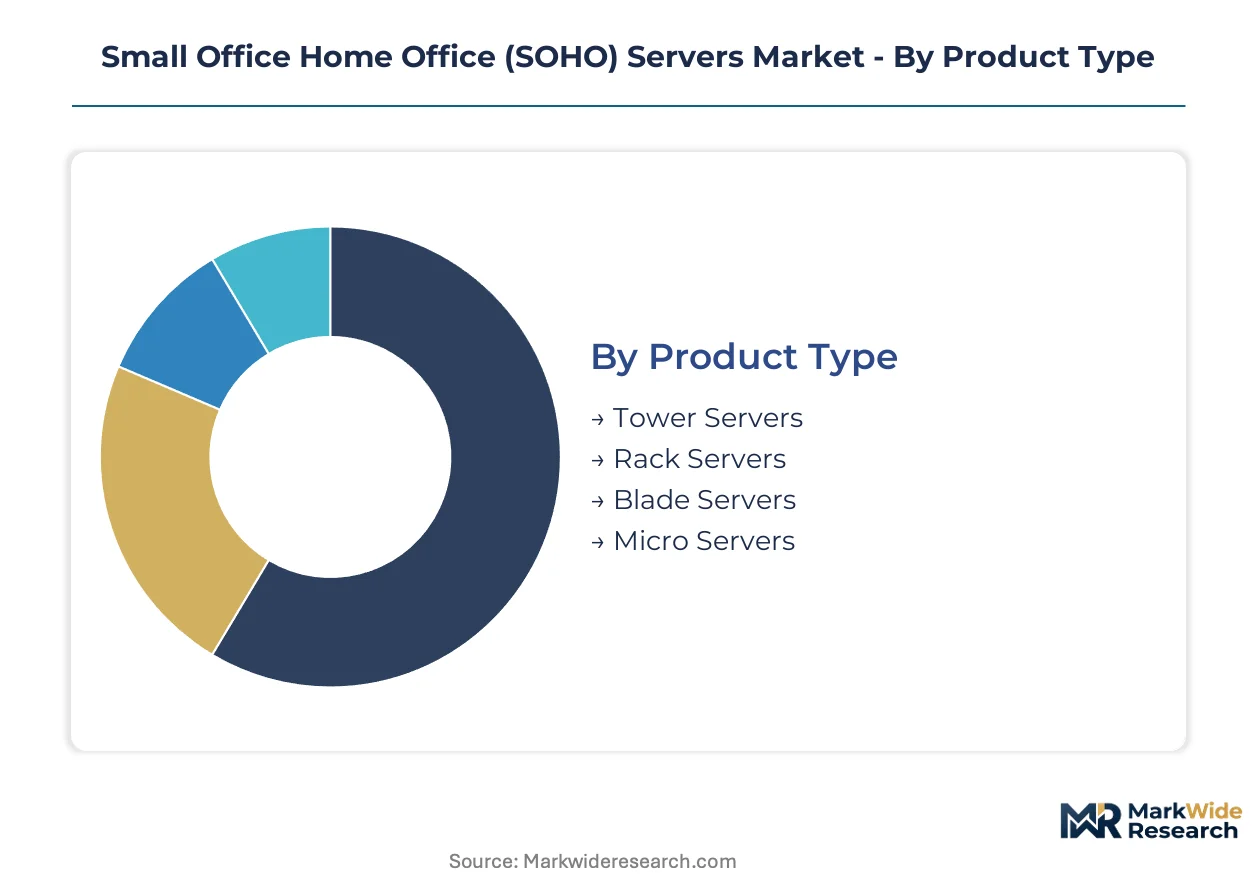
SOHO server procurement patterns diverge sharply between standalone appliance buyers and embedded-system integrators. Segmentation reveals how thermal constraints, deployment flexibility, and connectivity requirements reshape vendor product roadmaps across residential and micro-enterprise environments.
Product Type:
Tower configurations function as discrete appliances for standalone file serving, while rack and blade formats embed into consolidated infrastructure stacks.
- Tower Servers:Vertical chassis designs isolate acoustic signatures through padded enclosures and large-diameter low-RPM fans. Architecture partnerships in Germany and legal practices across the United States specify these units for satellite offices lacking dedicated server rooms.
- Micro Servers:ARM-based silicon from Ampere and Qualcomm enables sub-35W thermal envelopes that operate without forced-air cooling. Freelance video editors in Los Angeles and London post-production collectives deploy these for localized 4K transcoding without workstation-grade power draw.
- Rack Servers:Standardized 19-inch mounting suits consolidated wiring closets in multi-tenant professional buildings.
- Blade Servers:Shared backplane architectures minimize cabling density for clustered compute deployments.
Tower Servers lead volumes today; Micro Servers are gaining share fastest.
Installation:
Deployment models stratify by capital preference—hardware ownership versus operational expenditure—and data sovereignty requirements.
- On-Premises:Physical hardware ownership satisfies GDPR data-localization mandates for German medical practices and French accounting partnerships. These buyers prioritize UEFI firmware attestation and hardware-rooted encryption over subscription flexibility.
- Hybrid:Edge-to-cloud orchestration synchronizes local NAS caches with object storage tiers, eliminating cloud egress fees for frequently accessed files. Distributed creative agencies in New York and Amsterdam adopt these configurations for collaborative project archives.
- Cloud-Based:Fully managed instances shift capital expenditure to recurring subscriptions for cash-constrained startups.
- Removable Storage:Hot-swappable drive bays enable physical data transport for air-gapped backup workflows.
On-Premises retains the largest installed base; Hybrid deployments show the steepest expansion trajectory.
Connectivity:
Interface selection determines integration depth with existing network infrastructure and mobile device ecosystems.
- Ethernet:Wired Gigabit and 10GbE backbones anchor performance-sensitive workloads in home studios and small production houses. These deployments prioritize deterministic latency for video editing timelines and database transaction consistency.
- Wi-Fi:Wi-Fi 6E and emerging Wi-Fi 7 standards eliminate cabling constraints for retrofitted residential spaces. Remote workers in suburban United States markets favor these configurations for flexible room placement without structural modifications.
- Bluetooth:Low-energy pairing supports peripheral management and initial device provisioning.
- USB:Direct-attached expansion handles archival cold storage and emergency recovery scenarios.
- VPN:Encrypted tunneling extends LAN security boundaries for traveling professionals and branch locations.
Ethernet dominates throughput-critical applications; Wi-Fi is climbing fastest as mesh networking matures.
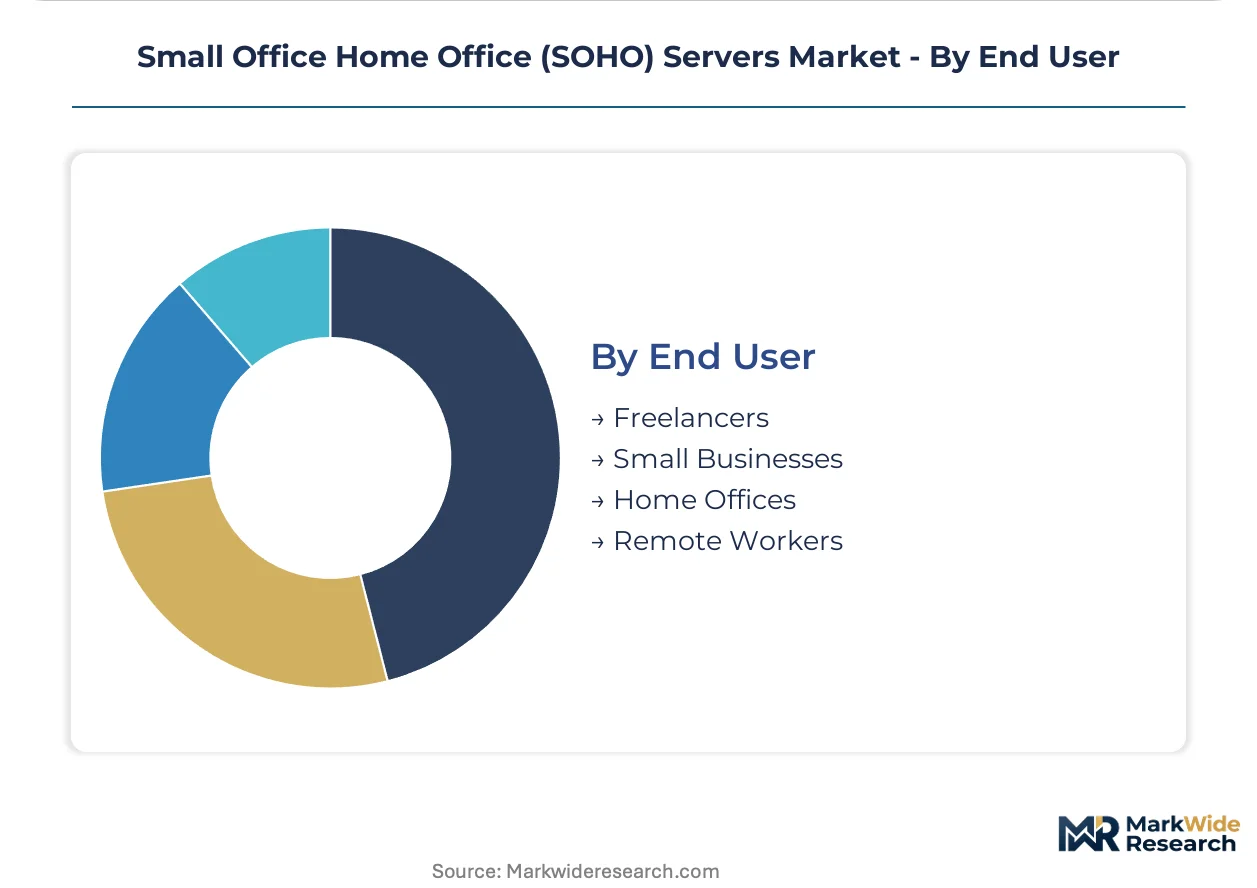
End User:
Buyer categories separate by technical sophistication, procurement authority, and workload predictability.
- Small Businesses:Partnerships with 10-50 employees centralize file collaboration and customer databases on localized infrastructure. These buyers negotiate volume licensing for virtualization stacks and prioritize next-business-day hardware replacement.
- Remote Workers:Individual professionals operating from dedicated home offices require silent operation and residential-grade power efficiency. Former enterprise IT staff in Seattle and Austin drive premium configuration sales with sophisticated software-defined storage requirements.
- Freelancers:Solo practitioners balance minimal capital outlay against professional deliverable requirements.
- Home Offices:Household-based administrative functions prioritize ease of setup over performance headroom.
Small Businesses contribute the largest revenue pool; Remote Workers are expanding most quickly as distributed employment models institutionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Remote work professionals cluster in metropolitan technology corridors, driving localized demand for compact server infrastructure across distinct regulatory environments.
United States
Distributed architecture and legal partnerships in Austin and Seattle anchor procurement of tower servers with sub-65W thermal signatures. The FCC governs electromagnetic emissions for integrated wireless modules under Part 15 rules. Dallas-Fort Worth hosts engineering centers refining acoustic isolation for residential deployments without dedicated cooling infrastructure.
Germany
Medical practices and accounting partnerships in Munich and Hamburg prioritize GDPR-compliant on-premises storage with hardware-rooted encryption. The EU F-Gas Regulation and Ecodesign requirements mandate fanless thermal architectures below 500W consumption. Stuttgart engineering clusters develop heat-pipe arrays and vapor-chamber spreads for tower chassis compliance.
Japan
Post-production collectives in Tokyo and Osaka deploy ARM-based micro servers for localized 4K transcoding without workstation-grade power draw. METI top-runner standards progressively tighten idle-state consumption limits for network-attached equipment. Yokohama manufacturing corridors concentrate supply chain coordination for compact thermal designs.
India
The country's 63 million MSME segment drives assembly localization under the PLI scheme for electronics manufacturing. BIS certification requirements shape minimum efficiency thresholds for power supplies entering the domestic market. Bengaluru and Hyderabad technology corridors anchor software-defined storage integration for micro-enterprise digitization.
United Kingdom
Creative agencies in London and Manchester adopt hybrid edge-to-cloud configurations to eliminate egress fees for collaborative project archives. GDPR data-localization mandates persist post-Brexit through retained EU law frameworks. Cambridge engineering clusters refine computational fluid dynamics for silent residential operation.
Small Office Home Office (SOHO) Servers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated vendor base. The market structures around three tiers: incumbent x86 system integrators, ARM-native appliance specialists, and subscription-orchestrated hybrid platforms. Consolidation pressure concentrates among tower server fabricators facing DDR5 and NAND flash margin compression. Dominant competitive moves include geographic assembly diversification and software licensing unbundling from hardware transactions.
Within the proprietary ecosystem tier, Synology Inc and QNAP Systems Inc exemplify appliance-centric architectures competing through software-defined storage differentiation. NETGEAR Inc anchors mesh-integrated positioning at the networking convergence vector. Dell Technologies and Hewlett Packard Enterprise occupy the enterprise-descended system integrator archetype, while ASUSTOR Inc represents the specialized NAS-native fabricator segment.
| Leading Market Players |
|---|
| Synology Inc |
| QNAP Systems Inc |
| NETGEAR Inc |
| Western Digital Corporation |
| ASUSTOR Inc |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Lenovo |
| Apple Inc |
| Others |
Value Network & Pricing Analysis
Distributed professional services partnerships in the United States anchor transactional hardware procurement with bundled installation and tier-1 support, while European micro-enterprises under EU Ecodesign mandates absorb premium engineering costs for sub-2W idle-state compliance. This geographic bifurcation concentrates pricing power with vendors possessing modular thermal architectures and software licensing flexibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silent ARM-based micro servers from acoustic-isolated tower configurations and entry-level rack units. Price differentiation rests on certification grade—ENERGY STAR and EU Ecodesign tiers command 15-25% premiums—and after-sales service bundling. Cost compression in the standard tier intensifies because DDR5 and NAND flash volatility squeezes system integrator margins. Freelancers and home offices exhibit highest price sensitivity, while distributed architecture partnerships in Germany and the United States demonstrate lowest sensitivity due to total-cost-of-ownership framing.
Supply Chain Analysis
Engineering talent scarcity in Taiwan and China constrains chassis thermal design capacity, forcing OEMs to relocate computational fluid dynamics teams to Stuttgart and Dallas-Fort Worth. Advanced node fabrication for ARM SoCs draws from TSMC in Taiwan, while NAND flash supply sources from Samsung and SK Hynix in South Korea. Single-source vulnerability in leading-edge semiconductor lithography exposes volume server deployments to geopolitical disruption. Distribution runs through value-added resellers in the United States and Germany who unbundle hardware from software licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's PLI-scheme manufacturing incentives and the EU's escalating Ecodesign efficiency mandates, where assembly cost differentials of 30-40% separate subcontinental production from European compliance engineering.
For Market Incumbents: Anticipate ARM-native software ecosystem displacement by securing backward compatibility licenses for x86 virtualization stacks. Defensive consolidation through captive supply of heat-pipe arrays from Stuttgart engineering clusters mitigates acoustic engineering talent scarcity. Channel control expansion into Indian MSME distribution networks counters margin compression from DDR5 pricing volatility.
For New Entrants and Emerging Players: Capture subscription-based hybrid orchestration revenue pools that extend lifetime value beyond transactional hardware sales. White-space concentration in India's 63 million MSME segment offers lowest competitive density, particularly for software-defined storage integration. Go-to-market leverage through Bengaluru technology corridor partnerships accelerates local assembly qualification under PLI scheme incentives.
For Investors and Strategic Acquirers: Networking equipment manufacturers are the most active acquirer in this space, seeking mesh-integrated server node capabilities. Long-term viability over a 5-10 year window hinges on instruction-set architecture bifurcation resolution favoring ARM-native ecosystems. Acquisition target archetypes include specialized NAS-native fabricators with proprietary containerization platforms. The signal to watch is TSMC capacity allocation shifts for sub-5nm ARM SoC production.
| Strategic Initiative | Industry Significance |
|---|---|
| ARM-Native Software Ecosystem Development | Qualcomm and Ampere silicon displacement of legacy x86 virtualization stacks accelerates margin recovery. |
| Fanless Thermal Architecture Engineering | EU F-Gas Regulation compliance for sub-500W equipment opens German and French procurement channels. |
| Subscription-Based Hybrid Orchestration | Recurring revenue models capture lifetime value beyond Dell and HPE transactional hardware sales. |
| India PLI Scheme Assembly Localization | Bengaluru and Hyderabad corridors reduce landed cost for 63 million MSME addressable market. |
| Acoustic Isolation IP Acquisition | Dallas-Fort Worth engineering clusters hold scarce computational fluid dynamics talent for residential deployment. |
Research Methodology
Multiple input streams—primary interviews with SOHO server procurement officers, platform engineers at distributed creative agencies, and channel partners in value-added reseller networks—were reconciled against secondary validation from SEC filings of networking equipment manufacturers, hyperscaler capex disclosures, and EU Ecodesign regulatory documentation. Bottom-up and top-down triangulation cross-checked unit shipment estimates with revenue aggregation across tower, micro, rack, and blade configurations.
Data-stream reconciliation applied analytical frameworks across the analysis window, modeling segmentation by product type, installation model, connectivity interface, and end-user archetype. CAGRs were derived from slope-intercept analysis of historical shipment trajectories and forward-looking replacement cycle assumptions. Industry-specific forecast inputs incorporated METI top-runner standard phase-in schedules and India PLI scheme capacity buildout timelines.
Taiwan semiconductor concentration, EU regulatory tier escalation, and ARM software ecosystem maturity are the dominant revision risks that could compress or extend projection horizons. Forecasts reflect documented assumptions about thermal envelope engineering feasibility and supply continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bitcoin Mining Servers Market
Others
China Packaging Primers Market
Others
North America Luxury Car Market
Others
Smart Home Water Softener Market
Others
Global Mica Market
Others
Global Bio-Based Chemicals Market
Others
Rugged Tablet Market
Others
Global Digital Caliper Market
Others
Aircraft Cameras Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Global Multi Domain Controller Market
Others
Animal Feed Alternative Protein Market
Others
Nuclear Power Cables Market
Others
Gym Wipes Market
Others
Latin America Domestic CEP Market
Others
South America Automotive LED Lighting Market