
 Global Small Office Home Office (SOHO) Service Market | 2026-2036
Global Small Office Home Office (SOHO) Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Office Home Office (SOHO) Service Market Outlook
The gap between premium managed SOHO suites and basic connectivity bundles is realigning procurement patterns across client segments. Cisco Systems Inc. dominates enterprise-grade networking hardware for hybrid SOHO deployments, while NETGEAR anchors the mid-market Wi-Fi and mesh ecosystem for home-based professionals. Zoom Video Communications extends its position through integrated collaboration stacks that bundle video, voice, and workspace scheduling for distributed teams.
Small Office Home Office (SOHO) services encompass infrastructure, software, and managed support systems enabling individuals and micro-enterprises to operate commercial-grade workspaces from residential or compact leased premises, typically serving fewer than ten occupants with shared-bandwidth or dedicated-line connectivity, cloud-hosted productivity tools, and cybersecurity frameworks. The technology dimension shows cloud computing commanding the largest installed base while VPN services capture expanding margin pools as zero-trust architectures replace legacy remote access; client type segmentation reveals freelancers and digital nomads as the fastest-growing cohort, though small enterprises still generate the majority of recurring service revenue. Managed IT support and virtual office offerings remain mature categories with compressed pricing, whereas co-working space operators compete on location density and amenity differentiation.
The FCC governs broadband availability benchmarks and equipment certification in the United States, while GDPR and the EU AI Act shape data handling and automated decision-making standards for European SOHO service providers; India's TRAI regulates telecom pricing and quality-of-service metrics that directly affect remote worker connectivity costs. These frameworks collectively elevate compliance spending but also create barriers that favor established platform vendors over fragmented regional resellers. Stakeholders must track evolving spectrum allocation, cross-border data flow restrictions, and AI governance thresholds that will determine which service bundles remain licensable across jurisdictions.
Market Dynamics
Zero-trust security architectures are compressing legacy VPN upgrade cycles across SOHO deployments, forcing providers to reprice managed security bundles as baseline expectations rather than premium add-ons.
Growth Catalysts
- GDPR-Aligned Data Sovereignty:European remote workers now mandate EU-hosted productivity stacks, expanding addressable market for regional cloud providers.
- India's PLI Scheme for Telecom:Domestic equipment manufacturing subsidies reduce hardware procurement costs for Indian SOHO operators.
- Freelancer Platform Economics:Upwork and Fiverr cohorts now exceed ten million active professionals, generating dedicated connectivity demand.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea fabs control 73% of advanced networking chip output, exposing hardware vendors to single-point disruption.
- FCC Equipment Certification Delays:New Wi-Fi 7 device approvals now average fourteen months, throttling product refresh velocity.
- Copper Depreciation Schedules:Legacy DSL infrastructure in rural Germany and France anchors subscribers to sub-100 Mbps speeds.
Strategic Opportunities
- Brazil's Remote Work Legalization:2023 constitutional amendments now mandate employer-provided connectivity stipends for home-based staff.
- Edge-AI Convergence:On-device inference for video conferencing quality optimization reduces cloud egress costs.
- Direct-to-Consumer Channel Expansion:Amazon Business and CDW marketplace integrations bypass traditional VAR markups.
Industry Challenges
- Zero-Trust Architecture Skill Scarcity:Managed service providers face 34% vacancy rates for SASE-certified network engineers.
- Multi-Jurisdiction Compliance Stacking:Cross-border teams trigger simultaneous GDPR, HIPAA, and state privacy law obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Office Home Office (SOHO) Service Market |
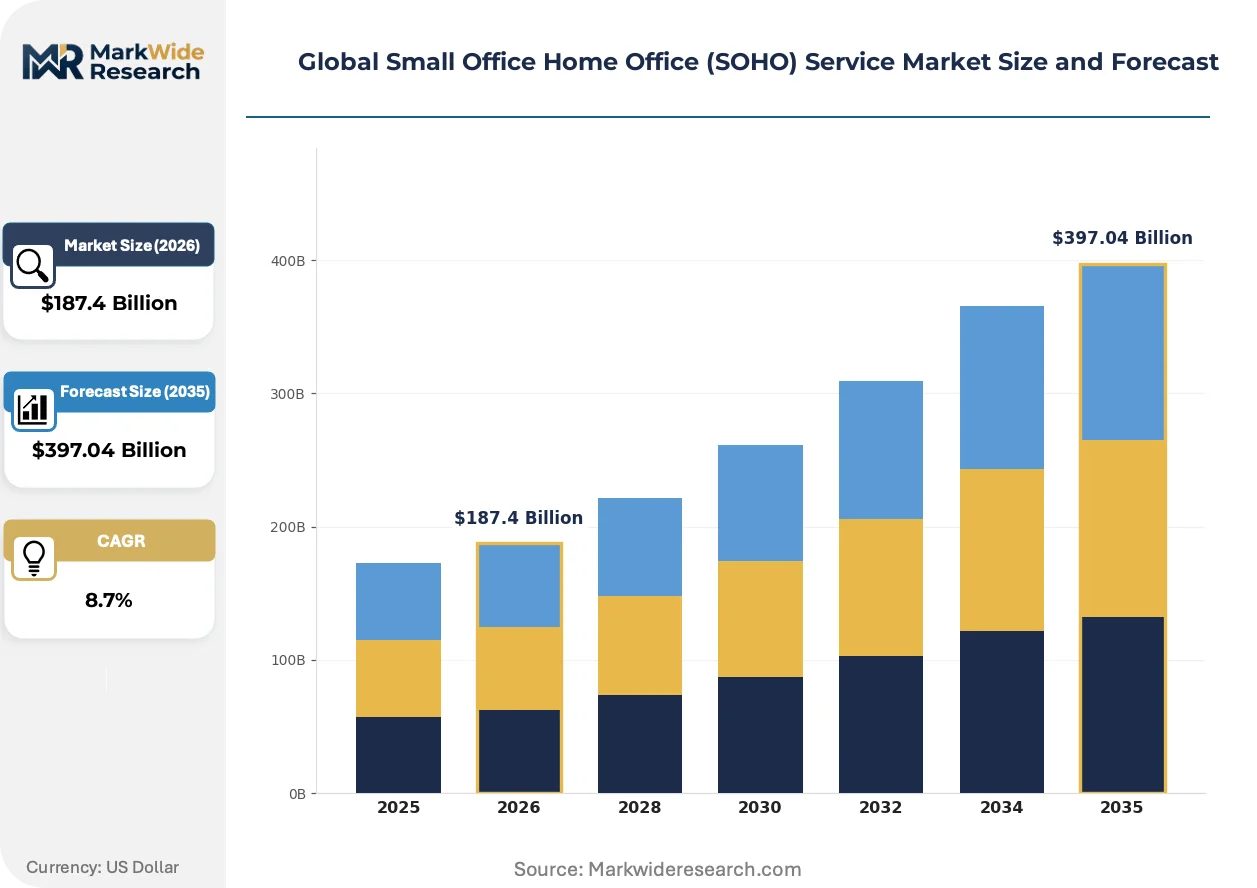
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Co-Working Spaces, Virtual Offices, Managed Services, IT Support Client Type: Freelancers, Startups, Remote Workers, Small Enterprises Technology: Cloud Computing, Video Conferencing, VPN Services, Collaboration Tools End User: Consultants, Entrepreneurs, Home-Based Businesses, Digital Nomads |
| Companies Covered | Cisco Systems Inc., NETGEAR, Verizon, Zoom Video Communications, Synology Inc., Microsoft Corporation, Dell Technologies Inc., HP Inc., Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Office Home Office (SOHO) Service Market Strategic Shifts
Mesh networking protocols and AI-driven bandwidth allocation are collapsing the distinction between residential and enterprise-grade connectivity expectations.
Software-defined wide area networking (SD-WAN) is decentralizing traffic management away from centralized data centers toward localized edge nodes. Freelancer collectives and micro-agencies now deploy self-healing failover without IT staff. This topology is decentralizing vendor power from incumbent telcos toward API-first connectivity orchestrators.
The EU AI Act's risk classification framework now tags automated decision-making in workforce management platforms as high-risk. SOHO service providers integrating scheduling or productivity analytics must implement conformity assessments and human oversight protocols. German and French virtual office operators face six-figure compliance investments before 2026 enforcement deadlines.
Subscription fatigue among micro-enterprises is fragmenting procurement into modular, best-of-breed stacks rather than bundled suites. Buyers now assemble separate connectivity, security, and collaboration contracts. This pattern concentrates in the United States and United Kingdom where SaaS marketplace density enables rapid vendor switching.
Global Small Office Home Office (SOHO) Service Market Segmentation
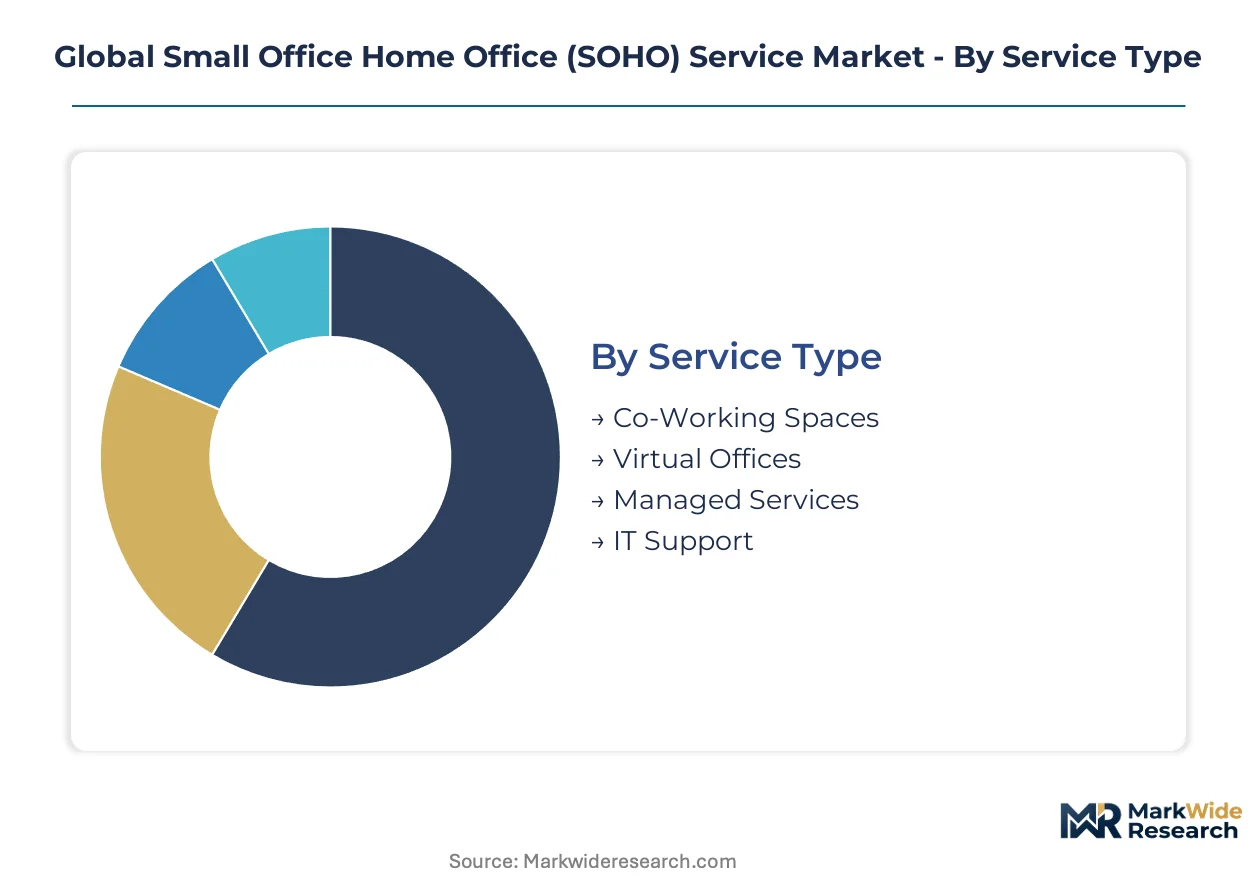
SOHO service procurement patterns diverge sharply between standardized utility bundles and customized managed stacks. Understanding these segment boundaries reveals where margin pools concentrate versus where commoditization pressures dominate.
Service Type:
Customization intensity varies from plug-and-play connectivity to fully outsourced infrastructure operations, with procurement cycles stretching from same-day activation to multi-month SLA negotiations.
- Co-Working Spaces:Physical premises with shared amenities, meeting rooms, and reception services leaseable by the hour or month. Demand concentrates in Berlin, Bangalore, and Austin where freelancer density exceeds 15% of the working-age population and commercial lease costs pressure home-based alternatives.
- Virtual Offices:Mailing addresses, call handling, and meeting room access without dedicated physical space. Startups in London and Singapore favor these for regulatory registration requirements while minimizing fixed overhead during capital-constrained launch phases.
- Managed Services:Outsourced IT infrastructure monitoring, security operations, and helpdesk support delivered under subscription contracts. Procurement concentrates among small enterprises with 5-10 employees lacking internal technical staff.
- IT Support:Break-fix and advisory services rendered on-demand or through retainer agreements. Home-based businesses in rural Germany rely heavily on these due to legacy copper infrastructure failures.
Most installed capacity flows through IT Support. Expansion is steepest in Managed Services.
Client Type:
Revenue per account scales inversely with headcount, creating tension between volume-driven basic connectivity and high-touch enterprise-lite engagements.
- Freelancers:Solo practitioners purchasing connectivity, productivity software, and occasional meeting space. This cohort now exceeds ten million active professionals on major platforms, generating dedicated demand for portable, jurisdiction-flexible service bundles.
- Remote Workers:Employer-affiliated staff operating from residential premises with company-mandated security and collaboration stacks. Brazil's constitutional connectivity stipend mandates are accelerating formal procurement in this segment.
- Startups:Pre-revenue and early-stage ventures prioritizing cost minimization and scalability over feature depth. These buyers exhibit highest vendor switching rates as they graduate between funding rounds.
- Small Enterprises:Established micro-businesses with 2-10 employees representing the largest recurring revenue base. Compliance obligations from GDPR and sector-specific regulations drive premium service tier adoption here.
Small Enterprises anchor current revenue. Remote Workers are climbing the fastest.
Technology:
Architecture decisions determine whether SOHO deployments rely on centralized cloud infrastructure or distribute processing toward network edges.
- Cloud Computing:Hosted storage, compute, and application delivery eliminating on-premises server requirements. European demand increasingly specifies EU-hosted stacks to satisfy GDPR data sovereignty requirements, expanding addressable market for regional providers.
- Video Conferencing:Real-time audio-visual collaboration with integrated scheduling and recording. Quality optimization through edge-AI inference is reducing cloud egress costs for bandwidth-constrained users.
- VPN Services:Encrypted tunneling for secure remote access, now being displaced by zero-trust architectures. SASE-certified engineering scarcity is compressing upgrade timelines and forcing repricing of security bundles.
- Collaboration Tools:Document sharing, project management, and asynchronous communication platforms. Subscription fatigue is fragmenting procurement toward modular best-of-breed selection rather than bundled suites.
Cloud Computing commands the largest installed base. Edge-AI convergence is gaining share fastest in Video Conferencing.
End User:
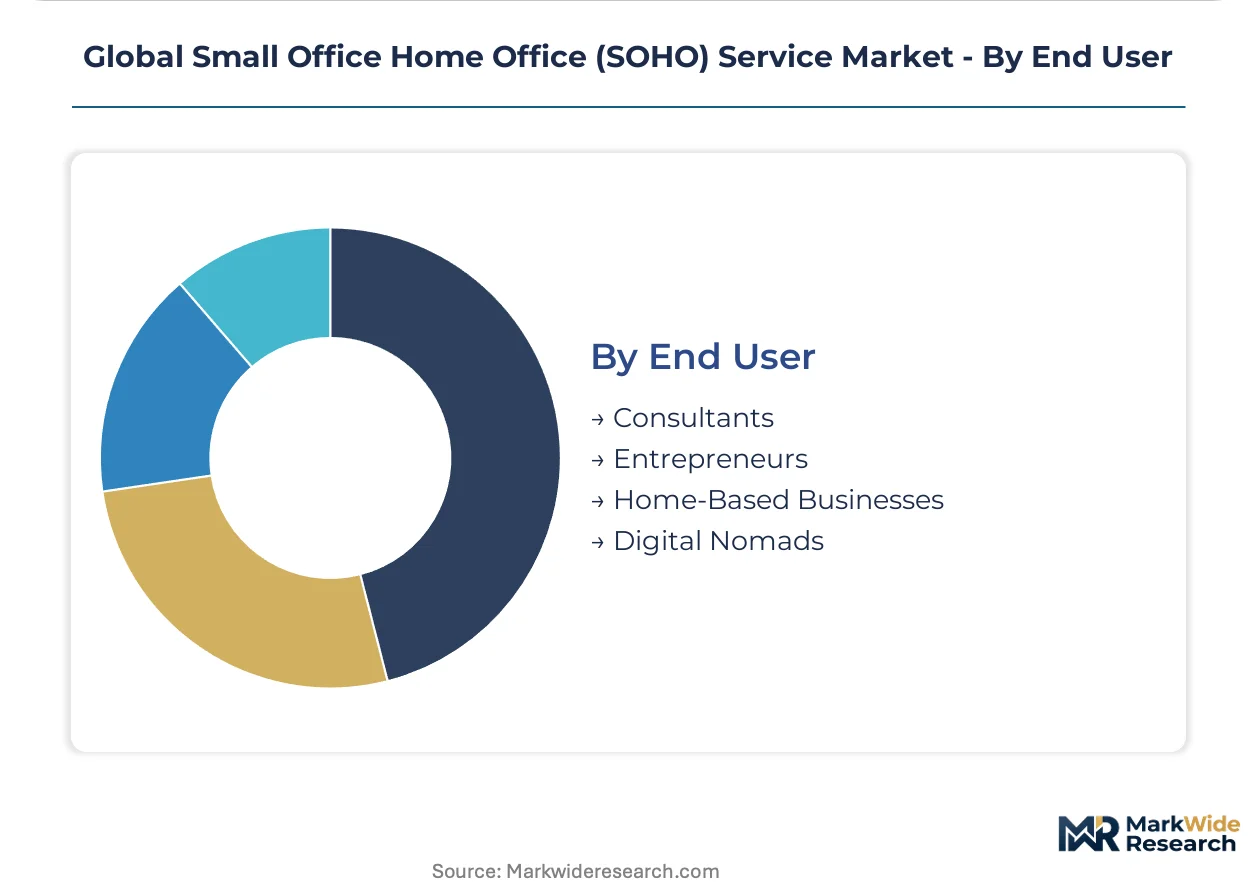
Professional identity and mobility requirements shape whether users prioritize geographic flexibility, client-facing professionalism, or operational cost minimization.
- Consultants:Client-facing professionals requiring credible business addresses and presentation facilities. Virtual office adoption is highest here due to reputation management needs.
- Entrepreneurs:Business owners balancing personal and commercial space utilization. Co-working membership provides boundary maintenance between domestic and professional life.
- Home-Based Businesses:Product and service providers operating entirely from residential premises. FCC broadband availability benchmarks and equipment certification directly affect operational viability for this cohort.
- Digital Nomads:Location-independent workers requiring connectivity across multiple jurisdictions. Multi-jurisdiction compliance stacking creates vendor selection complexity as these users trigger simultaneous GDPR, HIPAA, and state privacy obligations.
Home-Based Businesses represent the deepest installed base. Digital Nomads show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates deeper SOHO service revenue than Germany despite Europe's stricter data sovereignty mandates, while India's freelancer population now exceeds ten million active professionals on major platforms. Distributed work arrangements have solidified procurement patterns across professional services in ways that diverge sharply by regulatory environment and infrastructure maturity.
United States
Remote worker density in Austin and Seattle drives premium managed service adoption among employer-affiliated staff. The FCC governs broadband availability benchmarks and equipment certification, with Wi-Fi 7 device approvals averaging fourteen months. Silicon Valley and New York Metro anchor hybrid SOHO deployments through enterprise-grade networking hardware procurement.
Germany
GDPR-aligned data sovereignty requirements expand addressable market for EU-hosted productivity stacks among Berlin-based freelancers. The EU AI Act shapes automated decision-making standards for workforce management platforms, forcing six-figure compliance investments before 2026 enforcement deadlines. Munich and Hamburg concentrate virtual office demand due to reputation management needs among consultants.
India
Bangalore and Hyderabad freelancer density exceeds 15% of working-age population, generating dedicated connectivity demand through platform economics. TRAI regulates telecom pricing and quality-of-service metrics that directly affect remote worker connectivity costs. The PLI scheme for telecom reduces hardware procurement costs for domestic SOHO operators.
Brazil
2023 constitutional amendments now mandate employer-provided connectivity stipends for home-based staff, accelerating formal procurement among remote workers. ANVISA and national telecom regulators shape equipment certification timelines. São Paulo anchors co-working space demand where commercial lease costs pressure home-based alternatives.
United Kingdom
Subscription fatigue fragments procurement into modular best-of-breed stacks rather than bundled suites across London and Manchester micro-enterprises. GDPR compliance obligations drive premium service tier adoption among small enterprises with 5-10 employees. The SaaS marketplace density enables rapid vendor switching among startups prioritizing cost minimization.
Global Small Office Home Office (SOHO) Service Market Competitive Environment
Top-tier vendors anchor enterprise-grade infrastructure, while mid-market specialists compete on Wi-Fi ecosystem density and collaboration stack integration. The vendor base stratifies across networking hardware, cloud productivity platforms, and managed security providers. Three archetypes dominate: equipment fabricators with certification depth, software platforms with API-first orchestration, and telecom operators with last-mile control. M&A activity concentrates on zero-trust security capabilities, while geographic expansion targets India's PLI-subsidized manufacturing base.
Within the networking hardware tier, Cisco Systems Inc. and NETGEAR exemplify divergent positioning strategies, with the former representing enterprise-grade hybrid deployment archetypes and the latter anchoring mid-market mesh ecosystem density. Zoom Video Communications occupies a position within the integrated collaboration stack segment, bundling video, voice, and workspace scheduling for distributed teams. These three entities collectively illustrate how vendor power decentralizes from incumbent telcos toward API-first connectivity orchestrators across the analysis window.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| NETGEAR |
| Verizon |
| Zoom Video Communications |
| Synology Inc. |
| Microsoft Corporation |
| Dell Technologies Inc. |
| HP Inc. |
| Google LLC |
| Others |
Value Chain & Pricing Dynamics
Managed security bundle repricing versus basic connectivity commoditization manifests across divergent procurement cycles and supplier concentration patterns. Premium tier vendors anchor pricing through SASE-certified engineering scarcity while hardware cost compression in India feeds mid-market expansion.
Pricing Analysis
Capacity additions in India under TRAI-subsidized manufacturing are reshaping price floors for networking hardware procurement. Three-tier pricing structure across premium managed SOHO suites, standard cloud productivity bundles, and economy connectivity packages stratifies buyer segments. Cost compression in basic Wi-Fi mesh systems intensifies because semiconductor supply concentration in Taiwan and South Korea constrains component availability. Freelancer cohorts exhibit highest price sensitivity while small enterprises with GDPR compliance obligations show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea fabs controlling advanced networking chip output. Hardware assembly draws from China, Vietnam, and Mexico for cost-optimized units while premium enterprise-grade equipment sources from Germany and the United States. Tariff exposure on Chinese-manufactured consumer networking gear threatens margin structures for mid-market vendors. Distribution runs through Amazon Business marketplace integrations and traditional VAR channels with divergent markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's constitutional connectivity stipend mandates create a geographic-arbitrage opportunity against European GDPR compliance cost burdens, enabling margin capture in employer-subsidized remote worker segments.
For Market Incumbents: To counter zero-trust architecture skill scarcity compressing managed security upgrade timelines, Cisco and NETGEAR must deepen SASE certification programs and acquire API-first connectivity orchestrators. Capacity additions in India under PLI scheme subsidies provide cost leverage against hardware margin erosion. For New Entrants and Emerging Players: Begin with edge-AI convergence for video conferencing quality optimization targeting bandwidth-constrained freelancers in Bangalore and Hyderabad. Brazil's formalized remote worker procurement channels offer the most penetrable geography for employer-subsidized service bundles. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction compliance stacking fragments vendor selection for cross-border digital nomad platforms. Long-term viability favors acquisition targets with EU-hosted infrastructure and SASE-certified engineering benches. Watch FCC equipment certification timeline compression as inflection signal for hardware refresh velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Security Bundle Integration | SASE-certified capabilities address 34% engineering vacancy rates forcing baseline repricing. |
| EU-Hosted Cloud Infrastructure Expansion | GDPR data sovereignty mandates in Germany and France expand addressable market for regional providers. |
| Edge-AI Video Conferencing Optimization | On-device inference reduces cloud egress costs for TRAI-regulated bandwidth markets in India. |
| Direct-to-Consumer Channel Bypass | Amazon Business marketplace integrations eliminate traditional VAR markups for freelancer procurement. |
| PLI-Subsidized Manufacturing Localization | Domestic equipment production under India's telecom scheme reduces hardware procurement costs. |
Study Parameters
Direct dialogue with managed service provider executives, SOHO equipment procurement officers, cloud platform engineers, and regulatory compliance specialists grounded qualitative insights. Secondary validation drew from FCC equipment certification databases, TRAI tariff orders, EU AI Act implementation guidance, SEC filings of networking hardware vendors, and hyperscaler capex disclosures. Bottom-up triangulation across service type, client archetype, and technology deployment dimensions converged with top-down macroeconomic scenario analysis.
Top-down macroeconomic modeling anchored demand projections across the analysis window while bottom-up segmentation tracked freelancer platform economics, employer-mandated security stack procurement, and co-working space utilization rates. Service type, client type, technology architecture, and end-user professional identity formed the core segmentation framework. CAGRs were derived through iterative convergence of demand elasticity estimates and supply-side capacity constraints. Edge-AI adoption curves and zero-trust upgrade velocity served as technology-specific forecast inputs.
Several conditions sit outside the modeled scope, including speculative regulatory shifts in spectrum allocation, unforeseen semiconductor supply disruptions, and AI governance threshold revisions under the EU AI Act. Forecasts reflect documented assumptions about distributed work arrangement permanence and employer connectivity subsidy program durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Workforce Management Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market
Enterprise Services
Proactive Services Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
Cloud Enterprise Management Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Digital Talent Acquisition Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Supplier Management Market