
 Animal Feed Alternative Protein Market | 2026-2036
Animal Feed Alternative Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Alternative Protein Market Analysis
Soymeal is hardening as the baseline cost benchmark against which novel proteins must compete. Innova Feed leverages vertical integration from larvae rearing to oil extraction, anchoring its position in French aquafeed supply chains. Cargill Incorporated competes through its global oilseed processing footprint, while Darling Ingredients specializes in rendering-derived proteins that occupy a distinct sustainability narrative.
Animal feed alternative protein encompasses non-conventional protein sources formulated for livestock and aquaculture nutrition, typically containing 40-80% crude protein with amino acid profiles adjusted through enzymatic processing or blending to meet species-specific digestibility coefficients. Its primary purpose is to displace fishmeal, soybean meal, and other conventional inputs in diets for monogastric and ruminant animals. Insect protein leads product type segments due to established regulatory approvals in Europe and superior feed conversion ratios in salmonids. Aquaculture feed represents the fastest-growing application channel, driven by marine ingredient substitution mandates from retailers and certification bodies. Powder form dominates current volume, though pellet formulations are gaining share in automated feeding systems for intensive pig and poultry operations.
The EU Green Deal and EFSA novel food frameworks shape product approval timelines and labeling requirements across European feed markets. The EPA regulates insect-farming effluent standards in the United States, while FAO/WHO Codex Alimentarius guidelines influence international trade acceptance for alternative protein safety claims. Stakeholders must monitor how rapidly evolving feed additive regulations in major protein-consuming countries will determine which technologies achieve commercial scale first.
Market Dynamics
Soymeal price volatility is compressing margins for aquafeed compounders and forcing rapid evaluation of insect meal, single-cell proteins, and processed animal proteins as displacement candidates.
Growth Catalysts
- EU Green Deal F-Gas Regulation:Binding emission-reduction targets for livestock operations are mandating lower-carbon feed inputs across Danish, Dutch, and French supply chains.
- Salmonid aquaculture expansion:Norwegian and Scottish farmed salmon producers are reformulating diets to reduce marine ingredient dependence below 10% inclusion rates.
- Black soldier fly larvae processing:Automated rearing and fractionation systems are collapsing production costs for insect meal oil and protein concentrates.
Market Restraints
- Soybean meal price anchoring:Chicago Board of Trade futures continue setting the cost floor against which novel proteins must achieve parity.
- EFSA novel food authorization timelines:18-24 month safety evaluation periods delay commercial rollout for new insect species and microbial strains.
- Rendering capacity concentration:Darling Ingredients and three European processors control 70% of EU animal by-product processing infrastructure.
Strategic Opportunities
- Brazilian cattle feed underpenetration:World's largest beef exporter maintains minimal alternative protein inclusion despite deforestation-linked soy pressure.
- Precision fermentation amino acids:Integration with existing corn ethanol infrastructure offers pathways to bypass whole-protein regulatory pathways.
- Direct-to-farm digital channels:Bypassing traditional distributor markups through automated feed ordering platforms for intensive poultry operations.
Industry Challenges
- Entomology and bioprocess engineering talent scarcity:Insect farming operations compete with pharmaceutical biotech for fermentation specialists and geneticists.
- ASC and BAP certification alignment:Aquaculture stewardship standards require traceability documentation that legacy protein suppliers cannot yet provide.
- Feed mill retrofit costs:Pelleting equipment designed for soybean meal requires modification to handle hygroscopic insect protein powders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Alternative Protein Market |
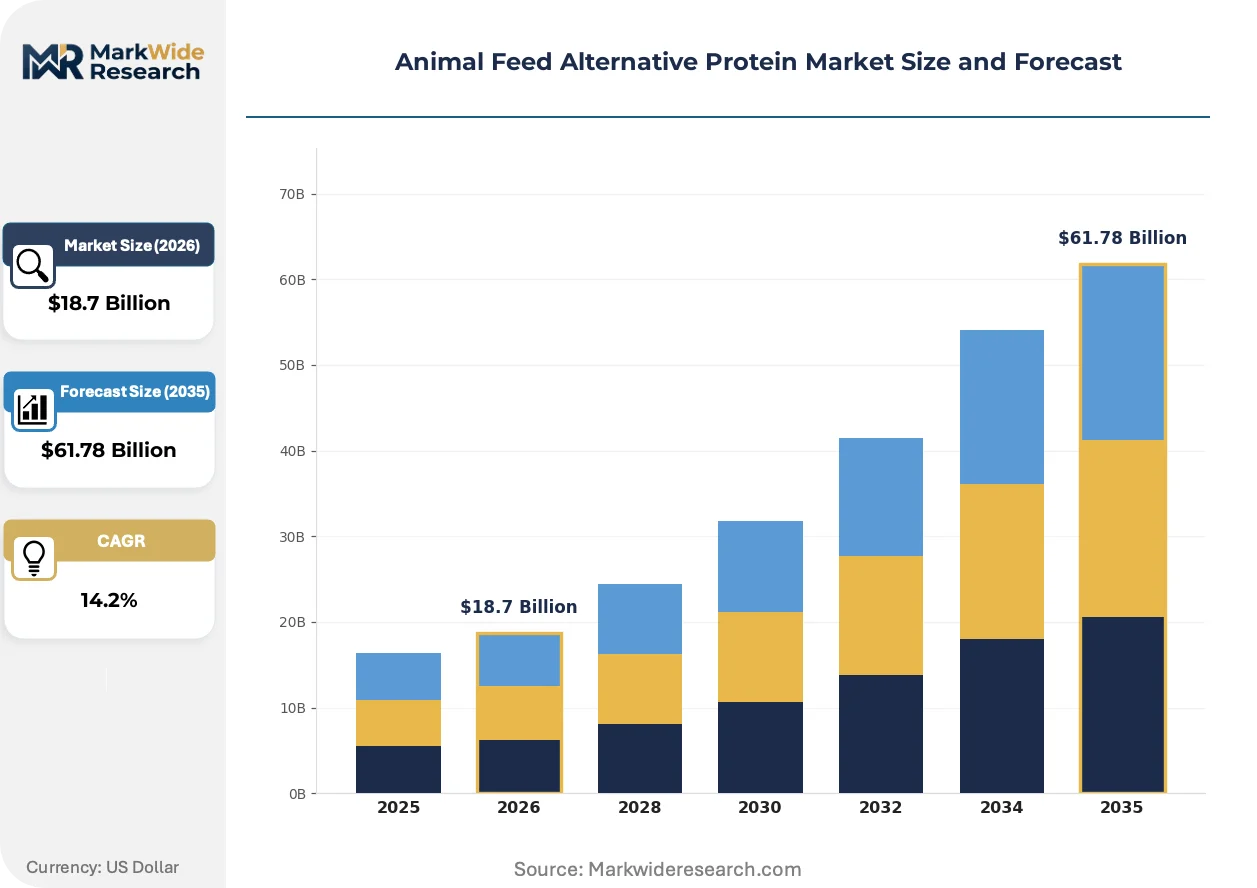
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insect Protein, Soy Protein, Pea Protein, Algal Protein Application: Poultry Feed, Aquaculture Feed, Ruminant Feed, Swine Feed Form: Powder, Granules, Liquid, Pellets End User: Farmers, Livestock Producers, Aquaculture Operations, Feed Manufacturers |
| Companies Covered | ADM (Archer Daniels Midland Company), Cargill Incorporated, DuPont, Innova Feed, Roquette Frères, Ingredion Incorporated, Darling Ingredients, Glanbia PLC, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Alternative Protein Market Emerging Trajectories
Processing technology maturation is collapsing the cost gap between conventional and alternative proteins faster than regulatory frameworks can adapt, compressing commercialization timelines for novel ingredients.
Continuous-flow black soldier fly rearing with automated harvest and fractionation is overtaking batch-system mealworm operations in capital efficiency. Norwegian salmon feed compounders are adopting the technology at commercial scale. The shift is compressing payback periods for insect farming infrastructure below four years.
EFSA's 2023 updated guidance on novel protein safety dossiers is extending data requirements for allergenicity and heavy-metal bioaccumulation. European insect processors are consolidating to share toxicology study costs. The regulation is delaying market entry for smaller larval species while favoring established black soldier fly suppliers.
Retail-driven marine ingredient substitution mandates are restructuring procurement specifications for certified aquafeed. French supermarket chains now require salmon suppliers to document fishmeal inclusion below 5%. The specification is concentrating demand among compounders with validated alternative protein supply agreements.
Animal Feed Alternative Protein Market Segmentation
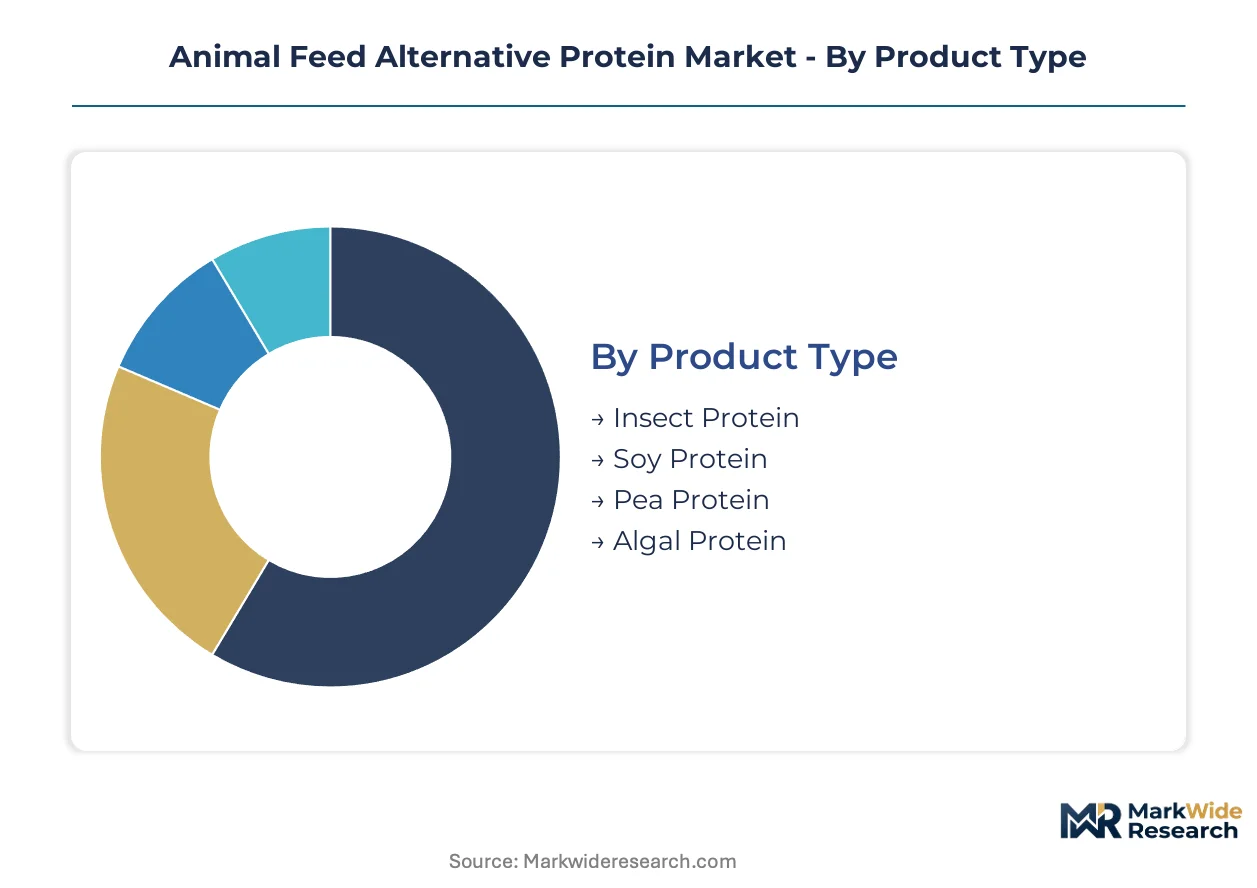
Alternative protein feed ingredients fragment across four structural dimensions. Product chemistry determines nutritional substitution potential. Application channels dictate regulatory exposure and margin capture. Form factor shapes processing infrastructure requirements. End-user category fixes procurement scale and technical specification intensity.
Product Type:
Feed compounders cycle through protein sources as cost-performance benchmarks shift. Each alternative carries distinct amino acid profiles, digestibility coefficients, and approval statuses that determine upgrade timing.
- Insect Protein:Black soldier fly larvae meal contains 40-60% crude protein with favorable methionine-lysine ratios for monogastric diets. Norwegian salmon feed producers are locking in multi-year offtake agreements as marine ingredient caps tighten below 10% inclusion thresholds.
- Soy Protein:Processed soy concentrates and isolates deliver standardized 65-85% protein content with established supply chains anchored to Chicago futures pricing. Danish and Dutch compounders treat soy protein as the displacement baseline that novel proteins must undercut on cost or exceed on sustainability credentials.
- Pea Protein:Pulse-derived concentrates offer intermediate protein levels (50-60%) with lower anti-nutritional factors than raw legumes. French poultry integrators are testing pea protein in antibiotic-free diet formulations.
- Algal Protein:Microalgal biomass and extracted proteins provide omega-3 fatty acid co-benefits alongside protein content. Production scale remains constrained by photobioreactor capital costs and energy inputs.
Volume placements concentrate in Soy Protein; the faster expansion belongs to Insect Protein.
Application:
Species-specific digestive physiology and certification requirements create divergent substitution economics. Aquaculture carries the strictest marine ingredient displacement mandates. Ruminant applications face methane emission accounting complexities.
- Aquaculture Feed:Salmonid and shrimp diets drive premium alternative protein adoption. Retail procurement specifications from French supermarket chains now require documented fishmeal inclusion below 5%, forcing compounders into validated supply agreements with insect and algal protein processors.
- Poultry Feed:Broiler and layer operations consume the largest absolute volumes of alternative proteins. Automated feeding systems in intensive Dutch and Belgian operations are shifting from mash to pellet formulations that accommodate processed soy and insect meal blends.
- Swine Feed:Post-weaning diets for piglets represent the highest-value insertion point for novel proteins due to digestive sensitivity and growth rate premiums. Sow gestation diets remain dominated by conventional soybean meal.
- Ruminant Feed:Cattle and dairy applications confront methane emission measurement requirements under EU Green Deal livestock protocols. Protein substitution must demonstrate lifecycle carbon reduction to qualify for sustainability-linked procurement programs.
Procurement volume clusters in Poultry Feed; Aquaculture Feed is climbing the fastest on certification-driven reformulation.
Form:
Physical presentation determines handling characteristics, storage stability, and equipment compatibility. Legacy feed mill infrastructure constrains adoption of hygroscopic or non-flowing materials.
- Powder:Fine-milled insect meal and algal protein concentrates dominate current volumes. Danish compounders report bridging and caking issues in pneumatic conveying systems designed for soybean meal.
- Pellets:Extruded formulations reduce dust losses and improve flowability in automated feeding systems. Norwegian salmon feed producers are standardizing on 6-8mm pellets containing 15-30% alternative protein inclusion.
- Granules:Intermediate particle sizes suit on-farm mixing operations and smaller-scale poultry producers. French livestock cooperatives favor granules for flexibility in diet customization.
- Liquid:Protein hydrolysates and fermented extracts enable precision delivery in water systems and TMR mixers. Applications concentrate in calf milk replacers and specialty aquaculture feeds.
Current infrastructure locks in Powder dominance; Pellets are gaining share fastest on automation retrofit cycles.
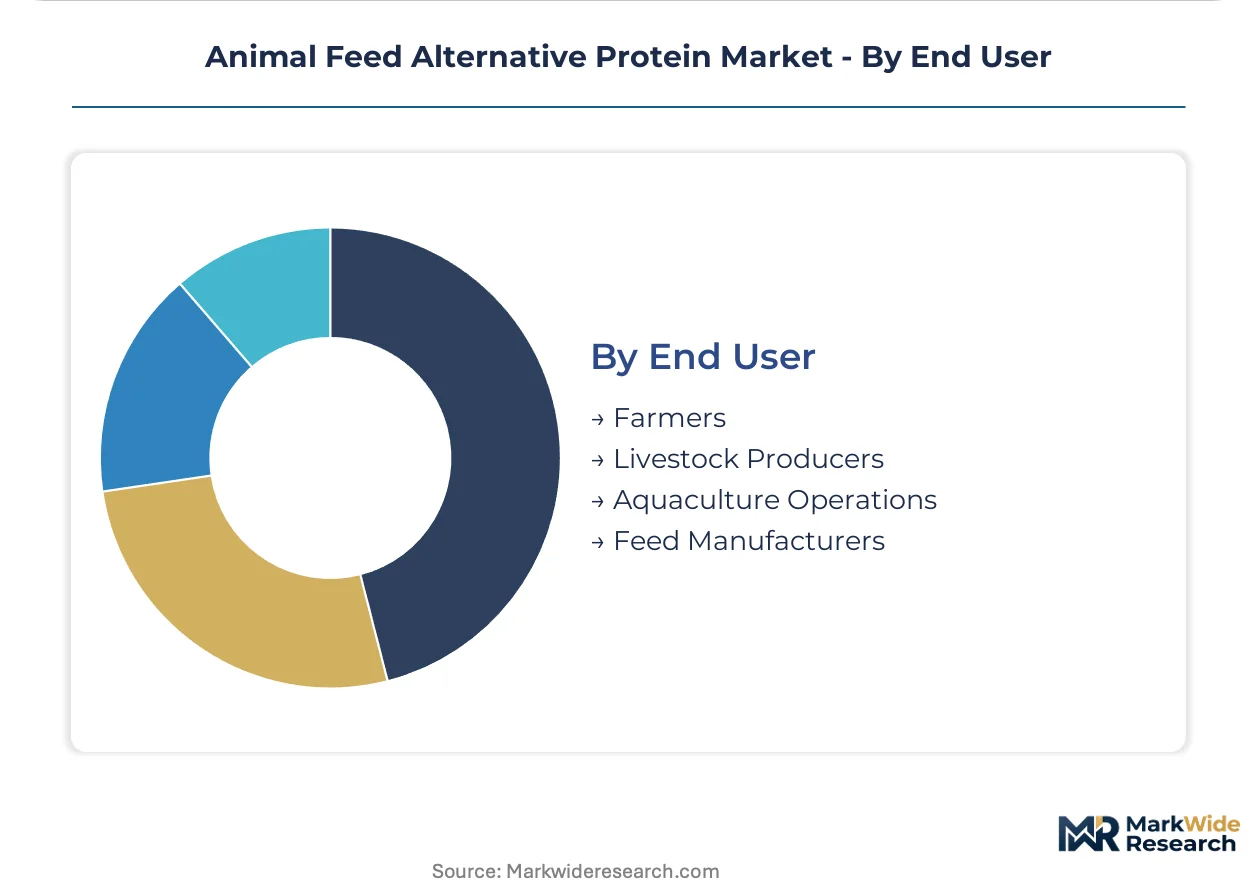
End User:
Procurement scale and technical capability separate volume purchasers from specification influencers. Feed manufacturers intermediate between raw material processors and on-farm consumption.
- Feed Manufacturers:Industrial compounders control formulation decisions and supplier qualification. French and Dutch integrated aquafeed producers are consolidating insect protein offtake to secure marine ingredient substitution compliance.
- Aquaculture Operations:Large salmon and shrimp producers are bypassing compounders for direct protein procurement. Scottish and Norwegian farm groups are investing in captive insect farming capacity.
- Livestock Producers:Intensive pig and poultry operations specify diet composition but purchase through manufacturer channels. Belgian and Dutch broiler integrators are driving pellet formulation adoption.
- Farmers:Smaller-scale ruminant and mixed livestock operations purchase blended feeds with limited alternative protein visibility. Price sensitivity and distributor access constrain direct procurement of novel ingredients.
Procurement authority concentrates in Feed Manufacturers; Aquaculture Operations are deepening direct sourcing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark concentrates insect protein production capacity for European aquafeed supply chains. Dutch compounders process soy alternatives at industrial scale. French retailers enforce marine ingredient caps through procurement specifications.
Denmark
Clustered black soldier fly facilities supply integrated salmon feed producers. The EU Green Deal F-Gas Regulation mandates emission-reduction targets for livestock operations. Kalundborg's industrial symbiosis hub hosts larvae rearing and oil extraction operations serving Norwegian aquaculture.
Netherlands
Intensive poultry and pig operations drive alternative protein formulation demand. EFSA novel food frameworks govern approval timelines for insect meal inclusion. Venlo's feed manufacturing corridor processes soy concentrates and pea protein blends for automated broiler systems.
France
Supermarket chains require documented fishmeal inclusion below 5% in certified salmon. The EU Green Deal shapes labeling requirements for lower-carbon feed inputs. Nantes and Brittany host aquafeed compounders locking in multi-year insect protein offtake agreements.
Norway
Salmonid producers reformulate diets to reduce marine ingredient dependence below 10%. National regulators align with ASC certification standards for traceability documentation. Bergen and Trondheim farming groups invest in captive insect farming capacity for supply security.
United States
Poultry integrators evaluate insect meal for antibiotic-free diet formulations. The EPA regulates effluent standards for insect farming operations. Iowa and North Carolina feed mill clusters retrofit pelleting equipment to handle hygroscopic protein powders.
Animal Feed Alternative Protein Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated compounders controlling formulation decisions and raw material processors supplying ingredient concentrates. The vendor base organizes around three archetypes: global oilseed traders with crushing infrastructure, insect farming specialists with captive rearing operations, and rendering-derived protein processors with animal by-product networks. Capacity expansion and backward integration into upstream raw material production dominate competitive moves as margin pressure intensifies.
Within the oilseed processing tier, Cargill Incorporated and ADM exemplify scale-driven positions anchored to Chicago futures pricing and global crushing footprints. Innova Feed represents the insect protein specialist archetype with French aquafeed supply chain integration. Darling Ingredients occupies the rendering-derived segment with EU animal by-product processing infrastructure.
| Leading Market Players |
|---|
| ADM (Archer Daniels Midland Company) |
| Cargill Incorporated |
| DuPont |
| Innova Feed |
| Roquette Frères |
| Ingredion Incorporated |
| Darling Ingredients |
| Glanbia PLC |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
Entomology and bioprocess engineering talent scarcity in Denmark and the Netherlands widens pricing-tier spreads between premium insect protein and commodity soybean meal, as labor-cost differentials compound with EFSA authorization timelines to stratify procurement economics across compounder tiers.
Pricing Analysis
Volume placements concentrate in soy protein at commodity margins, while insect protein commands premium pricing through ASC certification alignment and marine ingredient substitution compliance. Price differentiation rests on EFSA novel food authorization status and traceability documentation depth, with certified aquafeed producers absorbing 15-30% markups for validated supply agreements. Pricing pressure stems from Chicago Board of Trade futures anchoring baseline costs, forcing novel proteins toward cost parity. Small-scale livestock farmers exhibit highest price sensitivity; Norwegian salmon integrators demonstrate lowest sensitivity due to retailer mandate compliance requirements.
Supply Chain Analysis
Direct-to-compounder channels handle industrial-scale demand from Dutch and Danish feed manufacturers, while direct-to-farm digital platforms serve intensive Belgian poultry operations. Geographic supply concentrates in Denmark, France, and the Netherlands for insect protein infrastructure, with Brazil and Argentina anchoring soy protein flows. Raw material dependencies include black soldier fly larvae substrate, soybean crushing capacity, and rendering-derived animal by-products. Single-source vulnerability concentrates in Darling Ingredients and three European processors controlling EU rendering infrastructure. Distribution runs through integrated aquafeed producers consolidating multi-year offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compounders with validated alternative protein supply chains, as EFSA novel food authorization timelines and toxicology study costs force smaller larval species processors toward acquisition or exit.
For Market Incumbents: To counter margin compression from soymeal price anchoring, Cargill and ADM should deepen backward integration into Brazilian crushing capacity while securing long-term offtake with Danish insect farming clusters. Certification investment in ASC and BAP alignment offers defensive positioning against retailer procurement mandates. For New Entrants and Emerging Players: Launch via direct-to-farm digital channels targeting Brazilian cattle feed underpenetration, where deforestation-linked soy pressure creates procurement receptivity for novel proteins. Precision fermentation amino acids integrated with corn ethanol infrastructure offer regulatory bypass pathways absent whole-protein EFSA timelines. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated insect protein specialists given EU Green Deal F-Gas Regulation tightening emission-reduction targets across livestock supply chains. Long-term viability favors archetypes with captive rearing, automated fractionation, and Norwegian aquafeed offtake lock-in. Watch for French supermarket chain procurement specification tightening below 5% fishmeal inclusion as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Larvae Substrate Supply | Cargill's oilseed processing footprint anchors cost control over black soldier fly rearing inputs. |
| EFSA Novel Food Authorization Investment | Innova Feed's dossier completion secures multi-year supply agreements with French aquafeed compounders. |
| Automated Fractionation Capacity Expansion | Kalundborg's industrial symbiosis hub collapses insect meal production costs below four-year payback thresholds. |
| Direct-to-Farm Digital Channel Launch | Dutch broiler integrators bypass distributor markups through automated feed ordering platforms. |
| ASC Certification Alignment Program | Norwegian salmon producers satisfy retailer traceability documentation that legacy protein suppliers cannot provide. |
Methodological Framework
Trade databases, EFSA novel food submission records, and aquafeed formulation specifications formed the secondary backbone, supplemented by primary interviews with feed compounder procurement directors, insect farming operations managers, EFSA regulatory affairs specialists, and Norwegian salmon producer sustainability officers. Bottom-up volume triangulation across product type, application, and form factor segments converged with top-down macroeconomic anchoring.
Historical trendline analysis of soymeal futures volatility and insect protein production cost curves informed the projection framework across the analysis window. Segmentation modeling incorporated product chemistry, species-specific digestive physiology, physical form handling characteristics, and procurement scale intensity. CAGRs derived from capacity expansion announcements, offtake agreement volumes, and regulatory approval timeline probabilities.
EFSA authorization delays, soymeal price volatility spikes, and rendering capacity concentration are the dominant revision risks to forecast outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Level Measuring Instrument Market
Others
Latin America Fire Sprinklers Market
Others
Video Paas Market
Others
Metaverse Market
Others
Global Transparent Plastics Market
Others
Europe Polycarbonate Sheets Market
Others
Global Mobile Gambling Market
Others
Snus Market
Others
Global ESD Protection Devices Market
Others
Ultra Mobile Devices (UMD) Market
Others
Bio-Based Leather Market
Others
North America Enterprise Video Market
Others
United States Bean Bags Market
Others
Molybdenum-99 Market
Others
Cat Food Market
Others
Edge Computing in Healthcare Market