
 North America Luxury Car Market | 2026-2036
North America Luxury Car Market Size, Share, and Industry Trends Forecast 2026-2036
North America Luxury Car Market Analytics
The North America luxury car market is restructuring around a sharp divergence between battery-electric flagship platforms and legacy internal-combustion volume models, with powertrain architecture now the primary tier separator rather than cabin size alone. Mercedes-Benz USA leverages its captive battery supply chain to secure allocation priority for the EQS and EQE lines. BMW of North America anchors its position through dual-architecture manufacturing flexibility across Spartanburg and Mexico. Tesla dominates direct-to-consumer channel control and over-the-air revenue streams that traditional dealers cannot replicate.
North America luxury cars comprise passenger vehicles engineered to premium material, performance, and comfort specifications, typically incorporating aluminum-intensive body structures, adaptive air suspension systems, and cabin noise suppression below 60 decibels at highway speeds; their commercial purpose centers on status signaling, driver assistance technology access, and superior occupant experience for affluent buyers. SUV configurations now lead volume across all price bands as ride height and cabin flexibility displace sedan preference among individual buyers and corporate clients. Electric powertrains represent the fastest-expanding segment, though hybrid variants retain margin strength where charging infrastructure remains sparse. Entry-level luxury pricing faces compression from mainstream brand upward extension, while ultra-premium tiers concentrate margin pools in limited-production coachbuilt variants.
EPA Corporate Average Fuel Economy standards and California Air Resources Board zero-emission mandates directly shape powertrain development timelines and regional sales mix, forcing manufacturers to maintain compliance credit portfolios or face market access restrictions. NHTSA safety rating protocols and the US Inflation Reduction Act's domestic assembly and battery sourcing requirements further constrain product planning and cost structures. Stakeholders must monitor how rapidly Canadian federal and provincial ZEV incentives converge with US IRA provisions to determine whether North American production integration or cross-border tariff exposure becomes the decisive competitive variable.
Market Dynamics
EPA tailpipe standards and California Air Resources Board zero-emission mandates are compressing powertrain development timelines, forcing manufacturers to reallocate engineering resources from internal-combustion refinement to battery-electric platform scaling while maintaining profitability on legacy architectures.
Growth Catalysts
- US Inflation Reduction Act domestic assembly credits:The IRA's battery sourcing and assembly location requirements accelerate North American production investment, creating captive supply chain advantages for qualifying manufacturers.
- Corporate fleet electrification mandates:Technology and financial services firms in California and Ontario are rewriting procurement policies to prioritize battery-electric executive transport, generating volume commitments that de-risk platform development.
- Silicon carbide power electronics:Widespread adoption of SiC inverters and onboard chargers extends electric range while reducing charging times, addressing range anxiety barriers among affluent suburban buyers.
Market Restraints
- Lithium carbonate price volatility:Battery cell input costs fluctuate with South American brine extraction capacity constraints, compressing margin visibility for multi-year platform planning.
- Charging infrastructure deserts:Rural interstate corridors and secondary Canadian highways lack 350kW fast-charging density, limiting electric powertrain penetration outside coastal metropolitan clusters.
- NHTSA autonomous vehicle regulatory uncertainty:Delayed federal standards for Level 3+ hands-free operation force manufacturers to maintain redundant manual controls, adding cost and complexity.
Strategic Opportunities
- Subscription-based feature access:Over-the-air activation of heated seats, enhanced acceleration, and driver assistance tiers creates recurring revenue streams independent of initial vehicle transactions.
- Mexico manufacturing integration:Proximity to USMCA-compliant battery assembly and aluminum stamping capacity offers tariff-advantaged export positioning to Canadian and US markets.
- Second-life battery energy storage:Retired electric vehicle packs from California and Texas fleets are repurposing into residential and commercial stationary storage, capturing circular economy value.
Industry Challenges
- Software-defined vehicle talent scarcity:Competition for embedded systems engineers and cloud infrastructure architects with technology firms drives compensation inflation and recruitment timelines.
- Dealer franchise law compliance:Direct-to-consumer sales restrictions in multiple US states force parallel channel maintenance, duplicating customer acquisition costs and service infrastructure.
- Multi-architecture manufacturing complexity:Simultaneous production of internal-combustion, hybrid, and battery-electric variants on shared assembly lines strains quality control and inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Luxury Car Market |
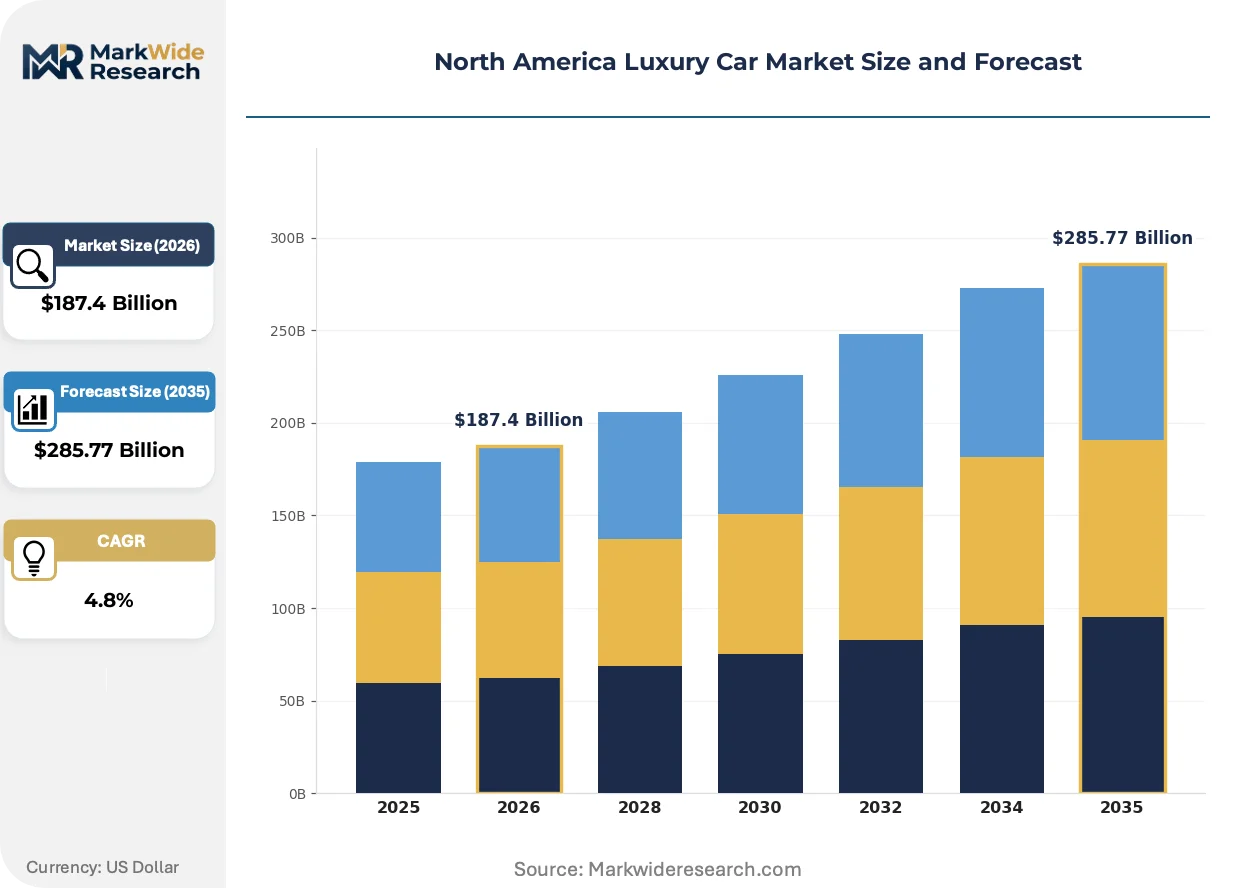
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Coupe, Convertible Powertrain: Petrol, Diesel, Hybrid, Electric Customer Type: Individual Buyers, Fleet Owners, Luxury Rentals, Corporate Clients Price Range: Entry-Level, Mid-Range, Premium, Ultra-Premium |
| Companies Covered | Mercedes-Benz USA, BMW of North America, Audi of America, Lexus, Porsche Cars North America, Jaguar Land Rover North America, Tesla, Volvo Car USA, Cadillac, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Luxury Car Market Evolving Landscape
Software-defined architectures and solid-state battery prototyping are converging to redefine how luxury vehicles generate revenue, shifting value capture from hardware transactions to continuous service relationships and performance upgrades delivered remotely.
800-volt electrical architectures are unifying powertrain, thermal management, and charging subsystems under unified high-voltage rails. Premium manufacturers are adopting these platforms for flagship electric SUVs and sedans targeting technology corridor buyers. This voltage standardization is unifying component sourcing strategies and compressing development cycle timelines across vehicle programs.
The US Inflation Reduction Act's domestic content requirements are restructuring battery supply chain geography, compelling cell manufacturers to establish North American cathode and separator production. Industrial consequence includes accelerated joint ventures between automakers and mining interests for lithium and nickel offtake agreements. Battery-electric luxury crossovers and full-size SUVs face the tightest compliance timelines as they absorb the highest cell volumes.
Direct-to-consumer digital retailing is displacing traditional dealership intermediation among electric-native brands, forcing established manufacturers to deploy agency sales models in select states. Franchise dealers in California, Texas, and Florida are restructuring compensation structures to accommodate fixed pricing and remote delivery handovers. This channel evolution is most visible in metropolitan markets where affluent buyers prioritize configuration transparency and minimal negotiation friction.
North America Luxury Car Market Segmentation
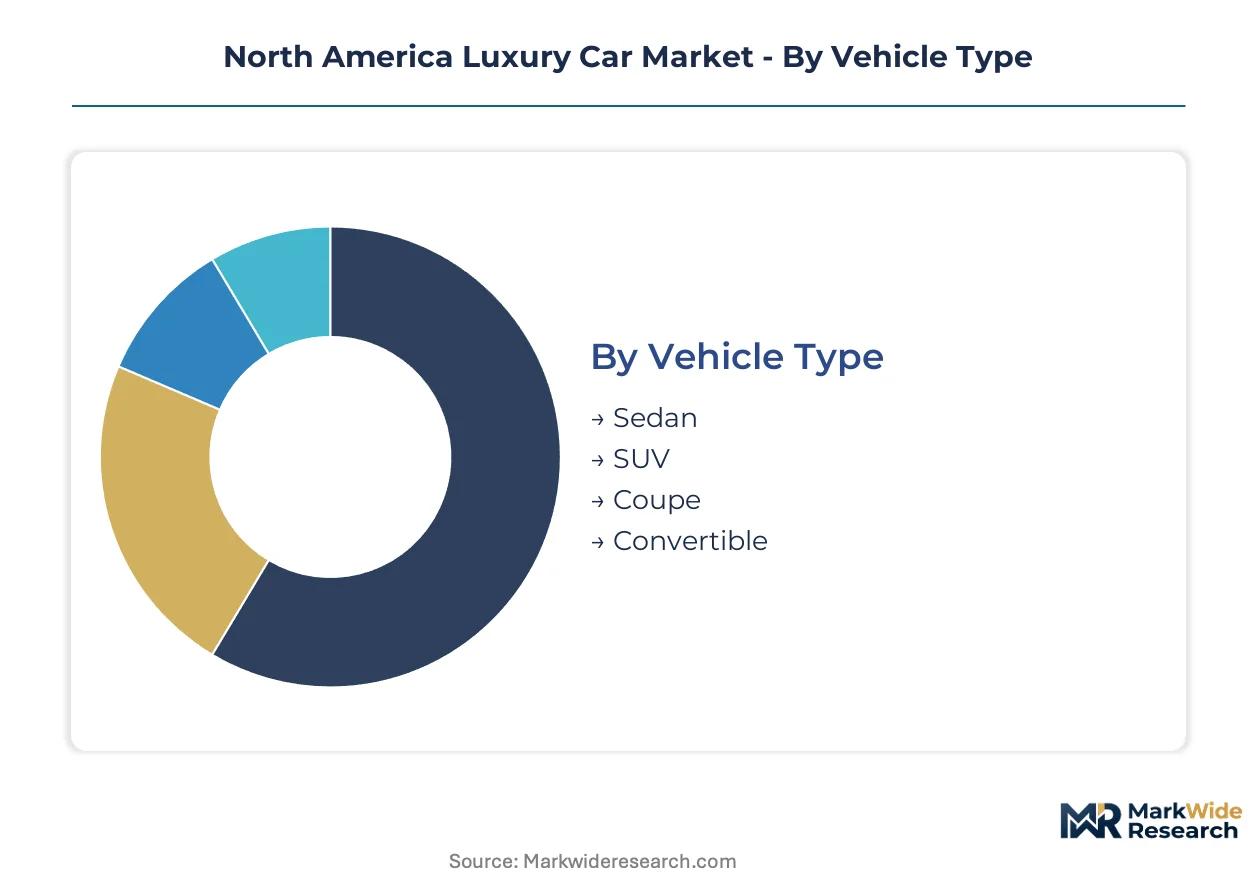
Segmentation in the North America luxury car market reveals how powertrain electrification and SUV preference are redrawing competitive boundaries faster than traditional price-tier or body-style classifications. Manufacturers now configure platform strategies around customer archetype and charging infrastructure access rather than assuming uniform upgrade paths across vehicle categories.
Vehicle Type:
The customization-standardization spectrum spans from coachbuilt limited editions to mass-produced modular platforms, with body style increasingly decoupled from price positioning as electric architectures enable cabin flexibility.
- Sedan:Aluminum-intensive unibody construction with adaptive air suspension prioritizes aerodynamic efficiency and highway noise suppression below 60 decibels. Demand concentrates in California's technology corridor where range optimization matters more than ride height; EPA fuel economy credits sustain engineering investment despite volume contraction.
- SUV:Dominant volume segment across all price bands as elevated seating position and configurable cargo space displace sedan preference among individual buyers and corporate fleet clients. Greater Toronto Area high-net-worth density supports sustained premium SUV turnover despite higher battery cell requirements.
- Coupe:Low-roof two-door configurations emphasize chassis rigidity and weight distribution for enthusiast positioning.
- Convertible:Soft-top and retractable hardtop variants target seasonal markets in Florida and Southern California with acoustic engineering challenges.
Leading the category by volume: SUV. Growing fastest: Electric SUV derivatives.
Powertrain:
Cost tier separation now runs from compliance-focused mild hybrids to flagship battery-electric platforms with 800-volt architectures and silicon carbide inverters.
- Petrol:Twin-turbocharged inline-six and V8 configurations retain margin strength in Texas and Mountain West regions where charging infrastructure remains sparse. BMW of North America maintains dual-architecture manufacturing flexibility at Spartanburg to serve this demand pool.
- Electric:Battery-electric platforms with unified high-voltage thermal management and 350kW charging capability represent the steepest expansion trajectory. California Air Resources Board zero-emission mandates and US Inflation Reduction Act domestic assembly credits accelerate platform development.
- Diesel:Compression-ignition variants persist in heavy-duty SUV applications for towing capacity.
- Hybrid:Plug-in and full-hybrid systems bridge infrastructure gaps in secondary Canadian highway corridors.
Dominant by installed base: Petrol. Climbing the fastest: Electric.
Customer Type:
Volume concentration varies from individual transaction economics to multi-year fleet procurement contracts with electrification mandates embedded.
- Corporate Clients:Technology and financial services firms in California and Ontario are rewriting procurement policies to prioritize battery-electric executive transport, generating volume commitments that de-risk platform development for manufacturers. These fleet mandates carry tighter EPA compliance timelines than individual buyer conversion.
- Individual Buyers:Affluent suburban purchasers in metropolitan clusters prioritize configuration transparency and minimal negotiation friction, accelerating direct-to-consumer channel displacement of traditional dealership intermediation.
- Fleet Owners:Rental and livery operators focus on residual value predictability and service network density.
- Luxury Rentals:Short-term premium vehicle access providers concentrate in Miami, Las Vegas, and Los Angeles tourism corridors.
Largest transaction volume: Individual Buyers. Fastest policy-driven conversion: Corporate Clients.
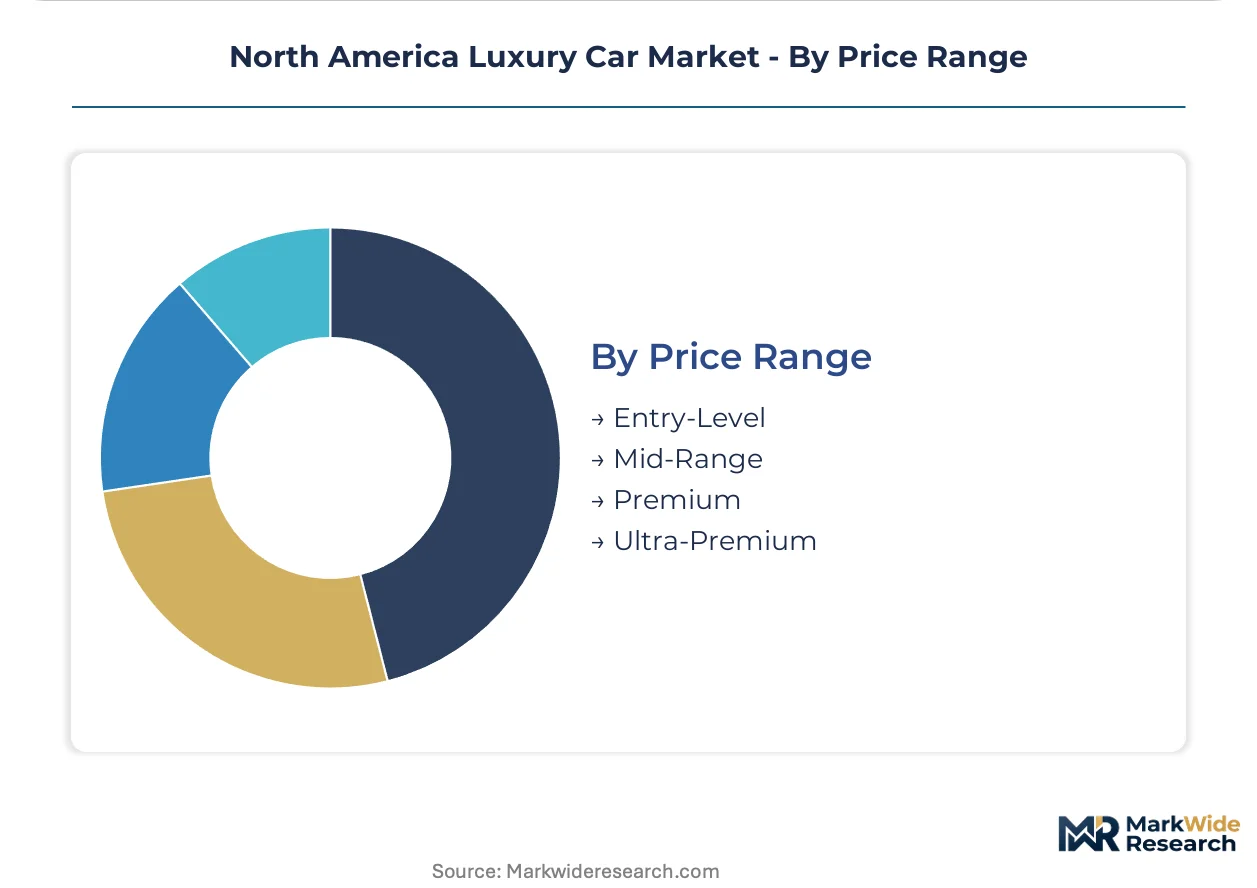
Price Range:
Margin architecture separates mass-premium scale economics from ultra-premium limited production with component commonality decreasing as price ascends.
- Mid-Range:Volume luxury segment facing compression from mainstream brand upward extension while defending position through technology feature bundling and subscription-based over-the-air revenue streams. This tier absorbs the highest engineering amortization per unit across multi-architecture manufacturing lines.
- Ultra-Premium:Coachbuilt and limited-production variants concentrate margin pools with aluminum-intensive body structures and bespoke interior material specifications. Canadian provincial zero-emission vehicle mandates penetrate this segment fastest due to buyer price elasticity.
- Entry-Level:Compact luxury positioning battles mainstream brand incursion.
- Premium:Full-size flagship configurations anchor brand technology demonstration.
Highest absolute margin: Ultra-Premium. Gaining share fastest: Mid-Range electric variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's technology corridor anchors North American luxury car demand concentration, with the San Francisco Bay Area and Los Angeles Basin generating disproportionate electric vehicle adoption rates among affluent technology sector employees.
United States
Corporate fleet buyers in Silicon Valley and Manhattan are accelerating battery-electric procurement as the US Inflation Reduction Act's domestic assembly credits reshape platform development timelines. EPA tailpipe standards and California Air Resources Board zero-emission mandates force manufacturers to maintain compliance credit portfolios or face market access restrictions. Texas maintains internal-combustion volume strength where charging infrastructure remains sparse.
Canada
The Greater Toronto Area's high-net-worth density supports sustained premium SUV turnover despite higher battery cell requirements. Provincial zero-emission vehicle mandates in British Columbia and Quebec penetrate the ultra-premium segment fastest due to buyer price elasticity. Ontario's technology corridor generates corporate fleet electrification commitments that de-risk manufacturer platform development.
Mexico
USMCA-compliant battery assembly and aluminum stamping capacity in Nuevo León and the Bajío Region offers tariff-advantaged export positioning to Canadian and US markets. Proximity to North American cathode production joint ventures accelerates cell manufacturing localization. Mexico's manufacturing integration captures circular economy value through second-life battery repurposing.
North America Luxury Car Market Competitive Landscape
Premium-margin players sit above commodity-margin players across powertrain architecture sophistication, with battery-electric platform control now the decisive tier separator. The vendor base concentrates around three strategic archetypes: captive battery supply chain operators, dual-architecture manufacturing specialists, and direct-to-consumer channel natives. Dominant competitive moves include strategic partnerships for lithium offtake agreements and vertical integration into silicon carbide power electronics production.
Among Germany-based manufacturers, Mercedes-Benz USA and BMW of North America exemplify the dual-architecture specialist archetype, balancing internal-combustion refinement with battery-electric platform scaling. Tesla occupies a distinct position as the direct-to-consumer channel native, with control over over-the-air revenue streams that traditional dealer structures cannot replicate. These three anchors illustrate how powertrain transition timelines and distribution model innovation now determine competitive positioning more than legacy brand equity alone.
| Leading Market Players |
|---|
| Mercedes-Benz USA |
| BMW of North America |
| Audi of America |
| Lexus |
| Porsche Cars North America |
| Jaguar Land Rover North America |
| Tesla |
| Volvo Car USA |
| Cadillac |
| Others |
Value Network & Pricing Analysis
Embedded software engineering talent concentration in California's technology corridor feeds directly into labor-cost differentials that widen pricing-tier spreads between battery-electric flagships and legacy internal-combustion volume models. Manufacturers competing for silicon carbide power electronics specialists and cloud infrastructure architects face compensation inflation that concentrates in premium vehicle program development costs.
Pricing Analysis
Value-based pricing anchored to total cost of ownership and charging infrastructure access now dominates battery-electric platform positioning. Three-tier pricing structure across premium, standard, and economy levels separates flagship 800-volt architectures from mid-range hybrid variants and entry-level compliance models. Price differentiation rests on silicon carbide inverter specification and domestic assembly qualification under US Inflation Reduction Act provisions. Cost compression in entry-luxury tiers is intensifying because mainstream brand upward extension erodes segment boundaries. Corporate fleet buyers in California and Ontario exhibit lowest price sensitivity; individual suburban purchasers in charging infrastructure deserts show highest elasticity.
Supply Chain Analysis
US Inflation Reduction Act domestic content certification gates cell manufacturer participation in qualifying vehicle programs. Geographic supply concentration spans China, South Korea, and emerging North American cathode production joint ventures. Raw material dependencies center on lithium carbonate from South American brine operations, nickel laterite from Indonesian processing facilities, and cobalt hydroxide from Central African copper belt sources. Single-source vulnerability in 350kW fast-charging hardware creates chokepoint exposure for flagship electric SUV ramp schedules. Distribution runs through captive battery supply chain operators and dual-architecture manufacturing specialists with Mexico assembly integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America luxury car market functions as a vertical-integration race where captive control over silicon carbide power electronics and lithium offtake agreements determines margin capture. Players securing upstream battery mineral commitments and downstream over-the-air revenue infrastructure build sustainable competitive moats.
For Market Incumbents: Hedge against direct-to-consumer channel displacement by restructuring dealer franchise compensation in California, Texas, and Florida to accommodate fixed pricing and remote delivery handovers. Accelerate backward integration into North American cathode production through joint ventures with mining interests for lithium and nickel offtake agreements. Battery-electric platform development timelines compress faster than legacy architecture profitability can sustain without captive supply chain control. For New Entrants and Emerging Players: The price-point gap between ultra-premium coachbuilt variants and mid-range electric derivatives offers white-space targeting for technology-native brands with software-defined vehicle architectures. Corporate fleet procurement in Ontario's technology corridor presents the most penetrable demand pool given electrification mandate velocity exceeding individual buyer conversion curves. A direct-to-consumer digital retailing go-to-market angle bypasses dealer franchise law compliance costs that burden established manufacturers. For Investors and Strategic Acquirers: Re-rating potential sits with dual-architecture manufacturing specialists given IRA domestic assembly credit qualification and Mexico tariff-advantaged export positioning. Long-term viability over a five-to-ten-year window favors players with unified high-voltage platform control spanning powertrain, thermal management, and charging subsystems. The signal to watch as inflection indicator is convergence between Canadian provincial ZEV incentives and US IRA provisions determining cross-border production integration versus tariff exposure calculus.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive lithium and nickel offtake secures IRA domestic content qualification for flagship electric SUV programs. |
| Software-Defined Vehicle Investment | Over-the-air revenue streams create recurring income independent of initial vehicle transactions in California metropolitan clusters. |
| Geographic Manufacturing Footprint | Mexico assembly integration captures USMCA-compliant tariff advantages for Canadian and US market export positioning. |
| Charging Infrastructure Partnership | 350kW fast-charging density expansion addresses range anxiety barriers among affluent suburban buyers in secondary highway corridors. |
| Platform Standardization | 800-volt electrical architecture unification compresses development cycle timelines across sedan and SUV vehicle programs. |
Research Methodology
Document review covered vehicle production databases, IHS Markit registration data, EPA compliance filings, and US Inflation Reduction Act domestic content guidance, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, dealership operations managers, and corporate fleet procurement directors. Secondary validation drew from California Air Resources Board zero-emission vehicle mandate documentation, Canadian provincial ZEV incentive program specifications, and NHTSA safety rating protocols. Bottom-up segment sizing and top-down market reconciliation ensured analytical triangulation.
Historical volume trajectories were cross-referenced against expert panel input regarding powertrain transition timelines and charging infrastructure deployment curves. Segmentation modeling spanned vehicle class, propulsion architecture, customer type, and regional production cluster across the projection horizon. CAGRs were derived from slope analysis of technology adoption curves and regulatory compliance deadline impacts. Forecast inputs incorporated silicon carbide inverter penetration rates and lithium carbonate price volatility assumptions.
Underlying measurement precision varies by segment; battery-electric platform forecasts carry tighter precision than hybrid transition volume projections given policy mandate visibility. Forecasts reflect assumptions regarding EPA tailpipe standard enforcement consistency and USMCA tariff regime stability. A model refresh is warranted upon material change in Canadian federal ZEV incentive convergence with US IRA domestic assembly provisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
DIY Smart Home Market
Others
Running Apparel Market
Others
Global Learning Analytics Market
Others
Bakery Packaging Market
Others
Triathlon Clothing Market
Others
Asia Pacific Automotive LED Lighting Market
Others
Football Sportswear Market
Others
Channel-In-A-Box (Ciab) Market
Others
Cat Food Market
Others
Duckweed Market
Others
Global Process Equipment Market
Others
Lepidolite Market
Others
Global Crowdsourced Testing Market
Others
Safety Instrumented System (SIS) Market
Others
Middle East Smart Home Market
Others
Nutricosmetics Market