
 Global Multi Domain Controller Market | 2026-2036
Global Multi Domain Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multi Domain Controller Market Intelligence
The modularization of controller hardware and software components is broadening the addressable market for system integrators. NXP Semiconductors N.V. leverages its portfolio in secure connectivity to target network controller applications. Robert Bosch GmbH competes on its system integration expertise for industrial automation. Continental AG positions its solutions for advanced networking within smart city infrastructure projects.
A multi-domain controller is a centralized computing platform designed to consolidate functions across disparate operational domains, often using high-performance multi-core processors. Its primary purpose is to simplify system architecture and reduce latency in environments like data centers. The adoption of Software-Defined Networking (SDN) and Network Functions Virtualization (NFV) technologies is fundamental to market expansion. Among applications, telecommunications and data centers represent the largest segments, with industrial automation showing significant uptake.
Regulatory frameworks like the EU's GDPR and standards from the US's FCC influence controller design, mandating robust security features. In China, MIIT directives for telecommunications infrastructure drive demand for certified hardware. These rules shape market access and product specifications. Consequently, stakeholder success depends on navigating the strategic choice between proprietary, integrated systems and open, disaggregated hardware and software solutions.
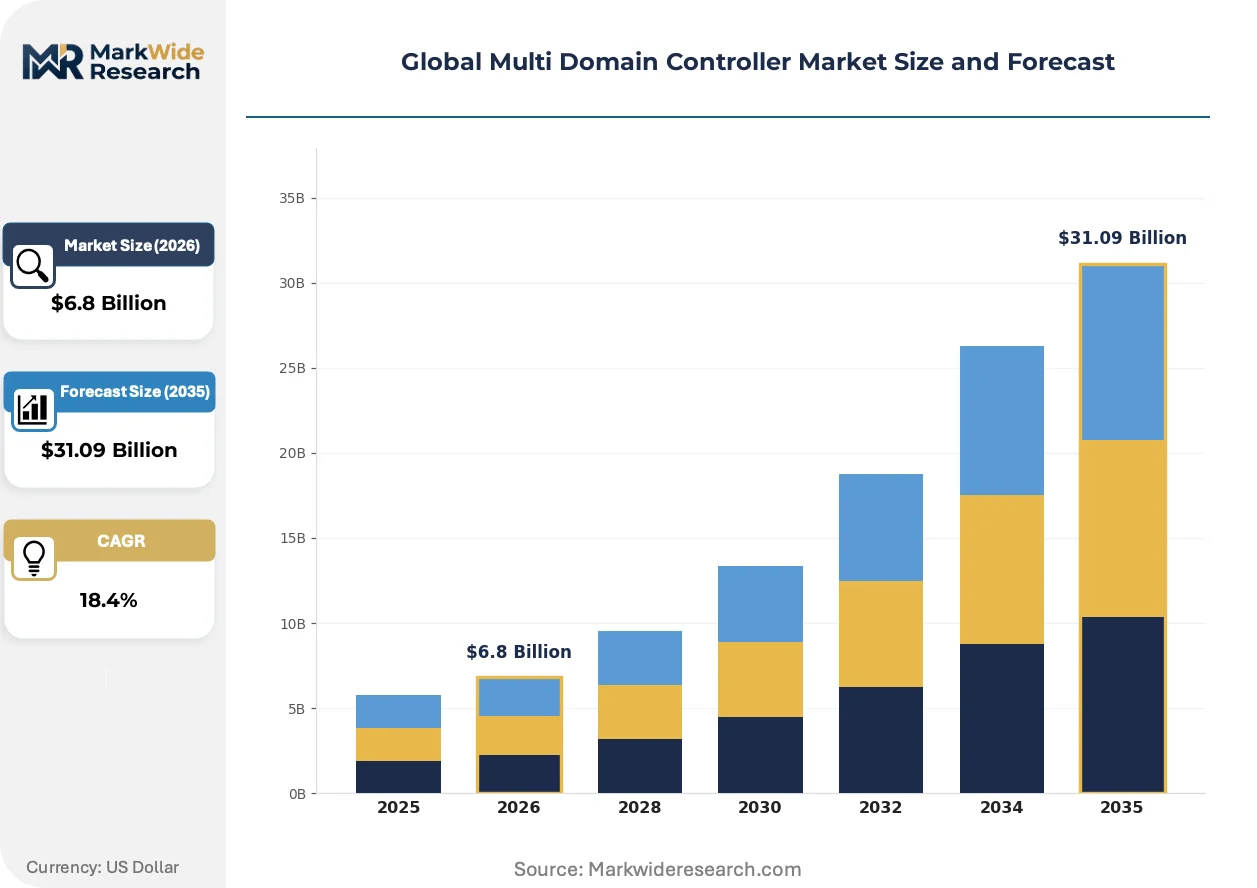
Market Dynamics
The central dynamic shaping the market is the architectural transition toward software-defined infrastructure. This fundamental shift, driven by the adoption of SDN and NFV in telecommunications and data centers, necessitates centralized computing platforms to manage increasingly complex and virtualized network functions.
Growth Catalysts
- 5G Infrastructure Rollouts:Massive network deployments, particularly in China and South Korea, require high-performance controllers to manage the increased data traffic and low-latency communication demands of new services.
- Data Center Modernization:The expansion of hyperscale data centers is creating demand for controllers that can simplify network architecture, automate resource allocation, and reduce operational complexity through centralized management.
- Industrial Automation:The adoption of Industry 4.0 principles in manufacturing environments in Germany and Japan drives the need for controllers that can consolidate functions from operational technology and information technology domains.
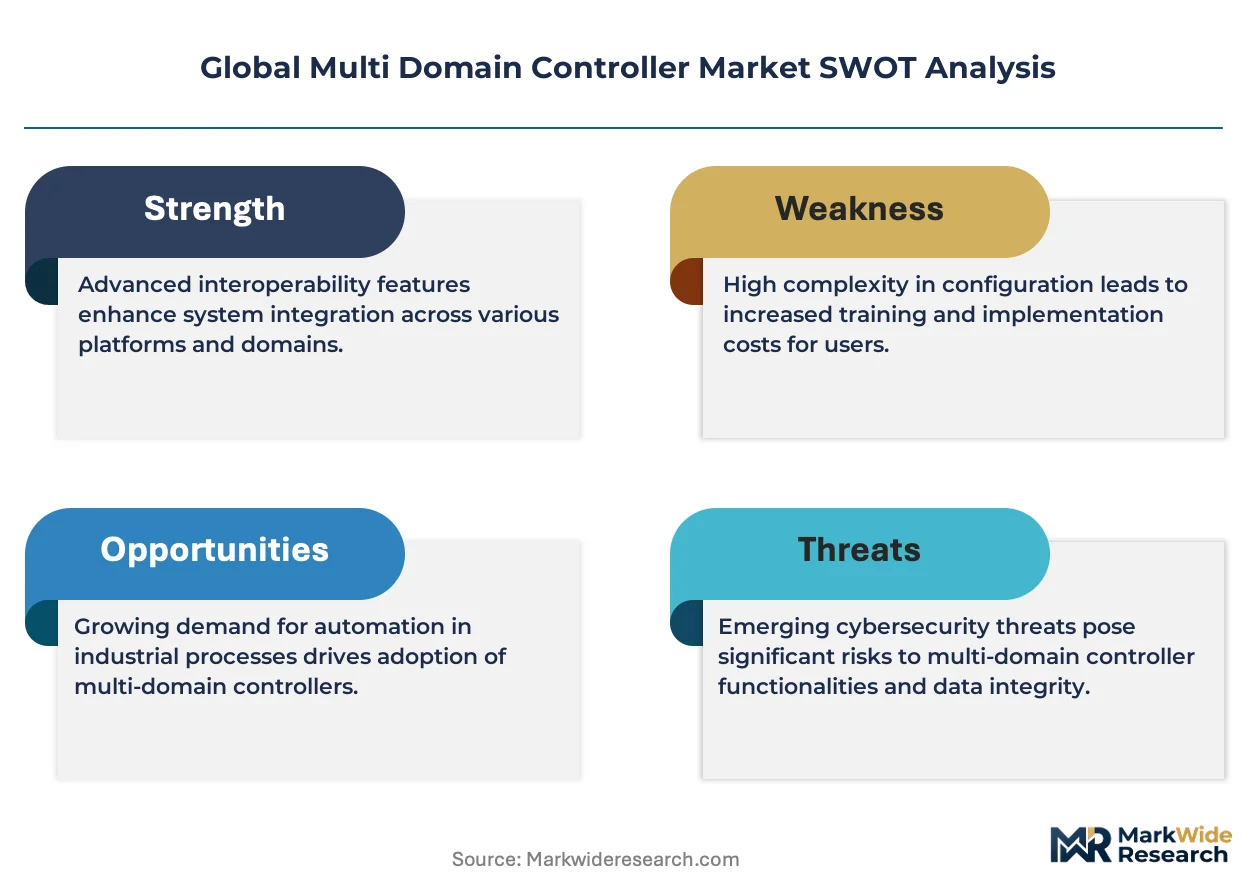
Market Restraints
- High Development and Integration Costs:The significant capital investment required for high-performance multi-core processors and the complexity of integrating controllers with legacy industrial or telecom systems act as barriers to adoption.
- Software Stack Complexity:Developing and validating the sophisticated software, including hypervisors and real-time operating systems, needed to run multiple critical functions on a single platform is a major technical hurdle.
- Security Vulnerabilities:The centralization of control functions creates a single, high-value target for cyberattacks, requiring extensive and costly security measures that can deter implementation in risk-averse sectors.
Strategic Opportunities
- Edge Computing Applications:Deploying multi-domain controllers at the network edge offers a new market for managing localized data processing in applications like smart city infrastructure and connected mobility solutions.
- Open Source Hardware and Software:The move toward open standards and disaggregated systems allows new vendors to provide specialized hardware or software components, expanding the ecosystem beyond vertically integrated incumbents.
- Regulatory-Driven Security Features:Mandates like the EU's NIS 2 Directive, which heightens cybersecurity requirements for critical infrastructure, create opportunities for controllers with certified, hardware-level security.
Industry Challenges
- Interoperability and Standardization:A lack of universally accepted standards for communication between controllers and the network elements they manage can lead to vendor lock-in and complicate multi-vendor deployments.
- Specialized Talent Shortage:The market faces a scarcity of engineers with combined expertise in embedded systems, networking protocols, and virtualization technologies, which slows down product development and implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multi Domain Controller Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Controller Type: Network Controller, Storage Controller, Security Controller, Traffic Controller, Access Controller Technology: SDN, NFV, Cloud-native, Virtualization, Edge Computing Application: Telecommunications, Data Centers, Smart Cities, Industrial Automation, Energy Management End User: Telecom Operators, Hyperscale Data Centers, Public Sector Agencies, Manufacturing Firms, Utilities |
| Companies Covered | ZF Friedrichshafen AG, Denso Corporation, Robert Bosch GmbH, Visteon Corporation, Panasonic Corporation, Continental AG, Magna International Inc., NXP Semiconductors N.V., Aptiv PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multi Domain Controller Market Strategic Shifts & Innovations
The market is defined by a push towards software abstraction, where controller functionality is increasingly decoupled from the underlying hardware. This enables greater flexibility and customization, allowing operators to deploy best-of-breed solutions rather than being locked into single-vendor ecosystems.
Heterogeneous computing architectures, which combine different types of processing cores on a single System-on-Chip (SoC), are becoming standard. Hyperscale data center operators and telecom equipment manufacturers are rapidly adopting these SoCs to handle diverse workloads efficiently. This trend is modularizing the controller platform, separating the hardware compute layer from the software-defined control and application layers, which dismantles the traditional integrated-system model.
Policy frameworks focused on digital sovereignty and critical infrastructure protection are influencing design and sourcing. For instance, the EU AI Act and cybersecurity certification schemes are compelling manufacturers to build in auditable security and data governance features from the ground up. This affects controller vendors targeting European telecommunications and public sector clients, who must now demonstrate compliance to secure market access.
A notable behavioral shift involves enterprise and telecom buyers moving from long-term, monolithic procurement contracts to more flexible, consumption-based models. The traditional approach of purchasing integrated hardware and software bundles is being challenged by disaggregated sourcing, where buyers acquire components separately. This pattern is most visible in the North American data center market, where cloud service providers prioritize vendor diversity and software-defined control.
Global Multi Domain Controller Market Segmentation
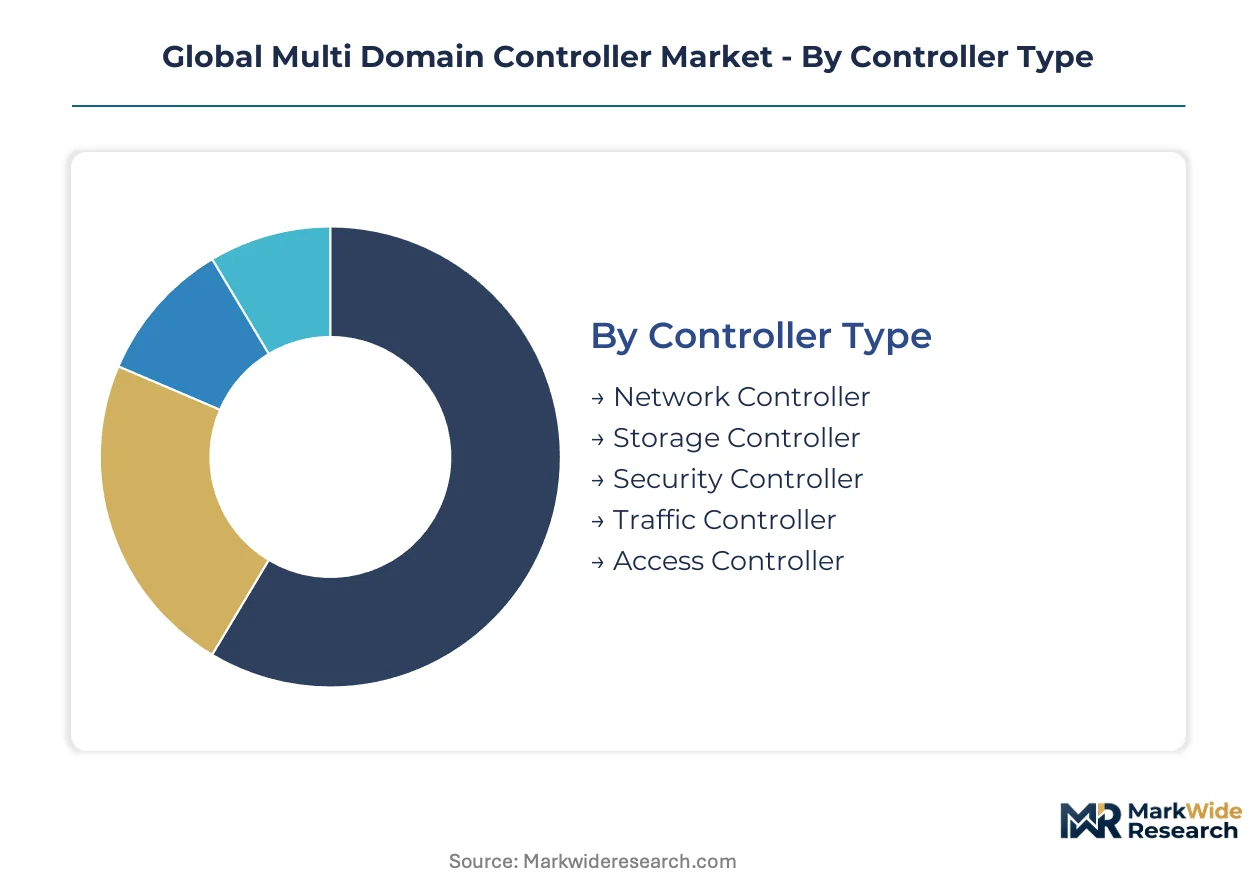
The Multi Domain Controller market segments into distinct categories, reflecting the diverse operational requirements and technological advancements driving its expansion. Understanding these segments is crucial for identifying areas of concentrated demand and specialized solution development across various industry verticals. Each segment addresses specific challenges in network management, data processing, or security enforcement.
Controller Type:
The market for multi-domain controllers shows a clear split between high-volume foundational controllers and specialized premium solutions addressing specific functions.
- Network Controller:These platforms provide centralized management and orchestration for complex network infrastructures, often leveraging SDN and NFV principles. Demand concentrates heavily in telecommunications for 5G rollouts and hyperscale data centers seeking enhanced network virtualization and automation.
- Security Controller:Designed for enforcing security policies, detecting threats, and managing access across disparate domains, these controllers offer robust protection for critical assets. Their adoption is particularly strong in sectors subject to stringent regulatory frameworks like the EU's NIS 2 Directive, which mandates heightened cybersecurity for critical infrastructure.
- Storage Controller:These optimize data flow and management within storage area networks and distributed storage systems, crucial for performance in hyperscale data centers.
- Traffic Controller:Focused on managing and optimizing data traffic flows, these are essential for maintaining quality of service in telecom networks and smart city infrastructure.
- Access Controller:These manage user authentication, authorization, and device access across enterprise networks and industrial IoT deployments, ensuring secure entry points.
Today's leader: Network Controller. Tomorrow's challenger: Security Controller.
Technology:
Technological differentiation drives competitive advantage within the multi-domain controller market, influencing capabilities and deployment models.
- SDN:Software-Defined Networking decouples the control plane from the data plane, enabling programmable and centralized network management. Telecommunications operators and large data centers widely adopt SDN for network agility and automation.
- Edge Computing:This technology brings computation and data storage closer to the data source, reducing latency and bandwidth usage. Smart city infrastructure and connected mobility solutions increasingly rely on edge controllers for real-time localized data processing.
- NFV:Network Functions Virtualization abstracts network functions from proprietary hardware, allowing them to run as software on standard servers. Telecom operators utilize NFV to reduce operational costs and accelerate service deployment.
- Cloud-native:Architectures built on microservices, containers, and serverless functions enable highly scalable and resilient controller deployments. Hyperscale data centers and public sector agencies leverage cloud-native approaches for flexible infrastructure.
- Virtualization:This technology creates virtual versions of computing resources, including servers, storage, and networks, consolidating hardware and improving resource utilization. Enterprise IT environments and data centers widely employ virtualization for efficiency.
SDN currently exhibits the steepest expansion trajectory due to its foundational role in modern network architectures.
Application:
The application landscape for multi-domain controllers highlights the diverse operational environments benefiting from centralized control and automation.
- Telecommunications:Multi-domain controllers orchestrate complex network functions, manage traffic, and ensure service delivery across 5G and fiber optic infrastructures. Massive 5G rollouts in China and South Korea significantly drive this segment's demand for high-performance controllers.
- Data Centers:These platforms simplify network architecture, automate resource allocation, and reduce operational complexity in large-scale data facilities. The expansion of hyperscale data centers globally creates substantial demand for controller solutions.
- Smart Cities:Controllers manage interconnected urban infrastructure, including traffic systems, public safety, and utility networks, enhancing efficiency and citizen services. Projects in cities like Singapore and London integrate these controllers for comprehensive urban management.
- Industrial Automation:Controllers consolidate functions from operational technology and information technology domains in manufacturing environments, supporting Industry 4.0 initiatives. German and Japanese manufacturing firms are significant adopters for advanced factory automation.
- Energy Management:These systems optimize power grids, manage renewable energy integration, and enhance the efficiency of smart utility networks. Utilities deploy multi-domain controllers for grid modernization and demand-side management.
Telecommunications and Data Centers represent the largest revenue concentration within the application segment.
End User:
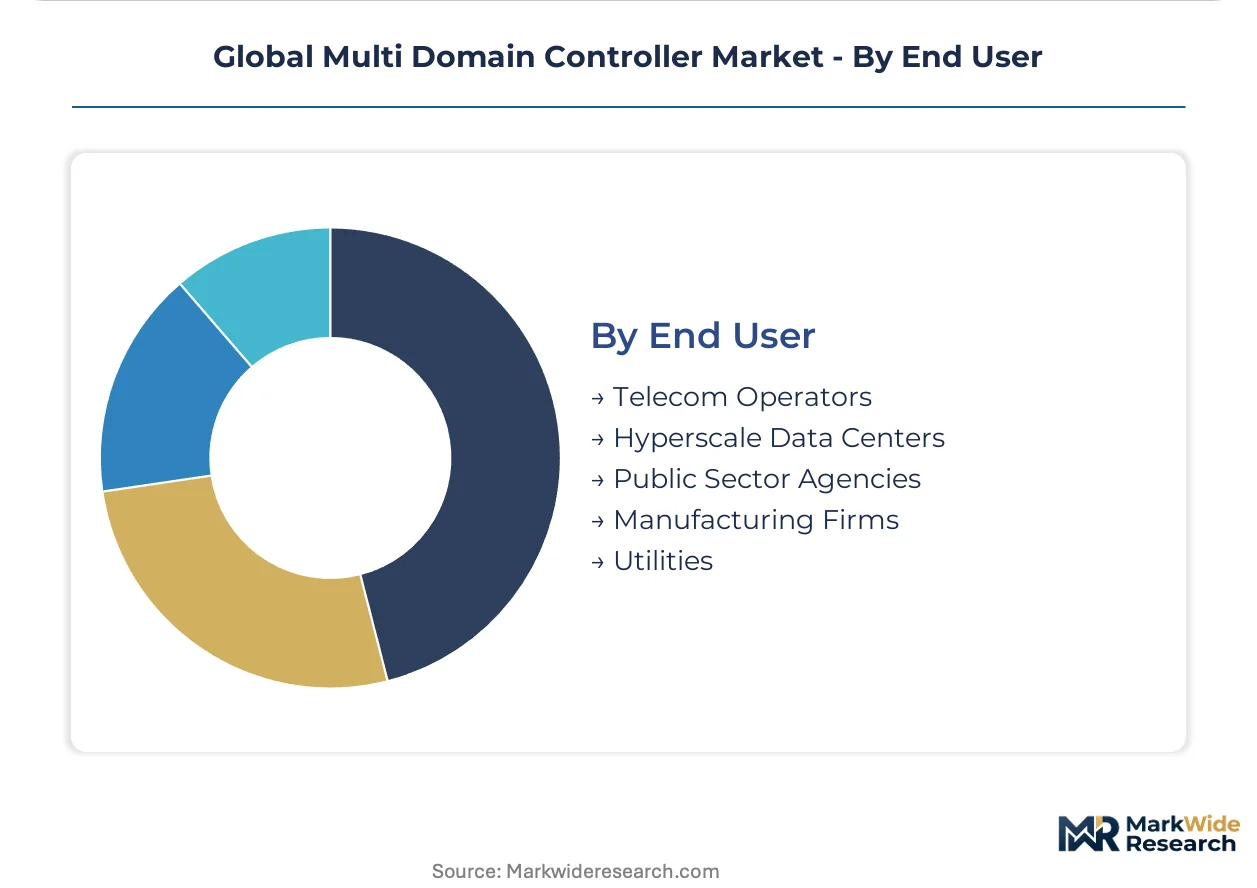
Multi-domain controller adoption varies significantly across different end-user types, each with unique requirements and integration challenges.
- Telecom Operators:These entities deploy controllers for managing their vast and complex network infrastructures, including 5G base stations, core networks, and edge deployments. They seek solutions that offer operational cost reduction and service agility.
- Hyperscale Data Centers:Operators of massive cloud computing facilities utilize multi-domain controllers to automate resource provisioning, simplify network management, and enhance the efficiency of their global operations. Global cloud service providers drive this demand.
- Public Sector Agencies:Government bodies and municipal organizations use controllers for critical infrastructure projects, smart city initiatives, and secure communication networks. MIIT directives in China influence procurement for telecommunications infrastructure.
- Manufacturing Firms:These companies integrate controllers to converge IT and OT systems, enabling advanced automation, predictive maintenance, and real-time process control in factories. Industry 4.0 adoption in Germany fuels demand.
- Utilities:Energy and water utility companies deploy multi-domain controllers for smart grid management, demand response, and integrating distributed energy resources. Grid modernization efforts globally drive this segment.
Hyperscale Data Centers are exhibiting the strongest growth prospects among end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The multi-domain controller market scaled significantly in regions adopting advanced networking paradigms. Early deployments in telecommunications infrastructure and data centers established foundational demand. This rapid expansion was particularly evident in East Asia, driven by aggressive digital transformation initiatives.
China
Massive 5G network deployments and hyperscale data center construction fuel multi-domain controller demand. MIIT directives for telecommunications infrastructure drive certified hardware procurement. The Yangtze River Delta region, including Shanghai, sees significant investment in data center modernization projects.
South Korea
Advanced 5G infrastructure rollouts and smart city initiatives drive significant controller adoption. The country's national broadband policies encourage high-performance network components. The Seoul Capital Area is a hub for smart city infrastructure and connected mobility solutions.
Germany
Industry 4.0 principles in manufacturing environments drive strong demand for industrial automation controllers. European cybersecurity certification schemes influence industrial controller design and specifications. Bavaria's manufacturing sector heavily integrates multi-domain controllers for IT/OT convergence.
Japan
Industrial automation and data center modernization initiatives create substantial controller demand. METI guidelines promote digital transformation across manufacturing sectors. The Kansai region, particularly Osaka, focuses on smart factory deployments and robotics.
United States
Hyperscale data center expansion and edge computing applications generate significant controller demand. FCC regulations for telecommunications infrastructure influence network controller specifications. Silicon Valley and Northern Virginia anchor massive hyperscale data center operations.
Global Multi Domain Controller Market Key Industry Players
The competitive structure tilts toward specialized component providers and diversified industrial conglomerates. The market exhibits a tiered structure, with established players offering integrated systems alongside newer entrants focusing on disaggregated hardware and software. Strategic archetypes include embedded systems specialists, industrial automation integrators, and advanced networking solution providers, each addressing specific domain requirements. Portfolio diversification and strategic partnerships represent dominant competitive moves across the ecosystem.
Specialists in secure connectivity and system integration exemplify the market's diverse offerings. Netherlands-based NXP Semiconductors N.V. leverages its portfolio in secure connectivity to target network controller applications. German-based Robert Bosch GmbH competes on its system integration expertise, particularly for industrial automation. Continental AG, also a German-based public company, positions its solutions for advanced networking within smart city infrastructure projects. These entities represent distinct approaches to consolidating functions across disparate operational domains.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Visteon Corporation |
| Panasonic Corporation |
| Continental AG |
| Magna International Inc. |
| NXP Semiconductors N.V. |
| Aptiv PLC |
| Others |
Cost & Logistics Intelligence
The architectural transition toward software-defined infrastructure simultaneously reshapes cost economics and supply concentration. This fundamental shift influences both component sourcing and the value proposition of integrated solutions for multi-domain controllers.
Pricing Analysis
Project-based and long-term contract pricing currently dominates multi-domain controller procurement, particularly for large infrastructure deployments. Price differentiation stems from the performance tier of multi-core processors and specific regulatory certification levels, such as those mandated by the EU AI Act. Pricing softness stems from the increasing availability of disaggregated hardware and open-source software solutions. Hyperscale data centers exhibit high price sensitivity, seeking competitive component pricing and flexible consumption models.
Supply Chain Analysis
Regulatory certification and qualification gating significantly shape the multi-domain controller supply chain, particularly for critical infrastructure deployments. Component manufacturing for high-performance multi-core processors concentrates in countries like South Korea, China, and Germany. The supply chain draws from specialized secure connectivity components and advanced SoCs. Single-source vulnerability for these specialized components presents a structural risk. Distribution runs through a mix of vertically integrated incumbents and specialized system integrators, increasingly favoring disaggregated sourcing models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multi-domain controller market presents a geographic-arbitrage play due to differing regulatory frameworks, such as MIIT directives in China versus NIS 2 Directive requirements in the EU. This creates distinct market access and product specification demands across regions.
For Market Incumbents:Acquire specialized software IP or open-source development teams to counter the threat of disaggregated solutions. Deepen vertical integration into secure connectivity components to maintain competitive positioning against new entrants. Invest in R&D for heterogeneous computing architectures to address evolving workload demands. Pursue strategic partnerships to overcome interoperability challenges and expand market reach.
For New Entrants and Emerging Players:The price-point gap between premium integrated solutions and lower-cost, disaggregated components presents an entry opportunity. Target underpenetrated segments like edge computing applications in smart city infrastructure using open-source hardware and software. Focus on regulatory-driven security features, leveraging mandates like the EU's NIS 2 Directive for market differentiation. Offer cloud-native architectures for flexible, consumption-based models to appeal to hyperscale data centers.
For Investors and Strategic Acquirers:Roll-up economics work for specialized software providers because of the increasing demand for disaggregated control plane solutions. The long-term viability of multi-domain controllers remains strong due to foundational needs for centralized control logic in SDN/NFV environments. Identify acquisition targets among embedded systems specialists or cybersecurity firms with certified hardware-level security expertise. A signal to watch is the progress in interoperability and standardization for multi-vendor deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Open-Source Ecosystems | This fosters broader adoption of disaggregated solutions, reducing vendor lock-in for telecommunications operators. |
| Develop Certified Security Modules | Compliance with regulations like the EU's NIS 2 Directive secures market access for critical infrastructure deployments. |
| Expand Edge Computing Offerings | This addresses low-latency processing requirements for smart city infrastructure and connected mobility solutions. |
| Form System Integration Partnerships | This overcomes software stack complexity and accelerates deployment for manufacturing firms adopting Industry 4.0. |
| Standardize API Interfaces | This enhances interoperability between controllers and network elements, benefiting hyperscale data center operators. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and quantitative modeling — were reconciled to build a comprehensive market view. Primary engagement included telecom operators' network architects, hyperscale data center engineers, industrial automation specialists, and public sector IT procurement leads. Secondary sources comprised government regulatory filings from MIIT and FCC, industry association reports, and technology vendor whitepapers. Bottom-up and top-down triangulation ensured data consistency.
Reconciliation of disparate data streams underpinned the forecast framework, which projected market evolution across the analysis window. The model segmented by controller type, technology, application, end user, and geographic region, including processor architecture. Compound annual growth rates were derived from historical trends and projected adoption curves. Key forecast inputs included global 5G deployment rates and hyperscale data center expansion plans.
The model assumes a particular technology adoption path; alternative pathways for SDN/NFV architectures would alter the outlook. Forecasts reflect assumptions concerning future interoperability standards and cybersecurity threat evolution. A model refresh is warranted upon material change in global semiconductor supply chain stability or regulatory policy changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
One-Way Degassing Valve Market
Others
Electrical Calibration Equipment Market
Others
Bitcoin Mining Hardware Market
Others
Fenoxanil Market
Others
Global Cryogenic Tanks Market
Others
Liquid Density Meters Market
Others
Shisha Tobacco Market
Others
Embedded Computer Market
Others
India Data Center Physical Security Market
Others
Asia-Pacific Adtech Market
Others
Process Spectroscopy Market
Others
Global Snow Sports Apparel Market
Others
Augmented Reality in BFSI Market
Others
North America Automotive LED Lighting Market
Others
5G Smartphone Market
Others
Radiation Detection Monitoring and Safety Market