
 Latin America Domestic CEP Market | 2026-2036
Latin America Domestic CEP Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Domestic CEP Market Foresight
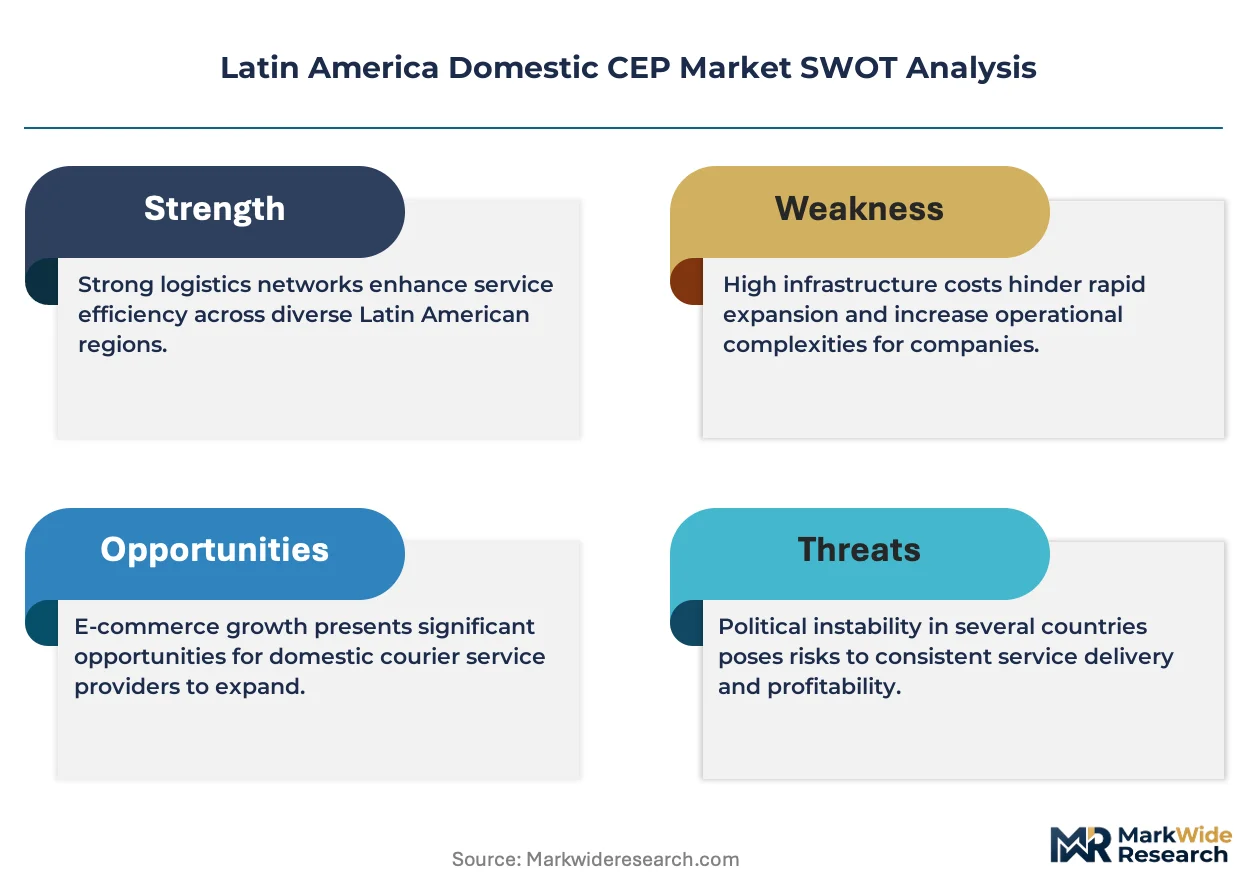
REACH is repositioning compliance costs for cross-border parcel flows entering Latin America from European suppliers. DHL Express leverages its customs brokerage network to preempt documentation bottlenecks at Mercosur entry points. Brazil Post anchors last-mile density through its Correios retail footprint across municipalities with fewer than fifty thousand residents. FedEx Corporation competes on temperature-controlled parcel infrastructure for pharmaceutical and perishable verticals.
Latin America Domestic CEP encompasses courier, express, and parcel services operating within national borders, combining hub-and-spoke sortation, multi-modal line-haul, and variable-density last-mile networks to move documents and packages with delivery commitments ranging from same-day to standard five-day windows. The primary commercial purpose centers on fulfilling time-definite logistics contracts for B2B document exchange and B2C e-commerce order fulfillment. Express delivery and same-day delivery command premium rate cards as urban consolidation deepens in São Paulo and Mexico City, while standard delivery occupies the volume base across price-sensitive residential and small business accounts. E-commerce customer types generate disproportionate growth in technology investments, with mobile tracking and route optimization absorbing capital as delivery density rises.
ANVISA in Brazil, Mexico's Tax Administration Service digital reporting mandates, and Argentina's AFIP import tracking requirements collectively tighten parcel documentation and traceability standards across the region. These frameworks elevate technology minimums for market access and compress margins for operators lacking automated customs interfaces. Stakeholders must weigh regulatory compliance capex against network density economics when prioritizing country expansion sequences.
Market Dynamics
E-commerce fulfillment density in São Paulo and Mexico City is compressing delivery windows and forcing network reconfiguration across the region's CEP operators.
Growth Catalysts
- ANVISA pharmaceutical standards:Temperature-controlled parcel requirements expand specialized service tiers and equipment investment across Brazil's healthcare logistics corridor.
- Mobile-first tracking adoption:Smartphone penetration enables real-time visibility investments that reduce failed delivery rates in dense urban last-mile zones.
- Mexico City–Monterrey axis consolidation:Manufacturing relocation to northern Mexico generates express document and spare parts flows between industrial clusters.
Market Restraints
- Fuel price volatility:Diesel cost swings directly compress line-haul margins for operators lacking fuel surcharge mechanisms or electric fleet transition timelines.
- Correios retail lock-in:Brazil Post's municipal coverage in sub-fifty-thousand-resident towns creates last-mile access barriers for private competitors.
- Argentina's AFIP documentation complexity:Import tracking mandates generate customs brokerage bottlenecks that delay cross-border parcel flows from Mercosur partners.
Strategic Opportunities
- Colombia's Andean corridor:Bogotá–Medellín express lane development remains underpenetrated relative to São Paulo and Mexico City density levels.
- Perishables vertical expansion:Fresh produce e-commerce platforms in Chile and Peru create demand for cold-chain parcel infrastructure currently served by generalist operators.
- Mexico SAT digital reporting tailwind:Tax Administration Service mandates accelerate automated customs interface adoption, favoring technology-capable entrants over manual brokers.
Industry Challenges
- Route optimization talent scarcity:Data science capabilities for dynamic dispatch algorithms remain concentrated in São Paulo and Mexico City, limiting operational scaling.
- Hub automation capex cycles:Sortation robotics deployment requires capital commitments that strain mid-tier operators serving secondary Brazilian states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Domestic CEP Market |
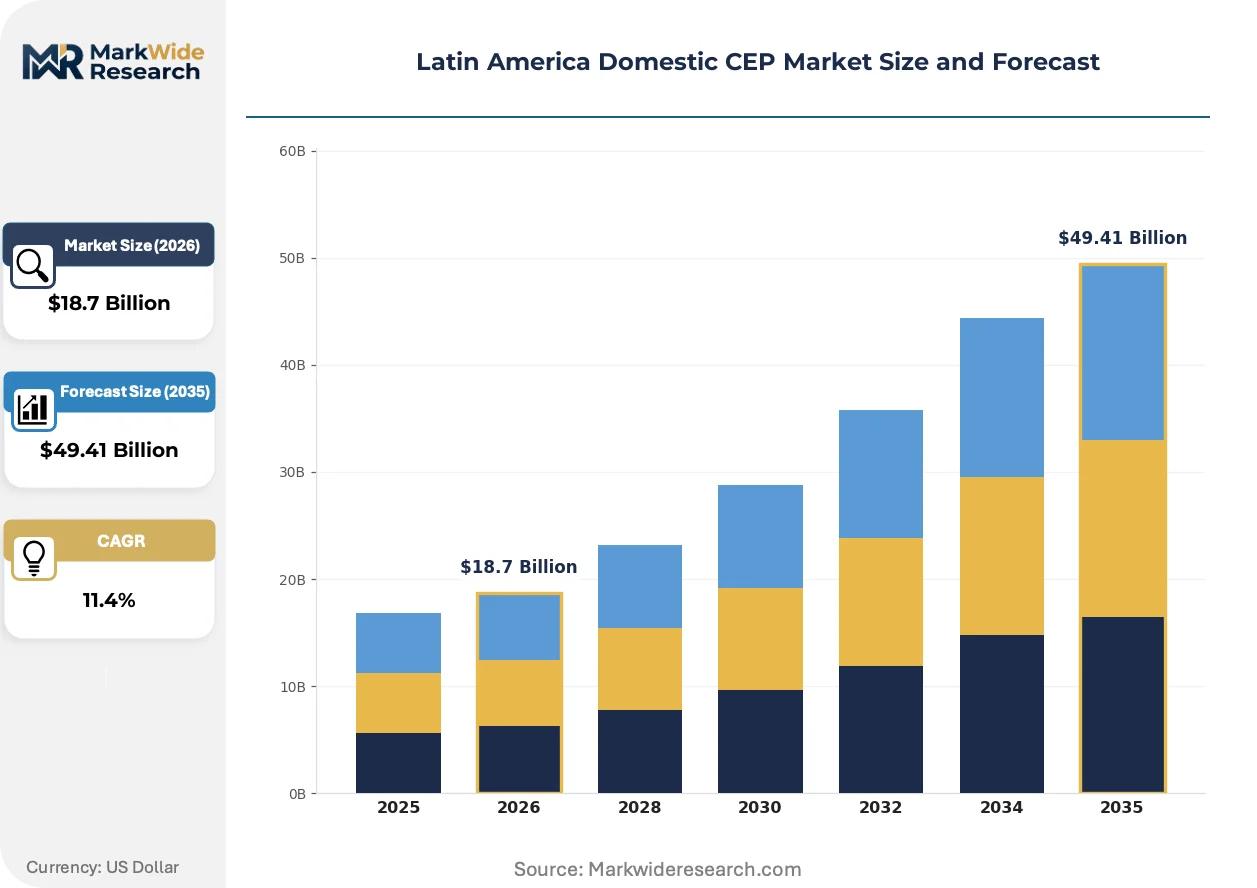
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Express Delivery, Same-Day Delivery, Next-Day Delivery Customer Type: Residential, Small Business, Large Enterprise, E-commerce Technology: Mobile Tracking, Automated Sorting, Route Optimization, Delivery Drones Packaging Type: Boxes, Bubble Wrap, Envelopes, Pallets |
| Companies Covered | DHL Express, UPS, Brazil Post, Kerry Logistics, Kuehne Nagel, Sky Postal, FedEx Corporation, Nippon Express, Loggi, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Domestic CEP Market Shifts & Advancements
Digital customs interfaces and dynamic fleet routing are compressing operational latency while regulatory documentation mandates elevate technology minimums for market participation.
Dynamic route optimization software is modularizing last-mile dispatch decisions across Brazil's São Paulo corridor. Regional carriers and Brazil Post are deploying algorithmic sequencing tools that resequence stops in real-time based on traffic patterns and customer availability windows. This capability is modularizing the traditional fixed-route model into adaptive micro-territories served by gig-economy or employed drivers interchangeably.
ANVISA's pharmaceutical distribution temperature standards are forcing cold-chain infrastructure investments across Brazilian express networks. Operators must validate continuous temperature logging from pickup through delivery for vaccine and biologic shipments. The healthcare vertical is responding by certifying dedicated pharmaceutical sorting facilities in Campinas and Rio de Janeiro.
Buyer expectations for delivery window precision are compressing service-level agreements in Mexico's e-commerce channels. Retail platforms now guarantee four-hour delivery windows in Mexico City, displacing the previous day-definite standard. This shift is most visible in consumer electronics and fashion verticals where cart abandonment correlates directly with estimated delivery range uncertainty.
Latin America Domestic CEP Market Segmentation
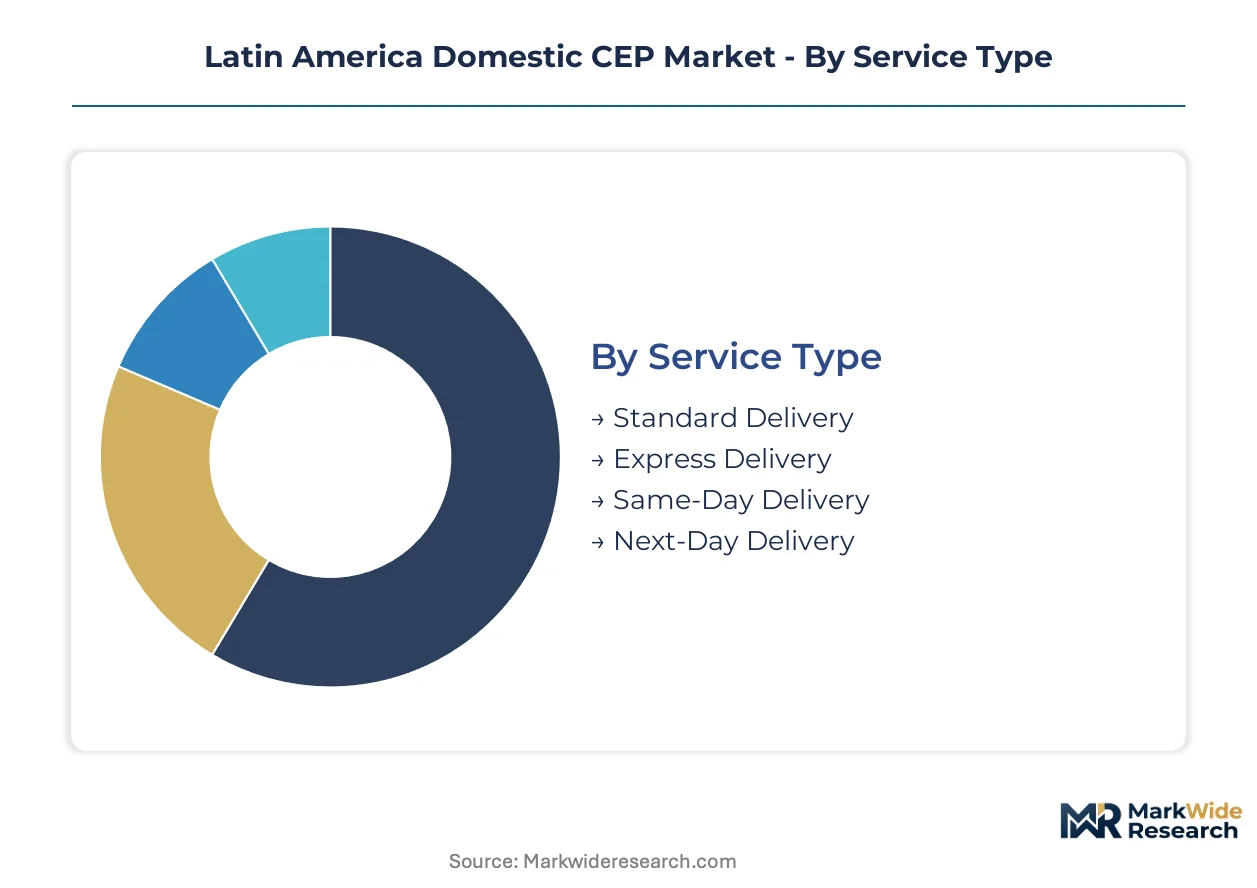
Segmentation in Latin America Domestic CEP reveals where capital deployment concentrates and which service tiers generate sustainable returns. Network configuration decisions hinge on matching infrastructure investment to segment-specific density patterns.
Service Type:
Capital intensity peaks with delivery velocity commitments, as same-day networks require distributed micro-fulfillment nodes rather than centralized hubs.
- Standard Delivery:Five-day delivery windows utilize consolidated line-haul and deferred sortation schedules to minimize per-unit costs. Demand concentrates in Brazil's secondary states and Mexico's central plateau where price sensitivity dominates commercial procurement.
- Express Delivery:Time-definite two-to-three-day service balances hub economies with premium rate cards through scheduled air and ground line-haul integration. São Paulo–Rio de Janeiro and Mexico City–Monterrey corridors absorb the bulk of express volume as manufacturing and financial document flows cluster.
- Same-Day Delivery:Urban micro-fulfillment networks with dynamic dispatch algorithms serving dense metropolitan zones.
- Next-Day Delivery:Overnight sortation operations with dedicated line-haul capacity for B2B contract customers.
Standard delivery absorbs the bulk of installed capacity; same-day delivery is expanding most quickly.
Customer Type:
Margin profiles diverge sharply across customer categories, with e-commerce platforms demanding technology integration that residential accounts rarely justify.
- E-commerce:Platform-integrated fulfillment requiring API connectivity, real-time inventory synchronization, and branded tracking interfaces. São Paulo and Mexico City digital retail concentration drives disproportionate technology investment toward this segment.
- Large Enterprise:Contract logistics with dedicated account management and customized SLA frameworks for financial, pharmaceutical, and industrial verticals.
- Residential:Single-parcel deliveries to individual households with high failed-attempt rates and address verification challenges.
- Small Business:Volume-aggregated shipping with simplified rate structures and retail drop-off access points.
Large enterprise contracts anchor revenue stability; e-commerce is climbing the fastest.
Technology:
Technology deployment stratifies operators by automation depth, with sortation robotics requiring capital commitments that mid-tier carriers defer.
- Automated Sorting:Hub robotics and dimensioning systems processing parcel flows exceeding threshold volumes. Campinas and Rio de Janeiro pharmaceutical certification hubs demonstrate where automation justifies capex.
- Route Optimization:Algorithmic dispatch sequencing reducing miles-per-stop in dense urban territories.
- Mobile Tracking:Smartphone-delivered visibility reducing customer service inquiries and failed delivery rates.
- Delivery Drones:Experimental last-mile automation for remote or congestion-constrained zones with limited regulatory clearance.
Mobile tracking has achieved near-universal adoption; automated sorting is gaining share fastest.
Packaging Type:
Packaging specifications correlate directly with network handling requirements and damage liability exposure.
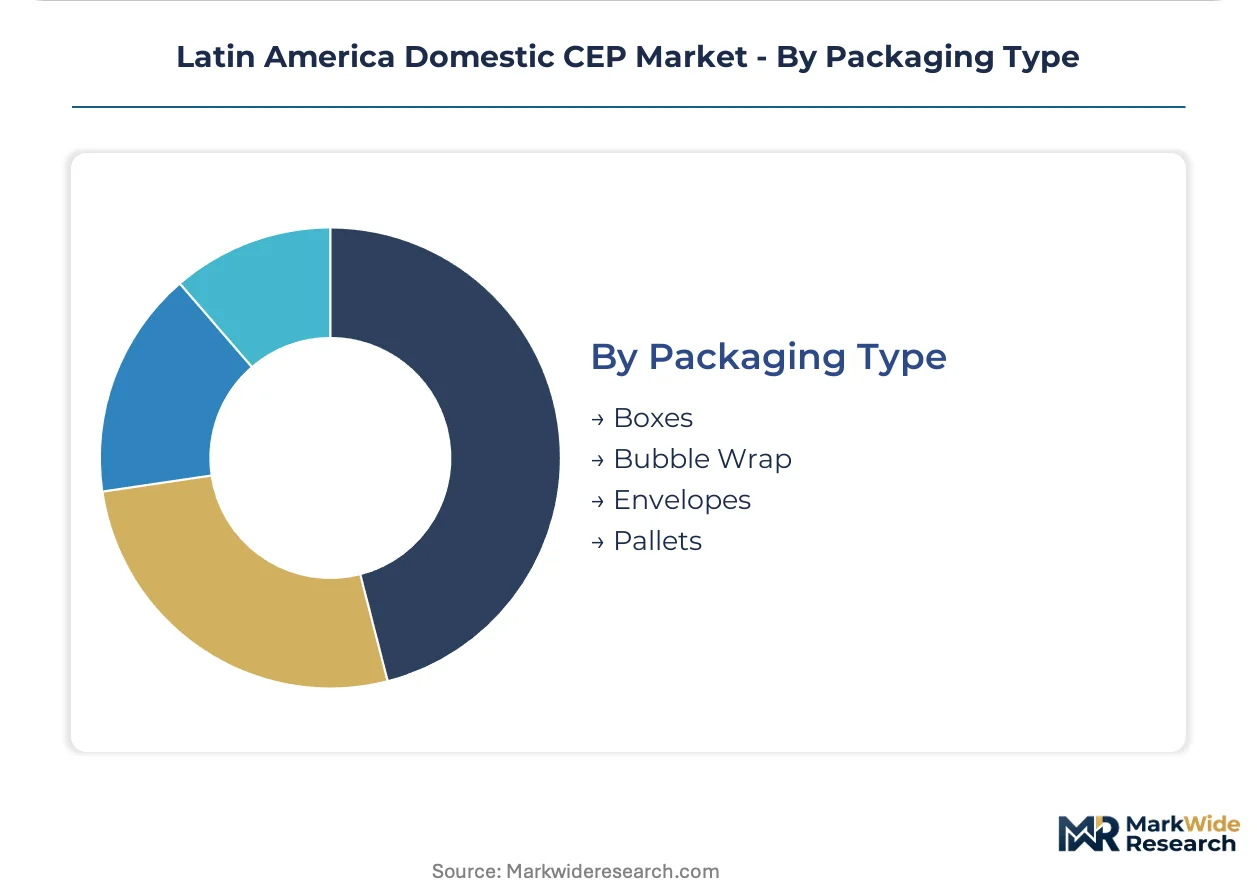
- Boxes:Rigid corrugated containers protecting general merchandise through multi-modal handling. E-commerce fulfillment centers in São Paulo and Mexico City drive standardized box dimension requirements to maximize vehicle cube utilization.
- Envelopes:Document and flat-item protection for B2B correspondence and lightweight retail.
- Bubble Wrap:Fragile-item cushioning for electronics and glassware with specialized handling protocols.
- Pallets:Unitized freight consolidation for B2B shipments requiring forklift handling and dock-level access.
Boxes dominate parcel volume; envelopes retain share in document-heavy B2B corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives concentrate electronics manufacturing in Brazil's northwest, generating cross-border component flows that feed São Paulo assembly lines. This tax-advantaged hub anchors regional CEP demand patterns.
Brazil
E-commerce platform consolidation and pharmaceutical cold-chain requirements drive express volume growth. ANVISA temperature-validation mandates force infrastructure upgrades along the São Paulo–Rio de Janeiro healthcare corridor. Campinas hosts certified pharmaceutical sorting facilities serving vaccine distribution networks.
Mexico
Nearshoring manufacturing relocation and SAT digital reporting requirements reshape cross-border parcel flows. The Tax Administration Service's automated customs interfaces favor technology-capable operators over manual brokers. The Mexico City–Monterrey axis absorbs express document and spare parts shipments between industrial clusters.
Argentina
Import tracking mandates and currency volatility constrain cross-border parcel velocity. AFIP documentation complexity generates customs brokerage bottlenecks that delay Mercosur partner shipments. Buenos Aires concentration creates last-mile density challenges amid urban traffic constraints.
Chile
Fresh produce e-commerce platforms and mining spare parts logistics generate specialized cold-chain demand. Santiago–Valparaíso corridor development supports temperature-controlled parcel infrastructure for agricultural exports. The central valley's perishables verticals attract operator investment in refrigerated last-mile capacity.
Colombia
Bogotá–Medellín express lane development remains underpenetrated relative to regional density benchmarks. Andean corridor manufacturing relocation generates document and component flows between industrial zones. Coffee region agricultural exports create seasonal parcel volume spikes requiring flexible network capacity.
Latin America Domestic CEP Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin America's CEP landscape. Global integrators leverage cross-border infrastructure to capture premium express segments, while regional carriers defend price-sensitive standard delivery through municipal density. Three archetypes dominate: multinational integrators with customs brokerage depth, state-affiliated postal operators with rural coverage, and technology-native challengers with algorithmic routing. Competitive moves concentrate on hub automation capex cycles and strategic partnerships with e-commerce platforms.
Among multinational integrators, DHL Express and FedEx Corporation occupy positions defined by customs brokerage networks and temperature-controlled infrastructure. Brazil Post anchors the state-affiliated tier through Correios retail penetration in sub-fifty-thousand-resident municipalities. Loggi represents technology-native challengers deploying dynamic dispatch algorithms in dense urban zones.
| Leading Market Players |
|---|
| DHL Express |
| UPS |
| Brazil Post |
| Kerry Logistics |
| Kuehne Nagel |
| Sky Postal |
| FedEx Corporation |
| Nippon Express |
| Loggi |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap carriers across Brazil's secondary states anchor supply-side consolidation while exercising pricing discipline through deferred sortation schedules and fuel surcharge pass-through mechanisms. Their ownership structures limit access to automation capex, compressing margins against multinational integrators with deeper balance sheets.
Pricing Analysis
Lead-time-driven pricing separates same-day delivery premiums from standard five-day economy tiers across São Paulo and Mexico City corridors. Price differentiation rests on fuel surcharge mechanisms, temperature-controlled certification grades, and API integration depth for e-commerce platforms. Pricing pressure stems from diesel volatility and Correios municipal lock-in, squeezing mid-tier operators. Small business accounts exhibit highest price sensitivity; large enterprise pharmaceutical contracts demonstrate lowest elasticity due to ANVISA compliance requirements.
Supply Chain Analysis
Domestic-content mandates in Brazil's pharmaceutical corridor reshape sourcing toward certified Campinas and Rio de Janeiro sorting facilities. Geographic supply concentrates in Brazil, Mexico, and Chile, with equipment dependencies on European sortation robotics and Asian last-mile tracking hardware. Supply chain risk centers on single-source vulnerability for automated dimensioning systems. Distribution runs through hub-and-spoke networks with micro-fulfillment nodes in dense urban zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over cold-chain infrastructure and customs brokerage interfaces determines margin capture. Players are pursuing downstream integration into last-mile micro-fulfillment to defend rate-card premiums.
For Market Incumbents: Hedge against technology-native challengers by acquiring route optimization talent clusters in São Paulo and Mexico City. Deploy capital into pharmaceutical certification hubs before ANVISA mandates tighten further. Lock in e-commerce platform API integrations to raise switching costs for retail customers. For New Entrants and Emerging Players: Capture underpenetrated density in Colombia's Bogotá–Medellín corridor where express lane development lags regional benchmarks. Target perishables verticals in Chile's central valley with refrigerated last-mile capacity. Enter through SAT-compliant automated customs interfaces rather than manual brokerage relationships. For Investors and Strategic Acquirers: ANVISA enforcement actions against non-compliant cold-chain operators are the leading indicator that pharmaceutical certification assets will command scarcity premiums. Long-term viability favors operators with integrated temperature-logging infrastructure and dense municipal coverage. Monitor Correios privatization progress as the signal for competitive access in Brazil's sub-fifty-thousand-resident towns.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Cold-Chain Certification | ANVISA compliance mandates validate continuous temperature logging from pickup through delivery. |
| Dynamic Route Optimization Deployment | Algorithmic dispatch sequencing reduces miles-per-stop in São Paulo's dense urban micro-territories. |
| Automated Customs Interface Integration | Mexico SAT digital reporting favors technology-capable operators over manual brokerage competitors. |
| Micro-Fulfillment Network Expansion | Urban consolidation in Mexico City enables four-hour delivery window guarantees for electronics retail. |
| Perishables Cold-Chain Infrastructure | Chile's fresh produce e-commerce platforms demand refrigerated last-mile capacity beyond generalist networks. |
Research Methodology
Independent corroboration across logistics operations executives, e-commerce platform supply chain directors, pharmaceutical distribution managers, and customs brokerage specialists underwrites the qualitative findings. Secondary validation draws from ANVISA regulatory filings, Mexico SAT digital reporting mandates, Brazil customs trade data, and operator capex disclosures. Bottom-up parcel volume modeling triangulates against top-down regional GDP and e-commerce penetration benchmarks.
Comparable-period anchoring to historical express volume growth and line-haul capacity deployment patterns structures the forecast framework across the analysis window. Segmentation dimensions include service type velocity tiers, customer category margin profiles, technology automation depth, and pharmaceutical certification status. CAGRs derive from density-driven network economics and regulatory compliance capex cycles. Forecast inputs incorporate diesel price trajectory assumptions and mobile tracking adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fuel price volatility, Correios structural reform timing, and AFIP documentation complexity shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Linseed Oil Market
Others
Moveable Water Tap Market
Others
Solar Panel Testers Market
Others
Asia-Pacific Legal Services Market
Others
5G Devices Market
Others
Asia-Pacific B2B Legal Services Market
Others
Construction Wearables Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Fire Sprinkler Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
North America Flexographic Printing Market
Others
Composite Copper Foil Production Equipment Market
Others
Smart TV Platforms Market
Others
Asia-Pacific Social Media Management Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Reef Aquarium Market