
 Global Bio-Based Chemicals Market | 2026-2036
Global Bio-Based Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio-Based Chemicals Market Foresight
Petrochemical feedstock is decoupling from specialty chemical production as bio-fermentation pathways achieve cost parity at scale. BASF SE leverages its Ludwigshafen Verbund site to integrate renewable feedstocks into existing polymer trains without redundant capital. Cargill, Incorporated anchors North American supply through its Blair, Nebraska biorefinery complex, converting corn starch into platform chemicals for downstream partners. Braskem dominates biopolymer output from its Triunfo, Brazil facility, where sugarcane-derived I'm green polyethylene competes with conventional LLDPE on specification parity.
Bio-based chemicals comprise molecules synthesized from renewable biomass feedstocks—sugars, lipids, lignocellulosic residues—via enzymatic catalysis, microbial fermentation, or thermochemical conversion, delivering functional equivalence to petrochemical counterparts with lower cradle-to-gate carbon intensity. Bioethanol and lactic acid lead product type volume, though biopropylene glycol is accelerating fastest as automotive coolant formulators seek non-toxic alternatives to petroleum-derived MEG. Plastics application segments capture the deepest margin pools, where brand-owner sustainability commitments translate into long-term offtake contracts with price premiums tied to mass-balance certification.
REACH registration requirements in Europe, the EPA's Renewable Fuel Standard in the United States, and Japan's METI Biomass Plastics Strategy collectively shape demand by mandating recycled or renewable content thresholds across packaging and automotive supply chains. The EU Green Deal's Carbon Border Adjustment Mechanism tightens compliance costs for imported petrochemical derivatives, redirecting procurement budgets toward certified bio-based alternatives. Stakeholders must monitor fermentation yield improvements and feedstock competition with food markets, as these variables determine whether bio-based chemicals sustain cost competitiveness against naphtha-derived benchmarks without subsidy dependence.
Market Dynamics
Fermentation yield improvements are compressing unit economics for bio-based platform chemicals, enabling producers to undercut naphtha-derived benchmarks without subsidy dependence in select product categories.
Growth Catalysts
- EU Green Deal Carbon Border Adjustment Mechanism:Imported petrochemical derivatives face tightening compliance costs, redirecting European packaging converters toward certified bio-based alternatives with mass-balance certification.
- Automotive coolant formulators:These end-users are accelerating substitution of petroleum-derived MEG with biopropylene glycol to meet non-toxic specifications and OEM sustainability mandates.
- Sugarcane-to-polyethylene pathways:Brazilian biorefinery clusters achieve cost parity through integrated cultivation, fermentation, and polymerization infrastructure.
Market Restraints
- Feedstock competition with food markets:Corn and sugarcane starch diversion into chemical production creates price volatility spikes during agricultural yield shortfalls.
- Enzymatic catalysis yield ceilings:Current biocatalyst performance limits conversion efficiency for lignocellulosic feedstocks, trapping producers in first-generation sugar pathways.
- REACH registration timelines:Novel bio-based molecules face extended ECHA evaluation periods, delaying commercial launch by 18-36 months versus petrochemical equivalents.
Strategic Opportunities
- India's PLI scheme for bioplastics:Production-linked incentives for bio-based polymer capacity are attracting fermentation technology licensors to establish local manufacturing.
- Lignocellulosic residue valorization:Agricultural waste streams in Southeast Asia offer untapped feedstock pools for second-generation bio-ethanol and platform chemical production.
- Japan's METI Biomass Plastics Strategy:Mandatory renewable content thresholds in packaging create guaranteed offtake volumes with price premiums for certified suppliers.
Industry Challenges
- Industrial biotechnology talent scarcity:Fermentation process engineering and metabolic pathway design expertise concentrates in limited geographic clusters, constraining scale-up velocity.
- Mass-balance certification complexity:ISCC PLUS and RSB chain-of-custody audits require substantial documentation infrastructure, particularly for multi-site polymer producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio-Based Chemicals Market |
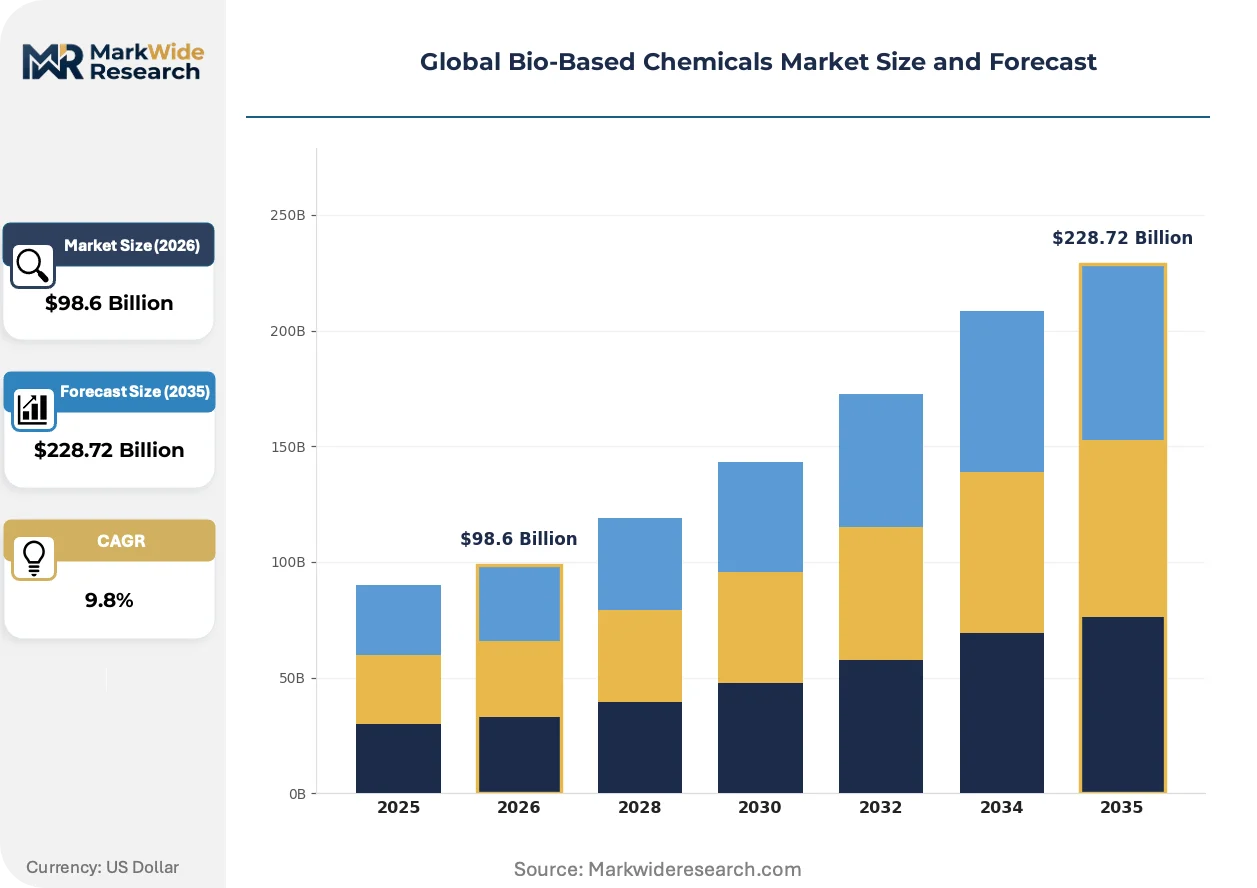
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $228.72 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioethanol, Biobutanol, Lactic Acid, Biopropylene Glycol Application: Plastics, Pharmaceuticals, Cosmetics, Textile Distribution Channel: Direct Sales, E-commerce, Retail, Wholesale End User: Food Industry, Automotive, Packaging, Agriculture |
| Companies Covered | BASF SE, Cargill, Incorporated, DuPont, Braskem, dsm-firmenich, Evonik Industries, Novozymes, Mitsubishi Chemical Corporation, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio-Based Chemicals Market Shifts & Advancements
Continuous processing is displacing batch fermentation across bio-based chemical manufacturing, compressing capital intensity and enabling real-time quality control that batch systems cannot match.
Cell-free enzymatic synthesis is integrating into specialty chemical production, eliminating the metabolic burden of living cells and achieving higher product titers for pharmaceutical intermediates. Contract manufacturers serving agrochemical and personal care formulators are adopting these systems to reduce purification costs. The technology is integrating downstream separation steps that previously required dedicated capital equipment, flattening the cost curve for low-volume high-value molecules.
REACH authorization requirements for persistent organic pollutants are tightening discharge standards for conventional petrochemical production, elevating compliance costs for naphtha-derived aromatics. European chemical parks in Ludwigshafen and Antwerp are retrofitting existing polymer trains to accept renewable feedstocks rather than building greenfield capacity. Bio-based benzene and toluene substitutes are capturing share in polyurethane foam and polyester resin applications where carbon intensity disclosures are mandatory.
Brand-owner sustainability scorecards now require tier-two and tier-three suppliers to document cradle-to-gate emissions, extending certification pressure deeper into chemical supply chains. Packaging converters in Germany and France are consolidating supplier bases to reduce audit burden, favoring integrated bio-refiners with captive certification. This concentration is most visible in flexible packaging, where multinational food brands have established preferred supplier programs with bio-based polymer specialists.
Global Bio-Based Chemicals Market Segmentation
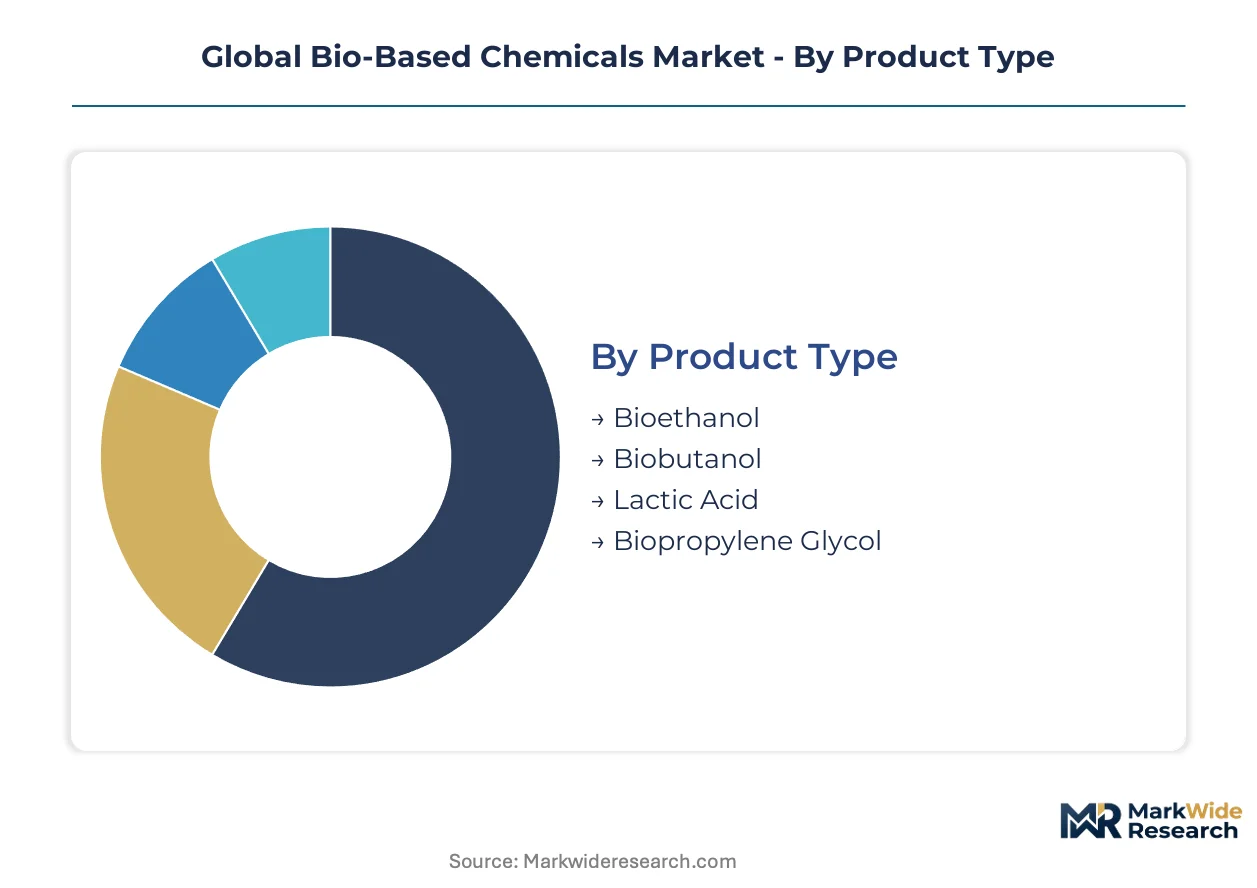
Bio-based chemicals fragment across four intersecting dimensions that determine procurement patterns and margin capture. Product chemistry defines feedstock flexibility and carbon intensity credentials. Application verticals impose divergent purity specifications and certification requirements that reshape competitive positioning.
Product Type:
Buyers in this category differentiate by fermentation pathway maturity and substitution economics against petrochemical benchmarks.
- Bioethanol:First-generation sugar fermentation delivers platform chemical volumes for fuel blending and industrial solvent applications. Demand concentrates in Brazil and the United States where corn and sugarcane feedstock infrastructure achieves cost parity without subsidy dependence.
- Lactic Acid:Polylactic acid precursor manufactured via bacterial fermentation of carbohydrates achieves polymer-grade purity through advanced separation. Packaging converters in Germany and France secure long-term offtake with mass-balance certification tied to EU Green Deal compliance timelines.
- Biobutanol:Four-carbon alcohol produced through acetone-butanol-ethanol fermentation offers higher energy density than bioethanol for fuel applications.
- Biopropylene Glycol:Non-toxic glycol manufactured via hydrogenolysis of glycerin serves automotive coolant formulators seeking petroleum-derived MEG replacements.
Volume sits with bioethanol; growth tilts toward lactic acid.
Application:
Margin capture in this category tracks sustainability disclosure requirements and brand-owner certification pressure intensity.
- Plastics:Bio-based polyethylene and polylactic acid compounds deliver specification parity with virgin petrochemical resins. Flexible packaging converters in Germany consolidate supplier bases to reduce ISCC PLUS audit burden, favoring integrated biorefiners with captive certification infrastructure.
- Pharmaceuticals:Fermentation-derived active pharmaceutical intermediates achieve chiral purity that chemical synthesis cannot match economically. Contract manufacturers in Switzerland and India adopt cell-free enzymatic systems to reduce purification costs for low-volume high-value molecules.
- Cosmetics:Bio-based emollients and surfactants serve formulators responding to EU REACH restrictions on petrochemical-derived persistent organic pollutants.
- Textile:Bio-based polyester and fiber intermediates supply apparel brands with cradle-to-gate carbon intensity disclosures mandated by tier-two supplier scorecards.
Margin concentrates in plastics; certification complexity escalates fastest in pharmaceuticals.
Distribution Channel:
Channel selection in this category reflects order scale, documentation intensity, and technical service requirements.
- Direct Sales:Long-term supply agreements with dedicated account management support fermentation process integration and custom specification development. Automotive OEM coolant formulators in Germany and Japan procure biopropylene glycol through direct channels to secure technical collaboration on formulation compatibility.
- Wholesale:Distributor networks aggregate fragmented demand from mid-scale processors lacking procurement infrastructure for direct refinery relationships. Agricultural chemical blenders in the United States access bio-based platform chemicals through regional distributors with inventory positioning.
- E-commerce:Digital platforms serve research-scale buyers and specialty formulators requiring rapid sample turnaround and technical documentation.
- Retail:Limited to consumer-facing bio-based products with finished goods branding rather than industrial chemical offtake.
Transaction volume flows through wholesale; documentation intensity drives direct sales expansion.
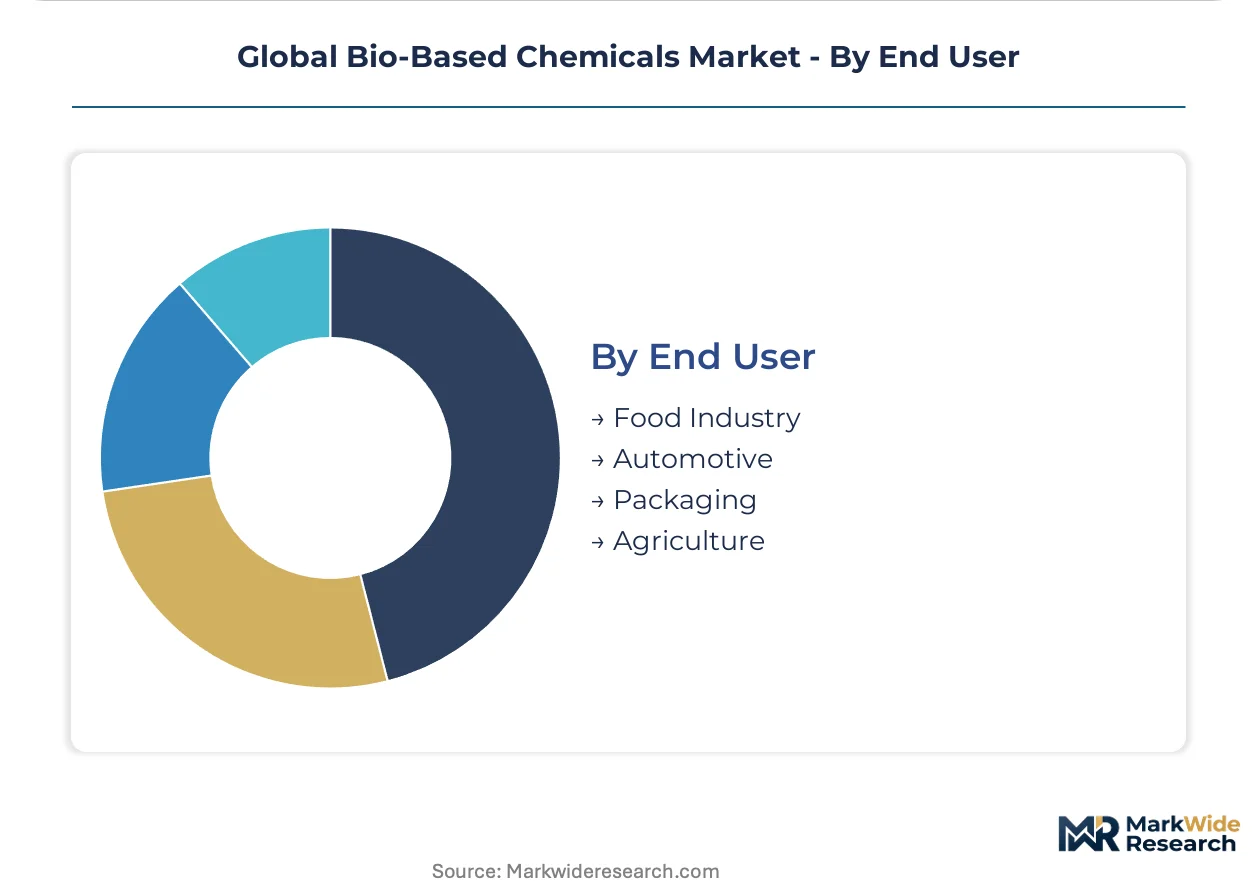
End User:
End-user segmentation reveals divergent price sensitivity and specification rigor that reshape supplier qualification criteria.
- Packaging:Food and beverage brand owners mandate renewable content thresholds that cascade to converter procurement specifications. EU Green Deal Carbon Border Adjustment Mechanism redirects European converter budgets toward certified bio-based alternatives with mass-balance chain-of-custody documentation.
- Automotive:Coolant and interior material formulators substitute petroleum-derived MEG with biopropylene glycol to meet OEM non-toxic specifications and sustainability scorecard requirements.
- Food Industry:Acidulants, preservatives, and emulsifiers derived from fermentation serve clean-label formulation trends with regulatory acceptance from EFSA and FDA.
- Agriculture:Bio-based pesticides and fertilizer coatings leverage fermentation-derived platform chemicals to reduce synthetic petrochemical dependence.
Contract value concentrates in packaging; specification evolution accelerates most rapidly in automotive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Triunfo petrochemical complex anchors the hemisphere's lowest-cost sugarcane-to-polyethylene corridor, drawing integrated biorefinery investment through state-level tax abatements and preferential ethanol pricing frameworks.
Germany
Packaging converters in Ludwigshafen and Cologne accelerate procurement of mass-balance certified bio-based polymers as EU Green Deal carbon intensity thresholds tighten. ECHA REACH registration timelines for novel bio-based molecules extend commercial launch windows by 18-36 months. BASF SE operates integrated fermentation and polymerization corridors at its Ludwigshafen Verbund site, accepting renewable feedstocks into existing polymer trains without redundant capital deployment.
United States
Automotive coolant formulators in Michigan and Ohio substitute petroleum-derived MEG with biopropylene glycol to meet OEM non-toxic specifications. EPA Renewable Fuel Standard mandates create baseline demand for bioethanol platform chemicals. Cargill, Incorporated anchors North American supply through its Blair, Nebraska biorefinery complex, converting corn starch into downstream chemical precursors.
Japan
Automotive and electronics material suppliers face METI Biomass Plastics Strategy mandates requiring renewable content thresholds in packaging applications. Mitsubishi Chemical Corporation and domestic compounders secure long-term offtake contracts with price premiums tied to mass-balance certification. The Nagoya-Tokyo industrial corridor concentrates fermentation-derived specialty chemical production for pharmaceutical and cosmetic applications.
India
Packaging converters in Maharashtra and Gujarat respond to brand-owner sustainability scorecards cascading from multinational food companies. PLI scheme production-linked incentives for bioplastics attract fermentation technology licensors to establish local manufacturing. The Mumbai-Pune belt emerges as a contract fermentation hub serving agrochemical and personal care formulators seeking chiral purity intermediates.
Brazil
Sugar-ethanol mills in São Paulo state pivot toward chemical-grade ethanol output as Braskem's I'm green polyethylene achieves specification parity with conventional LLDPE. ANVISA regulatory acceptance of bio-based food contact materials accelerates flexible packaging adoption. The Triunfo complex integrates cultivation, fermentation, and polymerization infrastructure to capture cost parity without subsidy dependence.
Global Bio-Based Chemicals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated biorefiners capturing packaging volume while fermentation technology licensors serve pharmaceutical and cosmetic formulators. The market structure concentrates around three archetypes: agricultural processors with captive feedstock infrastructure, diversified chemical conglomerates retrofitting existing polymer trains, and industrial biotechnology specialists licensing enzymatic catalysis platforms. Competitive moves center on strategic partnerships for mass-balance certification infrastructure and capacity expansion in sugarcane- and corn-belt corridors.
Within the agricultural processor tier, Cargill, Incorporated and Archer Daniels Midland Company represent feedstock-integrated archetypes with North American corn-belt positioning. Braskem occupies a distinct geography-driven position as the dominant biopolymer output source from Brazilian sugarcane corridors. BASF SE exemplifies the diversified chemical conglomerate archetype, leveraging Verbund site integration to accept renewable feedstocks without greenfield capital deployment.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Incorporated |
| DuPont |
| Braskem |
| dsm-firmenich |
| Evonik Industries |
| Novozymes |
| Mitsubishi Chemical Corporation |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon intensity thresholds gate both qualified supply and premium-tier pricing access, as packaging converters in Germany and France consolidate procurement around integrated biorefiners with captive mass-balance certification infrastructure. Buyers without documented cradle-to-gate emissions face exclusion from long-term offtake contracts, compressing margins for uncertified suppliers while rewarding verified low-carbon producers with price premiums tied to ISCC PLUS chain-of-custody documentation.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency spot buyers from contracted volume purchasers, with automotive coolant formulators in Germany paying premiums for biopropylene glycol delivered within compressed windows versus standard contract pricing for scheduled offtake. Pricing stratifies across mass-balance certified, conventional bio-based, and uncertified tiers, with certification grade and volume scale as the primary differentiation drivers. Cost compression in the uncertified tier is intensifying because REACH registration delays trap novel molecules in extended ECHA evaluation periods. Small-scale cosmetic formulators exhibit the highest price sensitivity, while automotive OEM procurement teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for biopropylene glycol and polylactic acid compounds, with BASF SE and Braskem operating dedicated account management for automotive and packaging converters respectively. Geographic supply concentration centers on Germany, Brazil, and the United States, where integrated fermentation and polymerization corridors achieve cost parity through captive feedstock infrastructure. Raw material dependencies rest on corn starch, sugarcane-derived ethanol, and lignocellulosic agricultural residues. Single-source vulnerability in Brazilian sugarcane corridors creates exposure to climate-induced yield volatility. Distribution runs through long-term supply agreements with technical service support, supplemented by regional wholesale networks aggregating fragmented mid-scale processor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated biorefiners with captive certification infrastructure, as EU Green Deal compliance timelines force smaller fermentation technology licensors into acquisition or exit. Extended ECHA REACH registration periods and mass-balance audit complexity disproportionately burden capital-constrained players.
For Market Incumbents: Anchor backward integration into sugarcane and corn-belt corridors to secure feedstock cost parity without subsidy dependence, while expanding captive ISCC PLUS certification infrastructure to reduce buyer audit burden. Defensive moves should prioritize capacity expansion in Brazil's Triunfo complex and Germany's Ludwigshafen Verbund site, as emerging Asian contract fermentation hubs threaten European packaging volume share. For New Entrants and Emerging Players: Launch via India's PLI scheme production-linked incentives to establish local biopolymer manufacturing with guaranteed offtake from Maharashtra and Gujarat packaging converters. Target lignocellulosic residue valorization in Southeast Asia as the most penetrable white-space opportunity, where agricultural waste streams offer untapped feedstock pools for second-generation platform chemicals without food market competition. For Investors and Strategic Acquirers: Fermentation yield improvements achieving cost parity without subsidy dependence is the leading indicator that bio-based platform chemicals have crossed into sustainable margin structures. Acquisition targets should concentrate on industrial biotechnology specialists with proprietary enzymatic catalysis platforms and metabolic pathway design expertise, as talent scarcity in fermentation process engineering constrains scale-up velocity across the competitive landscape.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Corridors | Cargill's Blair complex and Braskem's Triunfo facility demonstrate cost parity through captive corn and sugarcane supply. |
| Mass-Balance Certification Infrastructure | ISCC PLUS chain-of-custody documentation secures long-term offtake from EU packaging converters facing Carbon Border Adjustment Mechanism compliance. |
| Continuous Processing Technology Adoption | Real-time quality control systems displace batch fermentation, compressing capital intensity for specialty chemical manufacturers. |
| Cell-Free Enzymatic Synthesis Integration | Elimination of metabolic burden enables higher product titers for pharmaceutical intermediates serving Swiss and Indian contract manufacturers. |
| Joint Venture with Automotive OEM Coolant Formulators | Technical collaboration on biopropylene glycol formulation compatibility accelerates petroleum-derived MEG substitution in Germany and Japan. |
Research Methodology
Trade databases, ECHA REACH registration filings, and customs export records formed the secondary backbone, supplemented by SEC 10-K disclosures from diversified chemical conglomerates and ANVISA regulatory acceptance documentation for bio-based food contact materials. Primary fieldwork encompassed fermentation process engineers at integrated biorefineries, procurement leads at German flexible packaging converters, technical directors at automotive coolant formulators, and certification auditors at ISCC PLUS-accredited bodies. Bottom-up volume estimates triangulated against top-down demand projections from end-use industry consumption patterns.
Historical trendline analysis tracked fermentation yield improvements and feedstock cost movements across the projection horizon, with segmentation modeling across product chemistry, application vertical, and regional production hub dimensions. CAGRs derived from unit economics convergence trajectories between bio-fermentation pathways and naphtha-derived benchmarks. Industry-specific forecast inputs incorporated EU Green Deal carbon intensity threshold implementation timelines and METI Biomass Plastics Strategy mandatory renewable content phase-ins.
Feedstock competition with food markets, enzymatic catalysis yield ceilings for lignocellulosic conversion, and REACH authorization timeline extensions are the dominant revision risks that could compress growth trajectories or accelerate competitive consolidation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart TV Platforms Market
Others
UK Cat Food Market
Others
Infant Positioning Aids Market
Others
China Packaging Primers Market
Others
Foldable Smartphone Market
Others
Smart Badge Market
Others
India Data Center Physical Security Market
Others
Rope Market
Others
Deep Sea Mining Market
Others
Profilometer Market
Others
Industrial Air Pollution Control Solutions Market
Others
Japan Coal Market
Others
North America Healthcare Flexible Packaging Market
Others
LAMEA Astrology Market
Others
Bicycle Panniers Market
Others
Connected TV Market