
 Global Hospital Linen Supply and Management Services Market | 2026-2036
Global Hospital Linen Supply and Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hospital Linen Supply and Management Services Market Foresight
Market Context
Surgical centers is rebalancing the buyer mix as hospitals outsource non-core linen operations to specialized vendors. Cintas Corporation leverages its national service network to capture multi-facility contracts across integrated delivery networks. Aramark Corporation anchors its position through long-term food-and-facilities bundling that locks in linen volumes. ImageFIRST Healthcare Laundry Specialist differentiates through dedicated healthcare focus and infection prevention protocols.
Technical Definition and Segment Structure
Hospital linen supply and management services encompass the commercial provisioning, laundering, inventory control, and lifecycle tracking of reusable textiles including surgical gowns, patient bedding, and operating room drapes, processed to meet healthcare-grade hygiene standards through thermal disinfection and barrier validation. Laundry management commands the largest revenue share within service type due to capital-intensive processing infrastructure and regulatory compliance burdens. Operating rooms application generates premium pricing relative to patient bedding because of stringent sterility requirements and shorter replacement cycles. Contractual agreements dominate distribution channels as multi-year service contracts reduce procurement friction and stabilize vendor capacity planning.
Regulatory Framework and Outlook
The FDA governs reusable medical textiles as Class I devices, while OSHA enforces worker exposure limits in commercial laundry facilities, and the EPA regulates wastewater discharge from high-temperature washing operations. These overlapping standards elevate capital requirements for processing equipment and create barriers to unlicensed market entry. Stakeholders must monitor how FDA guidance evolution and state-level hospital infection control mandates reshape certification requirements for linen service providers.
Market Dynamics
Hospital consolidation across the United States is compressing vendor relationships into multi-facility service agreements, forcing linen providers to restructure operations around centralized distribution hubs and unified infection-control protocols.
Growth Catalysts
- Outsourcing momentum in surgical centers:Ambulatory surgery centers are expanding linen management programs as patient volumes rise, creating dedicated demand for specialized healthcare laundry services with validated thermal disinfection cycles.
- FDA guidance elevation:Updated FDA regulations on reusable medical textiles as Class I devices are mandating stricter barrier validation and documentation, accelerating facility transitions to certified commercial processors.
- Centralized procurement in integrated delivery networks:Hospital system mergers are consolidating purchasing authority, enabling vendors to capture multi-year contracts spanning dozens of facilities under unified service-level agreements.
Market Restraints
- Capital intensity of processing infrastructure:Continuous-batch washer-extractors, tunnel finishers, and barrier-isolated clean rooms require seven-figure investments that lock out regional competitors and compress returns during contract ramp periods.
- Energy cost volatility:Natural gas and electricity price swings directly impact thermal disinfection economics, squeezing margins for processors locked into fixed-rate multi-year hospital contracts.
- Water discharge compliance:EPA wastewater regulations for high-temperature laundry operations impose treatment infrastructure costs and permitting delays that extend facility commissioning timelines.
Strategic Opportunities
- Rural hospital penetration:Community hospitals and critical access facilities in the United States remain underpenetrated by national service networks, presenting acquisition targets for regional operators with established route density.
- RFID-enabled lifecycle tracking:Convergence of radio-frequency identification with cloud-based inventory management is enabling usage-based billing models that align vendor revenue with actual textile consumption rather than flat fees.
- EU MDR alignment services:European Medical Device Regulation harmonization is creating advisory demand for US-based processors seeking to export barrier-validated surgical textiles to EU member states.
Industry Challenges
- Certified maintenance technician scarcity:Commercial laundry equipment requiring specialized knowledge of thermal validation systems and FDA documentation protocols faces recruiting constraints in regional labor markets.
- Legacy ERP integration friction:Hospital materials management systems often lack API connectivity with vendor inventory platforms, forcing manual data reconciliation and delaying real-time linen availability visibility.
- Replacement cycle compression:Accelerated surgical textile wear from enhanced washing protocols is shortening asset lifespans faster than depreciation schedules, pressuring capital planning accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hospital Linen Supply and Management Services Market |
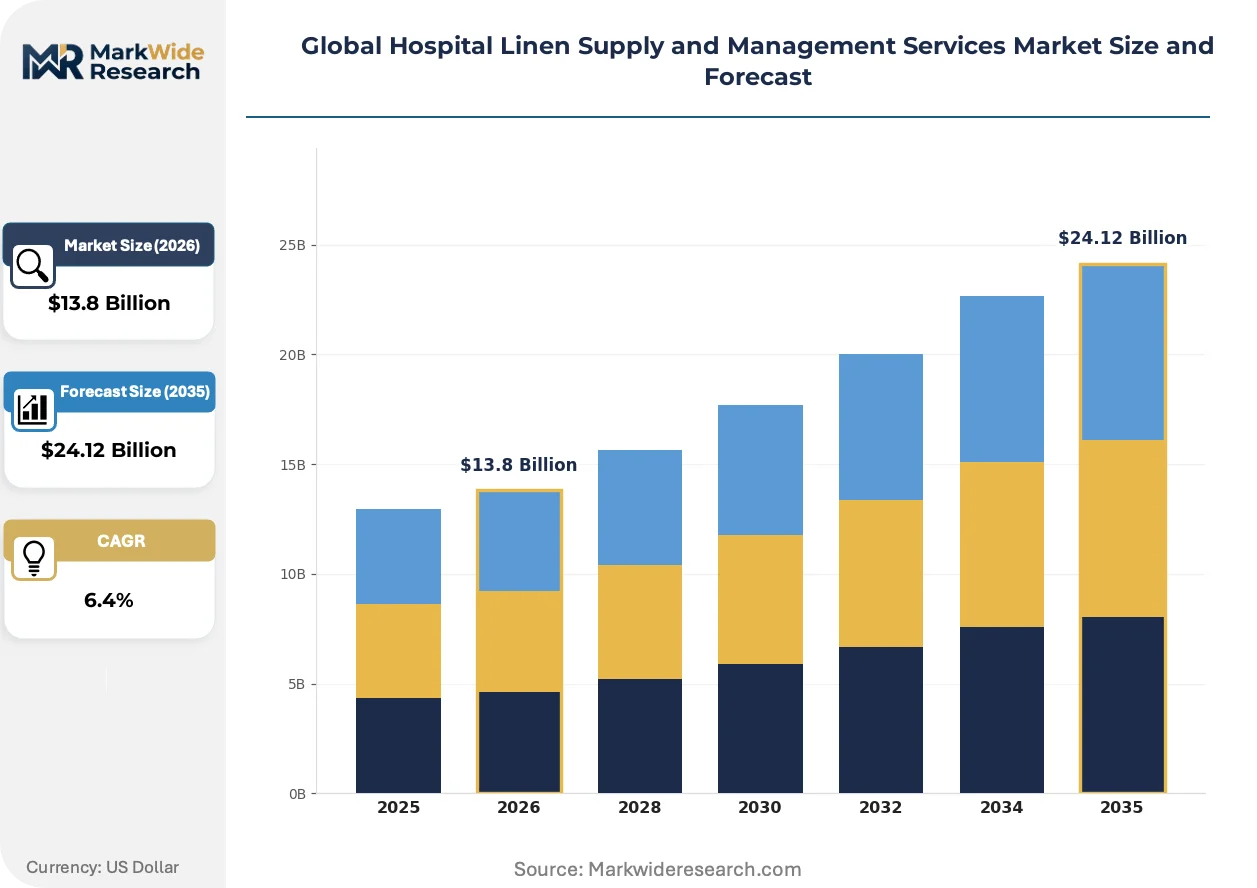
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Linen Rental, Laundry Management, Inventory Management, Linen Repair, Tracking & Monitoring End User: Hospitals, Surgical Centers, Long-Term Care Facilities, Dialysis Centers Distribution Channel: Direct Sales, Online Platforms, Third-Party Distributors, Contractual Agreements Application: Patient Bedding, Operating Rooms, Emergency Services, Diagnostic Centers, Rehabilitation Units |
| Companies Covered | Alsco Inc., UniFirst Corporation, Aramark Corporation, Mission Linen Supply, Rentokil Initial plc, Cintas Corporation, ImageFIRST Healthcare Laundry Specialist, Unitex Textile Rental Services, Elis S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hospital Linen Supply and Management Services Market Shifts & Advancements
Digital tracking technologies and regulatory harmonization are converging to reshape how linen services demonstrate compliance, optimize logistics, and structure commercial relationships with healthcare buyers.
Radio-frequency identification (RFID) chips embedded in surgical gowns and patient bedding are unifying inventory visibility across hospital campuses and vendor facilities. Integrated delivery networks in the United States are mandating RFID compatibility in new service contracts. This technology is unifying previously siloed data streams into single-source-of-truth platforms that compress reconciliation cycles and enable predictive replenishment.
REACH substance restrictions in the European Union are tightening chemical input standards for textile finishing agents used in reusable medical fabrics. Industrial laundries serving EU export markets must reformulate detergent chemistries and validate alternative barrier coatings. Surgical drape manufacturers with EU distribution exposure are accelerating substitution timelines for legacy fluorocarbon treatments.
Performance-based service agreements are displacing flat-fee linen contracts in US hospital procurement. Materials managers now tie vendor payments to infection prevention metrics, shortage rates, and turnaround time guarantees. This contracting evolution is most visible in the southeastern United States, where health system consolidation has concentrated purchasing leverage and standardized vendor scorecard methodologies.
Global Hospital Linen Supply and Management Services Market Segmentation

Hospital linen supply and management services fragment across service delivery models, end-user scale, and clinical application intensity. Each segment carries distinct capital requirements, regulatory exposure, and margin profiles that reshape competitive positioning across the value chain.
Service Type:
Supply concentration in thermal processing infrastructure creates divergent economics across service models, with capital intensity acting as the primary segmentation driver.
- Laundry Management:Continuous-batch washer-extractors and tunnel finishers demand seven-figure capital commitments. Demand concentrates in United States integrated delivery networks seeking validated thermal disinfection cycles with documented FDA compliance. Energy cost volatility directly compresses processor margins under fixed-rate hospital contracts.
- Inventory Management:Cloud-based platforms with RFID-enabled tracking unify previously siloed data streams across hospital campuses. United States health systems are mandating RFID compatibility in new procurement cycles, enabling usage-based billing models that displace flat-fee structures. The fastest-growing trajectory sits here as predictive replenishment contracts expand.
- Linen Rental:Asset ownership shifts textile replacement risk from hospitals to vendors, requiring working capital reserves for accelerated wear cycles from enhanced washing protocols.
- Linen Repair:Barrier revalidation and seam reinforcement extend surgical textile lifespans, serving cost-constrained community hospitals in rural United States markets.
- Tracking & Monitoring:Lifecycle visibility tools integrate with hospital ERP systems, though API connectivity gaps force manual reconciliation at legacy facilities.
Today's leader: Laundry Management. Tomorrow's challenger: Inventory Management.
End User:
Customer scale determines contract structure, with facility consolidation trends compressing vendor relationships into multi-facility agreements.
- Hospitals:Acute care facilities generate the largest absolute linen volumes, with operating room textiles commanding premium pricing for sterility assurance. United States hospital mergers are consolidating purchasing authority under centralized procurement functions. Contract duration typically extends 3-5 years with unified infection-control protocols.
- Surgical Centers:Ambulatory surgery centers are expanding linen management programs as patient volumes rise, creating dedicated demand for specialized healthcare laundry with validated thermal disinfection. These facilities prioritize flexibility over scale, favoring regional processors with rapid turnaround capabilities.
- Long-Term Care Facilities:Extended patient stays elevate bedding replacement frequency, though reimbursement pressures constrain pricing tolerance for premium services.
- Dialysis Centers:High-frequency patient touchpoints generate predictable, recurring linen demand with standardized textile specifications across clinic networks.
Contract value concentrates in Hospitals. Volume growth accelerates fastest in Surgical Centers.
Distribution Channel:
Channel selection reflects procurement sophistication, with larger health systems gravitating toward relationship-based structures that reduce transaction friction.
- Contractual Agreements:Multi-year service contracts stabilize vendor capacity planning and align payment terms with infection prevention metrics. United States southeastern health systems have standardized vendor scorecard methodologies that tie payments to shortage rates and turnaround guarantees. These agreements dominate revenue concentration across the sector.
- Direct Sales:National service networks leverage established route density to capture multi-facility contracts, though legacy ERP integration friction delays real-time visibility.
- Third-Party Distributors:Regional operators use distributor relationships to extend geographic reach without capital-intensive facility expansion.
- Online Platforms:Digital procurement portals serve smaller facilities with standardized product catalogs, though clinical linen specifications limit pure self-service adoption.
Procurement leverage flows through Contractual Agreements. Digital adoption advances fastest in Online Platforms.
Application:
Clinical risk tier determines textile specification, processing intensity, and replacement cycle velocity across hospital departments.
- Operating Rooms:Surgical gowns and drapes require barrier validation, sterile packaging, and shortest replacement cycles due to contamination protocols. Premium pricing reflects stringent FDA documentation requirements and validated thermal disinfection standards. Demand concentrates in United States surgical centers expanding outsourced programs.
- Patient Bedding:Higher volume but lower unit value, with standard thermal disinfection sufficient for non-sterile applications. United States long-term care facilities drive steady replacement demand.
- Emergency Services:Unpredictable volume spikes stress inventory buffers, favoring vendors with regional distribution hubs and rapid replenishment capabilities.
- Diagnostic Centers:Moderate throughput with specialized drape requirements for imaging equipment, creating niche demand for custom textile dimensions.
- Rehabilitation Units:Extended patient stays with standard bedding specifications, prioritizing durability over clinical barrier performance.
Premium capture belongs to Operating Rooms. Volume expansion is climbing the fastest in Patient Bedding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States hospital consolidation wave is compressing vendor relationships into multi-facility service agreements spanning integrated delivery networks. Germany's commercial laundry sector faces REACH substance restrictions on textile finishing agents. Japan's aging demographic is elevating long-term care linen demand while thermal disinfection standards tighten.
United States
Hospital mergers in the southeastern United States are consolidating purchasing authority under centralized procurement functions. FDA guidance on reusable medical textiles as Class I devices mandates stricter barrier validation documentation. Texas and Florida health systems are standardizing vendor scorecard methodologies that tie payments to infection prevention metrics.
Germany
Industrial laundries serving EU export markets must reformulate detergent chemistries under REACH restrictions on fluorocarbon treatments. The country's national healthcare regulator aligns with EU MDR harmonization for barrier-validated surgical textiles. The Rhine-Ruhr industrial corridor hosts specialized processors investing in thermal validation infrastructure.
Japan
Extended patient stays in geriatric care facilities elevate bedding replacement frequency beyond acute-care benchmarks. METI oversees industrial energy efficiency standards that impact thermal disinfection economics. The Kanto region around Tokyo concentrates demand from super-aging municipalities seeking outsourced linen management.
China
Domestic hospital groups are expanding outsourced linen programs as patient volumes rise in tier-two cities. NMPA regulations govern reusable medical textiles with escalating documentation requirements. The Yangtze River Delta industrial cluster is attracting commercial laundry investment to serve concentrated hospital networks.
United Kingdom
NHS procurement frameworks are consolidating linen service contracts under national purchasing agreements. The country's national healthcare regulator enforces infection control mandates that reshape vendor certification requirements. The Midlands region hosts processors specializing in rapid-turnaround surgical textile services for ambulatory centers.
Global Hospital Linen Supply and Management Services Market Competitive Landscape
Multi-facility contract capture dominates the current landscape as hospital consolidation compresses vendor relationships. The vendor base clusters around three archetypes: national service networks with route density advantages, healthcare-specialized processors with dedicated infection prevention protocols, and diversified facilities managers bundling linen with food service. M&A activity and RFID technology licensing represent the primary competitive vectors reshaping market position.
Within the national network tier, Cintas Corporation and UniFirst Corporation exemplify scale-driven operators leveraging established route infrastructure. Aramark Corporation occupies a position as a diversified facilities manager anchoring linen volumes through long-term bundling agreements. ImageFIRST Healthcare Laundry Specialist represents the healthcare-pure-play archetype, differentiating through dedicated clinical focus rather than cross-sector diversification.
| Leading Market Players |
|---|
| Alsco Inc. |
| UniFirst Corporation |
| Aramark Corporation |
| Mission Linen Supply |
| Rentokil Initial plc |
| Cintas Corporation |
| ImageFIRST Healthcare Laundry Specialist |
| Unitex Textile Rental Services |
| Elis S.A. |
| Others |
Supply & Pricing Matrix
Natural gas futures benchmarks cascade directly into thermal disinfection cost tiers, with United States processors passing through energy volatility to surgical centers on fixed-rate contracts while reserving flexible pricing for integrated delivery networks with volume guarantees.
Pricing Analysis
Input-cost pass-through dominates contract economics, with energy and cotton fiber indices feeding into three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FDA barrier-validation tier and geographic delivery density, with rural hospital premiums reflecting route inefficiency. Pricing pressure stems from fixed-rate multi-year hospital contracts locking processors into margin compression during energy spikes. Surgical centers exhibit highest price sensitivity due to reimbursement constraints, while operating room textiles command lowest sensitivity given sterility non-negotiability.
Supply Chain Analysis
Regional distribution centers in Texas, Florida, and Ohio anchor hub-and-spoke patterns serving southeastern United States health systems. Cotton sourcing draws from Texas high-plains growers and Egyptian long-staple suppliers, with polyester blends imported from China. Single-source vulnerability concentrates in specialized barrier-coating chemistries subject to EPA discharge restrictions. Distribution runs through vendor-managed inventory programs with hospital ERP integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States energy-cost exposure and European REACH compliance burdens, with processors able to bridge both jurisdictions capturing premium positioning.
For Market Incumbents: Extend RFID-enabled lifecycle tracking capabilities into predictive replenishment contracts before regional competitors achieve scale. Consolidate route density through acquisition of critical-access hospital networks in rural Texas and Florida to defend against emerging pure-play healthcare specialists. Certification investment in EU MDR alignment creates defensible export positioning. For New Entrants and Emerging Players: Surgical center partnerships offer the most penetrable channel, with ambulatory facilities in the southeastern United States prioritizing rapid turnaround over national scale. Target community hospitals in rural markets with linen repair and barrier revalidation services that national networks underserve. Go-to-market leverage rests on thermal validation documentation superior to incumbent legacy protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with regional operators possessing established route density in underpenetrated United States rural markets and clean regulatory histories. Long-term viability favors processors with backward integration into textile manufacturing and captive energy hedging. Watch FDA guidance evolution on Class I device documentation as inflection indicator for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Platform Integration | Enables usage-based billing models that displace flat-fee contracts in United States IDNs. |
| EU MDR Certification Pathway | Opens export channels for barrier-validated surgical textiles to German and French hospital systems. |
| Regional Distribution Hub Expansion | Compresses turnaround times for ambulatory surgery centers in Texas and Florida corridors. |
| Backward Integration into Textile Manufacturing | Captures margin from accelerated surgical gown replacement cycles under enhanced washing protocols. |
| Hospital System Partnership | Locks multi-facility volumes through unified infection-control scorecards in consolidated southeastern networks. |
Research Methodology
Direct dialogue with hospital materials managers, commercial laundry operations directors, GPO contracts specialists, and FDA regulatory consultants grounded qualitative findings, cross-referenced against EPA discharge filings, hospital procurement databases, energy cost indices, and CMS Medicare cost reports. Bottom-up facility-level capacity modeling and top-down health system expenditure analysis provided triangulation.
Segmented outputs across service type, end-user scale, application intensity, and regional regulatory clusters informed the projection framework throughout the forecast period. CAGRs derived from weighted average of historical contract value growth and forward-looking health system consolidation trajectories. Thermal disinfection energy intensity and surgical textile replacement velocity served as industry-specific demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance evolution, natural gas price volatility, and hospital merger regulatory approval timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Smart Face Masks Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Suture Sleeve Kit Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Pre-Packaged Medical Supplies Market