
 Heavy Wall Bottles Market | 2026-2036
Heavy Wall Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Wall Bottles Market Foresight
Polyethylene terephthalate (PET) is decoupling heavy wall bottle economics from traditional glass dependency by offering comparable barrier performance at reduced weight and lower thermal processing costs. Gerresheimer leverages its pharmaceutical glass expertise to sustain premium positioning in injectable and diagnostic packaging. Zignago Vetro anchors Mediterranean supply chains through vertical control over raw silica sourcing and furnace operations. Bormioli Luigi differentiates via decorative glass capabilities that command price premiums in prestige fragrance and spirits segments.
Heavy wall bottles are rigid containers engineered with wall thicknesses substantially exceeding standard packaging specifications, typically manufactured through extrusion blow molding, injection blow molding, or glass forming processes to withstand internal pressure, thermal stress, and mechanical impact in demanding logistics environments. Glass bottles retain dominance in pharmaceutical and high-end cosmetic applications where inertness and oxygen barrier properties are non-negotiable, while HDPE bottles capture institutional cleaning product volumes where chemical resistance and cost efficiency outweigh aesthetic requirements. PET bottles represent the fastest-expanding product category as resin recycling infrastructure matures and brand owners specify post-consumer content targets.
The FDA enforces stringent USP Type I-III glass standards for pharmaceutical packaging, directly dictating material selection and qualification protocols for any supplier accessing US drug distribution channels. The EU MDR and REACH frameworks impose additional traceability and substance restriction obligations on European-market bottles, particularly for devices incorporating plasticizers or colorants. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return mandates, as these mechanisms will increasingly determine viable business models and geographic manufacturing footprints.
Market Dynamics
Pharmaceutical serialization mandates and biologics proliferation are compressing qualification timelines for heavy wall bottles while elevating barrier performance requirements beyond commodity specifications.
Growth Catalysts
- Biologics packaging demand:Injectable formulations and cell therapies require Type I borosilicate glass with enhanced thermal shock resistance, pulling capacity toward pharmaceutical-grade production.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases accelerate furnace technology upgrades and lightweighting investments across European glass manufacturing.
- Post-consumer PET recycling infrastructure:Mature mechanical and chemical recycling streams enable brand owners to specify verified recycled content thresholds for cosmetic and beverage applications.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings in Germany and Italy directly compress margins for soda-lime glass furnace operations.
- Silica sand supply concentration:High-purity silica sourcing clusters in specific Mediterranean and North African regions create geopolitical exposure for container glass producers.
- Aluminum and flexible pouch substitution:Aseptic cartons and aluminum bottles capture share in premium beverage segments where portability outweighs glass aesthetics.
Strategic Opportunities
- Indian pharmaceutical export growth:CDSCO-aligned manufacturing investments create demand for USP-certified heavy wall bottles serving regulated export markets.
- Deposit-return scheme expansion:Germany, Sweden, and Denmark are extending mandatory return systems to cosmetic and pharmaceutical glass, incentivizing closed-loop material flows.
- Digital printing convergence:Direct-to-glass inkjet and laser marking technologies enable lot-level traceability without label substrates, reducing material complexity.
Industry Challenges
- Pharmaceutical qualification timelines:USP Type I-III certification protocols and extractables/leachables testing extend new product introduction cycles to 18-24 months.
- Furnace rebuild capex intensity:End-of-life regenerative furnace replacements require capital deployment exceeding standard maintenance budgets by an order of magnitude.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Wall Bottles Market |
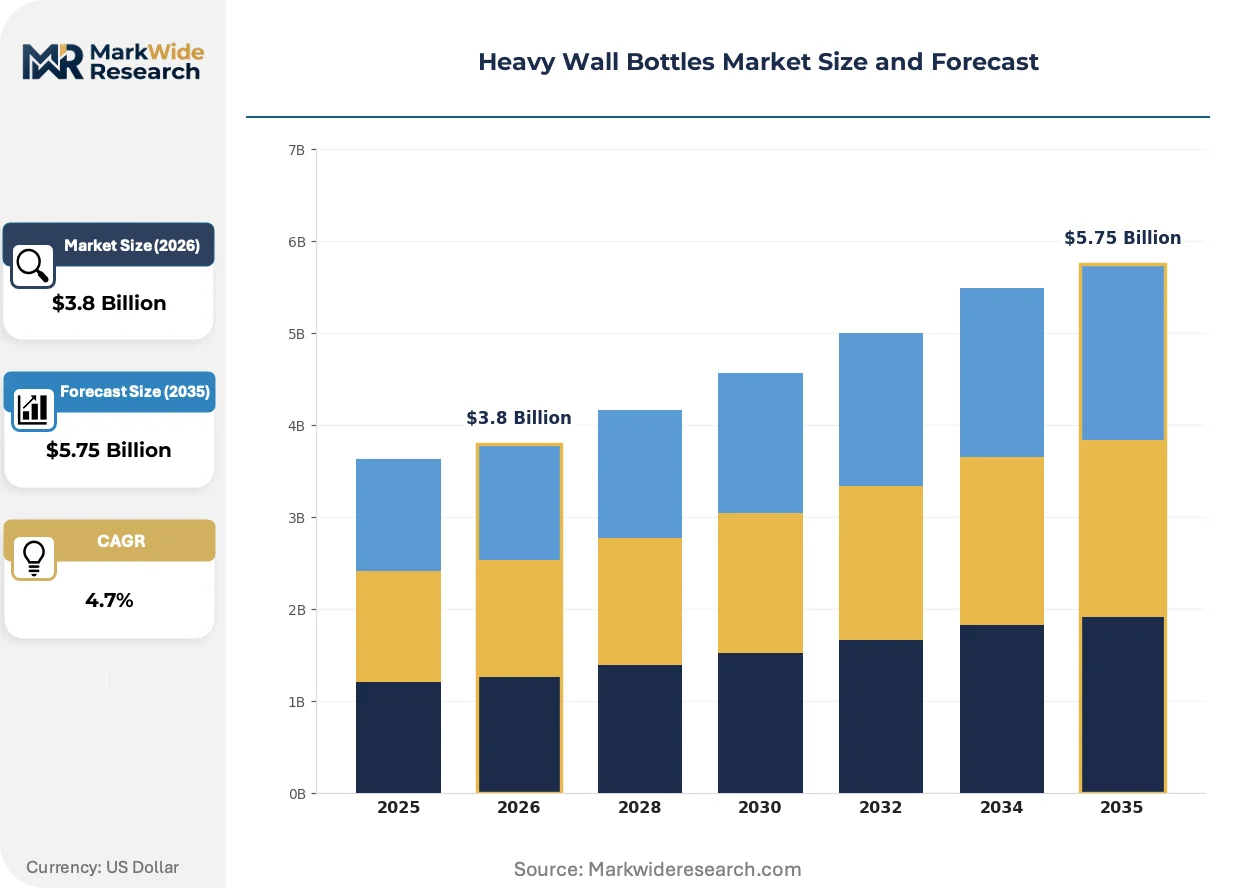
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Bottles, HDPE Bottles, Glass Bottles, PVC Bottles Capacity: 250ml, 500ml, 1L, 2L End User: Food & Beverage, Pharmaceuticals, Personal Care, Cleaning Products Closure Type: Screw Cap, Flip-Top Cap, Pump Dispenser, Trigger Sprayer |
| Companies Covered | Gerresheimer, Zignago Vetro, Vitro Packaging, Bormioli Luigi, Pochet, SGD Group, HEINZ GLAS, Stolzle Glass, Piramal Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Wall Bottles Market Shifts & Advancements
Material science advances and regulatory traceability requirements are bifurcating heavy wall bottle production into high-performance pharmaceutical lines and sustainability-optimized commodity platforms.
Plasma-enhanced chemical vapor deposition (PECVD) barrier coatings are expanding into pharmaceutical and sensitive cosmetic applications where glass inertness must be preserved while weight reduction targets tighten. Contract manufacturers serving biologics fill-finish operations are qualifying silicon oxide and diamond-like carbon coatings at accelerated rates. This technology is expanding into markets previously reserved for multilayer plastic or aluminum barrier solutions, compressing the performance gap between glass and advanced polymer alternatives.
REACH substance restrictions and SCIP database obligations are forcing reformulation of decorative coatings, colorants, and surface treatments across European cosmetic glass supply chains. ECHA enforcement of candidate list substance notifications now extends to imported articles, compelling non-EU suppliers to establish European-based testing and documentation capabilities. Fragrance and skincare brands with premium glass dependencies are responding by consolidating supplier bases to entities with established EU regulatory infrastructure.
Direct-to-brand e-commerce channels are fragmenting traditional distributor-centric procurement patterns for mid-volume cosmetic and specialty beverage applications. Brand owners are establishing captive specification teams and auditing glassworks directly, bypassing legacy packaging intermediaries. This pattern is most visible in German and French prestige fragrance markets where limited-edition runs and rapid SKU rotation demand compressed sourcing timelines.
Heavy Wall Bottles Market Segmentation
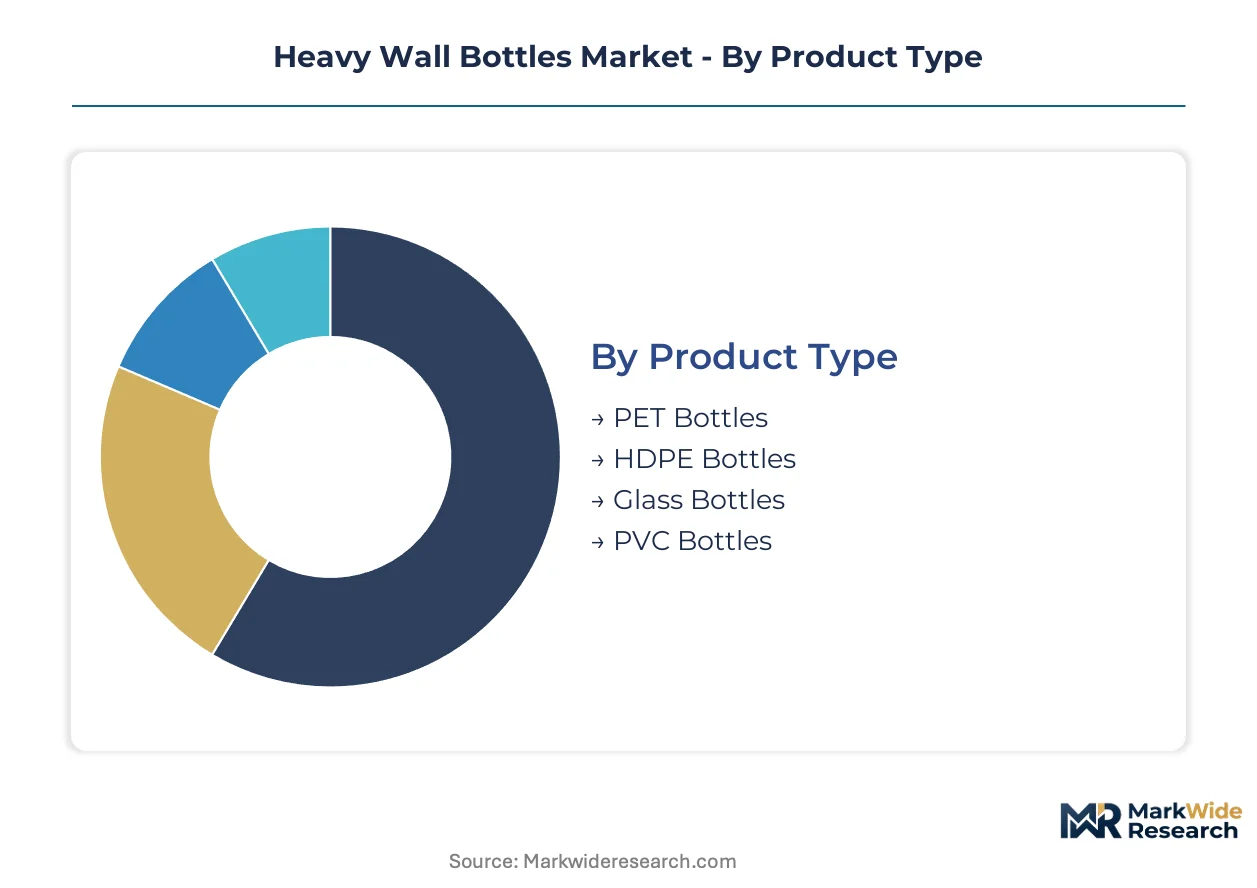
Heavy wall bottle procurement decisions hinge on material certification requirements, capacity logistics, and closure compatibility with automated filling lines. Segmentation reveals how pharmaceutical-grade specifications diverge sharply from commodity packaging economics across material and end-use categories.
Product Type:
USP Type I-III glass standards, FDA food-contact regulations, and REACH substance restrictions create divergent compliance burdens across material platforms.
- Glass Bottles:Borosilicate and soda-lime compositions deliver inert surfaces required for parenteral pharmaceuticals and biologics. Germany's Gerresheimer and Italy's Bormioli Luigi anchor European pharmaceutical-grade capacity, though energy cost volatility in German furnace operations compresses margins.
- PET Bottles:Post-consumer recycled content capabilities and mechanical recycling infrastructure maturity position this segment for cosmetic and beverage brand owner sustainability mandates. Chemical vapor deposition barrier coatings now extend PET into applications previously reserved for glass or aluminum.
- HDPE Bottles:Institutional cleaning product volumes favor this resin for chemical resistance and cost efficiency in high-throughput manufacturing.
- PVC Bottles:Niche industrial applications persist where specific chemical compatibility requirements outweigh sustainability headwinds from chlorine-based resin production.
Glass bottles sit at the top of the volume ranking, with PET bottles climbing the fastest.
Capacity:
Logistics cost structures and retail shelf-space economics concentrate demand at specific volume thresholds that optimize pallet density and consumer handling.
- 500ml:Prestige fragrance and skincare applications standardize on this format for countertop display aesthetics and travel retail compliance. German and French brand owners specify this capacity for limited-edition runs requiring rapid SKU rotation.
- 1L:Pharmaceutical oral solutions and diagnostic reagents concentrate procurement here, balancing dosing convenience with warehouse handling efficiency. CDSCO-aligned Indian exporters source this capacity for regulated market shipments.
- 250ml:Sample sizes and clinical trial packaging drive demand from contract manufacturing organizations serving biologics development pipelines.
- 2L:Institutional cleaning concentrates and industrial chemical applications utilize this format for dilution ratios and bulk dispensing economics.
500ml formats command the highest unit margins, with 1L volumes expanding most quickly in pharmaceutical export channels.
End User:
Extractables-leachables testing protocols and serialization mandates fragment supplier qualification requirements across application categories.
- Pharmaceuticals:Injectable formulations, cell therapies, and diagnostic packaging require Type I borosilicate glass with documented thermal shock resistance. FDA USP standards and EU MDR traceability obligations extend qualification timelines to 18-24 months for new bottle introductions.
- Personal Care:Prestige fragrance and skincare brands specify decorative glass with direct-to-container digital printing for lot-level traceability without label substrates. REACH SCIP database compliance forces reformulation of coatings and colorants across European supply chains.
- Food & Beverage:Oxygen barrier requirements and deposit-return scheme participation drive material selection toward lightweight glass or advanced barrier PET in German, Swedish, and Danish markets.
- Cleaning Products:Chemical resistance priorities favor HDPE for institutional and household formulations where aesthetic requirements are secondary to cost efficiency.
Pharmaceutical applications carry the steepest certification burden, with personal care segments gaining share fastest through e-commerce channel fragmentation.
Closure Type:
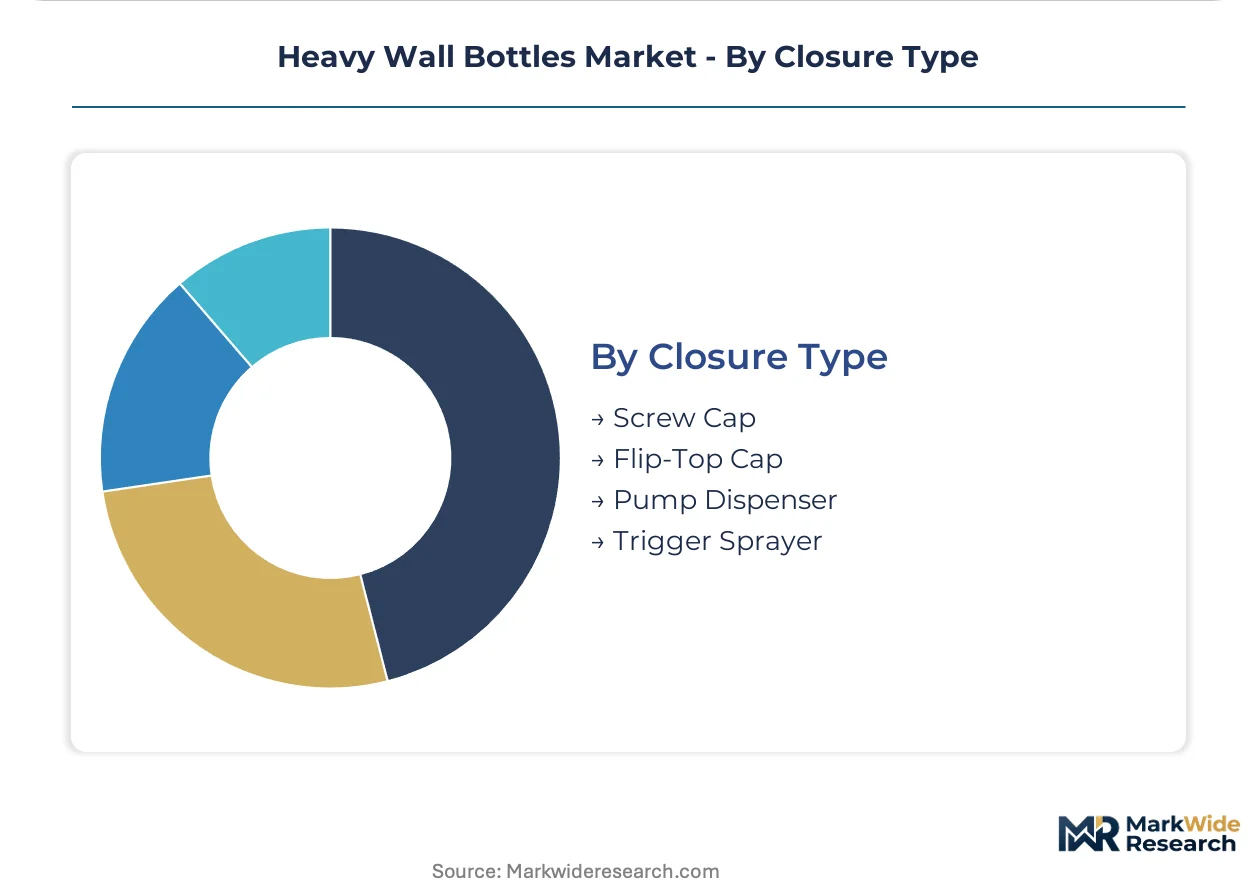
Automation compatibility and child-resistance mandates determine specification patterns across pharmaceutical and consumer applications.
- Screw Cap:Universal threading standards and tamper-evident band integration position this closure across pharmaceutical oral solids and beverage applications. FDA 21 CFR compliance for food-contact and drug packaging concentrates procurement with qualified European and North American molders.
- Pump Dispenser:Viscous skincare and haircare formulations require precise dose control and airless chamber designs that preserve product integrity through consumption cycles. German cosmetic brand owners specify this closure for premium positioning.
- Flip-Top Cap:Single-handed operation favors personal care and food applications where convenience drives repeat purchase behavior.
- Trigger Sprayer:Cleaning product formulations utilize this mechanism for directional application and dilution ratio control in institutional and household settings.
Screw caps dominate unit volumes across all end-use categories, with pump dispensers showing the strongest expansion in prestige personal care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German glassworks clusters in Düsseldorf-Ruhr and Bavaria anchor European pharmaceutical-grade heavy wall bottle capacity, though furnace energy costs and regulatory compliance burdens reshape competitive positioning across manufacturing geographies.
Germany
Injectable biologics and cell therapy packaging pull capacity toward Type I borosilicate glass production. The EU F-Gas Regulation and national industrial energy policies accelerate furnace technology upgrades. Gerresheimer and HEINZ GLAS concentrate specialized operations in North Rhine-Westphalia and Bavaria to serve CDMO fill-finish networks.
United States
FDA USP Type I-III certification requirements concentrate procurement with qualified suppliers serving generic injectable and diagnostic reagent markets. The FDA enforces extractables-leachables testing protocols that extend qualification timelines. New Jersey and Pennsylvania host contract manufacturing clusters where serialization mandates drive bottle traceability investments.
Italy
Prestige fragrance and decorative glass applications sustain demand for ornamental heavy wall bottles with digital printing capabilities. REACH SCIP database obligations force reformulation of coatings across Veneto and Lombardy glassworks. Bormioli Luigi anchors specialized capacity in Emilia-Romagna for limited-edition cosmetic runs.
India
CDSCO-aligned pharmaceutical exports create demand for USP-certified heavy wall bottles serving regulated markets in North America and Europe. Maharashtra and Gujarat host manufacturing investments targeting contract research organization supply chains. Piramal Glass concentrates operations in western states to capture biologics packaging growth.
France
Luxury skincare brand owners specify decorative glass with direct-to-container traceability for e-commerce channels. ECHA enforcement of candidate list substance notifications extends to imported articles. Pochet maintains specialized capacity in Normandy for prestige fragrance applications requiring rapid SKU rotation.
Heavy Wall Bottles Market Competitive Landscape
Global majors compete with regional champions across certification-grade glass production, creating tiered supply dynamics where pharmaceutical qualification capabilities separate premium-tier suppliers from commodity packaging specialists. The vendor base stratifies between integrated glassworks with captive silica sourcing and contract manufacturers serving brand-specific specifications. Two archetypes dominate: European heritage glassworks with decorative capabilities and Asian pharmaceutical-grade specialists with USP certification infrastructure. Competitive moves concentrate on furnace rebuild cycles and strategic partnerships with biologics CDMOs.
Among European heritage glassworks, Gerresheimer, Bormioli Luigi, and Zignago Vetro exemplify divergent strategic positioning. Gerresheimer occupies the pharmaceutical-grade archetype with Düsseldorf-based operations serving injectable drug packaging. Bormioli Luigi represents the decorative glass specialist tier anchored in Italian manufacturing clusters for prestige cosmetic applications. Zignago Vetro sits within the vertical integration archetype through captive silica control and Mediterranean furnace operations. These three entities illustrate how geographic concentration, certification capabilities, and raw material access define competitive boundaries in heavy wall bottle supply.
| Leading Market Players |
|---|
| Gerresheimer |
| Zignago Vetro |
| Vitro Packaging |
| Bormioli Luigi |
| Pochet |
| SGD Group |
| HEINZ GLAS |
| Stolzle Glass |
| Piramal Glass |
| Others |
Supply & Pricing Matrix
Biologics fill-finish contractors demanding USP Type I borosilicate certification are compressing supplier qualification timelines and forcing furnace operators to absorb extended validation costs, which in turn stratifies pricing across pharmaceutical-grade and commodity glass tiers.
Pricing Analysis
Natural gas and electricity cost pass-through mechanisms dominate soda-lime glass pricing in German and Italian furnace operations, with energy volatility compressing margins at the commodity end. Price differentiation hinges on USP certification tier and volume scale, with Type I borosilicate commanding substantial premiums over Type III soda-lime alternatives. Pricing pressure runs through standard cosmetic glass as brand owners specify lightweighting targets and post-consumer recycled content thresholds. Institutional cleaning product buyers exhibit highest price sensitivity, while injectable biologics manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for pharmaceutical manufacturing are reshaping raw material sourcing patterns for USP-certified packaging serving export markets. Supply concentrates in Germany, Italy, and India, with high-purity silica sand dependencies anchored in Mediterranean and North African extraction clusters. Furnace rebuild cycles and regenerative technology upgrades create single-source vulnerability during capacity transitions. Distribution runs through contract manufacturing organization networks for pharmaceutical applications, while direct-to-brand procurement fragments cosmetic glass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage potential through furnace energy cost differentials between German operations facing industrial electricity volatility and Indian manufacturing clusters benefiting from lower thermal processing inputs.
For Market Incumbents: Hedge against aluminum bottle and aseptic carton substitution in premium beverage segments by accelerating PECVD barrier coating qualifications for pharmaceutical applications. Backward integration into captive silica sourcing reduces exposure to Mediterranean supply concentration, while furnace technology upgrades aligned with EU F-Gas Regulation timelines defend margin position against energy cost volatility. For New Entrants and Emerging Players: Launch via direct-to-brand e-commerce procurement channels serving mid-volume cosmetic applications in French and German prestige fragrance markets. White-space opportunities concentrate in CDSCO-aligned Indian pharmaceutical exports requiring USP certification infrastructure, and in digital printing capabilities for limited-edition SKU rotation demanding compressed sourcing timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with pharmaceutical-grade specialists possessing established FDA and EMA qualification infrastructure rather than decorative glass generalists facing REACH coating reformulation burdens. Long-term viability favors entities with furnace rebuild capital deployment capacity and biologics CDMO partnership pipelines. Watch for deposit-return scheme expansion signals across cosmetic and pharmaceutical glass as inflection indicators for closed-loop material flow economics.| Strategic Initiative | Industry Significance |
|---|---|
| USP Type I Certification Investment | Qualification infrastructure unlocks biologics packaging contracts with Gerresheimer-tier margins. |
| PECVD Barrier Coating Deployment | SiOx and diamond-like carbon coatings extend PET into glass-dominated pharmaceutical applications. |
| Regenerative Furnace Technology Upgrade | EU F-Gas Regulation compliance reduces energy intensity in German soda-lime operations. |
| Direct-to-Glass Digital Printing Integration | Lot-level traceability without label substrates meets REACH SCIP database obligations. |
| Captive Silica Sourcing Consolidation | Vertical control over high-purity sand mitigates geopolitical exposure in Mediterranean supply clusters. |
Research Methodology
Coverage spans Germany, Italy, the United States, India, and France, with primary inputs from each market triangulated against secondary validation. Interviews with pharmaceutical packaging procurement managers, glassworks operations directors, cosmetic brand specification teams, and CDMO fill-finish executives combined with FDA USP filings, ECHA REACH registrations, CDSCO export approvals, and furnace energy cost databases. Bottom-up volume modeling and top-down value reconciliation anchored the analytical framework.
Rate-of-change decomposition across material platforms, end-use applications, and capacity formats drove the projection methodology. Segmentation dimensions included glass composition tier, pharmaceutical certification level, decorative capability grade, and regional manufacturing cluster. CAGRs derived from elasticity-adjusted demand curves incorporating biologics pipeline expansion rates, EU regulatory compliance cost trajectories, and recycling infrastructure maturity indicators across the analysis window.
Several conditions sit outside the modeled scope, including unannounced furnace closures, abrupt silica sand export restrictions, and pharmaceutical serialization mandate delays. Forecasts reflect assumptions about energy cost stabilization and qualification timeline standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Combi Cans Market
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Media Bottles Market