
 Asia Pacific Beverage Packaging Market | 2026-2036
Asia Pacific Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Beverage Packaging Market Outlook
Functional beverage startups are unwinding the historical dominance of carbonated soft-drink bottlers across Southeast Asia. Tetra Pak International S.A. leverages its aseptic carton technology to anchor shelf-stable dairy and juice portfolios in China and Indonesia. Amcor plc sustains polyethylene terephthalate film leadership through lightweighting programs that reduce resin intensity per bottle. Ball Corporation dominates two-piece aluminum can supply to Vietnamese and Thai beer exporters, capitalizing on metal recycling economics.
Asia Pacific beverage packaging encompasses the engineered containment, protection, and dispensing systems for liquid consumables, typically fabricated from polyethylene terephthalate, aluminum, glass, or laminated cardboard with specified barrier properties against oxygen and light ingress. These formats must withstand pasteurization temperatures, carbonation pressures up to six volumes CO₂, and distribution humidity extremes while enabling retail shelf differentiation. Plastic bottles occupy the largest volume share across bottled water and soft drink applications, though aluminum cans represent the fastest-expanding material category as brewers and sparkling water brands exit glass. Pouches gain traction in single-serve juice and dairy segments where flexible format economics and chilled logistics infrastructure mature.
China's SAMR enforces GB standards for food-contact plastics that mandate migration testing and recyclability labeling, while India's FSSAI tightens packaging material safety protocols for bottled water and beverages. Australia's container deposit legislation and Japan's METI circular economy guidelines drive demand for mono-material and post-consumer recycled content designs. Stakeholders must monitor how ASEAN harmonization of packaging waste directives reshapes material qualification timelines and cross-border substrate acceptance.
Market Dynamics
China's dual carbon goals and Australia's container deposit schemes are forcing material redesigns across the Asia Pacific beverage packaging value chain, compressing timelines for mono-material adoption and post-consumer recycled content qualification.
Growth Catalysts
- India's bottled water surge:Urban centers in Mumbai, Delhi, and Bangalore are driving polyethylene terephthalate bottle volumes as municipal water reliability deteriorates and convenience retail expands.
- Japan's METI circular economy guidelines:These frameworks mandate recyclability labeling and design-for-disassembly protocols, accelerating aluminum can and aseptic carton investment across Japanese beverage manufacturing.
- Lightweighting technology maturation:Resin reduction programs now achieve sub-10 gram preform weights for 500ml water bottles without sacrificing carbonation pressure tolerance or drop-test performance.
Market Restraints
- Polyethylene terephthalate resin price volatility:Feedstock paraxylene and ethylene glycol costs fluctuate with crude oil movements, squeezing converter margins on fixed-price annual contracts with beverage brands.
- Chinese substrate concentration:Over 60 percent of Asia Pacific aluminum can sheet and biaxially oriented polyethylene terephthalate film originates from Chinese smelters and extruders, creating supply vulnerability during export quota adjustments.
- Glass-to-aluminum transition bottlenecks:Vietnamese and Thai brewers face filling line retooling costs and pasteurization protocol redesigns when exiting returnable glass systems.
Strategic Opportunities
- Indonesia's chilled dairy logistics expansion:Cold chain infrastructure investment in Jakarta and Surabaya enables aseptic pouch and gable-top carton penetration previously constrained by ambient distribution.
- South Korea's premium ready-to-drink tea segment:Format innovation in slim cans and transparent polyethylene terephthalate bottles commands shelf price premiums of 40-60 percent above standard offerings.
- ASEAN packaging waste directive harmonization:Cross-border material qualification standardization reduces redundant testing costs and accelerates regional product launches for multi-country brand portfolios.
Industry Challenges
- Migration testing capacity constraints:China's SAMR GB standards and India's FSSAI protocols require specialized laboratory certification that bottlenecks new product introductions by 8-14 weeks.
- Legacy filling equipment incompatibility:Converters retrofitting for lightweight preforms or aluminum bottle formats encounter pneumatic handling calibration failures and capping torque inconsistencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Beverage Packaging Market |
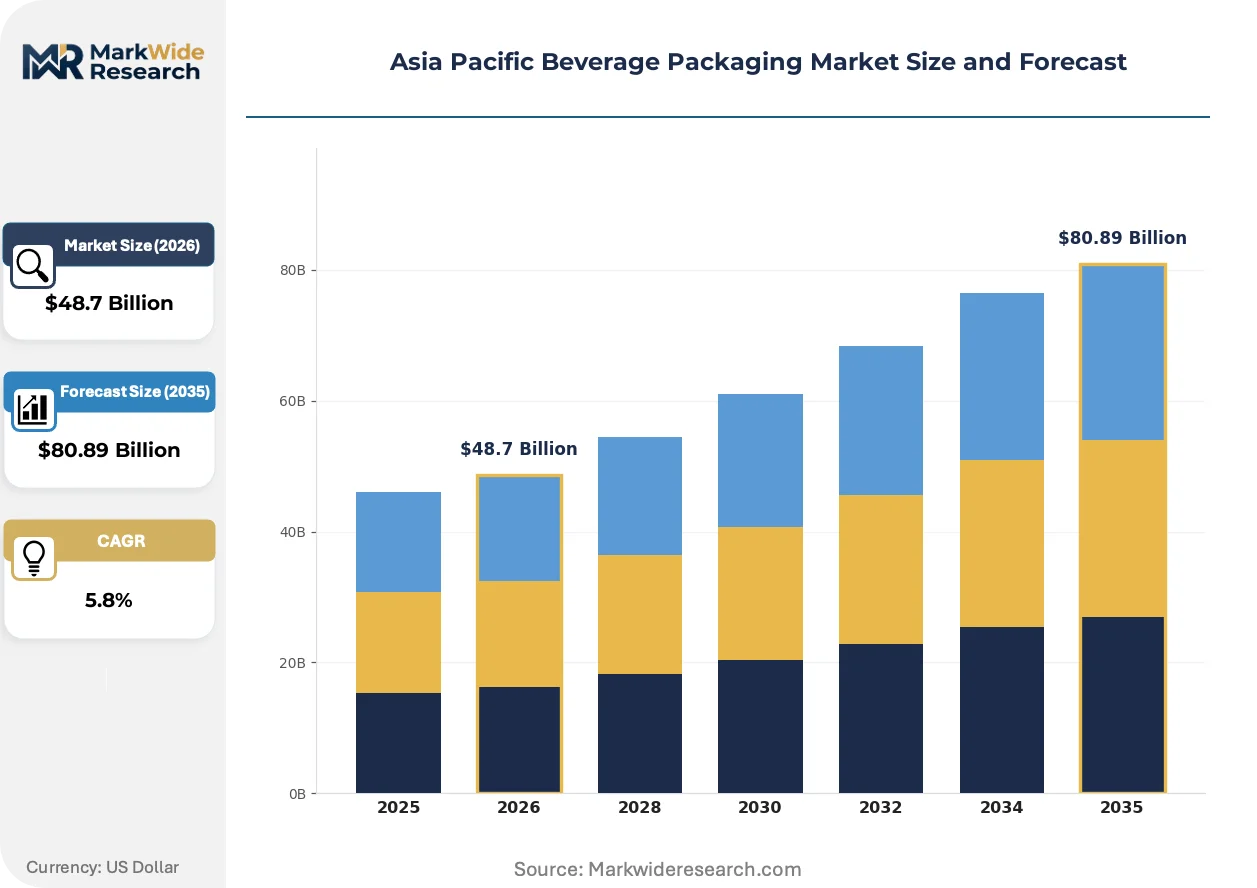
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bottles, Cans, Glass Bottles, Pouches Material: Polyethylene Terephthalate, Aluminum, Glass, Cardboard Closure Type: Screw Caps, Resealable, Corks, Snap-On Application: Soft Drinks, Juices, Alcoholic Beverages, Bottled Water |
| Companies Covered | Tetra Pak International S.A., Owens-Illinois Inc., Amcor plc, Stora Enso Oyj, Berry Global, Inc., Ball Corporation, Ardagh Group S.A., Westrock Company, Crown Holdings, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Beverage Packaging Market Strategic Shifts
Material science advances and regulatory pressure are converging to accelerate format substitution across the Asia Pacific beverage packaging market, with sustainability metrics now dictating procurement specifications ahead of unit economics.
Aluminum bottles with resealable closures are displacing glass in premium sparkling water and craft beer segments across Japan and South Korea. Suntory and Kirin have converted flagship product lines to aluminum formats since 2022. The shift compresses logistics costs through weight reduction and eliminates breakage losses while enabling full recyclability claims under METI guidelines.
Australia's container deposit legislation and China's SAMR recyclability labeling mandates are reshaping material qualification protocols. Brand owners must now submit detailed polymer composition data and end-of-life pathway documentation before market authorization. Small and mid-sized converters in Thailand and Vietnam face compliance cost burdens that favor partnership with multinational substrate suppliers possessing established testing infrastructure.
Direct-to-retail procurement platforms are fragmenting traditional distributor relationships in India's beverage packaging supply chain. Reliance Retail and D-Mart are negotiating direct converter contracts for private-label bottled water, bypassing legacy packaging traders in Mumbai and Chennai. The disintermediation concentrates volume with converters possessing national logistics networks and compresses payment cycles from 90 days to 45 days.
Asia Pacific Beverage Packaging Market Segmentation
Beverage packaging formats in Asia Pacific diverge sharply by channel requirements. Modern trade demands shelf-ready differentiation and supply chain efficiency, while traditional trade prioritizes unit economics and ambient durability.
Product Type:
Channel mix determines format dominance, with convenience stores and e-commerce driving divergent specifications across the region.
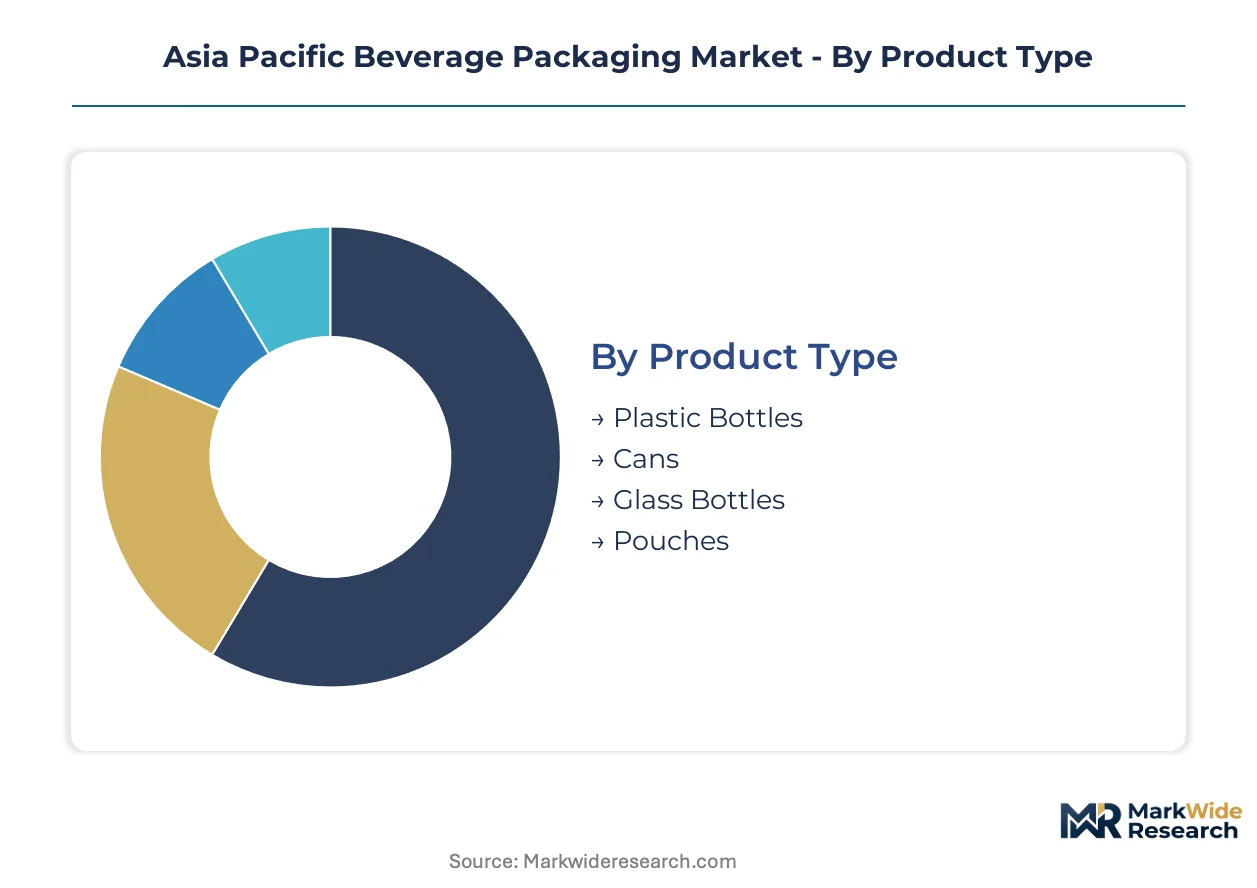
- Plastic Bottles:Polyethylene terephthalate constructions dominate bottled water and carbonated soft drinks through modern retail and vending networks. Urban centers in India and Indonesia concentrate volume as municipal water reliability gaps expand convenience-driven consumption.
- Cans:Two-piece aluminum designs withstand carbonation pressures to six volumes CO₂ while enabling full recyclability claims under Japan's METI guidelines. Vietnamese and Thai beer exporters are accelerating conversion from returnable glass, though filling line retooling costs create transition friction.
- Glass Bottles:Premium spirits and craft beer segments in Japan and South Korea sustain demand despite logistics weight penalties and breakage losses.
- Pouches:Flexible laminates penetrate single-serve juice and dairy where chilled distribution infrastructure matures in Jakarta and Surabaya.
By volume, Plastic Bottles leads. By growth pace, Cans is ahead.
Material:
Cost tier stratification separates commodity substrates from performance-grade alternatives with enhanced barrier specifications.
- Polyethylene Terephthalate:Biaxially oriented film and injection-stretch blow-molded preforms anchor mass-market soft drinks and water. China's concentration in resin and sheet production creates supply vulnerability during export quota adjustments.
- Aluminum:Cold-rolled can sheet from Chinese and Australian smelters enables lightweight, infinitely recyclable containment. Suntory and Kirin have converted flagship sparkling water lines since 2022, compressing logistics costs and eliminating breakage.
- Glass:Soda-lime compositions persist in premium beer and spirits where tactile quality commands shelf price premiums.
- Cardboard:Liquid packaging board with polyethylene barriers supports aseptic cartons for shelf-stable dairy and juice in China and Indonesia.
Polyethylene Terephthalate captures the highest shipment volumes. Aluminum demonstrates the steepest expansion trajectory.
Closure Type:
Application requirements dictate sealing performance, with carbonation retention and resealability driving specification divergence.
- Screw Caps:Polypropylene and polyethylene constructions with tamper-evident bands secure carbonated soft drinks and water bottles across mass retail channels.
- Resealable:Aluminum and plastic hybrid designs enable portion control for energy drinks and premium ready-to-drink teas in South Korea's convenience store networks.
- Corks:Natural and synthetic variants maintain traditional sealing for wine and premium spirits in Japan and Australia's on-premise channels.
- Snap-On:Low-cost polyethylene rings secure non-carbonated juices and dairy in price-sensitive Indonesian and Philippine markets.
Screw Caps dominates unit economics. Resealable closures gain share fastest in premium segments.
Application:
Customer type and consumption occasion fragment demand, with on-the-go formats diverging from at-home volume packaging.
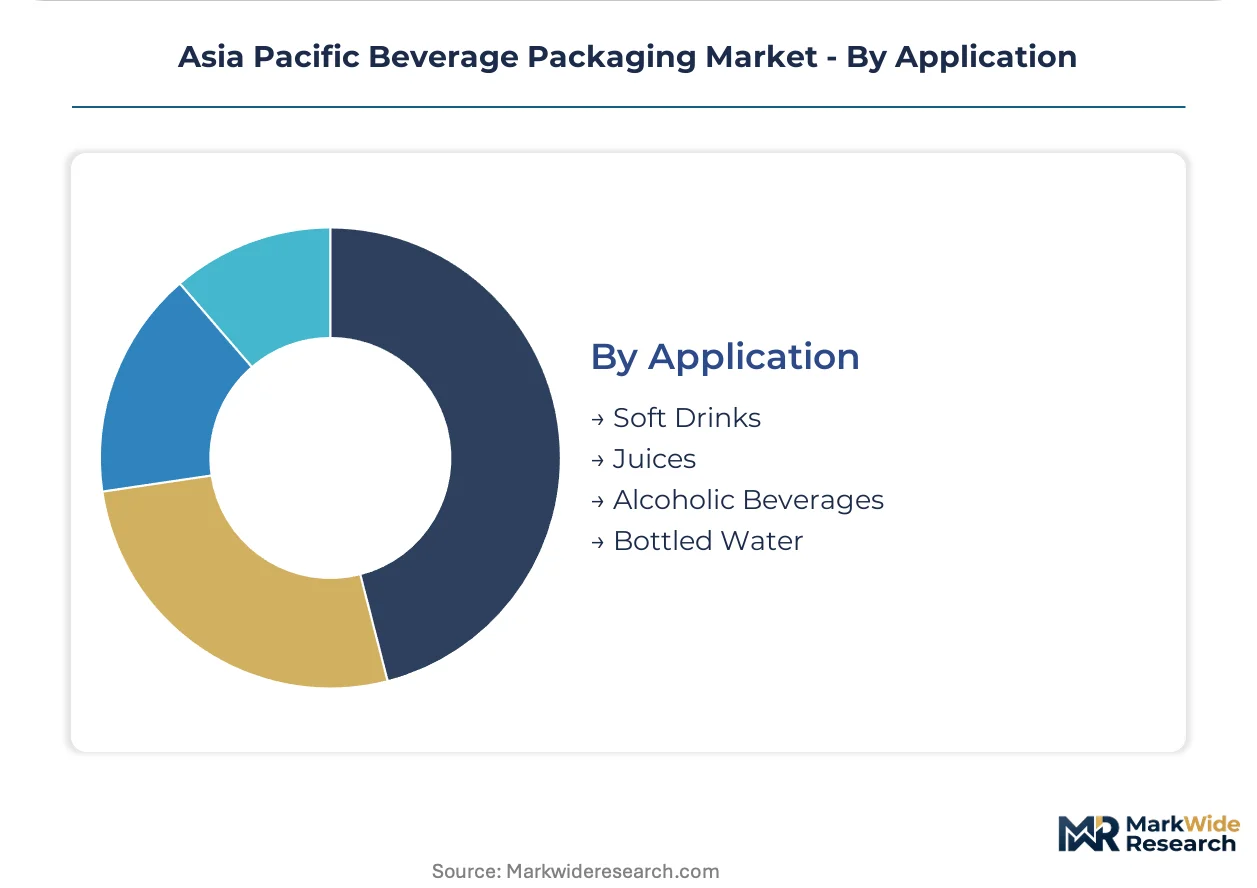
- Soft Drinks:Carbonated formulations in polyethylene terephthalate and aluminum serve immediate consumption through vending machines and convenience stores. Lightweighting programs now achieve sub-10 gram preform weights for 500ml bottles.
- Juices:Aseptic cartons and high-barrier pouches preserve vitamin stability where cold chain infrastructure remains limited. Tetra Pak's technology anchors shelf-stable portfolios in China and Indonesia.
- Alcoholic Beverages:Beer dominates aluminum can demand while spirits sustain glass bottle requirements. Vietnam and Thailand face pasteurization protocol redesigns when exiting returnable glass systems.
- Bottled Water:Polyethylene terephthalate bottles surge in Mumbai, Delhi, and Bangalore as municipal supply reliability deteriorates and private-label retail expands.
Bottled Water leads by shipment volume. Alcoholic Beverages in aluminum formats climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports aluminum cans to Thai beer brands while China ships biaxially oriented polyethylene terephthalate film across Southeast Asian converter networks. This trade-flow corridor concentrates substrate supply in Chinese extruders and Vietnamese can fabricators.
China
Urban bottled water demand in Shanghai and Guangzhou accelerates lightweight polyethylene terephthalate adoption. SAMR enforces GB standards for food-contact plastics with mandatory migration testing. The Yangtze River Delta houses preform injection-stretch blow-molding clusters where resin reduction programs achieve sub-10 gram weights for 500ml bottles.
Japan
Premium ready-to-drink tea brands in Tokyo and Osaka drive slim can and transparent bottle format premiums. METI circular economy guidelines mandate recyclability labeling and design-for-disassembly protocols. The Kanto region anchors aluminum can investment as Suntory and Kirin convert flagship sparkling water lines from glass.
India
Mumbai, Delhi, and Bangalore concentrate polyethylene terephthalate bottle volumes as municipal water reliability deteriorates. FSSAI tightens packaging material safety protocols for bottled water applications. Reliance Retail and D-Mart negotiate direct converter contracts, disintermediating legacy packaging traders in Mumbai and Chennai.
Australia
Container deposit legislation drives mono-material and post-consumer recycled content demand across Melbourne and Sydney. State-level schemes mandate detailed polymer composition documentation for market authorization. The container deposit infrastructure favors aluminum can and aseptic carton formats with established recycling pathways.
Indonesia
Jakarta and Surabaya cold chain expansion enables aseptic pouch and gable-top carton penetration in chilled dairy. National logistics investment overcomes prior ambient distribution constraints. Tetra Pak's aseptic technology anchors shelf-stable juice portfolios across Indonesian manufacturing.
Asia Pacific Beverage Packaging Market Competitive Environment
Listed leaders compete with private specialists across substrate technology and geographic coverage dimensions. The market structures around three tiers: multinational converters with integrated resin supply, regional fabricators serving single-country brand portfolios, and niche specialists in premium format innovation. Archetypes include lightweighting technology leaders, aseptic carton platform providers, and aluminum can scale operators. Competitive moves concentrate on capacity expansion in Vietnamese and Thai aluminum sheet rolling, plus strategic partnerships for post-consumer recycled content qualification.
Among Switzerland-based packaging groups, Tetra Pak International S.A. exemplifies the aseptic platform archetype through its laminated carton technology. Australian-listed Amcor plc occupies a position in flexible and rigid plastic leadership, while US-incorporated Ball Corporation anchors the aluminum can specialist tier. These three represent divergent strategic positions: carton-based shelf-stable systems, resin-lightweighting programs, and metal recycling economics.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| Owens-Illinois Inc. |
| Amcor plc |
| Stora Enso Oyj |
| Berry Global, Inc. |
| Ball Corporation |
| Ardagh Group S.A. |
| Westrock Company |
| Crown Holdings, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Vietnamese aluminum can fabricators and Thai beer exporters lock in sheet supply visibility while insulating converters from spot resin volatility. These arrangements concentrate procurement power with converters possessing direct rolling mill relationships, compressing margins for second-tier players dependent on Chinese traders.
Pricing Analysis
Current-generation lightweight polyethylene terephthalate preforms command 15-20 percent premiums over legacy-weight designs due to resin reduction technology and drop-test certification. Pricing stratifies across premium, standard, and economy tiers where FSSAI compliance grade and volume scale drive differentiation. Cost compression in standard-grade bottles is intensifying because Reliance Retail and D-Mart negotiate direct converter contracts, bypassing legacy traders. Private-label bottled water buyers in India exhibit highest price sensitivity, while Japanese premium ready-to-drink tea brands show lowest.
Supply Chain Analysis
Inventory cycles for aluminum can sheet extend 8-12 weeks from Chinese and Australian smelters to Vietnamese fabricators, creating working capital intensity for regional converters. Raw material flows draw from paraxylene and ethylene glycol feedstocks, biaxially oriented polyethylene terephthalate film, and cold-rolled aluminum sheet. Single-source vulnerability concentrates in Chinese substrate concentration where export quota adjustments disrupt Southeast Asian converter networks. Distribution runs through direct-to-retail procurement platforms that disintermediate Mumbai and Chennai packaging traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: SAMR GB standards and FSSAI protocols create 8-14 week migration testing bottlenecks that privilege established testing infrastructure.
For Market Incumbents: Shield market position by deepening backward integration into Chinese resin supply and securing SAMR pre-certification for post-consumer recycled content formats. Lightweighting technology leadership at Amcor and Ball Corporation demonstrates how resin reduction programs defend against emerging flexible pouch entrants in Indonesian dairy. Channel control through direct Reliance Retail contracts anchors volume visibility. For New Entrants and Emerging Players: Lead with mono-material aluminum bottle formats in South Korea's premium ready-to-drink tea segment where 40-60 percent shelf price premiums absorb retooling costs. Indonesia's chilled dairy logistics expansion offers the most penetrable white space, with Jakarta cold chain investment enabling aseptic pouch penetration previously constrained by ambient distribution. Pursue partnership with Tetra Pak technology licensing rather than proprietary platform development. For Investors and Strategic Acquirers: Regional fabricators serving single-country brand portfolios represent the priority acquisition archetype, particularly Vietnamese converters with Thai beer exporter relationships and established SAMR testing pathways. Long-term viability hinges on post-consumer recycled content qualification capabilities as Australia's container deposit schemes and Japan's METI guidelines tighten material specifications. Watch ASEAN packaging waste directive harmonization progress as inflection indicator for cross-border material qualification standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Investment | Sub-10 gram preform weights reduce resin intensity while maintaining carbonation pressure tolerance for Indian bottled water volumes. |
| Post-Consumer Recycled Content Qualification | SAMR recyclability labeling mandates and METI circular economy guidelines favor converters with established testing infrastructure. |
| Direct-to-Retail Procurement Platform Development | Reliance Retail and D-Mart contract concentration compresses payment cycles and disintermediates legacy Mumbai traders. |
| ASEAN Harmonization Compliance Preparation | Cross-border material qualification standardization reduces redundant testing costs for multi-country brand portfolios. |
| Aluminum Bottle Format Conversion | Suntory and Kirin flagship line conversions demonstrate logistics cost compression and breakage elimination in Japanese sparkling water. |
Study Parameters
The analysis maps plastic bottle, aluminum can, glass bottle, and aseptic pouch sub-sectors, each validated through converter procurement managers, beverage brand supply chain directors, and FSSAI compliance officers. Primary interviews with Tetra Pak licensing partners and Ball Corporation distribution heads combined with secondary validation from SAMR GB standard filings, Australian container deposit scheme reports, and Indian customs trade data. Bottom-up preform volume modeling and top-down regional packaging consumption estimates triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models material type, closure specification, application segment, and regional regulatory cluster dimensions. CAGRs derive from weighted average of historical trajectory and forward-looking capacity expansion announcements, with specific inputs including lightweighting technology adoption curves and cold chain infrastructure investment pipelines.
The analysis sits within stated boundaries; outcomes outside sustained Chinese substrate supply or accelerated ASEAN directive implementation would require recalibration. Forecasts reflect documented assumptions regarding resin price volatility and migration testing capacity expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Combi Cans Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Europe Beverage Container Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market
Beverage Packaging
Beverage Crates Market