
 Bomber Bottles Market | 2026-2036
Bomber Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Bomber Bottles Market Analytics
Market Context
A shift from single-source glass procurement to multi-source supplier networks is broadening procurement flexibility across the bomber bottles value chain. Owens-Illinois leverages vertical integration across melting and forming operations to secure raw material access. Ardagh Group anchors its position through geographic dominance in European glass container manufacturing. Ball Corporation competes via aluminum substrate specialization for craft beverage can-to-bottle hybrid formats.
Technical Definition and Segments
Bomber bottles denote large-format beverage containers, typically 22 fluid ounces (650 ml) in capacity, manufactured from amber or flint glass through IS machine blow-and-blow forming to provide UV protection and pressure resistance for carbonated contents. Glass material commands the dominant share of value given premium beverage brand preference for inert, recyclable packaging with tactile shelf differentiation. Aluminum capacity segments are expanding fastest as mobile canning lines migrate toward bomber-equivalent slim bottle formats. Screw cap configurations occupy the largest volume position across sauces and oils applications where resealability drives repeat purchase.
Regulatory Frame
FDA food-contact substance notifications govern glass and plastic resin approvals for bomber bottles in US beverage distribution, while EU REACH and F-Gas Regulation constrain coating chemistries and forming furnace emissions in European manufacturing. Germany's national packaging ordinance implements extended producer responsibility fees that directly alter material cost structures for imported bottles. Stakeholders must monitor evolving state-level bottle deposit expansions and carbon-border adjustment mechanisms to calibrate regional production footprints against compliance cost trajectories.
Market Dynamics
Craft beverage producers are fragmenting procurement across multi-source glass networks to hedge against raw material volatility and furnace capacity constraints in North American and European forming operations.
Growth Catalysts
- EU Packaging Waste Directives:Extended producer responsibility mandates are accelerating demand for refillable amber glass formats among German and Belgian premium bottlers.
- Mobile canning lines:Craft breweries in Colorado and Oregon are retrofitting equipment to run bomber-equivalent aluminum slim bottles alongside traditional glass.
- Amber glass UV protection:Inert material properties satisfy FDA food-contact substance notifications for hop-forward beer categories requiring shelf stability.
Market Restraints
- Soda ash and silica sand cost volatility:Energy-intensive melting operations face input price swings tied to natural gas benchmarks in European furnace networks.
- IS machine forming concentration:Specialty blow-and-blow equipment for 650 ml formats concentrates among a limited supplier base in Ohio and Illinois.
- Aluminum substrate substitution:Slim can formats below 500 ml are capturing trial-oriented craft beverage launches previously routed to glass bombers.
Strategic Opportunities
- India craft brewing emergence:Mumbai and Bangalore microbreweries are importing European amber glass formats as FSSAI labeling compliance matures.
- Screw cap resealability:Hot-fill sauce and oil applications in California and Texas are migrating from crown caps to continuous-thread aluminum closures.
- Carbon-border adjustment mechanisms:EU importers are qualifying low-emission furnace operations in Spain and Portugal to minimize tariff exposure.
Industry Challenges
- IS machine technician scarcity:Blow-and-blow forming specialists with 10+ years of parison programming experience are retiring faster than apprenticeship pipelines refill.
- Multi-source quality variance:Procurement teams struggle to harmonize thermal shock resistance specifications across Mexican, Chinese, and domestic glass suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bomber Bottles Market |
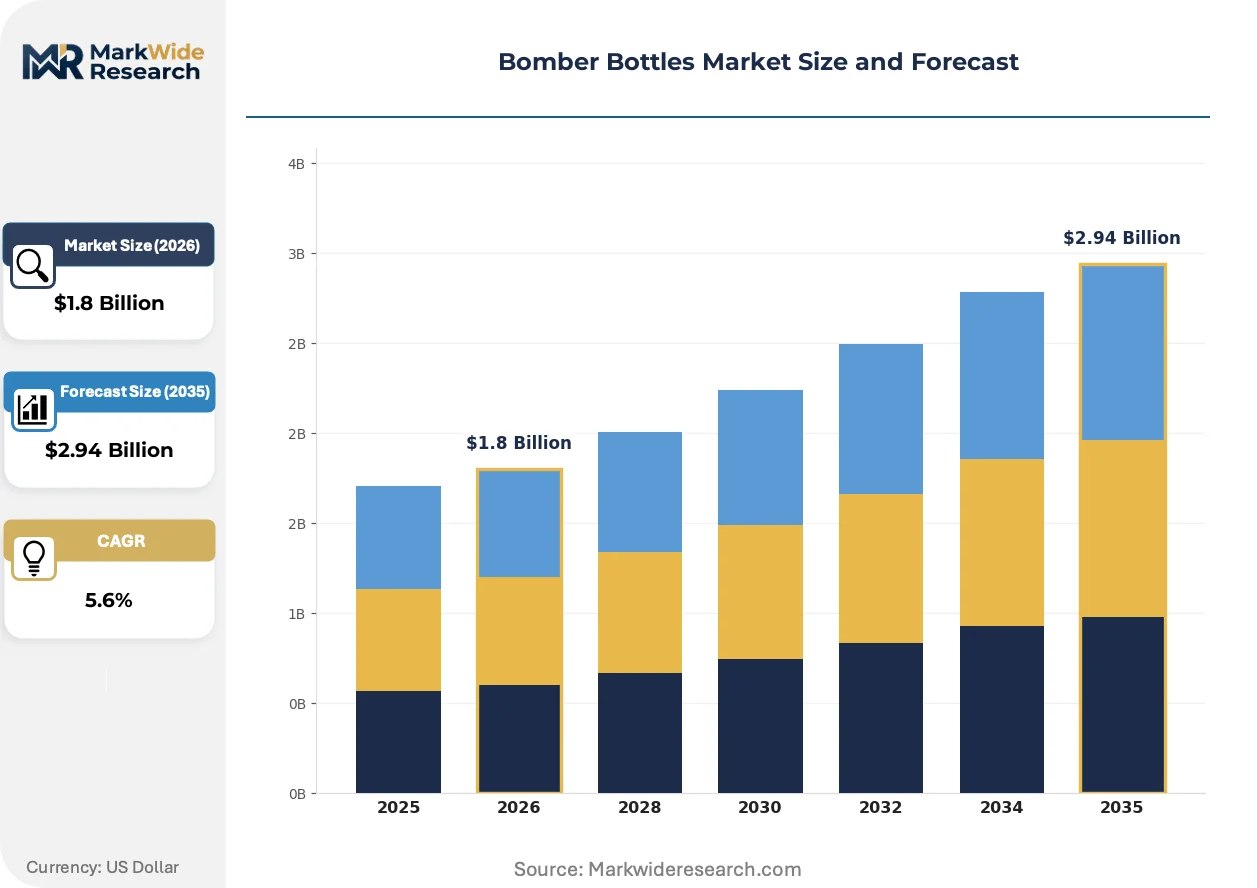
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Aluminum, Stainless Steel, Plastic Cap Type: Screw Cap, Flip Top, Cork, Pump Capacity: 250 ml, 500 ml, 750 ml, 1 L Application: Beverages, Sauces, Oils, Chemicals |
| Companies Covered | Owens-Illinois, Ardagh Group, Verallia, Vidrala, Ball Corporation, Crown Holdings, Sisecam Group, Orora Limited, Amcor Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bomber Bottles Market Evolving Landscape
Digital printing and lightweighting technologies are compressing minimum order quantities and enabling SKU proliferation without mold inventory bloat across craft beverage portfolios.
Direct-to-glass digital inkjet decoration is converging with on-demand label personalization platforms. Small-batch breweries in Portland and Asheville are adopting single-pass UV-cured printing to rotate seasonal artwork without plate changeover costs. This capability is converging with e-commerce fulfillment models that require batch sizes below 500 units.
REACH Annex XVII restrictions on heavy metal pigments are forcing reformulation of ceramic enamel decorations used in premium spirits applications. German bottlers operating under ECHA compliance deadlines are qualifying organic-based colorants that reduce leaching risk during alkaline washing cycles. Amber glass producers in Bavaria are absorbing certification costs to maintain access to export markets.
Buyer consolidation among multi-brand craft beverage holding companies is compressing supplier negotiation cycles. Regional distributors in Texas and Florida are demanding uniform bottle specifications across acquired brewery portfolios to rationalize warehousing. Glass converters are responding with modular mold systems that accommodate pressure rating variance without full equipment swaps.
Bomber Bottles Market Segmentation
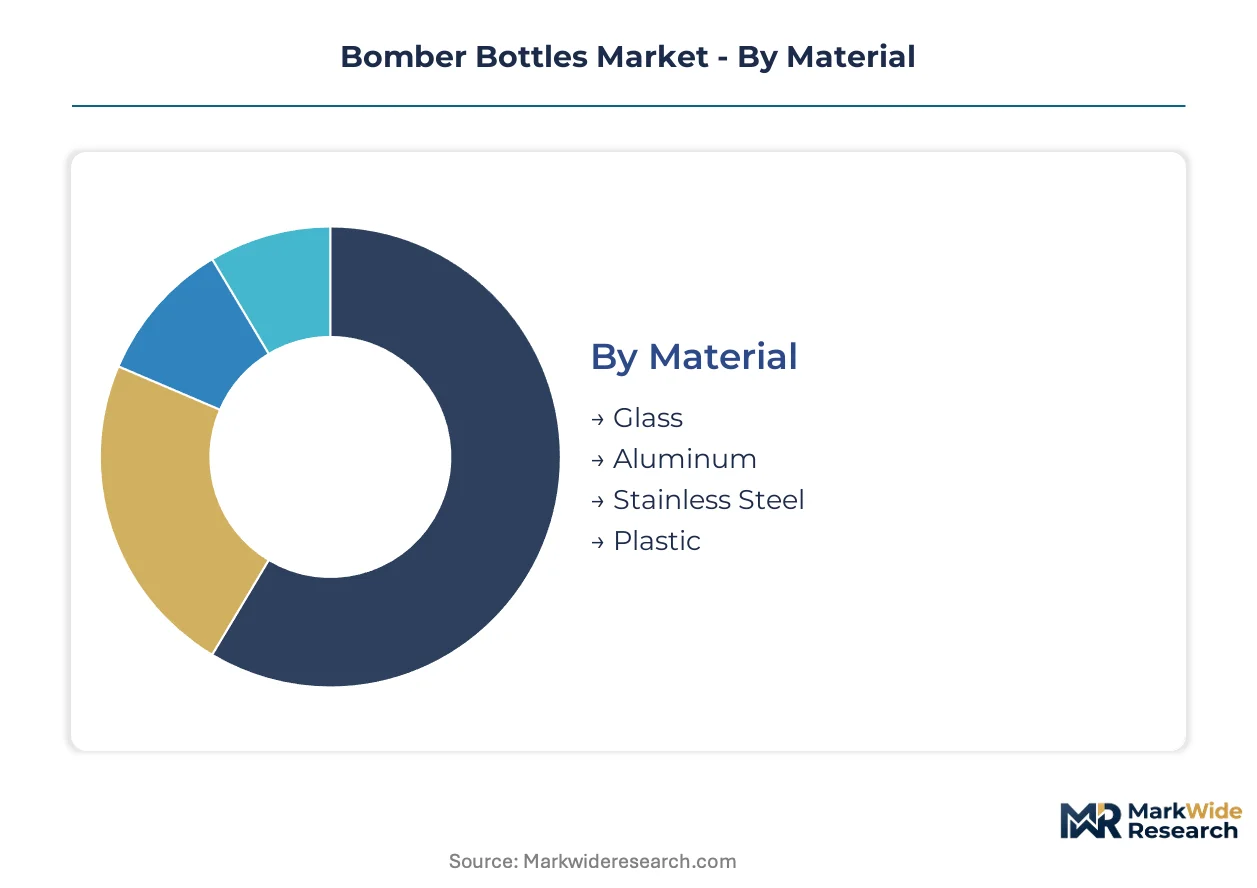
Bomber bottles serve divergent end-uses—from craft beer cellaring to hot-fill sauce distribution—requiring material and closure specifications that fragment procurement strategies across supplier networks. Understanding how technical requirements map to buyer budgets enables targeted positioning against furnace capacity constraints and mobile canning line migration.
Material:
Buyers differentiate primarily by thermal stability needs and brand positioning against shelf differentiation versus logistics cost.
- Glass:Amber and flint variants manufactured through IS machine blow-and-blow forming deliver UV protection and pressure resistance for carbonated craft beverages. German premium bottlers dominate procurement of refillable amber formats under extended producer responsibility mandates, absorbing certification costs to maintain EU market access.
- Aluminum:Slim bottle formats compatible with mobile canning lines enable craft breweries in Colorado and Oregon to run hybrid glass-to-aluminum production without dedicated bottling investments. This substrate is expanding most quickly as trial-oriented launches migrate from traditional glass bombers.
- Stainless Steel:Double-wall vacuum construction serves outdoor and adventure beverage segments requiring impact resistance beyond glass fragility limits.
- Plastic:PET and HDPE formats compete in chemical and mass-market sauce applications where freight cost minimization overrides premium tactile properties.
Glass leads volumes today; aluminum is gaining share fastest.
Cap Type:
Resealability requirements and fill temperature protocols determine closure selection across beverage, sauce, and oil applications.
- Screw Cap:Continuous-thread aluminum closures dominate hot-fill sauce and oil applications in California and Texas where repeat purchase depends on refrigerator storage convenience. Migration from crown caps is accelerating as California processors retrofit capping equipment.
- Flip Top:Swing-top wire bale mechanisms serve Belgian and German traditional ale formats where heritage aesthetics command shelf price premiums.
- Cork:Natural and synthetic corks retain position in premium spirits and barrel-aged beer categories requiring oxidative maturation control.
- Pump:Dispensing closures concentrate in foodservice oil and sauce formats where portion control drives operational efficiency.
Screw cap configurations anchor procurement volume; flip top formats are climbing the fastest in European heritage positioning.
Capacity:
Distribution channel constraints and consumption occasion fragmentation shape volume selection against warehousing standardization pressures.
- 500 ml:The traditional bomber format at 22 fluid ounces matches single-serve craft beer consumption occasions and dominates North American craft brewery procurement.
- 750 ml:Wine-bottle-equivalent sizing serves Belgian strong ale and American wild ale categories where sharing occasions and cellar aging extend consumption timelines. Texas and Florida distributors increasingly demand this specification across acquired brewery portfolios to rationalize warehousing.
- 250 ml:Sample and trial formats serve festival distribution and airline catering channels where portion control regulations apply.
- 1 L:Large-format sharing bottles concentrate in German and Czech traditional beer cultures and foodservice sauce applications.
500 ml holds volume leadership; 750 ml is expanding most quickly under distributor consolidation pressure.
Application:
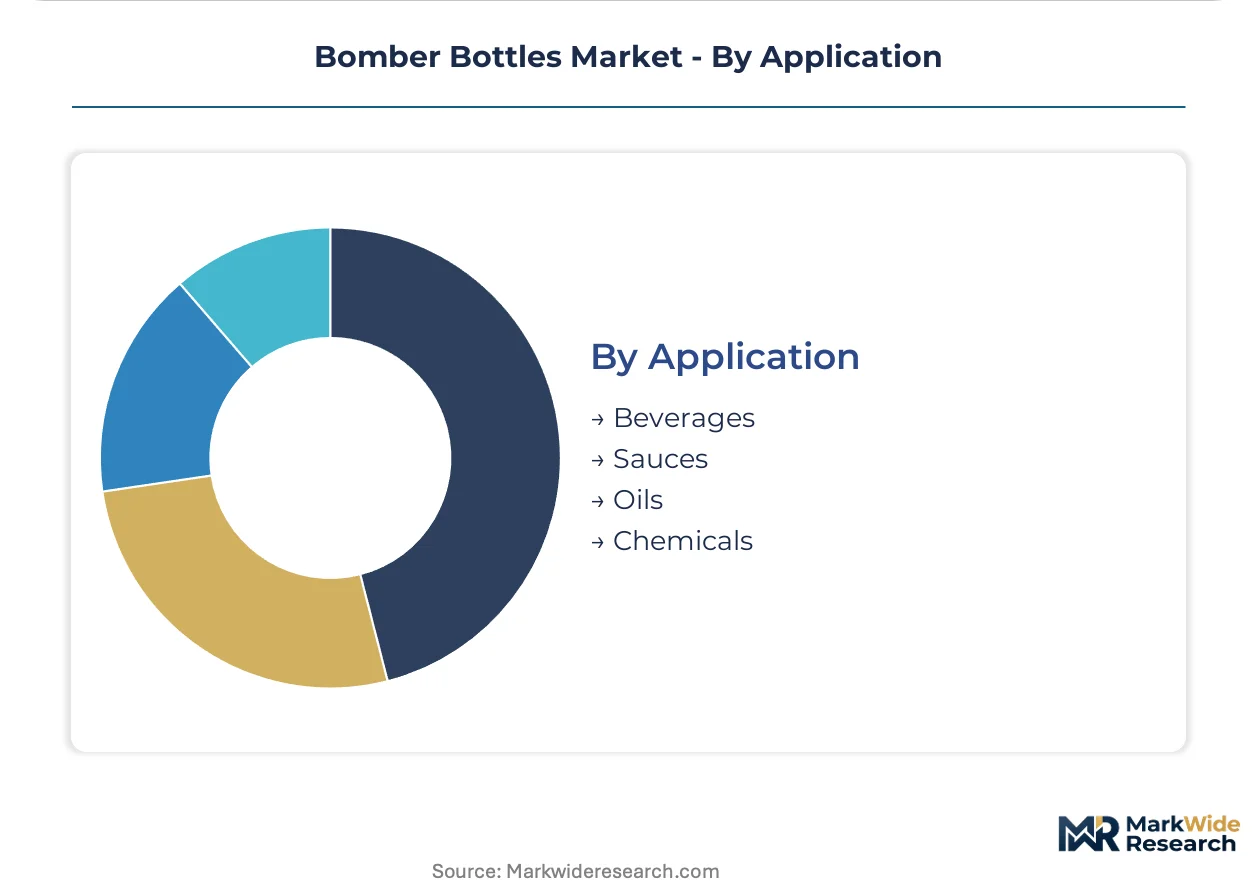
Fill temperature, pH stability, and regulatory contact requirements segment end-use demand across food, beverage, and industrial categories.
- Beverages:Carbonated beer and ready-to-drink cocktails require pressure-rated glass with crown or screw cap sealing against CO2 loss. FDA food-contact substance notifications govern resin and coating approvals for US distribution.
- Sauces:Hot-fill tomato and pepper-based products demand thermal shock-resistant glass and aluminum screw caps compatible with 85°C fill temperatures. California processors are migrating from crown caps to continuous-thread closures for resealability.
- Oils:Olive and specialty cooking oils require UV-protective amber glass or tinplate to prevent oxidation, with pump and screw cap configurations serving retail and foodservice channels respectively.
- Chemicals:Industrial solvents and cleaning products utilize HDPE and fluoropolymer-lined closures where chemical compatibility overrides food-grade certification costs.
Beverages command the dominant procurement position; sauces are gaining share fastest through hot-fill migration and private label expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass furnace operators are relocating forming capacity toward jurisdictions with lower carbon-border exposure and cheaper natural gas feedstock. This regulatory-arbitrage migration is redrawing procurement maps for bomber bottle buyers.
United States
Colorado and Oregon craft breweries are retrofitting mobile canning lines to run bomber-equivalent aluminum formats alongside traditional glass. FDA food-contact substance notifications govern resin approvals for beverage distribution. Pacific Northwest forming clusters face pressure from state-level bottle deposit expansions in California and Oregon.
Germany
Extended producer responsibility fees under the national packaging ordinance are accelerating refillable amber glass procurement among Bavarian premium bottlers. ECHA REACH compliance deadlines are forcing reformulation of ceramic enamel decorations. Munich-area glassworks are absorbing certification costs to maintain export market access.
Spain
EU carbon-border adjustment mechanisms are positioning Spanish furnace operations as low-emission supply sources for EU importers. F-Gas Regulation constraints on forming furnace emissions favor newer Spanish melting capacity over older Central European plants. Catalonian glass converters are qualifying modular mold systems for pressure-rated formats.
India
Mumbai and Bangalore microbreweries are importing European amber glass as FSSAI labeling compliance matures for craft beverage distribution. The country's central food safety regulator is tightening contact-material standards. Western India brewing clusters represent emerging demand nodes previously served by informal packaging channels.
Mexico
Multi-source procurement networks are incorporating Mexican glass suppliers to hedge against North American furnace capacity constraints. The country's environmental regulator is implementing emissions standards for heavy industry. Monterrey-area forming operations are expanding technical service capabilities for US craft brewery accounts.
Bomber Bottles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue aluminum substrate specialization and digital decoration capabilities. The supplier base concentrates among integrated glass manufacturers with captive melting capacity and independent converters serving regional craft beverage clusters. Three archetypes dominate: vertically integrated furnace-to-forming operators, mobile canning line equipment specialists, and modular mold system fabricators. Competitive moves center on backward integration into raw material sourcing and geographic expansion through distributor partnership networks.
Among North American integrated manufacturers, Owens-Illinois and Ball Corporation exemplify divergent substrate strategies—glass versus aluminum—while Ardagh Group occupies a position spanning both material classes through European and North American asset bases. These three anchors represent the scale-driven, substrate-specialized, and transatlantic-tier archetypes respectively.
| Leading Market Players |
|---|
| Owens-Illinois |
| Ardagh Group |
| Verallia |
| Vidrala |
| Ball Corporation |
| Crown Holdings |
| Sisecam Group |
| Orora Limited |
| Amcor Limited |
| Others |
Value Network & Pricing Analysis
Mobile canning line retrofits across Colorado and Oregon craft breweries are compressing batch economics while fragmenting supplier pricing power between glass furnace operators and aluminum substrate converters. This equipment transition simultaneously reduces per-unit decoration costs through digital inkjet adoption and concentrates procurement leverage among multi-brand holding companies demanding uniform specifications.
Pricing Analysis
Distributor margin compression in Texas and Florida is forcing glass converters toward contract-based long-term offtake structures with volume-scaled tiering. Price differentiation hinges on FDA food-contact certification tiers and thermal shock resistance grades, with premium amber formats commanding sustained premiums. Cost compression in standard flint glass is intensifying because energy-intensive melting operations face natural gas benchmark volatility. Mass-market sauce processors exhibit highest price sensitivity, while Bavarian premium bottlers absorbing ECHA compliance costs demonstrate lowest sensitivity.
Supply Chain Analysis
REACH Annex XVII certification gating and FSSAI labeling maturity requirements are concentrating qualified supply among Spanish, German, and Portuguese furnace operations with verified low-emission credentials. Raw material flows draw from soda ash deposits in Wyoming, silica sand from Illinois and Ohio, and aluminum ingot from domestic smelters. Single-source vulnerability concentrates in IS machine blow-and-blow forming equipment where parison programming specialists are retiring faster than apprenticeship pipelines refill. Distribution runs through regional distributor networks in North America and extended producer responsibility fee structures in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bomber bottles market functions as a regulatory compounder where EU Packaging Waste Directive extended producer responsibility mandates are structurally accelerating refillable amber glass demand among premium bottlers.
For Market Incumbents: Hedge against aluminum substrate substitution by qualifying modular mold systems that accommodate pressure rating variance without full equipment swaps. Absorb REACH Annex XVII ceramic enamel reformulation costs to maintain ECHA compliance access. Anchor furnace capacity in Spain and Portugal to minimize carbon-border adjustment exposure. For New Entrants and Emerging Players: The price-point gap between heritage flip-top Belgian ale formats and economy screw-cap sauce applications presents immediate white-space opportunity. Target California hot-fill processors migrating from crown caps to continuous-thread aluminum closures. Pursue direct-to-glass digital decoration partnerships with Portland and Asheville small-batch breweries seeking sub-500 unit seasonal artwork rotation. For Investors and Strategic Acquirers: Valuations sit cheapest among independent converters serving regional craft beverage clusters without captive melting capacity. Long-term viability over the projection horizon favors backward integration into raw material sourcing or geographic expansion through distributor partnership networks. Watch for FSSAI labeling compliance maturation in Mumbai and Bangalore as inflection indicator for Indian import demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Mold System Deployment | Enables pressure rating variance accommodation without full equipment swaps for Texas distributors. |
| Low-Emission Furnace Qualification | Positions Spanish and Portuguese operations favorably under EU carbon-border adjustment mechanisms. |
| Digital Inkjet Decoration Partnership | Captures Portland and Asheville brewery demand for sub-500 unit seasonal artwork rotation. |
| REACH Annex XVII Compliance Investment | Preserves Bavarian glassworks access to export markets through organic-based colorant certification. |
| Mobile Canning Line Retrofit | Allows Colorado and Oregon breweries to run hybrid glass-to-aluminum production without dedicated bottling investments. |
Research Methodology
Multiple input streams — primary interviews with glass furnace operators, craft brewery procurement leads, and distributor category managers, combined with secondary validation against ECHA regulatory filings, FSSAI labeling directives, and customs trade data — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations captured operational perspectives from IS machine technicians, mobile canning line equipment specialists, and modular mold system fabricators. Secondary sources incorporated EU Packaging Waste Directive implementation reports, state-level bottle deposit expansion tracking, and carbon-border adjustment mechanism policy documents.
Historical volume trajectories were cross-referenced against panel input from procurement executives to construct analytical frameworks across material substrate, cap type, capacity tier, and application end-use dimensions. CAGRs were derived through segmented growth rate reconciliation against macroeconomic drivers and regulatory compliance cost absorption patterns. Industry-specific forecast inputs included natural gas benchmark volatility for melting operations and mobile canning line migration rates among craft beverage producers.
Caveats apply where EU carbon-border adjustment mechanism implementation timing or FSSAI enforcement intensity could materially shift the outlook. Forecasts reflect assumptions regarding furnace capacity expansion rates and apprenticeship pipeline refill timelines. A model refresh is warranted upon material change in ECHA REACH enforcement posture or state-level bottle deposit expansion adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Dual Chamber Dispensing Bottles Market
Beverage Packaging
Insulated Cup Sleeves Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Pouring Spout Market
Beverage Packaging
Beveled Bottles Market