
 Hydrofoil Market | 2026-2036
Hydrofoil Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrofoil Market Foresight
Carbon fiber is expanding its share in hydrofoil construction as manufacturers replace heavier aluminum foils to improve lift-to-drag ratios and extend electric range. Candela leverages proprietary flight-control software to stabilize its fully electric vessels across chop. Artemis Technologies sustains deep R&D investment in foiling autonomy systems for commercial ferry applications. Mercury Racing anchors its position through high-performance powertrain integration with foiling hull platforms.
A hydrofoil is a submerged wing-like structure that generates lift at speed, raising a vessel's hull above the water surface to reduce hydrodynamic drag by up to 80 percent; modern iterations employ carbon fiber or composite layups with aspect ratios exceeding 10:1 for optimal efficiency, primarily serving commercial transit, defense, and recreational watercraft seeking fuel savings and smoother rides. Foil Kit configurations capture premium margins as retrofit demand grows among existing boat owners seeking electrification compatibility. Carbon Fiber material segments lead value contribution due to aerospace-grade supply chain requirements and autoclave curing costs. Composite alternatives gain traction where price sensitivity intersects with moderate performance thresholds in training and leisure applications.
The International Maritime Organization's revised carbon intensity indicators shape vessel certification pathways, while the EU Green Deal's FuelEU Maritime provisions impose escalating emissions penalties on conventional ferries operating within European Economic Area waters. The US Coast Guard maintains distinct stability criteria for foiling craft under 46 CFR subchapter T, creating compliance complexity for cross-border manufacturers. Stakeholders must monitor evolving battery safety standards from IEC and national maritime authorities as energy density thresholds climb alongside passenger capacity expansion in commercial foiling fleets.
Market Dynamics
Battery-electric propulsion is compressing the traditional 25-year ferry replacement cycle as operators face EU Green Deal compliance deadlines and fuel cost volatility. The shift from aluminum to carbon fiber foils is redistributing manufacturing value toward aerospace-tier composite suppliers.
Growth Catalysts
- FuelEU Maritime penalties:Escalating emissions levies on conventional ferries within European Economic Area waters are accelerating capital redeployment toward zero-emission foiling vessels.
- Carbon fiber foils:Aspect ratios exceeding 10:1 in composite wing sections deliver 40-50% drag reduction versus legacy aluminum, extending electric range for commercial operators.
- Stockholm archipelago corridor density:Swedish public transit authorities are consolidating fragmented ferry routes into electrified foiling networks, creating anchor demand for 150-300 passenger vessels.
Market Restraints
- Aerospace-grade carbon fiber supply:Autoclave curing capacity concentrates among Japanese and US suppliers, creating input bottlenecks for foil manufacturers scaling commercial production.
- IEC battery safety certification:Evolving maritime energy density thresholds extend type-approval timelines for high-capacity electric foiling ferries beyond 18 months.
- Aluminum foil residual value:Existing commercial fleets carry depreciated conventional hull assets that operators must retire prematurely, straining municipal transit budgets.
Strategic Opportunities
- Norwegian fjord transit networks:UNESCO-protected waterways ban conventional diesel traffic from 2026, mandating zero-emission alternatives across 47 ferry routes.
- Foil Kit retrofit channel:Aftermarket wing systems enable existing boat owners to electrify legacy hulls without full vessel replacement, capturing premium margins in recreational segments.
- Flight-control software licensing:Proprietary stabilization algorithms developed for electric foiling are transferable to autonomous surface vessel applications in defense and logistics.
Industry Challenges
- Maritime-aerospace talent crossover:Composite manufacturing and flight-control engineering skill sets remain scarce in traditional shipbuilding labor pools, forcing competitive recruitment from aviation sectors.
- USCG 46 CFR Subchapter T compliance:Distinct American stability criteria for foiling craft create dual-certification burdens for manufacturers serving transatlantic markets.
- High-voltage integration complexity:Battery-electric powertrains require retraining of dockside maintenance crews accustomed to mechanical diesel systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrofoil Market |
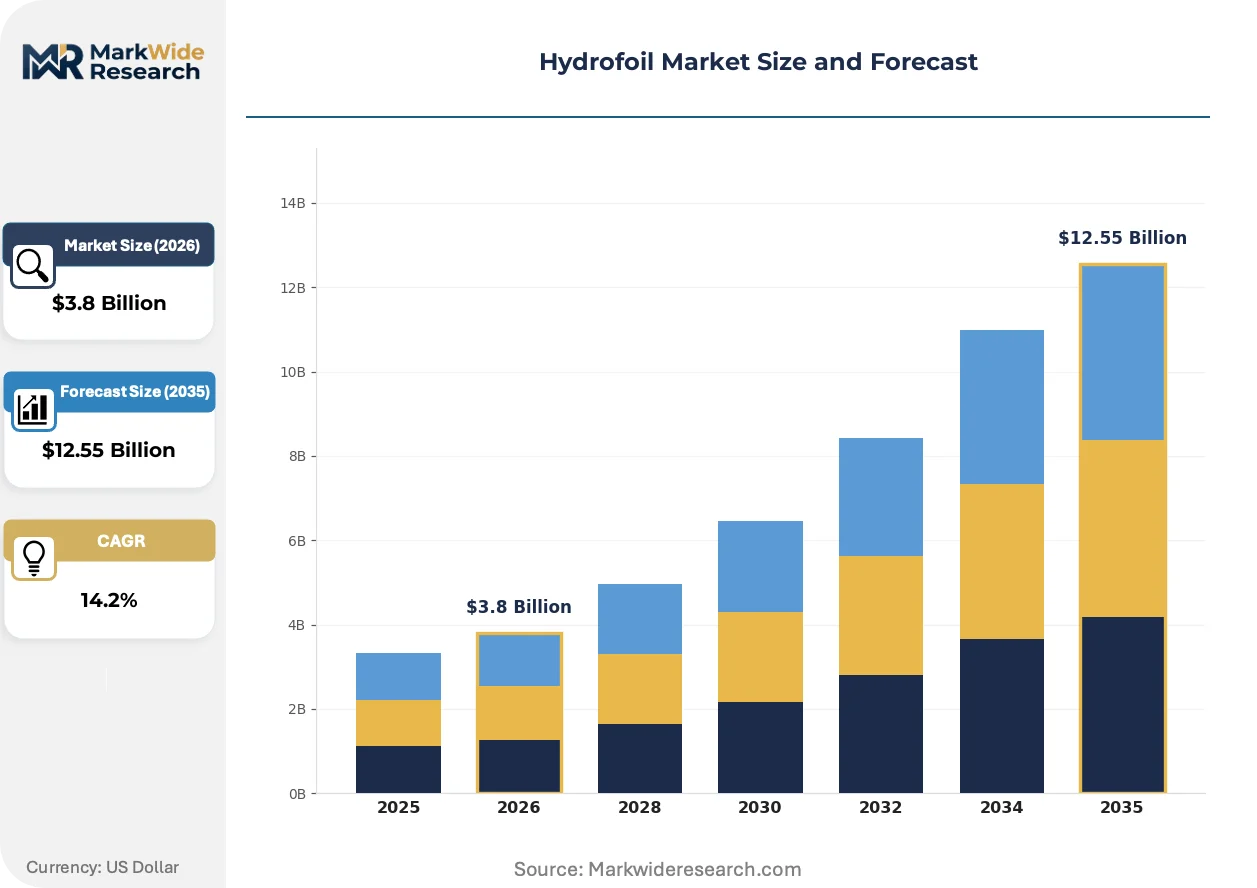
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Board, Sail, Surf, Foil Kit End User: Recreational Users, Professional Athletes, Racing Teams, Water Sports Schools Material: Carbon Fiber, Aluminum, Plastic, Composite Application: Leisure, Competition, Training, Research |
| Companies Covered | REGENT Craft, Lazzarini Design Studio, Artemis Technologies, Mercury Racing, Nemesis Yachts, Candela, Boeing, Red Funnel Ferries, HYFOIL Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrofoil Market Shifts & Advancements
Active foil control systems are displacing passive mechanical designs across commercial applications, while regulatory pressure compresses development timelines. Material science advances and procurement model evolution are simultaneously reshaping vessel economics and operator relationships with suppliers.
Carbon fiber composite layups with titanium leading-edge inserts are converging with electric propulsion architectures to enable 35-knot cruise speeds at half the energy consumption of planing hulls. Norwegian and Swedish ferry operators are specifying these configurations for 2026-2028 fleet renewals. The technology is converging with autonomous docking systems to reduce crew requirements on short-hop archipelago routes.
EU Green Deal FuelEU Maritime provisions impose escalating carbon intensity penalties on conventional ferries operating within European Economic Area waters from 2025. Vessel operators face 2% renewable fuel mandates rising to 75% by 2050, rendering diesel-electric hybrids economically unviable on high-frequency routes. Commercial transit authorities in Denmark and Germany are responding by accelerating sole-source negotiations with electric foil manufacturers.
After-sales service unbundling is disrupting traditional vessel procurement as operators separate hull acquisition from battery leasing and foil maintenance contracts. Swedish public transit agencies now contract energy-as-a-service providers for shore charging infrastructure while owning bare hull assets. This pattern is most visible in Nordic waters where municipal operators lack capital budgets for full-stack electrification.
Hydrofoil Market Segmentation
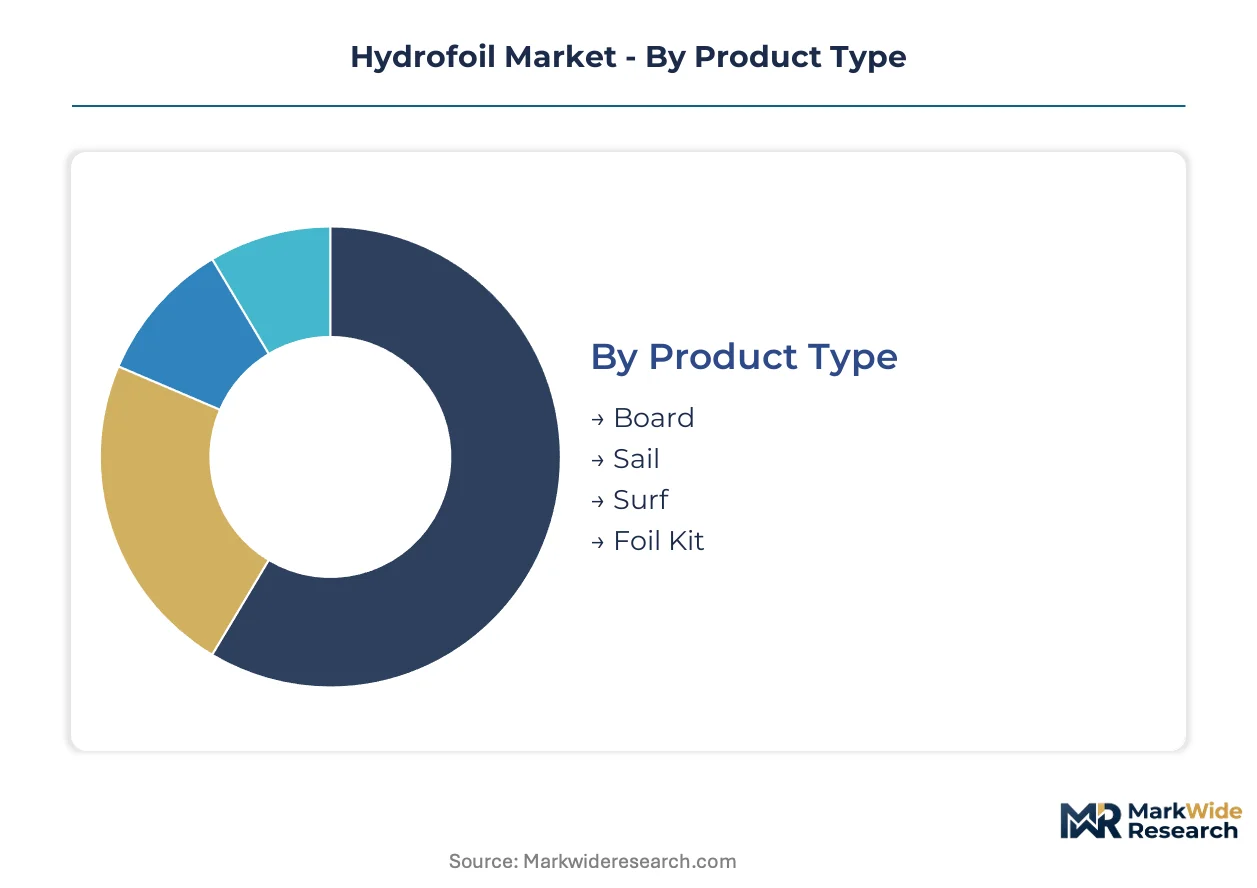
Segmentation in the hydrofoil market reveals how material science, user sophistication, and application intensity pull procurement decisions in divergent directions. Suppliers must align composite curing capacity and software integration depth against distinct performance thresholds across each slice.
Product Type:
Supply concentration tilts toward integrated manufacturers with captive autoclave capacity and flight-control engineering teams, leaving modular assemblers dependent on outsourced wing sections.
- Foil Kit:Modular wing-mast-fuselage systems ship in standardized configurations compatible with multiple hull platforms. Demand concentrates among recreational boat owners in Swedish and Norwegian archipelagos seeking retrofit electrification without full vessel replacement, constrained by IEC maritime battery certification timelines stretching beyond eighteen months.
- Board:Self-contained hydrofoil boards integrate propulsion, battery, and control surfaces into single-platform watercraft. Professional athletes and racing teams in EU Green Deal corridor markets drive specification toward carbon fiber layups with active stabilization, though aerospace-grade fiber supply bottlenecks limit manufacturer scaling.
- Sail:Wind-powered foiling craft employ rigid or soft sail architectures to generate thrust independent of motorized systems. Coastal leisure operators in Denmark specify these for training fleets where capital constraints preclude full electric conversion.
- Surf:Unpowered hydrofoil surfboards rely on wave energy and rider input for lift generation. Water sports schools in German Baltic ports represent the primary commercial channel, prioritizing durability over performance optimization.
Today's leader: Foil Kit. Tomorrow's challenger: Board.
End User:
Cost tier stratification separates municipal procurement with decade-long amortization horizons from individual purchasers optimizing for immediate operational expenditure reduction.
- Recreational Users:Individual owners and small charter operators purchase foiling craft for personal leisure and light commercial use. Norwegian fjord transit networks banning conventional diesel traffic from 2026 are accelerating municipal fleet procurement that indirectly supplies this channel through secondary resale.
- Professional Athletes:Elite competitors demand specification-tuned platforms with adjustable geometry and telemetry integration. Racing circuit concentration in Stockholm archipelago corridor routes sustains premium pricing for limited-production configurations.
- Racing Teams:Organized competitive programs operate multiple hulls with dedicated technical support and rapid component turnover. FuelEU Maritime penalty exposure on support vessels is pushing these operators toward full-electric logistics chains.
- Water Sports Schools:Training institutions prioritize fleet standardization, crash durability, and simplified maintenance protocols. German and Danish municipal recreation authorities dominate institutional procurement with multi-unit tender processes.
Volume concentrates with Recreational Users. Margin concentrates with Professional Athletes.
Material:
Application intensity dictates material selection, with commercial ferry operators accepting aerospace-tier costs for range extension while training fleets tolerate performance trade-offs for capital efficiency.
- Carbon Fiber:Aerospace-grade prepregs with autoclave curing deliver aspect ratios exceeding 10:1 for optimal lift-to-drag performance. Stockholm archipelago electrification mandates are concentrating demand among commercial ferry operators facing EU Green Deal compliance deadlines.
- Aluminum:Extruded and machined wing sections offer established supply chains and straightforward repairability. Residual value in existing commercial fleets creates stranded asset risk as operators accelerate premature retirement toward carbon fiber replacement.
- Plastic:Injection-molded or thermoformed foils serve entry-level recreational and training applications with moderate performance requirements. Price-sensitive leisure segments in German coastal markets sustain this category despite stiffness limitations.
- Composite:Hybrid layups combining glass fiber with selective carbon reinforcement balance cost and performance for mid-tier applications. Water sports schools specify these configurations where training intensity exceeds plastic durability thresholds.
Carbon Fiber commands premium positioning. Composite gains share fastest in training substitution.
Application:
Geography shapes application mix, with UNESCO-protected waterways and EU regulatory corridors concentrating commercial transit specification while coastal recreation sustains leisure demand.
- Leisure:Non-competitive recreational use spans individual ownership, charter operations, and tourism experiences. Norwegian fjord networks are mandating zero-emission alternatives across 47 ferry routes, displacing diesel leisure craft toward foiling platforms.
- Competition:Regulated racing events with standardized equipment classes and performance measurement protocols. Stockholm archipelago corridor density supports concentrated event scheduling that sustains dedicated vessel development programs.
- Training:Instructional programs for novice foiling operators emphasize stability, predictable handling, and damage tolerance. Danish and German municipal recreation authorities consolidate fragmented procurement into standardized fleet specifications.
- Research:Naval architecture, hydrodynamics, and autonomous systems development programs. Flight-control software licensing from electric foiling programs is transferring to defense and logistics surface vessel applications.
Leisure holds installed base dominance. Competition drives technology pull-through.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockholm anchors commercial hydrofoil deployment through archipelago electrification mandates that consolidate fragmented ferry routes into unified zero-emission networks.
Sweden
Swedish public transit authorities specify 150-300 passenger electric foiling vessels for Stockholm archipelago corridor density. EU Green Deal FuelEU Maritime provisions impose escalating emissions penalties on conventional ferries from 2025. Gothenburg's composite manufacturing cluster supplies aerospace-grade carbon fiber foils to commercial operators.
Norway
Norwegian ferry operators face UNESCO-protected waterway bans on conventional diesel traffic across 47 fjord routes from 2026. The country's national maritime regulator enforces zero-emission mandates through fjord transit network concessions. Bergen and Stavanger anchor electrified fleet procurement for high-frequency coastal services.
Germany
German municipal recreation authorities consolidate water sports school procurement into standardized fleet specifications for Baltic Sea training operations. The country's federal maritime authority coordinates with EU Green Deal implementation for coastal vessel certification. Kiel and Rostock concentrate composite hull fabrication for mid-tier commercial applications.
Denmark
Danish coastal leisure operators specify wind-powered foiling craft for training fleets where capital constraints limit full electric conversion. The national maritime administration aligns domestic ferry electrification with EU decarbonization timelines. Copenhagen's naval architecture cluster develops autonomous docking systems for short-hop archipelago routes.
United States
US commercial ferry operators navigate US Coast Guard 46 CFR Subchapter T stability criteria for foiling craft, creating dual-certification burdens for transatlantic manufacturers. The Federal Aviation Administration's flight-control software standards indirectly influence maritime autonomy system development. Pacific Northwest municipal transit agencies pilot electric foiling vessels for Puget Sound corridor services.
Hydrofoil Market Competitive Landscape
Global majors compete with regional champions across propulsion integration and composite manufacturing capabilities. The vendor base organizes around three tiers: integrated platform builders with captive flight-control software, specialized foil fabricators supplying modular wing systems, and powertrain integrators adapting marine propulsion for foiling architectures. Dominant competitive moves include strategic partnerships between hull manufacturers and battery leasing providers, plus technology licensing agreements transferring stabilization algorithms to autonomous surface vessel developers.
Within the integrated platform tier, Candela and Artemis Technologies exemplify vendors combining proprietary flight-control systems with carbon fiber foil production. Mercury Racing occupies a position among powertrain specialists adapting high-performance marine engines for foiling hull platforms. REGENT Craft represents the emerging class of electric-native designers targeting commercial ferry replacement cycles.
| Leading Market Players |
|---|
| REGENT Craft |
| Lazzarini Design Studio |
| Artemis Technologies |
| Mercury Racing |
| Nemesis Yachts |
| Candela |
| Boeing |
| Red Funnel Ferries |
| HYFOIL Marine |
| Others |
Supply & Pricing Matrix
Municipal transit authorities in Sweden and Norway anchor procurement volume for electric foiling ferries, locking in contract-based long-term offtake structures that bundle hull acquisition with energy-as-a-service provisions. This buyer concentration shifts pricing power toward integrated platform builders with captive composite curing capacity and proprietary flight-control software.
Pricing Analysis
Aerospace-grade carbon fiber prepreg costs pass through directly to vessel pricing, with autoclave curing energy intensity and Japanese supplier premiums amplifying input pressure at the premium tier. Three-tier pricing structure across fully integrated electric platforms, modular foil kit retrofits, and unpowered leisure craft separates EU Green Deal compliance-grade certification from recreational durability standards. Cost compression in the mid-tier composite segment is intensifying as German and Danish water sports schools consolidate standardized fleet procurement. Municipal ferry operators exhibit lowest price sensitivity due to amortization horizons and regulatory penalty avoidance, while individual recreational buyers in Baltic leisure markets face acute budget constraints.
Supply Chain Analysis
Composite manufacturing labor pools in Gothenburg, Kiel, and Rostock face acute scarcity of aerospace-trained autoclave technicians and flight-control software engineers, forcing competitive recruitment from aviation sectors. Supply concentrates among Japanese Toray and US Hexcel for aerospace-grade carbon fiber prepregs, with German SGL Carbon serving mid-tier hybrid composite demand. Raw material dependencies span titanium for foil leading-edge inserts, high-voltage battery cells from South Korean suppliers, and marine-grade epoxy systems. Single-source vulnerability in IEC-certified battery module supply creates certification timeline risk for commercial ferry programs. Distribution runs through direct OEM contracting for integrated platforms and specialized marine equipment distributors for aftermarket foil kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the hydrofoil market rests on carbon fiber cost curves flattening as autoclave capacity scales in European manufacturing clusters, while EU Green Deal compliance premiums sustain pricing power at the integrated platform tier.
For Market Incumbents: Lock in long-term offtake agreements with Stockholm and Oslo municipal transit authorities before 2026 UNESCO fjord bans trigger competitive tender floods. Secure captive carbon fiber prepreg allocation through backward integration into German composite manufacturing clusters or exclusive supply contracts with Toray. Defend against emerging electric-native entrants by accelerating IEC battery certification pipelines and embedding flight-control software licensing into hull sales to capture recurring revenue streams. For New Entrants and Emerging Players: The price-point gap between premium integrated electric ferries and economy-tier unpowered leisure craft creates white-space opportunity for mid-range hybrid composite platforms targeting Danish and German water sports schools. Target Norwegian fjord transit route concessions requiring zero-emission compliance but lacking capital budgets for full electric conversion, offering foil kit retrofit packages with battery leasing provisions. Pursue sole-source negotiation positioning through early pilot deployments with Bergen and Stavanger municipal operators to establish reference installations. For Investors and Strategic Acquirers: Maritime autonomy developers and defense surface vessel contractors are the most active acquirers in this space, seeking flight-control algorithm IP transferable to unmanned logistics applications. Long-term viability favors vertically integrated platform builders with captive composite manufacturing and software stacks over modular assemblers dependent on outsourced wing supply. Watch IEC battery energy density threshold revisions as the inflection signal—regulatory relaxation would compress type-approval timelines and unlock commercial ferry fleet expansion capital.| Strategic Initiative | Industry Significance |
|---|---|
| Flight-Control Software Licensing | Proprietary stabilization algorithms transfer to autonomous surface vessel defense applications beyond maritime transit. |
| Carbon Fiber Autoclave Capacity Expansion | Gothenburg manufacturing cluster additions reduce aerospace-grade foil supply bottlenecks for Stockholm archipelago fleet renewals. |
| Battery Leasing Service Unbundling | Energy-as-a-service provisions enable municipal operators to acquire bare hull assets without full-stack electrification capital burden. |
| Retrofit Foil Kit Channel Development | Aftermarket wing systems capture premium margins among existing boat owners seeking EU Green Deal compliance without vessel replacement. |
| Autonomous Docking System Integration | Copenhagen naval architecture cluster developments reduce crew requirements on short-hop electrified archipelago routes. |
Research Methodology
Coverage spans Nordic waters, German Baltic ports, and North American pilot programs, with primary inputs from each region combined with secondary validation. Primary interviews engaged ferry fleet procurement directors at Swedish and Norwegian transit authorities, composite manufacturing plant managers in Gothenburg and Kiel, marine battery system technical leads, and naval architecture firms specializing in hydrodynamic optimization. Secondary sources included EU Green Deal regulatory filings, IEC maritime battery safety standards documentation, US Coast Guard 46 CFR Subchapter T stability criteria, customs trade data for carbon fiber prepreg imports, and SEC filings from listed marine equipment suppliers. Bottom-up vessel deployment tracking triangulates against top-down market sizing from composite material demand modeling.
Granularity-level modeling distinguished integrated electric platforms from modular foil kits and unpowered craft across product type segmentation, with end-user stratification separating municipal procurement cycles from individual recreational purchase patterns. Material-grade tiers tracked aerospace-grade carbon fiber against aluminum and hybrid composite alternatives. CAGRs derive from installation base growth curves adjusted for EU regulatory compliance deadlines and fleet replacement cycle compression. Industry-specific forecast inputs incorporated UNESCO fjord protection timeline enforcement and FuelEU Maritime penalty escalation schedules.
Caveats apply where IEC battery certification timeline extensions, carbon fiber autoclave capacity constraints, or USCG stability criteria revisions could materially shift the outlook. Forecasts reflect assumptions on regulatory enforcement consistency, composite supply chain scaling, and municipal capital budget availability across the projection horizon. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Freighter Conversions Market
Marine
Ship Searchlight Market
Marine
Ship Heat Exchanger Market
Marine
Marine AIS Monitoring System Market
Marine
Boat Trolling Motor Market
Marine
Marine Glass Market
Marine
Marine Shaft Power Meter Market
Marine
Boat Control Lever Market
Marine
Marine Growth Removal Tool Market
Marine
Buoys and Beacon Market
Marine
Autonomous Ships Market
Marine
Recreational Vessel Battery Market
Marine
Shipbuilding Market
Marine
Marine Fuel Injector Market
Marine
Marine Turbocharger Market
Marine
Marine Big Data Market