
 Global Marine Gearbox Market | 2026-2036
Global Marine Gearbox Market Size, Share, and Industry Trends Forecast 2026-2036
Global Marine Gearbox Market Outlook
Offshore support vessel operators is rotating toward hybrid-ready marine gearboxes as fleet operators retrofit for lower-emission operations. Wärtsilä Corporation leverages integrated propulsion packages to anchor its position in hybrid-electric configurations. ZF Friedrichshafen AG sustains competitive pressure through precision manufacturing scale across European and Asian production networks.
A marine gearbox transmits mechanical power from engine to propeller shaft through precisely machined helical or planetary gear sets, with reduction ratios typically spanning 2:1 to 12:1 and torque ratings exceeding 50,000 Nm for deep-sea commercial applications. The device enables speed reduction, thrust reversal, and thrust vectoring across vessel classes. Reduction gearboxes dominate unit volume in commercial shipping due to standardized integration with two-stroke diesel engines, while hybrid technology segments command premium positioning as shipbuilders electrify auxiliary systems. Thruster gearboxes exhibit concentrated demand from offshore support vessels navigating dynamic positioning protocols.
IMO Tier III emissions standards and EU MRV monitoring frameworks compel gear manufacturers to engineer lower-friction sealing systems and lubricant formulations compatible with bio-based oils. The US Coast Guard enforces structural compliance through 46 CFR subchapter F for propulsion machinery certification on domestic routes. Stakeholders must evaluate supplier readiness for methanol-compatible drivetrain architectures as fuel pathways diversify beyond conventional distillates.
Market Dynamics
Hybrid-electric propulsion architectures are forcing marine gearbox manufacturers to reengineer power transmission interfaces for dual-source torque management, compressing development cycles across East Asian shipyards.
Growth Catalysts
- IMO Tier III mandates:Exhaust emission limits in North American and Caribbean Emission Control Areas compel retrofit demand for lower-friction gearboxes compatible with selective catalytic reduction systems.
- Offshore wind installation vessels:Dynamic positioning requirements for jack-up rigs and cable-layers drive specification of high-torque thruster gearboxes with integrated pitch control.
- China's shipbuilding consolidation:State-directed capacity rationalization at yards in Jiangsu and Zhejiang provinces concentrates procurement authority for standardized reduction gear systems.
Market Restraints
- Specialized alloy supply concentration:Case-hardening steels and nickel-chromium alloys for gear blanks face sourcing bottlenecks from Ukrainian and Russian metallurgical suppliers.
- Dual-certification burden:Gearbox assemblies for international routes must simultaneously satisfy 46 CFR Subchapter F, Lloyd's Register Type Approval, and China Classification Society rules.
- Electric motor substitution:Direct-drive permanent magnet motors eliminate mechanical reduction stages in sub-5MW auxiliary applications.
Strategic Opportunities
- Methanol fuel pathway readiness:DNV and Lloyd's Register certification protocols for methanol-compatible drivetrains create first-mover advantage for seal and bearing suppliers.
- India coastal shipping expansion:Sagarmala port modernization and domestic cabotage liberalization generate demand for medium-speed gearboxes in the 1,000-4,000 kW range.
- Predictive maintenance integration:Vibration sensor arrays and oil debris monitoring systems bundled with gearbox supply contracts shift revenue toward lifecycle service models.
Industry Challenges
- Precision grinding specialist shortage:Helical gear profile grinding and honing operations require machinists with 5+ year apprenticeships, constraining output at European and Japanese facilities.
- Legacy system integration complexity:Retrofit installations must mechanically interface with existing stern tubes, line shafts, and engine bedplates without hull modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Marine Gearbox Market |
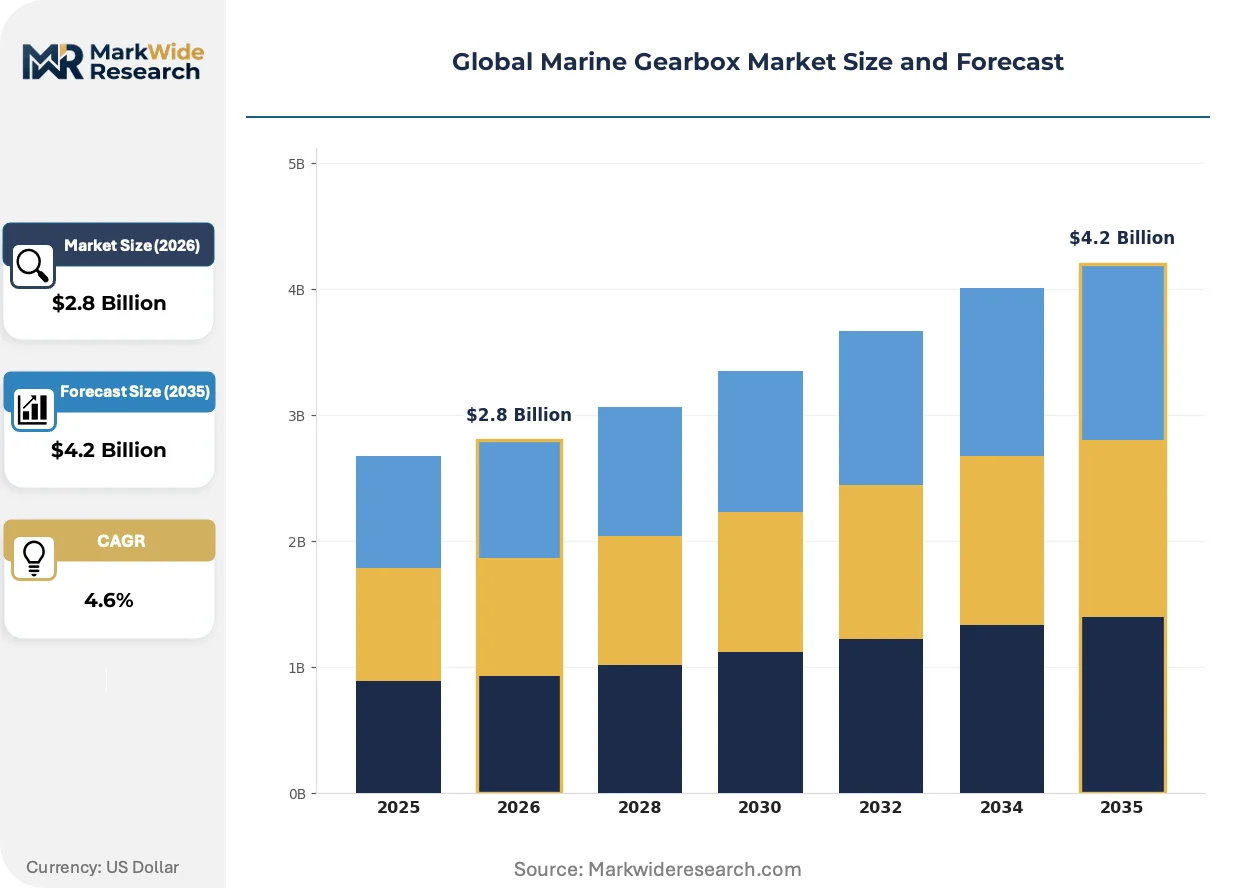
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reduction Gearboxes, Gear Couplings, Reversing Gearboxes, Thruster Gearboxes Application: Commercial Vessels, Naval Vessels, Offshore Support Vessels, Fishing Vessels End User: Shipbuilders, Repair Yards, Fleet Operators, Maritime Logistics Technology: Mechanical, Electrical, Hybrid, Digital Control |
| Companies Covered | ZF Friedrichshafen AG, Rolls-Royce Power Systems AG, Wärtsilä Corporation, Rexroth (Bosch Group), Sumitomo Heavy Industries Ltd., MAN Energy Solutions, Mitsubishi Heavy Industries Marine Machinery & Equipment Co., Ltd., Eaton Corporation, David Brown Santasalo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Marine Gearbox Market Strategic Shifts
Gearbox architecture is fragmenting along propulsion source lines as shipyards confront divergent fuel strategies and electrification roadmaps.
Hybrid-ready marine gearboxes with dual-input PTO/PTI configurations are bifurcating the product portfolio between conventional mechanical-only units and electro-mechanical integrated systems. Offshore support vessel operators in the North Sea and Gulf of Mexico specify these configurations for spinning reserve and harbor maneuvering modes. The technology split is compressing order volumes for single-purpose reduction gearboxes while expanding engineering service contracts.
EU MRV monitoring frameworks and the FuelEU Maritime initiative impose granular carbon intensity reporting on vessel operators. Gearbox manufacturers must now certify parasitic power losses and lubricant consumption rates as scope 3 emissions inputs. Deep-sea container lines and Ro-Ro operators face the steepest compliance curves, driving specification of efficiency-optimized helical gear sets with synthetic oil compatibility.
Charterers and fleet managers are consolidating gearbox procurement through framework agreements with integrated propulsion suppliers rather than component-level sourcing. This behavior shift compresses the addressable market for standalone gearbox vendors and elevates system integrators with in-house thruster and control capabilities. The pattern is most visible in Singapore and Rotterdam hub ports where major lessors centralize technical management.
Global Marine Gearbox Market Segmentation
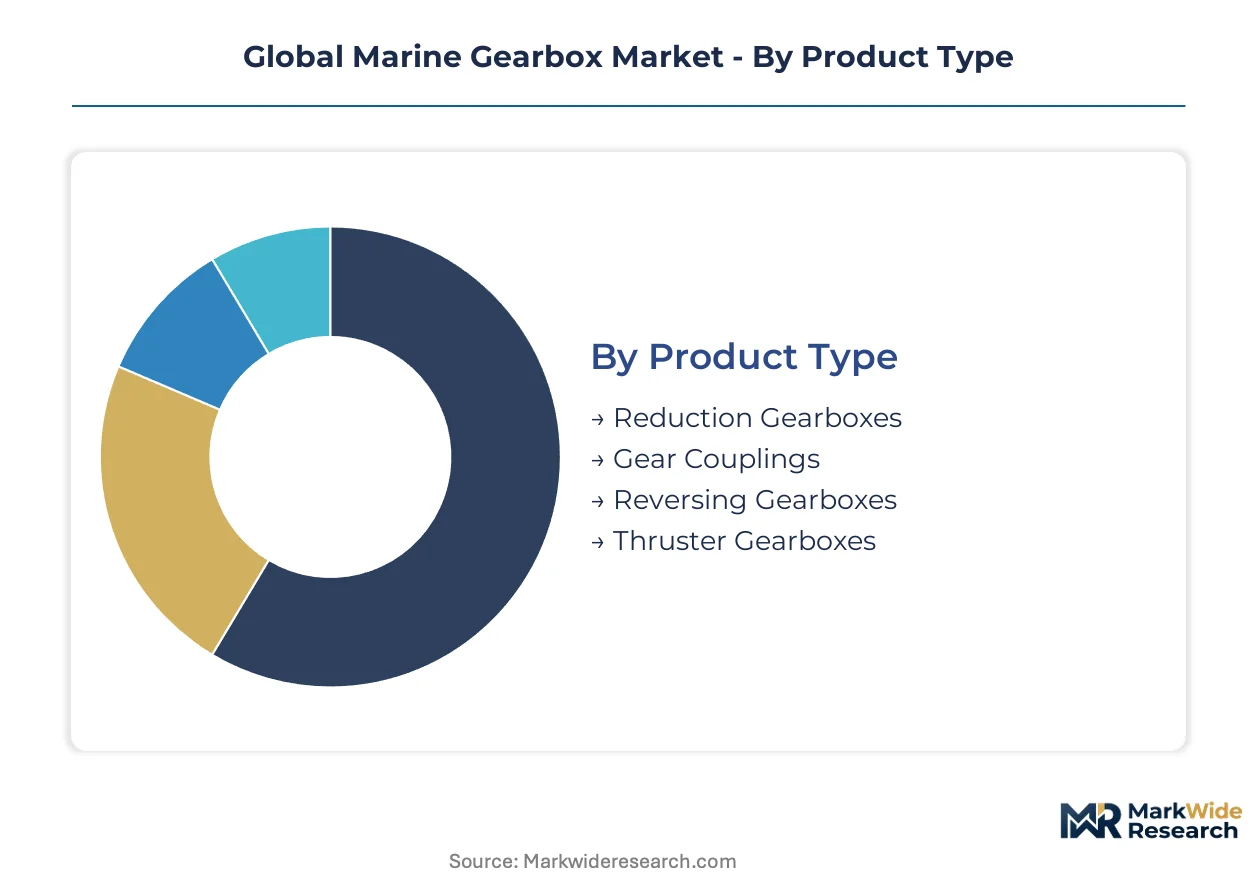
Marine gearbox segmentation reflects divergent pressures from electrification roadmaps and fuel pathway uncertainty. Shipyards and fleet operators now specify transmission architectures based on propulsion source compatibility rather than mechanical performance alone.
Product Type:
Direct-drive permanent magnet motors pose acute substitution pressure on mechanical reduction stages below 5MW, forcing product-level differentiation around torque density and hybrid integration.
- Reduction Gearboxes:Helical and planetary configurations dominate deep-sea commercial shipping with reduction ratios spanning 2:1 to 12:1. Demand concentrates at Chinese state-directed yards in Jiangsu and Zhejiang provinces where standardized two-stroke diesel integration drives procurement volumes.
- Thruster Gearboxes:High-torque units with integrated pitch control serve dynamic positioning protocols for jack-up rigs and cable-layers. Offshore wind installation vessels in the North Sea and Gulf of Mexico specify these for station-keeping precision under variable load conditions.
- Reversing Gearboxes:Enable thrust reversal for harbor maneuvering without engine shutdown.
- Gear Couplings:Connect mismatched shaft geometries while accommodating angular misalignment.
Reduction gearboxes anchor the volume base while thruster gearboxes gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive newbuild programs from retrofit-driven aftermarket demand across vessel categories.
- Commercial Vessels:Container lines and Ro-Ro operators face the steepest FuelEU Maritime compliance curves, driving specification of efficiency-optimized helical sets with synthetic oil compatibility and certified parasitic loss documentation.
- Offshore Support Vessels:Operators rotate toward hybrid-ready configurations for spinning reserve and harbor maneuvering. Charterers in Singapore and Rotterdam hub ports consolidate procurement through framework agreements with integrated propulsion suppliers.
- Naval Vessels:Military specifications prioritize shock resistance and redundant lubrication circuits.
- Fishing Vessels:Smaller displacement fleets drive demand for compact, maintenance-accessible units.
Commercial vessels generate the largest revenue pool while offshore support vessels expand most quickly on electrification mandates.
End User:
Customer type determines procurement authority concentration versus fragmentation across the value chain.
- Shipbuilders:East Asian yards in China, South Korea, and Japan command standardized reduction gear procurement through state-directed capacity rationalization. Newbuild specifications increasingly bundle gearbox supply with integrated propulsion packages.
- Fleet Operators:Deep-sea container lines and major lessors centralize technical management in hub ports, compressing the addressable market for standalone gearbox vendors. Lifecycle service contracts now include vibration monitoring and oil debris analysis.
- Repair Yards:Retrofit installations must interface with existing stern tubes and line shafts without hull modification.
- Maritime Logistics:Port operators and terminal service providers specify auxiliary drivetrains for tugs and pilot boats.
Shipbuilders capture the dominant procurement volume while fleet operators are shifting fastest toward outcome-based service agreements.
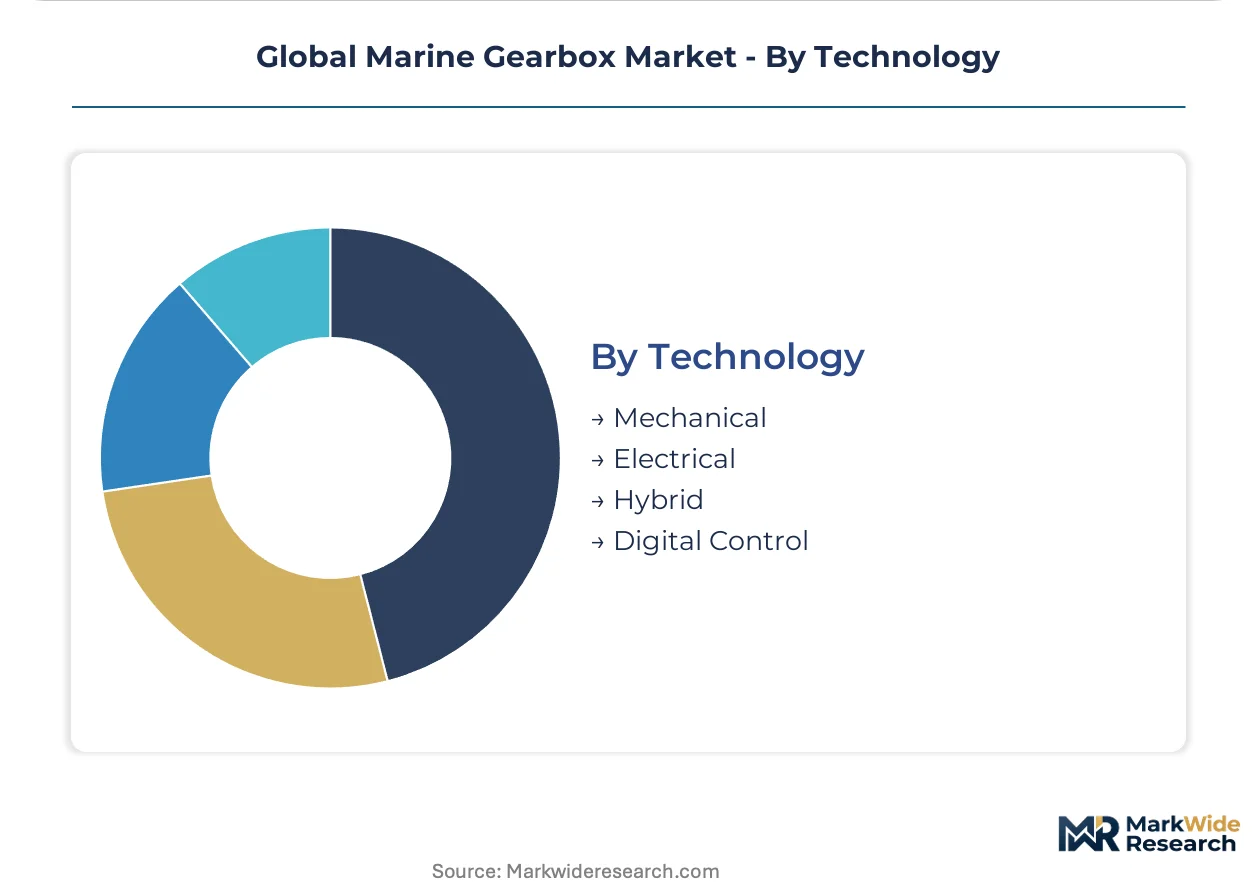
Technology:
Technology maturity curves separate proven mechanical architectures from emerging electro-mechanical systems facing certification bottlenecks.
- Mechanical:Conventional reduction stages using case-hardened alloy steel gear blanks remain the default for deep-sea two-stroke diesel integration. Precision grinding specialist shortages at European and Japanese facilities constrain output expansion.
- Hybrid:Dual-input PTO/PTI configurations bifurcate product portfolios between mechanical-only and electro-mechanical integrated systems. DNV and Lloyd's Register certification protocols for methanol-compatible drivetrains create first-mover positioning for seal and bearing engineering.
- Electrical:Direct-drive permanent magnet motors eliminate reduction stages in sub-5MW auxiliary applications.
- Digital Control:Sensor-integrated monitoring enables predictive maintenance revenue models.
Mechanical systems retain the installed base dominance while hybrid configurations show the steepest adoption trajectory on decarbonization deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta port cluster underwrites China's dominance in marine gearbox procurement, with Shanghai and Ningbo-Zhoushan handling the world's largest container throughput volumes. State-directed shipyard consolidation in Jiangsu and Zhejiang provinces concentrates demand for standardized reduction gear systems.
China
Shipbuilding capacity rationalization at yards in Jiangsu and Zhejiang provinces drives procurement volumes for two-stroke diesel-compatible reduction gearboxes. The Ministry of Industry and Information Technology enforces dual carbon goals that accelerate hybrid-electric propulsion adoption. Dalian and Qingdao manufacturing clusters specialize in high-torque thruster units for offshore support vessels.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor demand for precision-machined gear sets in ultra-large container vessels and LNG carriers. The Ministry of Trade, Industry and Energy enforces local content requirements under the Act on the Development of Ships and Shipbuilding Industry. Ulsan and Geoje shipyard complexes concentrate procurement authority for integrated propulsion packages.
Japan
Imabari Shipbuilding and Japan Marine United specify high-efficiency helical gear sets for FuelEU Maritime compliance on deep-sea container routes. The Ministry of Economy, Trade and Industry enforces JIS standards for marine machinery certification. Nagoya and Osaka industrial corridors host precision grinding specialists with decades of gear profile honing expertise.
Germany
Container lines headquartered in Hamburg and Bremen drive specification of efficiency-optimized gearboxes with certified parasitic loss documentation. The Federal Motor Transport Authority enforces KBA certification for methanol-compatible drivetrain components. Friedrichshafen and Munich manufacturing networks sustain competitive pressure through precision engineering scale.
United States
Offshore support vessel operators in the Gulf of Mexico retrofit fleets for IMO Tier III compliance in North American Emission Control Areas. The US Coast Guard enforces 46 CFR Subchapter F for propulsion machinery certification on domestic routes. Houston and New Orleans port complexes concentrate technical management authority for major lessors.
Global Marine Gearbox Market Competitive Environment
Listed leaders compete with private specialists across integrated propulsion system bundling. The vendor base spans multinational conglomerates with diversified industrial portfolios and focused marine transmission specialists. Three strategic archetypes dominate: integrated propulsion packagers, precision component specialists, and diversified industrial conglomerates. M&A activity concentrates on control system integration capabilities, while geographic expansion targets East Asian shipyard clusters.
Within the integrated propulsion tier, Wärtsilä Corporation and ZF Friedrichshafen AG exemplify system-level positioning. Among diversified industrial conglomerates, Rolls-Royce Power Systems AG and Mitsubishi Heavy Industries Marine Machinery & Equipment Co., Ltd. occupy positions spanning marine and non-marine power transmission. Precision-focused specialists include David Brown Santasalo and Sumitomo Heavy Industries Ltd., representing concentrated gearbox engineering expertise.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Rolls-Royce Power Systems AG |
| Wärtsilä Corporation |
| Rexroth (Bosch Group) |
| Sumitomo Heavy Industries Ltd. |
| MAN Energy Solutions |
| Mitsubishi Heavy Industries Marine Machinery & Equipment Co., Ltd. |
| Eaton Corporation |
| David Brown Santasalo |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month lead times for case-hardened alloy steel gear blanks concentrate procurement leverage among Japanese and German precision grinding specialists, compressing margin flexibility for mid-tier gearbox assemblers serving East Asian shipyards.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the marine gearbox market. Price differentiation hinges on Lloyd's Register certification grade and after-sales service bundling with predictive maintenance systems. Cost compression in economy-tier reduction gearboxes is intensifying because Chinese state-directed yards consolidate procurement through framework agreements with integrated propulsion suppliers. Fleet operators in Singapore and Rotterdam hub ports exhibit the lowest price sensitivity due to lifecycle cost optimization mandates, while independent repair yards in India and Southeast Asia face acute margin pressure on standalone component sourcing.
Supply Chain Analysis
Inventory cycles for nickel-chromium alloys and precision-machined helical gear sets stretch across 14-22 months, tethering output expansion to Ukrainian and Russian metallurgical supplier recovery timelines. Manufacturing gravity centers on China, Japan, and Germany, with Dalian and Qingdao clusters specializing in high-torque thruster units. Raw material dependencies span case-hardening steels, synthetic lubricant formulations, and vibration sensor arrays. Single-source vulnerability concentrates in precision grinding specialist labor pools at Nagoya and Osaka industrial corridors. Distribution runs through shipbuilder-integrated procurement channels and fleet operator framework agreements rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-drive permanent magnet motors threaten mechanical reduction stages below 5MW, forcing incumbent gearbox manufacturers to defend their installed base through hybrid-electric integration and service contract anchoring.
For Market Incumbents: Compound defensive positioning by backward integration into precision grinding capabilities at Nagoya and Osaka industrial corridors to offset specialist labor shortages. Secure Lloyd's Register and DNV certification for methanol-compatible seal and bearing architectures before regulatory deadlines tighten. Lock fleet operators into lifecycle service contracts bundling vibration monitoring and oil debris analysis to raise switching costs against electric motor substitution.
For New Entrants and Emerging Players: Lloyd's Register Type Approval fast-track programs for hybrid-ready PTO/PTI configurations open white-space access in offshore support vessel retrofits. Target jack-up rig and cable-layer operators in the North Sea and Gulf of Mexico where dynamic positioning requirements drive specification of high-torque thruster gearboxes with integrated pitch control. Pursue joint development agreements with Chinese state-directed yards in Jiangsu province to embed proprietary designs into standardized newbuild specifications.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming marine transmission divisions lacking hybrid-electric integration capabilities. Long-term viability favors precision component specialists with captive alloy steel sourcing and certified methanol drivetrain engineering. Watch for Lloyd's Register and DNV protocol finalization for methanol-compatible drivetrains as the inflection signal accelerating consolidation among seal and bearing suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Integration | Dual-input PTO/PTI configurations defend market share against permanent magnet motor substitution in auxiliary applications. |
| Methanol Compatibility Certification | DNV and Lloyd's Register seal and bearing protocols create first-mover positioning as fuel pathways diversify beyond distillates. |
| Predictive Maintenance Bundling | Vibration sensor arrays and oil debris monitoring shift revenue toward lifecycle service models with higher margin stability. |
| Precision Grinding Capacity Expansion | Nagoya and Osaka specialist labor pools constrain output; captive grinding capabilities secure supply chain control. |
| East Asian Shipyard Partnership | Framework agreements with Jiangsu and Zhejiang yards concentrate procurement authority for standardized reduction gear systems. |
Study Parameters
Operator-level perspectives from fleet technical managers, shipyard procurement officers, classification society surveyors, and aftermarket service directors anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through Lloyd's Register Type Approval databases, China Classification Society rule filings, customs trade records for alloy steel imports, and SEC disclosures from listed marine equipment suppliers. Bottom-up vessel fleet modeling and top-down shipbuilding capacity analysis provided cross-verification across the projection horizon.
Sensitivity analysis tested forecast robustness against IMO regulatory timeline acceleration, electric motor substitution rates in sub-5MW auxiliary applications, and precision grinding specialist labor availability constraints. The analytical framework segmented volume and value outputs across reduction gearbox, thruster gearbox, and hybrid-electric architectures; commercial vessel, offshore support vessel, and naval applications; and mechanical, hybrid, and electrical technology tiers. CAGRs derived from shipbuilding orderbook trajectories, retrofit cycle timing, and electrification penetration curves modeled through the analysis window.
Decision-makers should treat outputs as directional under assumptions of sustained IMO Tier III enforcement, continued Chinese state-directed shipbuilding consolidation, and stable alloy steel supply chain recovery; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Exhaust Systems Market
Marine
Marine Bearings Market
Marine
Marine LED Lights Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Hydrofoil Market
Marine
Boat Ladder Market
Marine
Marine Fin Stabilizer Market
Marine
Boat Cleat Market
Marine
Marine Winch Motors Market
Marine
Commercial Hovercraft Market
Marine
Sailboat Market
Marine
Azimuth Thrusters Market
Marine
Marine Base Steering Gear Market
Marine
Singapore Container Transshipment Market
Marine
Marine Chronometers Market
Marine
Ship Heat Exchanger Market