
 Slaughtering Equipment Market | 2026-2036
Slaughtering Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Slaughtering Equipment Market Intelligence
China's rapid modernization of its meat processing infrastructure is fragmenting the supplier base for high-throughput systems. Marel leverages its portfolio of integrated processing lines to secure large contracts with major food conglomerates in the country. The BAADER Group competes on the basis of its specialized poultry and fish processing technologies. Meanwhile, Jarvis Equipment specializes in handheld power tools for primary and secondary processing, serving a different segment of the abattoir workforce.
Slaughtering equipment encompasses a range of machinery designed for the humane and efficient processing of livestock, poultry, and fish. These systems perform functions from stunning, using precise electrical currents, to automated evisceration and carcass splitting. Automated technology segments represent the fastest-growing category, driven by large meat processors seeking higher throughput and labor savings. In terms of application, poultry slaughtering lines constitute the largest volume segment, followed by red meat processing for beef and pork.
Regulatory frameworks from bodies like the USDA and the European Food Safety Authority (EFSA) mandate specific equipment designs for food safety and animal welfare. Compliance with standards from organizations like the Halal Food Council of Europe also dictates equipment selection for processors targeting specific consumer markets. Stakeholders must now evaluate the capital expenditure for full automation against regional labor costs and skilled worker availability.
Market Dynamics
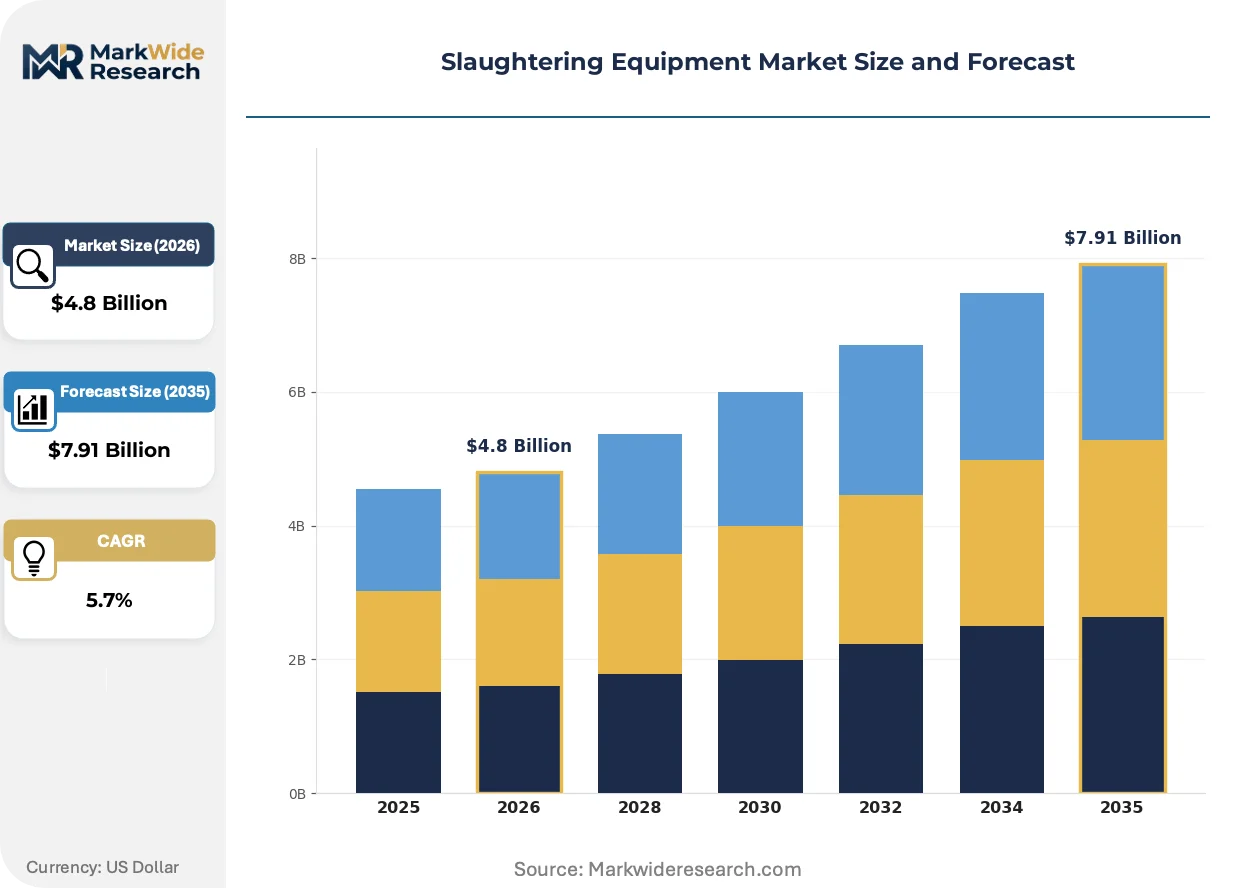
The imperative to modernize meat processing facilities in response to stringent food safety and animal welfare regulations is the central force shaping the slaughtering equipment market. This regulatory pressure from bodies like the USDA and EFSA necessitates significant capital investment in automated systems.
Growth Catalysts
- Regulatory Mandates:New rules from the European Union on animal welfare and the USDA's pathogen reduction standards are compelling large-scale processors to upgrade stunning, evisceration, and splitting systems to ensure compliance.
- Export-Oriented Growth:Brazil's focus on expanding its meat exports is driving concentrated demand for high-throughput, automated slaughtering lines capable of meeting international food safety and processing benchmarks.
- Food Safety Technology:The push for greater food safety is accelerating adoption of automated systems with improved hygienic design, such as automated evisceration machines that minimize contamination risks during processing.
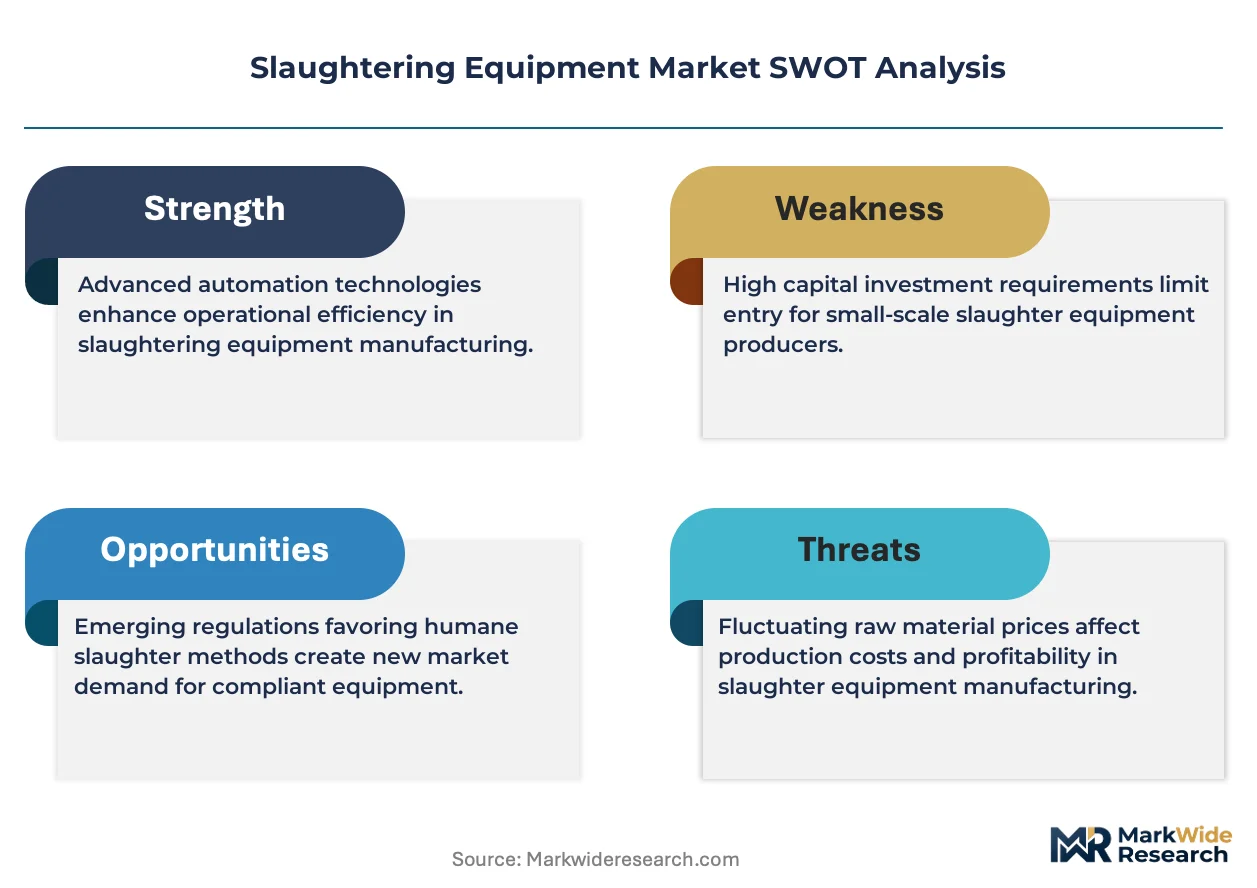
Market Restraints
- High Capital Expenditure:The substantial upfront cost of fully automated slaughtering lines presents a significant barrier to entry and modernization for small and medium-sized meat processors.
- Skilled Labor Scarcity:A shortage of technicians qualified to operate, maintain, and repair sophisticated automated processing equipment limits the operational efficiency of advanced systems.
- Technical Integration:Integrating new, automated machinery with older, existing infrastructure in established abattoirs creates significant operational and technical complexities for plant managers.
Strategic Opportunities
- Targeted Market Equipment:There is a distinct opportunity in designing and supplying equipment that meets specific religious and cultural processing requirements, such as those for compliance with the Halal Food Council of Europe.
- Digitalization of Processing:The integration of sensors, data analytics, and machine vision into processing lines offers a new frontier for optimizing yield, improving quality control, and providing end-to-end traceability.
- Modernization in China:The rapid consolidation and modernization of China's domestic meat processing industry creates a large-scale opportunity for suppliers of integrated, high-throughput slaughtering and processing lines.
Industry Challenges
- Workforce Training:A primary operational challenge involves upskilling the abattoir workforce to safely and effectively use new technologies, from advanced handheld power tools to complex automated line controls.
- Compliance Across Jurisdictions:Equipment manufacturers and meat processors face the challenge of navigating and complying with a complex and often divergent web of food safety and animal welfare regulations across different export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slaughtering Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Stunning Devices, Bleeding Systems, Skinning Machines, Evisceration Units, Carcass Splitting Tools Technology: Hydraulic, Pneumatic, Electrical, Manual, Automated End User: Meat Processors, Abattoirs, Butcher Shops, Food Packaging Units, Cold Storage Facilities Application: Poultry Slaughtering, Red Meat Processing, Seafood Preparation, Game Processing, Halal Processing |
| Companies Covered | Marel, BAADER Group, BAYLE SA, Prime Equipment Group, Brower Equipment, Jarvis Equipment, Industries Riopel, Asena, CTB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slaughtering Equipment Market Strategic Shifts & Innovations
The convergence of digital technology and mechanical engineering is redefining equipment capabilities. This shift is driven by demands for greater data-driven oversight of food safety, animal welfare, and operational throughput, moving beyond simple automation to intelligent processing.
Robotics and Vision Systems
Robotic systems equipped with 3D vision are being integrated into deboning and cutting lines. Large pork and beef processors are early adopters, using the technology to perform precise cuts that maximize yield and reduce repetitive strain injuries for workers. This technology is virtualizing the butcher's craft, translating anatomical knowledge into automated routines that adapt to variations in carcass size and shape for consistent output.
Enhanced Traceability Mandates
The European Food Safety Authority (EFSA) is tightening traceability requirements, pushing for farm-to-fork data logging. This directly impacts equipment design, forcing manufacturers to embed sensors and data-logging capabilities into machinery at every processing stage. The poultry segment is most affected, responding with investment in systems that can track individual batches from arrival through to final packaging.
Turnkey Solution Procurement
A notable shift in purchasing behavior sees large food conglomerates moving away from acquiring individual pieces of equipment. Instead, they are procuring complete, integrated turnkey processing lines from single-source suppliers. This trend disrupts the traditional model of using system integrators to piece together machinery from various vendors, and it is most prominent in new facility constructions in Brazil and China.
Slaughtering Equipment Market Segmentation
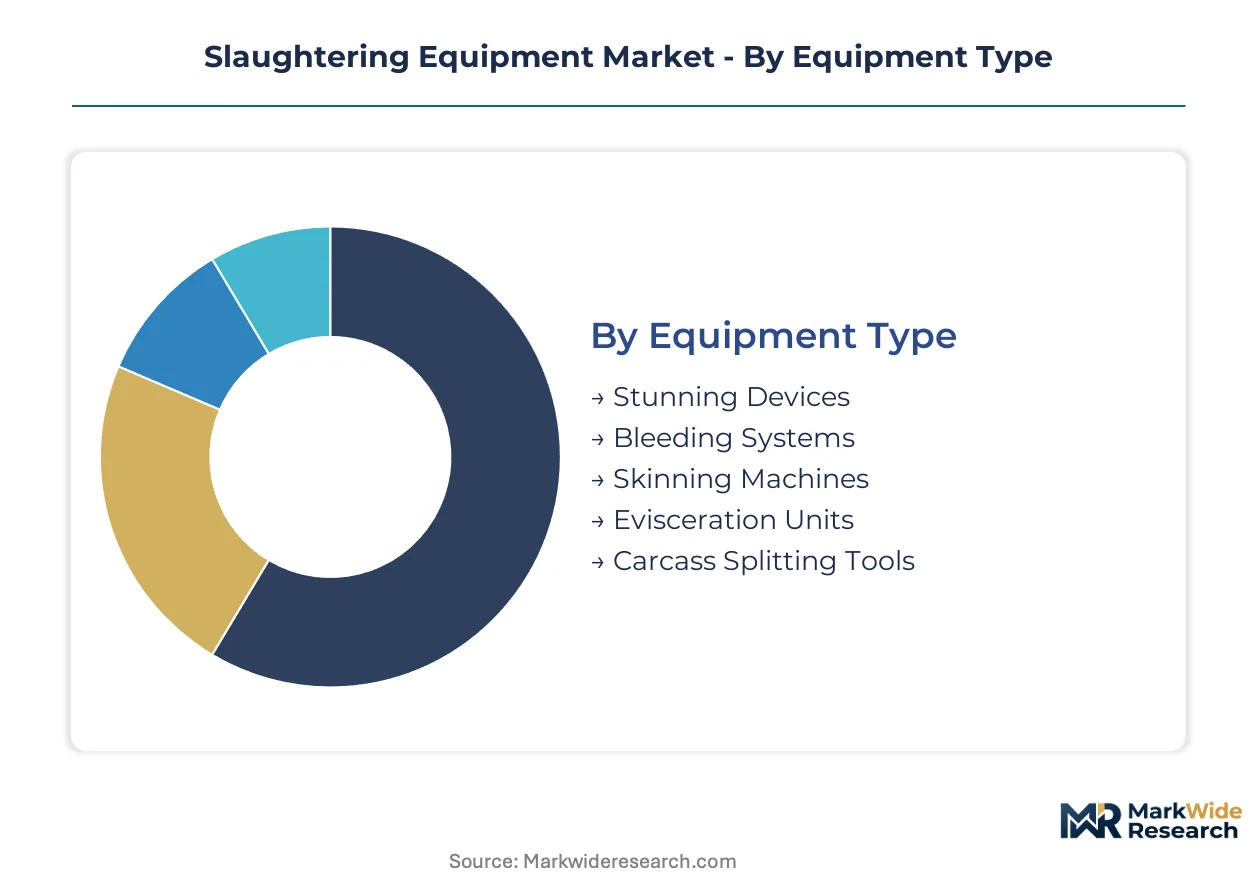
The slaughtering equipment market segments across diverse categories, each reflecting specialized machinery and operational needs within the meat processing industry. Understanding these segments clarifies where technological advancements and regulatory pressures are most acutely felt.
Equipment Type:
The spectrum of equipment types ranges from precision stunning devices to heavy-duty carcass processing tools, each addressing distinct stages of the slaughtering process.
- Stunning Devices:These systems render animals unconscious before slaughter, often utilizing electrical currents for humane treatment. Demand concentrates in the European Union, driven by stringent animal welfare regulations from bodies like EFSA.
- Evisceration Units:Automated evisceration units remove internal organs from carcasses, designed to minimize contamination risks and improve hygiene. Large-scale meat processors in Brazil prioritize these systems for export compliance and high throughput.
- Bleeding Systems:These systems facilitate efficient blood removal from stunned animals, crucial for meat quality and processing hygiene.
- Skinning Machines:Automated skinning machines separate hides from carcasses, enhancing operational speed and worker safety in red meat processing.
- Carcass Splitting Tools:These tools divide carcasses into halves or quarters, often using saws or cleavers, for further processing and cooling.
Established volume favors Evisceration Units; emerging adoption favors Stunning Devices.
Technology:
The technological maturity of slaughtering equipment spans from foundational manual tools to sophisticated automated systems, reflecting varying levels of capital investment and operational complexity.
- Automated:Automated systems integrate sensors, robotics, and control software to perform tasks like evisceration and cutting with minimal human intervention. Processors in China are rapidly adopting automated lines to modernize facilities and increase efficiency.
- Electrical:Electrical technologies power stunning devices and various cutting tools, offering precise control and improved animal welfare outcomes. The USDA's pathogen reduction standards influence the design and deployment of electrical stunning equipment.
- Hydraulic:Hydraulic systems provide robust power for heavy-duty tasks such as carcass splitting and lifting mechanisms in large abattoirs.
- Pneumatic:Pneumatic tools utilize compressed air for lighter, handheld operations, enhancing worker ergonomics and precision in secondary processing.
- Manual:Manual equipment, including knives and hand tools, remains essential for specialized tasks and smaller-scale operations where automation is not feasible.
The Automated segment represents the fastest-growing trajectory; Manual tools maintain a foundational role.
End User:
The scale of operations dictates end-user equipment needs, ranging from high-volume meat processors to specialized butcher shops and cold storage facilities.
- Meat Processors:Large-scale meat processors operate integrated slaughtering lines for high throughput and diverse product ranges. Their demand for automated systems is driven by labor savings and compliance with international food safety benchmarks.
- Abattoirs:Abattoirs focus on the initial stages of animal slaughter and primary processing, requiring robust stunning, bleeding, and evisceration equipment. Regulatory mandates from the EU and USDA directly influence abattoir facility upgrades.
- Butcher Shops:Butcher shops primarily use smaller-scale cutting and processing equipment for custom meat preparation and direct consumer sales.
- Food Packaging Units:These units integrate equipment for portioning, weighing, and packaging processed meat products, often linked to automated lines.
- Cold Storage Facilities:Cold storage facilities require specialized equipment for efficient carcass handling and temperature-controlled storage post-slaughter.
Meat Processors drive the largest equipment volumes; Butcher Shops exhibit steady, specialized demand.
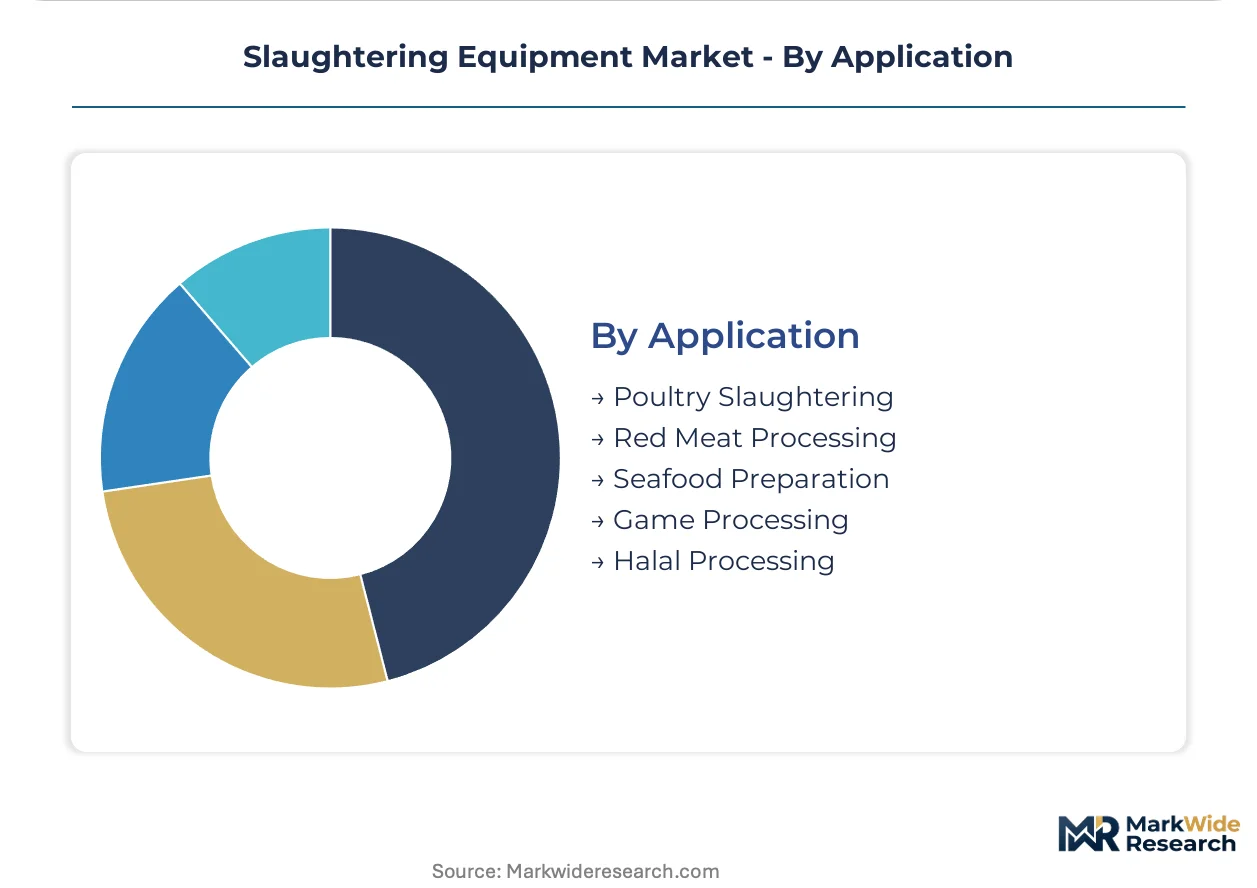
Application:
Equipment application varies across species, influencing design for yield optimization, hygiene, and compliance with specific processing standards.
- Poultry Slaughtering:Poultry slaughtering lines are characterized by high-speed, automated systems for processing large volumes of birds. EFSA traceability requirements compel investment in individual batch tracking systems for poultry.
- Red Meat Processing:This application covers beef and pork, requiring heavy-duty equipment for stunning, skinning, and carcass splitting. Large processors in Brazil prioritize red meat processing equipment for export market access.
- Seafood Preparation:Seafood preparation equipment includes specialized machines for stunning, gutting, and filleting fish, designed for delicate products.
- Game Processing:Game processing equipment caters to wild animal species, often requiring adaptable tools for varying sizes and carcass characteristics.
- Halal Processing:Halal processing equipment adheres to specific religious requirements for slaughter, impacting design for stunning and bleeding procedures to ensure compliance with bodies like the Halal Food Council of Europe.
Poultry Slaughtering lines are expanding most quickly; Red Meat Processing maintains significant market scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global supply of slaughtering equipment is increasingly concentrated in regions undergoing significant modernization and export expansion. Demand for advanced processing lines is particularly pronounced where food safety and animal welfare mandates intersect with large-scale meat production. This dynamic is driving investment across several key global markets.
Brazil
Demand for high-throughput, automated slaughtering lines is concentrated in Brazil, supporting its export-oriented meat industry. Brazil's focus on expanding meat exports drives investment in systems meeting international food safety benchmarks. The state of São Paulo, a major agricultural hub, sees significant upgrades in red meat processing facilities.
China
China's rapid modernization of its meat processing infrastructure creates substantial demand for integrated, high-throughput systems. The country's GB standards for food safety compel processors to adopt advanced automated technologies. In the Yangtze River Delta region, large food conglomerates are securing contracts for complete processing lines.
Germany
German meat processors invest in equipment to comply with stringent European Union animal welfare rules and EFSA food safety mandates. These regulations necessitate upgrades in stunning and evisceration systems across the country. The North Rhine-Westphalia region, home to major abattoirs, is a hub for adopting advanced automated solutions.
United States
Processors in the United States prioritize slaughtering equipment that meets USDA's pathogen reduction standards and enhances operational efficiency. Federal regulations from the USDA drive continuous investment in hygienic design and automated evisceration units. In the Midwest's corn belt, large beef and pork operations are integrating robotic deboning systems.
France
French abattoirs focus on specialized equipment to meet both national quality standards and EU animal welfare directives. Compliance with EFSA traceability requirements drives investment in data-logging capabilities for poultry processing. Brittany, a significant poultry producing region, sees ongoing upgrades in individual batch tracking systems.
Slaughtering Equipment Market Key Industry Players
Platform integrators command the system tier, offering complete processing lines, while component specialists sit upstream, providing niche machinery. The market exhibits a tiered structure, with a few dominant players providing integrated solutions and numerous smaller firms specializing in specific equipment types. Strategic archetypes include full-line providers, specialized technology firms, and regional equipment suppliers. Dominant competitive moves involve portfolio diversification into adjacent processing stages and strategic partnerships for technology co-development.
Within the full-line provider archetype, Marel represents a company leveraging its portfolio of integrated processing lines, securing large contracts globally, particularly in modernizing facilities. BAADER Group exemplifies a specialized technology firm, focusing on advanced poultry and fish processing technologies for high-volume operations. Jarvis Equipment, on the other hand, sits within the component specialist tier, providing handheld power tools for primary and secondary processing operations. These companies collectively illustrate the market's segmentation by scale and specialization, from comprehensive system integration to focused tool provision for abattoir workforces.
| Leading Market Players |
|---|
| Marel |
| BAADER Group |
| BAYLE SA |
| Prime Equipment Group |
| Brower Equipment |
| Jarvis Equipment |
| Industries Riopel |
| Asena |
| CTB |
| Others |
Cost & Logistics Intelligence
Integrated processing line suppliers like Marel and BAADER Group concentrate upstream value, allowing them to capture substantial margins from large-scale food conglomerates. This supply concentration influences pricing power across the slaughtering equipment market.
Pricing Analysis
USDA's pathogen reduction standards dictate the pricing tier structure for automated evisceration units and hygienic designs. The dominant pricing model is project-based for complete lines, combined with per-unit transactional sales for specialized components. Price differentiation stems from customization levels for integrated systems and comprehensive after-sales service packages. Pricing softness for smaller equipment reflects competition from regional suppliers, with small and medium-sized processors exhibiting the highest price sensitivity.
Supply Chain Analysis
Specialized component manufacturers in Germany and China hold significant capacity for advanced sensors and robotics components. The supply chain draws from these concentrated hubs for critical inputs like stainless steel and control software. A structural risk involves single-source vulnerability for highly specialized robotic and vision system components. Distribution runs through direct sales channels for integrated lines to large meat processors, complemented by regional distributor networks for handheld tools and smaller equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The slaughtering equipment market presents a fragmentation opportunity, driven by diverse regulatory mandates and specialized processing requirements across global regions. This creates distinct niches for compliance-driven equipment and cultural processing needs.
For Market Incumbents:Build technological moats through continuous R&D investment in robotics and AI-driven vision systems. Consolidate market position by acquiring niche technology firms specializing in specific processing requirements like Halal compliance. This strategy counters the threat from regional entrants and evolving regulatory landscapes. Certification investment in areas like EFSA traceability standards can also deepen competitive advantage.
For New Entrants and Emerging Players:Build out specialized equipment lines addressing specific religious and cultural processing requirements, such as Halal compliance. Target smaller-scale abattoirs and meat processors with modular, lower capital expenditure solutions, especially in regions with growing demand like Brazil. The most penetrable segment is custom equipment for niche applications, delivered with flexible financing options.
For Investors and Strategic Acquirers:Capital is best deployed toward integrated technology providers offering complete processing lines with strong digitalization capabilities. The market exhibits long-term viability, anchored by continuous regulatory pressure for food safety and animal welfare over the next decade. Target acquisition archetypes include mid-cap specialists with robust R&D in robotics and strong regional market penetration. The signal to watch is the increasing integration of AI-driven vision systems into existing processing lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-Driven Carcass Analysis | Optimizes yield and quality control in red meat processing. |
| Strategic Partnership: Regional System Integrators | Expands reach for turnkey solutions in emerging markets. |
| Technology Licensing: Hygienic Design Patents | Establishes industry standards for food safety compliance. |
| Acquisition of Specialist Firm: Halal Equipment Provider | Addresses specific cultural processing requirements and market niches. |
| Capacity Expansion: Automated Poultry Lines | Meets growing demand for high-throughput poultry slaughtering in Brazil. |
Research Approach
A standing panel of abattoir managers, equipment engineers, food safety regulators, and meat processing executives provided ongoing calibration and validation. This primary research was complemented by extensive secondary data analysis, including USDA filings, EFSA reports, and industry association publications. The study employed a rigorous bottom-up and top-down triangulation approach to ensure data accuracy.
Scenario-bracketing established the plausible range for market development across the analysis window. The analytical framework modeled segmentation dimensions including equipment type, technology, end-user, application, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market dynamics. Key forecast inputs included capital expenditure cycles for facility upgrades and global meat export volumes.
Stress conditions across geopolitical trade disputes and rapid shifts in animal welfare legislation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions, though these risk factors could influence market trajectories. Quarterly review of regulatory changes and major processor investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Cow Lifting Harness Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Russia Horse Riding Equipment Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Silage Tube Market
Livestock Equipment
Cattle Supplies Market
Livestock Equipment
Animal Workstations Market