
 Livestock Monitoring System Market | 2026-2036
Livestock Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Livestock Monitoring System Market Outlook
Edge computing integration with on-farm sensor networks is tilting system architecture toward real-time processing at the barn level rather than cloud-dependent latency. DeLaval leverages its Scandinavian manufacturing base to sustain premium positioning in automated milking systems. Zoetis anchors its veterinary diagnostics heritage into wearable health monitors for cattle. Nedap N.V. competes through specialized RFID ear tag systems that dominate European dairy cooperatives.
A livestock monitoring system comprises networked hardware and software for continuous animal health, behavior, and productivity tracking, typically incorporating accelerometers with sampling rates exceeding 10 Hz for rumination detection and temperature sensors accurate to 0.1°C for estrus identification. These systems serve commercial agriculture by reducing mortality losses and optimizing feed conversion ratios through early disease alerts. Wearable devices generate the deepest margin pools due to recurring replacement cycles and firmware subscription attach rates. Software solutions represent the fastest-expanding category as veterinary clinics demand predictive analytics dashboards. Deployment through cloud-based platforms now leads technology adoption among livestock ranchers managing dispersed grazing operations across multiple properties.
The FDA's Veterinary Feed Directive shapes antimicrobial use tracking requirements that drive monitoring system adoption in US cattle feedlots. EFSA welfare quality protocols and the EU Green Deal's Farm to Fork Strategy mandate traceability standards that accelerate sensor deployment across European dairy operations. Stakeholders must weigh interoperability investments against proprietary platform lock-in as national agricultural regulators diverge on data sovereignty requirements for farm-level animal health records.
Market Dynamics
Edge computing migration is compressing data latency from barn-level sensors to sub-second response windows, forcing cloud-dependent architectures toward hybrid processing models that split inference between on-farm gateways and remote servers.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory animal welfare traceability protocols across European dairy cooperatives are mandating sensor deployment for compliance documentation.
- Accelerometer miniaturization:Wearable rumination monitors sampling above 10 Hz now achieve veterinary-grade accuracy at consumer electronics cost curves.
- Brazilian pasture expansion:Dispersed grazing operations across Mato Grosso and Goiás are driving demand for satellite-linked collar systems managing herds across multiple properties.
Market Restraints
- Proprietary data lock-in:Major platform vendors restrict API access, preventing veterinary clinics from integrating multi-source health records into unified dashboards.
- Lithium battery supply concentration:Wearable device manufacturers remain dependent on Chinese cell suppliers, exposing margins to raw material volatility and export control friction.
- Rural connectivity gaps:Cellular dead zones across Australian outback stations and US Great Plains rangeland limit real-time alert reliability for cloud-dependent systems.
Strategic Opportunities
- India's dairy cooperative digitization:National Dairy Development Board initiatives are creating first-mover openings for low-cost ear tag systems across Gujarat and Maharashtra milk unions.
- Blockchain-IoT convergence:Immutable health record chains are enabling premium protein sourcing contracts that command price premiums from EU retailers.
- Veterinary telemedicine platforms:Remote diagnostic subscriptions are creating recurring revenue streams that subsidize hardware deployment costs for cash-constrained ranchers.
Industry Challenges
- Embedded firmware engineering scarcity:Barn-hardened device development requires rare combinations of agricultural domain knowledge and real-time operating system expertise.
- Cross-border data sovereignty fragmentation:Divergent national regulations on farm-level animal health records are forcing redundant infrastructure investments for vendors serving multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Livestock Monitoring System Market |
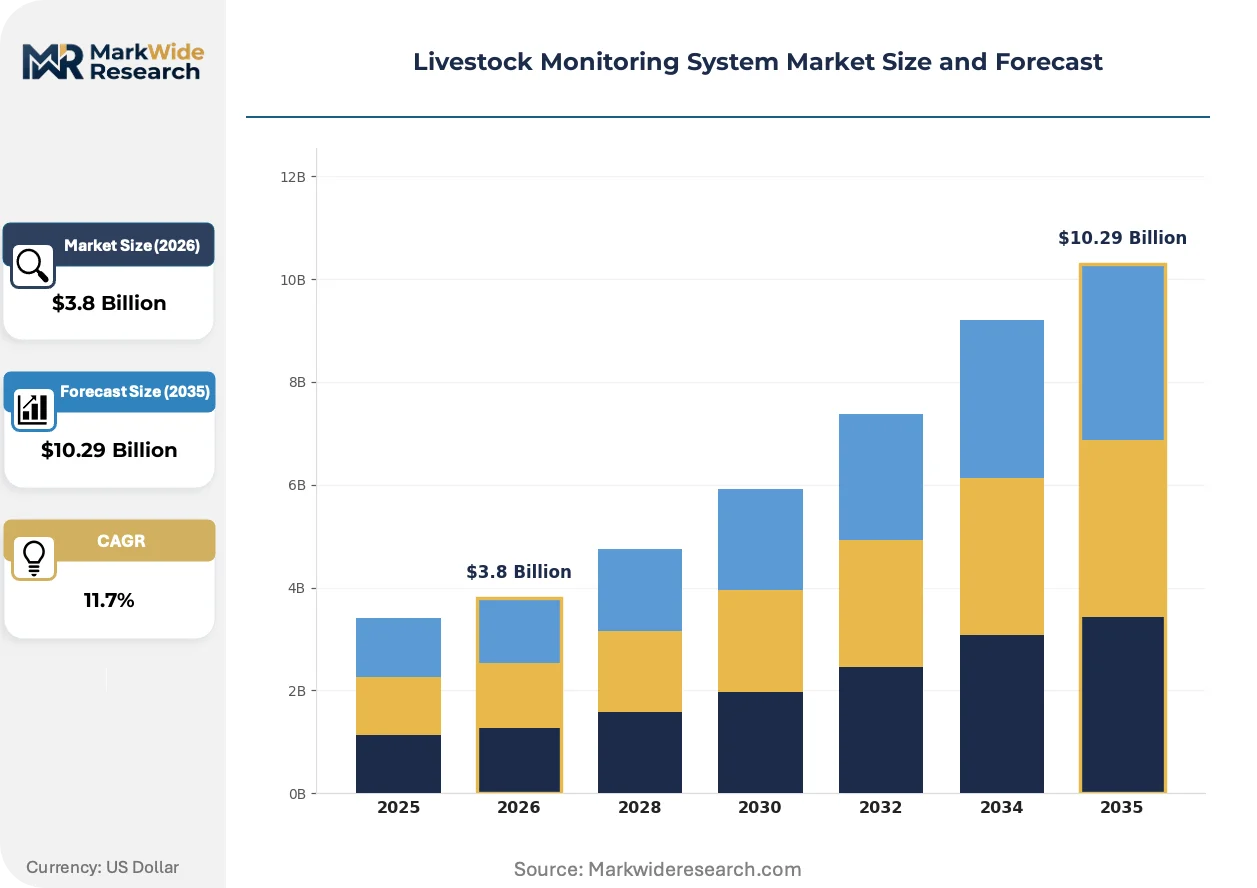
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Sensors, Software Solutions, Monitoring Platforms Technology: IoT, RFID, GPS, AI End User: Dairy Farmers, Livestock Ranchers, Veterinary Clinics, Agricultural Institutions Deployment: On-premises, Cloud-based, Hybrid, Mobile Solutions |
| Companies Covered | Merck & Co., Inc. (Allflex), DeLaval, GEA Group, Afimilk Ltd., BouMatic, Zoetis, Lely, Nedap N.V., Fancom BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Livestock Monitoring System Market Strategic Shifts
Processing architectures are bifurcating between low-latency edge inference and centralized model training, with hardware vendors racing to optimize power budgets for battery-constrained wearable form factors.
Accelerometer-based rumination detection is migrating from cloud-batch analysis to on-collar edge inference, enabling sub-minute estrus alerts without cellular connectivity. Large Australian grazing operations are piloting these systems across thousand-head stations. The shift is compressing veterinary response windows from hours to minutes while reducing recurring data transmission costs.
EFSA welfare quality protocols are mandating continuous behavioral monitoring as a condition of premium supply chain access. Dairy processors in the Netherlands and Denmark now require sensor-derived welfare scores for contract eligibility. This regulatory layer is accelerating hardware refresh cycles as older systems lack the sampling precision to generate audit-grade documentation.
Subscription-based predictive analytics are displacing perpetual-license software sales across veterinary clinic procurement. German and Brazilian distributors are bundling hardware with multi-year data service contracts. The model shift concentrates buyer relationships with platform vendors rather than equipment resellers, altering channel economics for traditional agricultural machinery dealers.
Livestock Monitoring System Market Segmentation
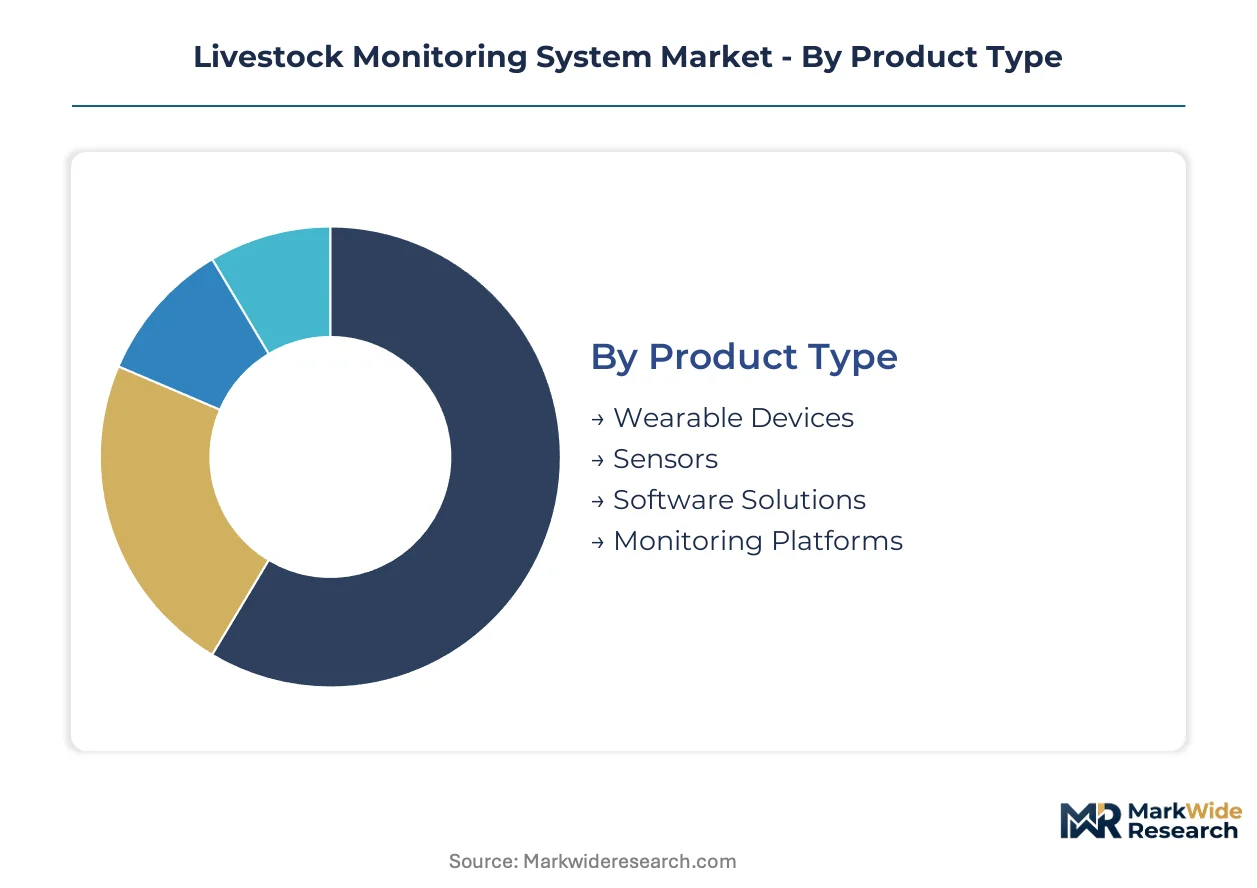
Livestock monitoring architectures fragment across hardware lifecycles, connectivity protocols, and buyer procurement sophistication. Understanding these divisions clarifies where recurring revenue concentrates versus one-time equipment sales.
Product Type:
Mature hardware categories dominate installed base volumes while software layers capture expanding margin pools through subscription economics.
- Wearable Devices:Collars, ear tags, and leg bands integrate accelerometers sampling above 10 Hz for rumination detection and temperature sensors accurate to 0.1°C for estrus identification. Dairy cooperatives in the Netherlands and Denmark mandate these for EFSA welfare quality compliance, driving replacement cycles every 3-4 years.
- Software Solutions:Predictive analytics dashboards and veterinary telemedicine platforms generate recurring subscription revenue. German distributors bundle multi-year data service contracts with hardware, displacing perpetual-license sales across veterinary clinic procurement.
- Sensors:Environmental monitors track barn humidity, ammonia levels, and ventilation efficiency. Brazilian pasture operations deploy satellite-linked variants for dispersed grazing management.
- Monitoring Platforms:Integrated hardware-software systems consolidate multi-source data streams. These command premium pricing but face interoperability constraints from proprietary API restrictions.
Wearable Devices retain volume leadership; Software Solutions hold the steepest expansion curve.
Technology:
Cost tiers separate established connectivity standards from emerging inference capabilities that reshape system architecture.
- IoT:Mesh networks of low-power wide-area sensors transmit health telemetry across cellular and LoRaWAN protocols. Australian outback stations depend on satellite backhaul where cellular coverage fails.
- RFID:Nedap N.V. anchors European dairy cooperative dominance through specialized ear tag systems. Passive and active variants enable individual animal identification for traceability compliance under EU Green Deal mandates.
- GPS:Geofencing and movement tracking collars manage thousand-head herds across Brazilian Mato Grosso and Goiás properties. Battery constraints limit sampling frequency to hourly bursts.
- AI:On-collar edge inference enables sub-minute estrus alerts without cloud dependency. Large Australian grazing operations pilot these systems across dispersed stations.
RFID retains volume leadership; AI holds the steepest expansion curve.
End User:
Customer type determines procurement sophistication, from cooperative bulk purchasing to individual rancher price sensitivity.
- Dairy Farmers:Intensive operations in the Netherlands and Denmark deploy comprehensive sensor networks for milk yield optimization and welfare documentation. EU Farm to Fork Strategy mandates accelerate hardware refresh cycles.
- Veterinary Clinics:Diagnostic practices demand predictive analytics dashboards for remote herd health monitoring. Subscription models concentrate buyer relationships with platform vendors rather than equipment resellers.
- Livestock Ranchers:Extensive grazing operations across US Great Plains and Australian rangeland prioritize satellite-linked collar systems. Rural connectivity gaps limit real-time alert reliability for cloud-dependent architectures.
- Agricultural Institutions:Research stations and extension services pilot emerging technologies. These buyers tolerate higher failure rates in exchange for early access to unproven capabilities.
Dairy Farmers retain volume leadership; Veterinary Clinics hold the steepest expansion curve.
Deployment:
Architecture choices reflect trade-offs between latency, connectivity dependency, and capital expenditure patterns.
- Cloud-based:Centralized processing dominates among livestock ranchers managing dispersed grazing operations across multiple properties. Cellular dead zones in Australian outback and US Great Plains constrain reliability.
- Hybrid:Split inference between on-farm gateways and remote servers compresses data latency to sub-second response windows. This architecture is displacing pure cloud models as edge computing matures.
- On-premises:Barn-level server installations serve operations with data sovereignty requirements or unreliable external connectivity. Higher upfront capital costs limit adoption to large-scale facilities.
- Mobile Solutions:Smartphone-dependent interfaces reduce hardware costs for cash-constrained ranchers. Functionality degrades in areas with poor cellular coverage.
Cloud-based retains volume leadership; Hybrid holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based sensor manufacturers export precision dairy monitoring equipment to German cooperatives and Danish processing clusters, establishing a North Sea trade corridor for welfare-compliant livestock technology.
United States
Cattle feedlot operators in Texas and Kansas deploy automated health tracking systems to comply with antimicrobial use documentation. The FDA's Veterinary Feed Directive mandates detailed feed additive records that sensor networks streamline. Nebraska's Precision Livestock Farming Consortium accelerates pilot programs across Midwestern ranching operations.
Germany
Dairy processors in Bavaria and Lower Saxony require sensor-derived welfare scores for contract eligibility under tightening supply chain standards. The EU Green Deal's Farm to Fork Strategy accelerates hardware refresh cycles among northern dairy cooperatives. Stuttgart's agricultural technology cluster hosts multiple system integrators serving cooperative procurement networks.
Brazil
Ranchers across Mato Grosso and Goiás manage dispersed thousand-head herds through satellite-linked collar systems. ANVISA's veterinary product registration framework shapes device import requirements for South American distributors. São Paulo's agribusiness financing sector bundles monitoring hardware with pasture expansion credit facilities.
Australia
Extensive grazing stations in Queensland and New South Wales pilot edge-computing collars enabling sub-minute estrus alerts without cellular dependency. The TGA's veterinary device classification system influences software-as-a-service compliance pathways. Wagga Wagga's livestock research hub validates ruggedized hardware for outback deployment conditions.
India
Milk unions in Gujarat and Maharashtra digitize cooperative records through low-cost ear tag systems. The National Dairy Development Board's rural technology initiatives create first-mover procurement channels for domestic and international vendors. Anand's dairy technology corridor serves as the implementation testbed for national cooperative digitization programs.
Livestock Monitoring System Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement relationships. Consolidation pressure concentrates influence among platform vendors bundling hardware with multi-year data subscriptions, while fragmented equipment resellers lose margin to direct manufacturer relationships. Three archetypes dominate: Scandinavian-origin integrated system houses, veterinary pharmaceutical extenders, and specialized identification technology developers. Competitive dynamics center on strategic partnerships with dairy processing cooperatives and geographic expansion through distributor acquisition.
Among the named participants, DeLaval and Lely represent Scandinavian-origin integrated system houses leveraging manufacturing proximity to northern European dairy clusters. Nedap N.V. occupies a position exemplifying specialized identification technology developers focused on RFID ear tag systems. Zoetis anchors the veterinary pharmaceutical extender archetype, translating animal health diagnostics heritage into wearable monitoring applications. Merck & Co., Inc. (Allflex) and GEA Group sit within diversified agricultural equipment portfolios where livestock monitoring serves as a connected component within broader farm management ecosystems.
| Leading Market Players |
|---|
| Merck & Co., Inc. (Allflex) |
| DeLaval |
| GEA Group |
| Afimilk Ltd. |
| BouMatic |
| Zoetis |
| Lely |
| Nedap N.V. |
| Fancom BV |
| Others |
Value Chain & Pricing Dynamics
Lithium battery supply concentration in Chinese cell manufacturing determines both margin compression risks for wearable device vendors and the three-tier pricing structure separating premium Scandinavian systems from mid-tier distributors and economy-focused ear tag suppliers. This single-source dependency cascades through procurement decisions, forcing hardware vendors to absorb volatility or pass costs downstream.
Pricing Analysis
Current-generation edge-computing collars with on-collar inference command substantial premiums over prior-generation cloud-dependent systems and emerging next-generation satellite-integrated platforms. Pricing stratifies across premium, standard, and economy tiers based on sampling precision certification and after-sales subscription bundling. Cost compression in the standard tier is intensifying as Brazilian and Indian distributors negotiate volume procurement contracts. Dairy cooperatives in the Netherlands and Denmark exhibit the least price sensitivity due to regulatory compliance mandates, while individual livestock ranchers across the US Great Plains demonstrate acute sensitivity to upfront hardware costs.
Supply Chain Analysis
Tariff exposure between Chinese lithium cell suppliers and European wearable device assemblers dominates supply chain risk assessments for hardware vendors. Manufacturing concentrates in China for battery components, the Netherlands and Denmark for precision dairy systems, and Brazil for satellite-linked pasture collars. Raw material dependencies include lithium carbonate, rare earth magnets for GPS modules, and medical-grade silicone for barn-hardened housings. Distribution runs through agricultural machinery dealer networks in developed markets and direct-to-cooperative procurement channels in emerging dairy regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Livestock monitoring represents an early-cycle expansion story as regulatory traceability mandates under the EU Green Deal's Farm to Fork Strategy accelerate first-time sensor deployment across previously manual operations.
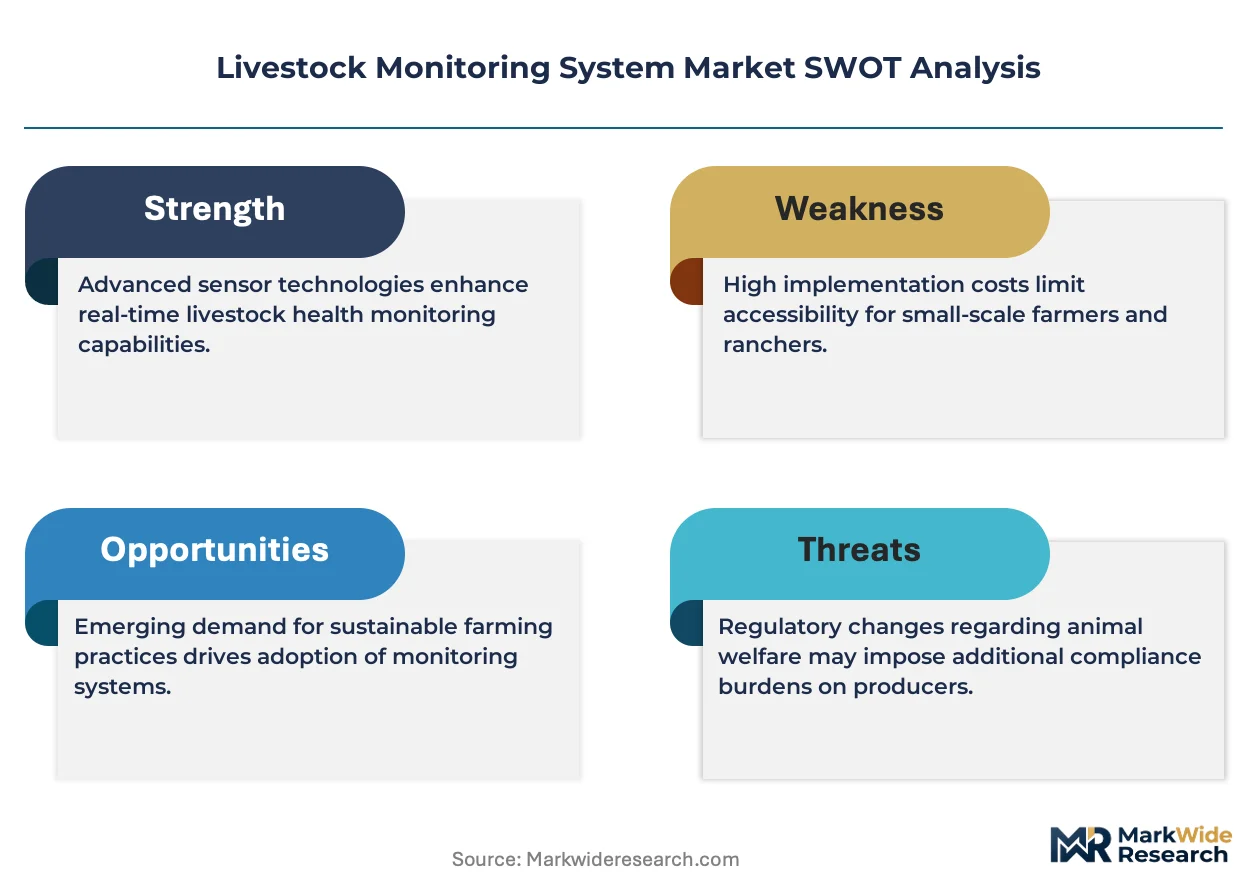
For Market Incumbents: Harden platform architecture against interoperability demands by opening API access to veterinary clinic dashboards, neutralizing the proprietary data lock-in threat that drives customer churn. Deepen backward integration into lithium cell supply through offtake agreements with non-Chinese suppliers, securing margin stability against export control friction. Prioritize certification investment for EFSA welfare quality protocol compliance to maintain contract eligibility with Dutch and Danish dairy processors. For New Entrants and Emerging Players: India's Gujarat and Maharashtra milk unions represent the most penetrable entry point, with National Dairy Development Board procurement channels creating first-mover advantages for low-cost ear tag systems. Veterinary telemedicine platform integration offers a differentiated go-to-market angle, subsidizing hardware deployment through recurring diagnostic subscription revenue. Brazilian pasture expansion in Mato Grosso and Goiás provides secondary white-space for satellite-linked collar systems serving dispersed grazing operations. For Investors and Strategic Acquirers: ANVISA's veterinary product registration framework in Brazil and TGA's device classification evolution in Australia reshape the acquisition landscape by elevating regulatory compliance capabilities as valuation drivers. The 5-10 year viability window favors platform vendors with proven cooperative relationships over pure hardware manufacturers facing margin erosion. Acquisition targets should demonstrate embedded firmware engineering depth and multi-jurisdiction data sovereignty infrastructure. The signal to watch is hardware refresh cycle acceleration among European dairy cooperatives as EFSA protocols tighten sampling precision requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Integration | On-collar inference reduces cloud dependency for Australian outback stations with cellular dead zones. |
| Blockchain-IoT Convergence | Immutable health records enable premium protein sourcing contracts with EU retailers demanding traceability. |
| Veterinary Telemedicine Platform Launch | Remote diagnostic subscriptions subsidize hardware costs for cash-constrained ranchers in Brazil and India. |
| RFID Ear Tag System Expansion | Nedap N.V.'s cooperative dominance demonstrates channel control value in European dairy procurement networks. |
| Hybrid Deployment Architecture | Split inference between barn gateways and remote servers compresses latency for real-time estrus alerts. |
Study Parameters
Initial hypotheses were tested against primary input from dairy cooperative procurement managers, veterinary clinic diagnostic directors, livestock rancher operations heads, and agricultural technology distributor principals, then refined through secondary validation against customs trade data, SEC 10-K filings from listed equipment manufacturers, EU Green Deal implementation progress reports, and national dairy board procurement disclosures. Bottom-up equipment shipment tracking and top-down agricultural technology spending estimates were triangulated to reconcile volume and value figures.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling segmentation dimensions including product type, connectivity technology, end-user procurement sophistication, and deployment architecture. CAGRs were derived from fitted growth curves incorporating hardware replacement cycle compression, subscription revenue attach rate expansion, and regulatory mandate adoption curves. Industry-specific forecast inputs included EFSA welfare quality protocol implementation timelines and National Dairy Development Board digitization budget allocations.
Practitioners should monitor lithium supply chain disruptions, cellular infrastructure expansion in Australian rangeland, and divergent national data sovereignty regulations for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Cattle Supplies Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Livestock Panel Gates Market
Livestock Equipment
Horse Bell Boots Market
Livestock Equipment
Horse Corral Panels Market
Livestock Equipment
Starter Feed Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
Nigeria Horse Riding Equipment Market
Livestock Equipment
Automatic Hog Feeder Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Livestock Farm Equipment Market
Livestock Equipment
Hog Feeder Market
Livestock Equipment
Sheep Handling Equipment Market