
 Cattle Grooming Chute Market | 2026-2036
Cattle Grooming Chute Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Grooming Chute Market Outlook
OSHA livestock handling guidelines is decoupling manual labor dependency from capital equipment decisions across North American cattle operations. Priefert leverages its Texas manufacturing base to anchor supply contracts with regional feedlot networks. Powder River competes through powder-coated frame durability that extends replacement cycles in high-throughput environments. Moly Manufacturing specializes in hydraulic lift integration that reduces operator strain during daily grooming protocols.
A cattle grooming chute is a stationary or mobile restraint apparatus incorporating adjustable side panels, rotating brush assemblies, and hydraulic or manual squeeze mechanisms designed to immobilize individual animals for coat cleaning, parasite inspection, and pre-processing hygiene. The equipment typically employs galvanized steel tubing rated for animals exceeding 1,500 pounds, with brush systems operating at variable speeds to accommodate different coat conditions and temperament levels. Portable chutes command expanding share among rotational grazing operations requiring field-deployable equipment, while fixed chutes sustain margin concentration in permanent feedlot installations where throughput justifies concrete anchoring. Hydraulic chutes lead technology substitution as end users prioritize operator safety and reduced handling time, whereas electric chutes occupy niche positioning in exhibition and show contexts demanding precision control.
USDA-FSIS sanitation protocols and OSHA workplace safety mandates collectively elevate equipment specification thresholds, compelling manufacturers to certify restraint systems for animal welfare compliance and operator protection simultaneously. The EPA's emerging scrutiny of wash-water runoff from grooming operations is reshaping site engineering requirements for permanent installations. Stakeholders must weigh capital deployment timing against pending regulatory clarifications on hydraulic fluid containment and brush disinfection protocols before committing to multi-unit procurement strategies.
Market Dynamics
USDA-FSIS sanitary mandates and OSHA livestock handling guidelines are compressing equipment replacement cycles across North American cattle operations, forcing capital allocation toward hydraulic systems that reduce manual labor exposure while meeting escalating pre-slaughter hygiene protocols.
Growth Catalysts
- OSHA workplace safety mandates:North American feedlot operators face escalating liability exposure from manual restraint injuries, accelerating capital substitution toward automated squeeze mechanisms and hydraulic lift systems that isolate operators from kick zones.
- Rotational grazing expansion:Portable chute demand is climbing among pasture-based operations in Australia and Brazil where field-deployable equipment eliminates transport stress and enables point-of-use grooming without permanent infrastructure investment.
- Brush system automation:Variable-speed rotating assemblies with integrated parasite detection sensors are displacing manual coat inspection, reducing handling time per animal while improving pathogen screening consistency for export-certified herds.
Market Restraints
- Galvanized steel price volatility:Tubing rated for 1,500-pound animals constitutes the primary structural input, and fluctuating zinc coating costs compress manufacturer margins during procurement cycles for large-frame chute production.
- Hydraulic fluid containment regulations:The EPA's emerging scrutiny of wash-water runoff creates site engineering uncertainty, delaying multi-unit procurement commitments among permanent feedlot operators awaiting clarified containment protocol specifications.
- Electric chute substitution ceiling:Precision control systems for exhibition contexts face demand compression from hydraulic alternatives in commercial settings, limiting addressable market expansion for electric-actuation specialists.
Strategic Opportunities
- Underpenetrated rotational grazing segments:Portable chute deployment remains sparse among mid-scale pasture operations in Argentina and Uruguay, creating white space for field-deployable systems with rapid setup mechanisms.
- EU Green Deal agricultural modernization incentives:European livestock handling equipment subsidies are channeling capital toward welfare-compliant restraint systems, opening procurement pathways for manufacturers certifying to EFSA animal handling standards.
- IoT-enabled maintenance unbundling:Sensor-integrated chutes transmitting brush wear and hydraulic pressure data to OEM service networks are creating recurring revenue streams that decouple manufacturer economics from unit sales alone.
Industry Challenges
- Veterinary technician certification timelines:Proper operation of hydraulic squeeze mechanisms requires species-specific handling credentials that lag equipment deployment, creating utilization gaps and liability exposure during operator onboarding.
- Legacy manual chute integration:Feedlots with sunk capital in fixed concrete-anchored systems face dislocation costs when retrofitting for hydraulic compatibility, slowing technology substitution despite safety mandate pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Grooming Chute Market |
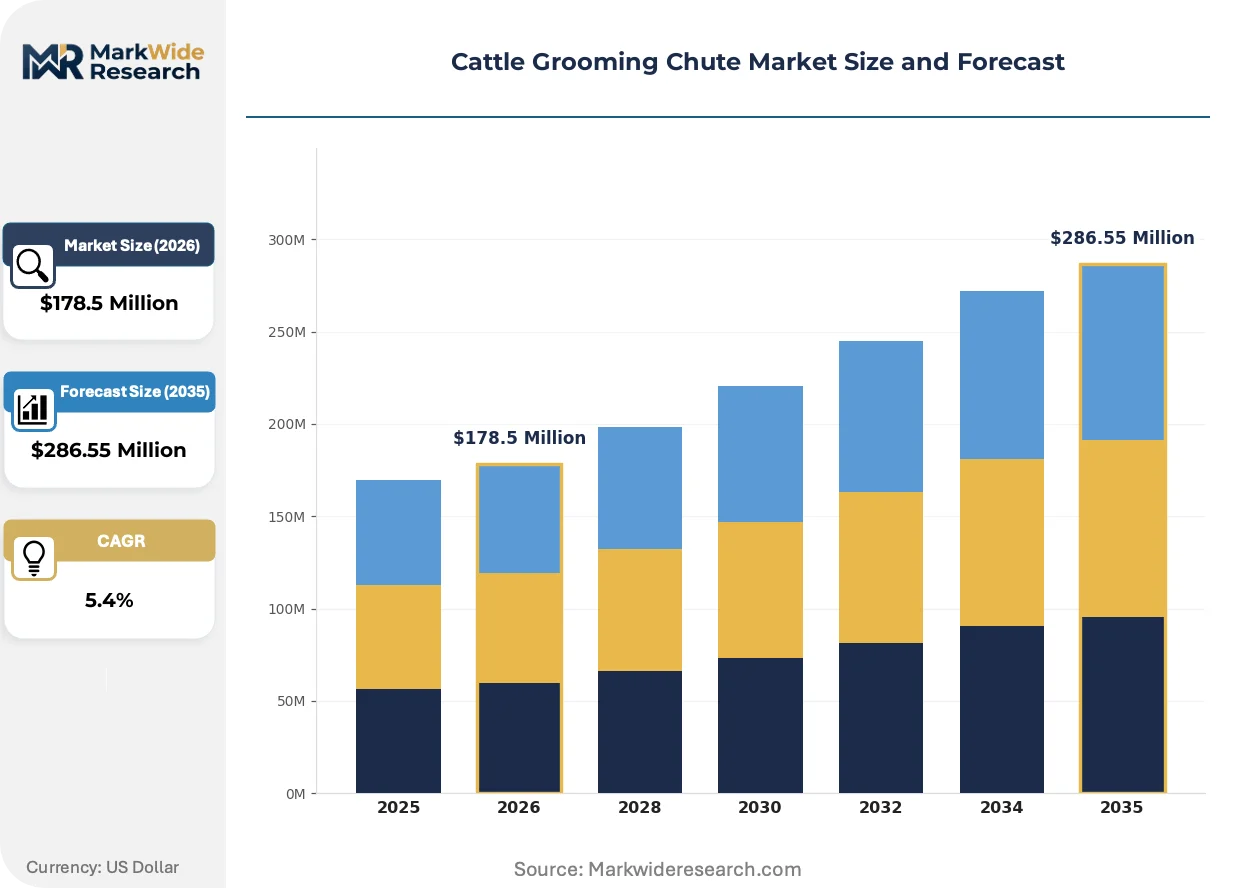
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $286.55 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chutes, Fixed Chutes, Hydraulic Chutes, Electric Chutes End User: Livestock Farms, Veterinary Clinics, Agricultural Shows, Dairy Operations Component: Frame, Brushes, Restraint Systems, Hydraulic Lift Installation: On-site Installation, Pre-assembled Units, Mobile Units, DIY Kits |
| Companies Covered | Riverode, Hi-Hog, Appleton Steel, Priefert, Powder River, Moly Manufacturing, Tuffy Tables, WW Manufacturing, MJE Livestock Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Grooming Chute Market Strategic Shifts
Equipment intelligence and regulatory compliance automation are converging to reshape capital deployment patterns across cattle handling infrastructure, compressing the traditional tradeoff between throughput volume and animal welfare certification.
Portable chute systems with rapid-deployment folding frames and towable configurations are decentralizing equipment ownership models across extensive grazing operations. Mid-scale ranchers in Australia and the Brazilian Cerrado are acquiring mobile units rather than contracting regional grooming services, collapsing the historical radius of commercial chute utilization and fragmenting demand across dispersed geographic points.
The EPA's pending hydraulic fluid containment rules for agricultural wash-water systems are forcing engineering redesigns of permanent installation drainage. Feedlot operators in Texas and Nebraska are pre-emptively specifying closed-loop hydraulic reservoirs and sealed brush housing assemblies, accelerating procurement of next-generation chutes ahead of formal compliance deadlines to avoid retrofitting stranded assets.
Leasing arrangements with bundled maintenance and certification support are displacing outright purchase among capital-constrained operations. Regional equipment distributors in the United States are capturing margin expansion through subscription-based service models that include OSHA compliance training and USDA-FSIS documentation assistance, shifting buyer relationships from transactional procurement to ongoing operational partnerships.
Cattle Grooming Chute Market Segmentation
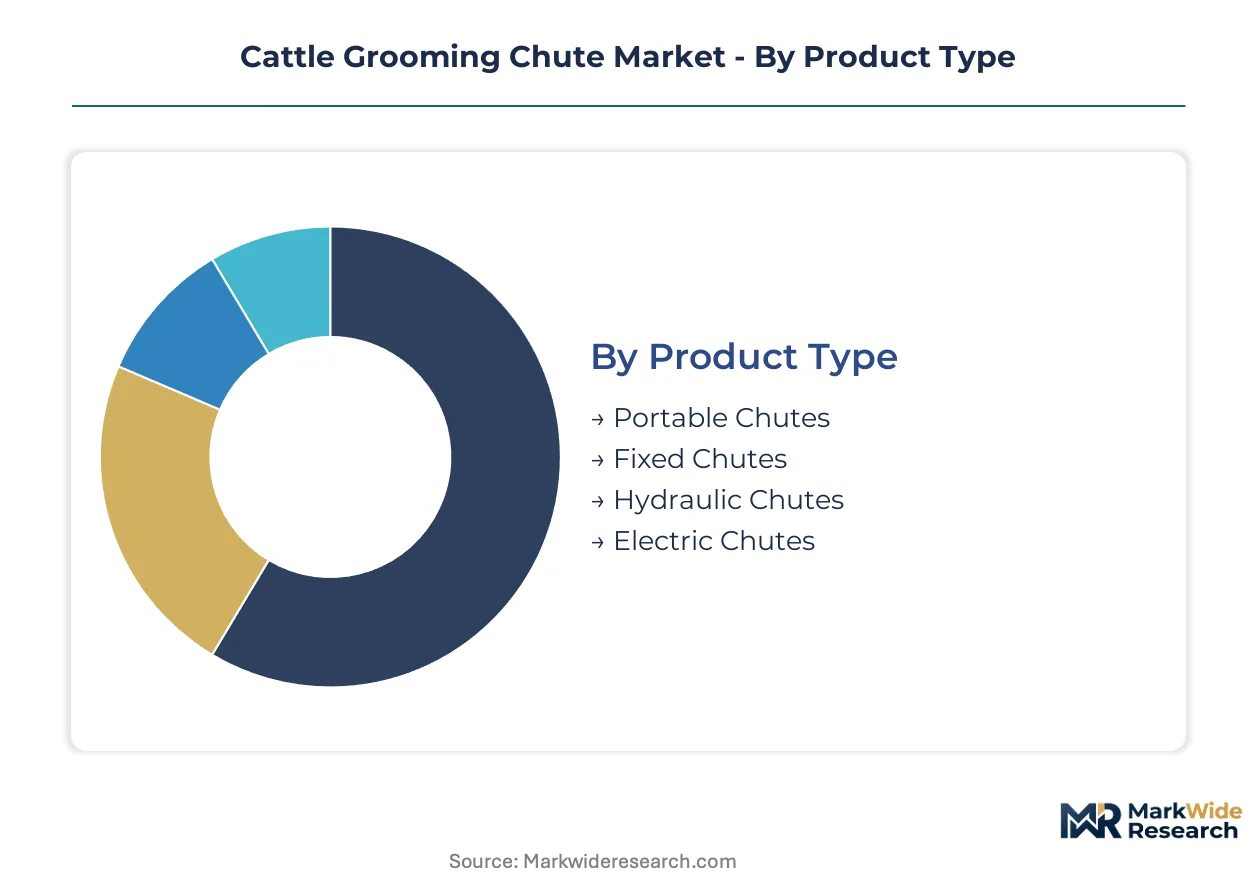
Cattle grooming chute procurement patterns diverge sharply between capital-intensive permanent installations and mobility-driven operational models. Equipment specification varies by end-use intensity, from daily throughput demands at commercial feedlots to episodic deployment at exhibition venues.
Product Type:
Hydraulic systems command premium positioning through labor substitution economics, while portable configurations address geographic fragmentation in extensive grazing systems.
- Portable Chutes:Folding-frame designs with towable configurations enable field-deployable restraint without concrete anchoring. Demand concentrates among rotational grazing operations in Australia and Brazil where transport infrastructure limits permanent facility investment.
- Fixed Chutes:Concrete-anchored steel assemblies rated for 1,500-pound animals sustain margin concentration in Texas and Nebraska feedlots where daily throughput justifies infrastructure permanence and USDA-FSIS compliance documentation.
- Hydraulic Chutes:Automated squeeze mechanisms with closed-loop fluid reservoirs reduce operator strain and accelerate handling cycles.
- Electric Chutes:Precision-actuated systems serve exhibition contexts requiring temperament-sensitive control.
Mature deployment sits with Fixed Chutes. Newer deployment is concentrated in Portable Chutes.
End User:
Commercial throughput requirements separate capital equipment decisions from episodic-use procurement patterns.
- Livestock Farms:Extensive grazing operations and confined feeding operations represent the volume foundation, with procurement scaling from single-unit mobile systems to multi-station permanent installations based on herd size and handling frequency.
- Dairy Operations:Pre-slaughter hygiene protocols and milk quality regulations drive consistent grooming scheduling, creating recurring equipment utilization that amortizes capital investment across higher duty cycles than beef-only counterparts.
- Veterinary Clinics:Mixed-species practices require adaptable restraint configurations.
- Agricultural Shows:Exhibition contexts prioritize animal presentation quality over throughput speed.
Volume concentration rests with Livestock Farms. Margin expansion concentrates in Dairy Operations.
Component:
Structural durability specifications and automation integration levels define replacement cycle economics.
- Frame:Galvanized steel tubing construction withstands corrosive wash-water exposure and animal impact loads, with powder-coated alternatives extending service intervals in high-throughput environments through enhanced abrasion resistance.
- Hydraulic Lift:Integrated vertical positioning systems reduce operator musculoskeletal injury exposure while enabling single-operator handling protocols that collapse labor requirements per animal.
- Brushes:Variable-speed rotating assemblies with replaceable bristle configurations accommodate coat condition variation.
- Restraint Systems:Adjustable side panels and squeeze mechanisms immobilize animals for inspection access.
Component upgrade cycles accelerate for Hydraulic Lift systems. Frame replacement extends longest across all configurations.
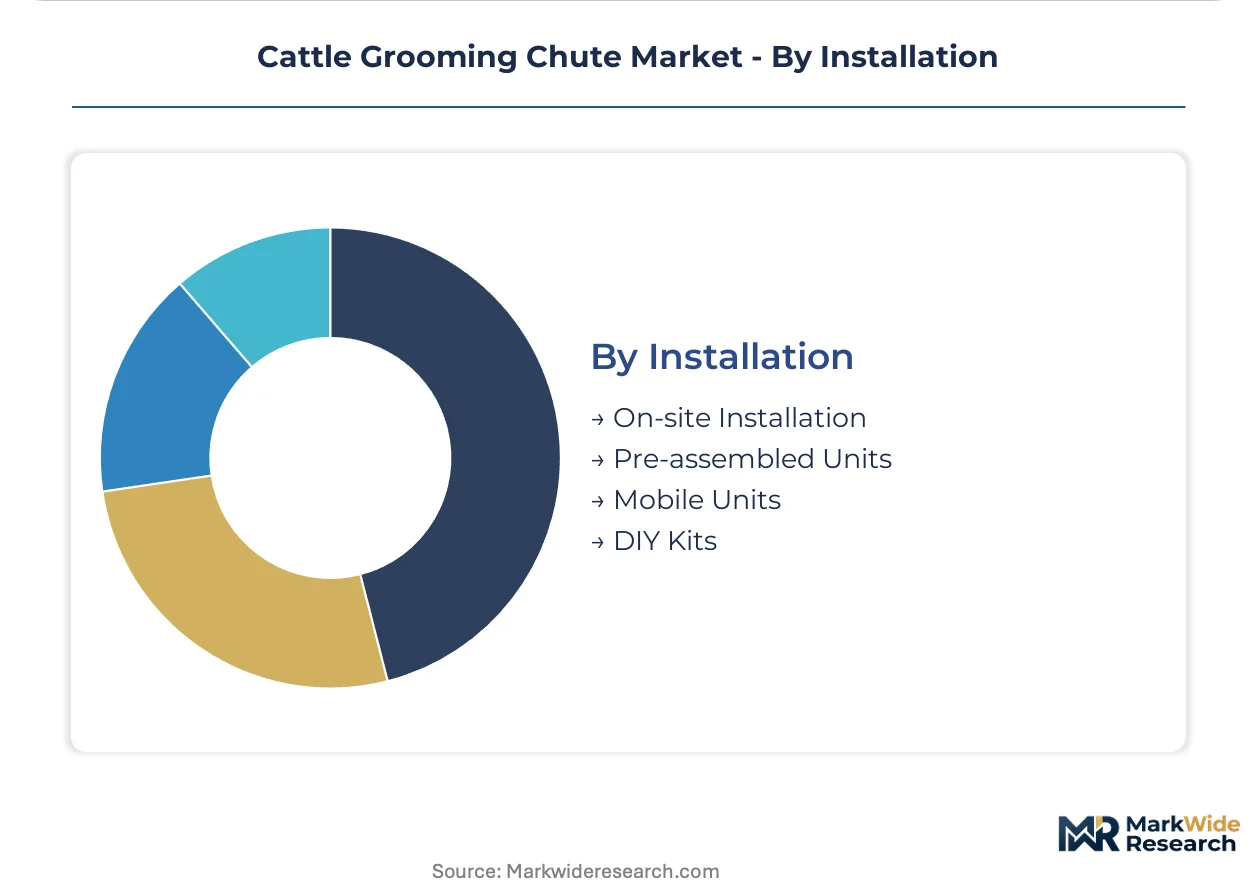
Installation:
Ownership model fragmentation separates capital-constrained operators from infrastructure-committed facilities.
- On-site Installation:Permanent concrete anchoring with integrated drainage and electrical supply serves feedlot operators maximizing throughput efficiency, with engineering specifications adapting to pending EPA hydraulic fluid containment mandates.
- Pre-assembled Units:Factory-configured systems reduce field commissioning time and warranty exposure, appealing to operations prioritizing operational continuity over customization flexibility.
- Mobile Units:Rapid-deployment configurations serve dispersed pasture operations.
- DIY Kits:Modular assembly options address price-sensitive smaller operations.
Service revenue attachment climbs with On-site Installation. Equipment mobility defines Mobile Units expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial feedlot density in Texas and Nebraska drives North American equipment procurement, while extensive grazing systems in Brazil and Australia generate parallel demand for portable configurations. Regulatory pressure from USDA-FSIS and OSHA compresses replacement cycles across these markets.
United States
Texas Panhandle feedlots and Nebraska's Platte River valley concentrate permanent chute installations serving daily throughput operations. OSHA livestock handling guidelines and USDA-FSIS sanitary mandates elevate hydraulic system specifications. Priefert anchors regional supply contracts from its Texas manufacturing base.
Brazil
The Cerrado and Pantanal regions drive portable chute demand among rotational grazing operations spanning vast pasture holdings. ANVISA veterinary equipment standards and emerging federal livestock welfare protocols shape import specifications. Campo Grande-based distributors capture margin through mobile unit leasing.
Australia
Queensland and New South Wales pastoral zones deploy field-deployable chutes eliminating animal transport stress. The country's national agricultural safety regulator enforces operator certification requirements for hydraulic restraint systems. Toowoomba equipment networks service dispersed station properties.
Canada
Alberta feedlots and Saskatchewan grazing operations balance permanent and portable procurement based on herd scale and winter confinement patterns. Health Canada veterinary drug residue monitoring intersects with pre-slaughter grooming protocols. Lethbridge agricultural equipment clusters serve Prairie province demand.
Argentina
The Pampas grasslands present underpenetrated white space for portable chute deployment among mid-scale estancia operations. SENASA livestock traceability requirements elevate hygiene documentation needs. Rosario distribution channels remain fragmented relative to equipment potential.
Cattle Grooming Chute Market Competitive Environment
United States producers anchor the premium hydraulic tier; Australian and Canadian specialists hold positioning in portable configurations. Market structure reflects moderate consolidation around regional fabrication networks serving feedlot procurement clusters. Three archetypes dominate: vertically integrated full-line manufacturers, regional steel fabrication specialists, and mobile equipment pure-plays. Competitive moves concentrate on capacity expansion in hydraulic assembly and strategic partnerships with regional veterinary service networks.
Among United States-based fabricators, Priefert, Powder River, and Moly Manufacturing occupy positions spanning the equipment spectrum. Priefert represents the vertically integrated archetype with captive Texas production capacity. Powder River exemplifies durability-focused positioning through powder-coated frame specialization. Moly Manufacturing anchors the hydraulic lift integration segment serving operator safety mandates.
| Leading Market Players |
|---|
| Riverode |
| Hi-Hog |
| Appleton Steel |
| Priefert |
| Powder River |
| Moly Manufacturing |
| Tuffy Tables |
| WW Manufacturing |
| MJE Livestock Equipment |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators concentrated in Texas and Queensland exercise pricing discipline through captive regional distribution networks, while their capital-constrained counterparts in Brazil and Argentina absorb margin compression through spot zinc procurement and deferred equipment refresh cycles.
Pricing Analysis
Lead-time-driven pricing stratification separates premium hydraulic systems with 8-12 week fabrication queues from spot-inventory electric chutes carrying 15-20% discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier (USDA-FSIS compliance versus exhibition-grade specifications) and volume scale (multi-unit feedlot contracts versus single-ranch procurement). Cost compression in economy-tier galvanized tubing is intensifying because Brazilian distributors are flooding adjacent markets with depreciated currency inventory. Dairy operations exhibit lowest price sensitivity due to amortization across daily handling cycles; rotational grazing specialists in Argentina demonstrate highest sensitivity, deferring replacement until brush-system failure.
Supply Chain Analysis
Regional distribution centers in Lubbock, Campo Grande, and Toowoomba anchor hub-and-spoke patterns radiating toward feedlot clusters and pastoral stations. Manufacturing concentrates in the United States, Brazil, and Australia, with each hub drawing from domestic steel tubing mills and imported hydraulic actuator assemblies. Raw material dependencies rest on zinc-coated steel tubing, synthetic brush bristles, and closed-loop hydraulic fluid systems. Single-source vulnerability in hydraulic pump assemblies sourced from German and Japanese specialists creates procurement risk. Distribution runs through agricultural equipment dealerships with bundled installation and certification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA livestock handling guidelines and USDA-FSIS sanitary mandates construct a cost-of-compliance barrier that rewards incumbents with certified production infrastructure while forcing marginal fabricators toward distressed exit or acquisition.
For Market Incumbents: Anchor market position through backward integration into galvanized steel tubing production and captive hydraulic assembly capacity in Texas and Nebraska. Defensive consolidation should prioritize acquiring regional veterinary service networks to bundle equipment sales with OSHA compliance training. The threat of portable chute pure-plays disrupting permanent installation margins demands channel control through exclusive dealership arrangements. For New Entrants and Emerging Players: Launch via mobile equipment leasing models targeting underpenetrated mid-scale estancia operations in Argentina's Pampas grasslands, where SENASA traceability requirements are elevating hygiene documentation needs without corresponding equipment deployment. The most penetrable segment is field-deployable rapid-setup configurations for rotational grazing. Go-to-market execution should partner with Rosario-based agricultural cooperatives for last-mile distribution. For Investors and Strategic Acquirers: Distressed-cycle entries favor hydraulic lift specialists with USDA-FSIS certification infrastructure in the United States and Queensland, where replacement cycle compression is accelerating capital deployment. Long-term viability over a 5-10 year window rests on recurring revenue attachment through IoT-enabled maintenance subscriptions. The signal to watch is EPA finalization of hydraulic fluid containment rules, which will strand non-compliant inventory and consolidate procurement toward pre-certified next-generation systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanized Steel Tubing | Captive supply of 1,500-pound-rated structural inputs insulates margin from zinc price volatility. |
| Hydraulic Assembly Capacity Expansion | Regional fabrication in Texas and Nebraska compresses lead times for OSHA-mandated safety systems. |
| IoT-Enabled Maintenance Subscription Launch | Sensor-integrated chutes transmitting brush wear data to OEM networks create recurring revenue streams. |
| Veterinary Service Network Acquisition | Bundled OSHA compliance training with equipment sales locks in feedlot procurement relationships. |
| Portable Chute Rapid-Deployment Engineering | Folding-frame configurations for Brazil's Cerrado and Australia's Queensland pastoral zones capture rotational grazing demand. |
Study Parameters
Independent corroboration across feedlot operations managers, agricultural equipment dealership principals, and hydraulic systems engineers underwrites the qualitative findings. Primary interviews with USDA-FSIS compliance officers, veterinary technician certification bodies, and regional steel fabrication plant managers were cross-referenced against secondary validation from SEC filings of publicly traded agricultural equipment manufacturers, customs records of galvanized steel tubing imports, and EPA docket submissions on hydraulic fluid containment proposals. Bottom-up unit deployment estimates from feedlot capacity expansions in Texas and Nebraska were triangulated with top-down capital expenditure surveys from Brazilian and Australian pastoral associations.
Rate-of-change decomposition across the projection horizon isolates equipment replacement cycle compression from net new installation demand. The analytical framework models segmentation dimensions including product type (hydraulic, electric, portable, fixed), end user (livestock farms, dairy operations, veterinary clinics, agricultural shows), and installation model (on-site, pre-assembled, mobile, DIY). CAGRs were derived from regression analysis of historical capital expenditure patterns against regulatory mandate implementation timelines. Industry-specific forecast inputs include OSHA injury rate data driving hydraulic substitution and ANVISA veterinary equipment standard adoption curves in Brazil.
The model assumes a particular technology adoption path; alternative pathways for electric-actuated precision control systems would alter the outlook if exhibition contexts expand beyond niche positioning. Forecasts reflect assumptions regarding EPA rule finalization timing and zinc price stabilization. Specific risk factors that could revise projections include delayed veterinary technician certification timelines creating utilization gaps, and stranded asset exposure from premature hydraulic chute deployment ahead of containment protocol clarification. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Starter Feed Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Sheep Creep Feeder Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Rabbit Hutches Market
Livestock Equipment
Horse Bell Boots Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Livestock Panel Gates Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Horse Stable Supplies Market
Livestock Equipment
China Horse Riding Equipment Market