
 Livestock Trailers Market | 2026-2036
Livestock Trailers Market Size, Share, and Industry Trends Forecast 2026-2036
Livestock Trailers Market Insights
Maintenance subscription packages for brake systems, flooring inspections, and ventilation calibration is recalibrating how fleet operators budget total cost of ownership across replacement cycles. Cimarron Trailers leverages in-house aluminum fabrication to control material sourcing and lead times. Sundowner Trailers anchors its position through dealer-network density across the southern plains. Logan Coach differentiates with modular interior configurations that adapt from cattle to equine transport.
Livestock trailers are specialized towable vehicles engineered for safe animal transport, typically constructed with non-slip aluminum flooring, slatted sidewalls for airflow, and partitioned compartments rated for species-specific weight loads; their primary purpose is to move cattle, swine, sheep, and other farm animals between production sites, auctions, and processing facilities while minimizing stress and injury. Gooseneck trailers dominate commercial hauler fleets due to superior stability at highway speeds and higher gross vehicle weight ratings. Bumper pull configurations sustain strong farmer-level demand where lighter towing requirements and lower price points align with smaller herd sizes. Aluminum material construction leads the premium tier for corrosion resistance and payload optimization, while steel persists in value-oriented stock trailer segments.
DOT Federal Motor Carrier Safety Administration hours-of-service rules shape long-haul livestock transport scheduling and trailer investment cycles, while NHTSA lighting and conspicuity standards govern rear-impact protection design. Transport Canada NSC Standard 11 mirrors U.S. brake and structural requirements, creating cross-border fleet commonality. Stakeholders must monitor pending animal welfare transport duration limits from USDA and CFIA that could mandate onboard water systems and climate control retrofits.
Market Dynamics
Aluminum-intensive construction is automating fleet compliance with DOT and Transport Canada weight regulations while compressing payload optimization cycles across commercial livestock hauler operations.
Growth Catalysts
- Feedlot Density Concentration:The Texas-Oklahoma corridor sustains the densest interstate livestock haul volumes in North America, driving replacement demand for high-capacity gooseneck configurations among commercial operators.
- Cross-Border Regulatory Alignment:Transport Canada NSC Standard 11 mirrors U.S. brake and structural requirements, enabling fleet commonality and reducing compliance friction for operators running transnational routes.
- Processor Scheduling Compression:Meatpacking facility just-in-time delivery mandates are forcing haulers to expand trailer fleet capacity and reduce loading turnaround times.
Market Restraints
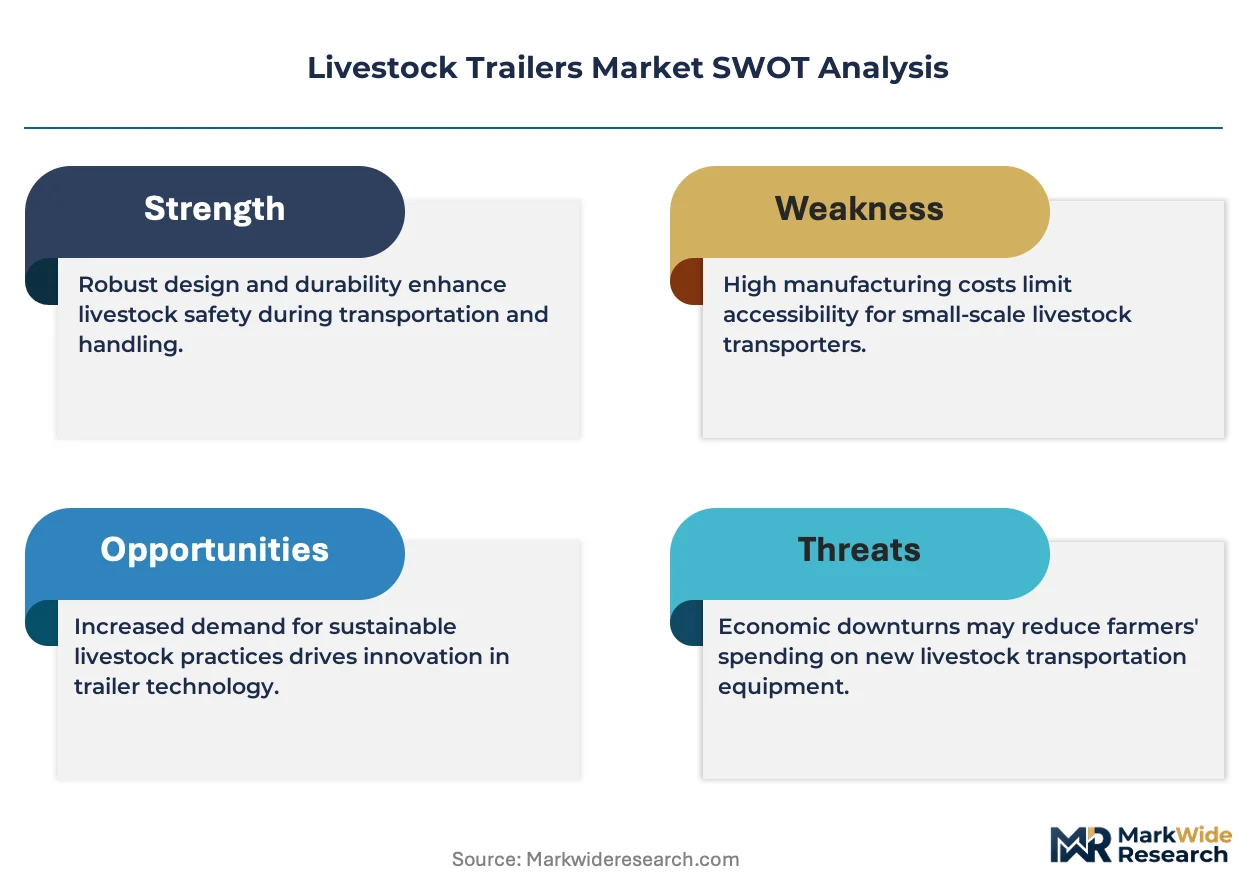
- Aluminum Input Cost Volatility:Primary aluminum price swings strain fabrication margins for trailer manufacturers committed to corrosion-resistant, lightweight construction.
- Steel Frame Displacement Lag:Value-oriented stock trailer segments persist with steel construction, fragmenting material standardization and complicating supplier economies of scale.
- Hours-of-Service Compliance Friction:DOT Federal Motor Carrier Safety Administration scheduling rules constrain long-haul livestock transport windows, reducing asset utilization rates for fleet operators.
Strategic Opportunities
- Onboard Climate System Retrofits:Pending USDA and CFIA animal welfare transport duration limits could mandate water systems and ventilation upgrades, creating aftermarket service revenue streams.
- Modular Interior Convergence:Partition systems adaptable across cattle, swine, and equine transport are opening fleet flexibility for diversified agricultural operators.
- Maintenance Subscription Expansion:Brake system monitoring, flooring inspection, and ventilation calibration packages are recalibrating total cost of ownership budgeting across replacement cycles.
Industry Challenges
- Certification Timeline Compression:NHTSA lighting and conspicuity standards for rear-impact protection design require engineering validation cycles that delay new model introductions.
- Specialized Welding Talent Scarcity:Aluminum fabrication expertise for structural joints and flooring assemblies remains concentrated among legacy skilled trades, constraining production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Livestock Trailers Market |
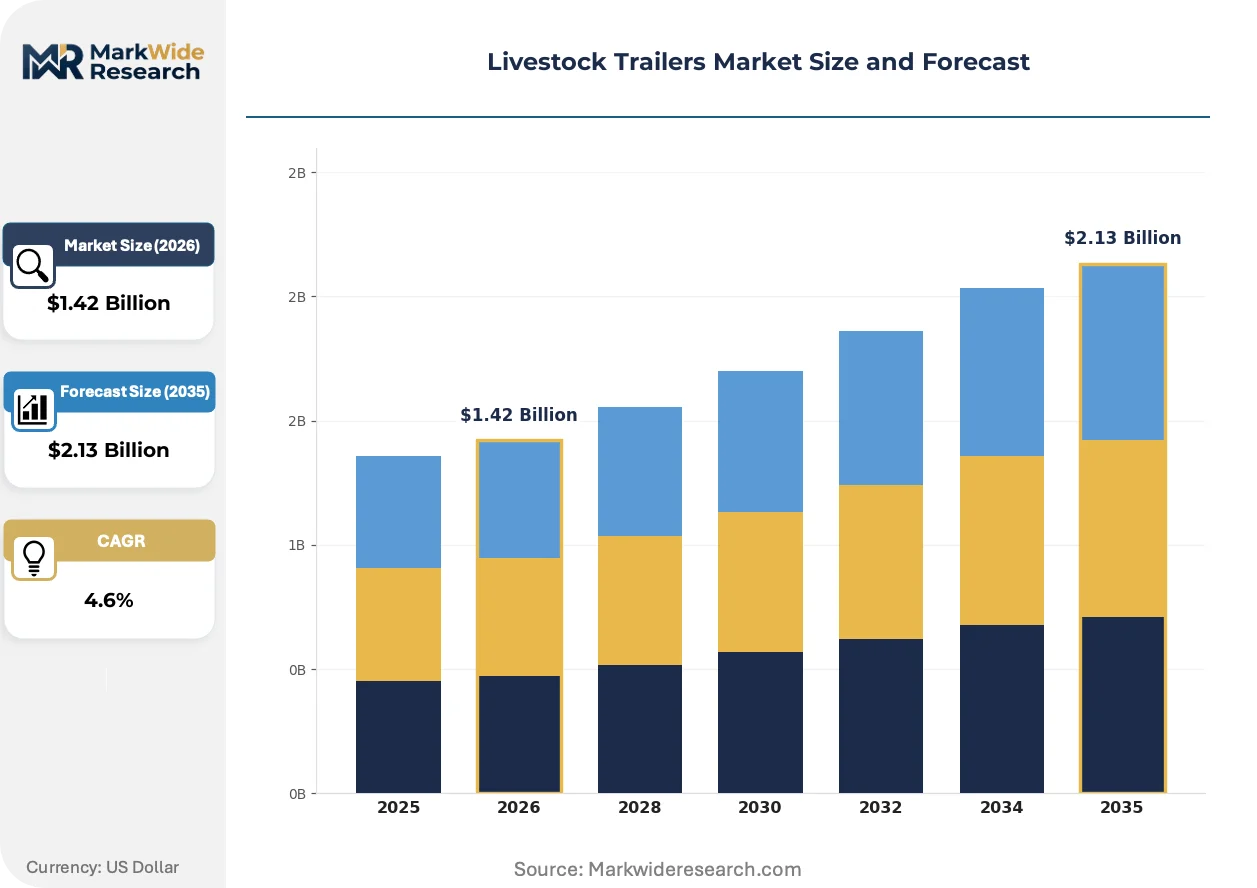
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gooseneck Trailers, Bumper Pull Trailers, Stock Trailers, Specialized Trailers End User: Farmers, Ranchers, Livestock Haulers, Animal Breeders Material: Aluminum, Steel, Composite, Fiberglass Size: Small Trailers, Medium Trailers, Large Trailers, Extra Large Trailers |
| Companies Covered | Neckover Trailers, Frontier Trailers, Cimarron Trailers, Corn Pro, Eagle X Trailers, Sundowner Trailers, WW Trailers, Logan Coach, Big Bend Trailers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Livestock Trailers Market Trends and Innovations
Digital monitoring systems and predictive maintenance protocols are reshaping how fleet operators manage trailer lifecycle costs and regulatory compliance documentation.
Telematics integration is automating real-time cargo monitoring for temperature, humidity, and animal stress indicators during transit. Large commercial haulers in the Texas-Oklahoma corridor are adopting these systems fastest, driven by processor liability requirements and insurance premium incentives. The technology is automating documentation chains that previously required manual driver logs and facility check-ins.
Pending animal welfare transport duration limits from USDA and CFIA are forcing engineering investment into onboard water delivery and climate control systems. Trailer manufacturers must redesign compartment configurations to accommodate plumbing and ventilation hardware without compromising payload ratings. Gooseneck configurations with higher gross vehicle weight ratings are absorbing these retrofits most effectively.
Service unbundling is separating trailer acquisition from lifecycle maintenance commitments. Fleet operators now negotiate brake system subscriptions, flooring inspection contracts, and ventilation calibration schedules as distinct procurement decisions rather than bundled warranty packages. This behavioral shift concentrates among commercial haulers with centralized procurement functions.
Livestock Trailers Market Segmentation
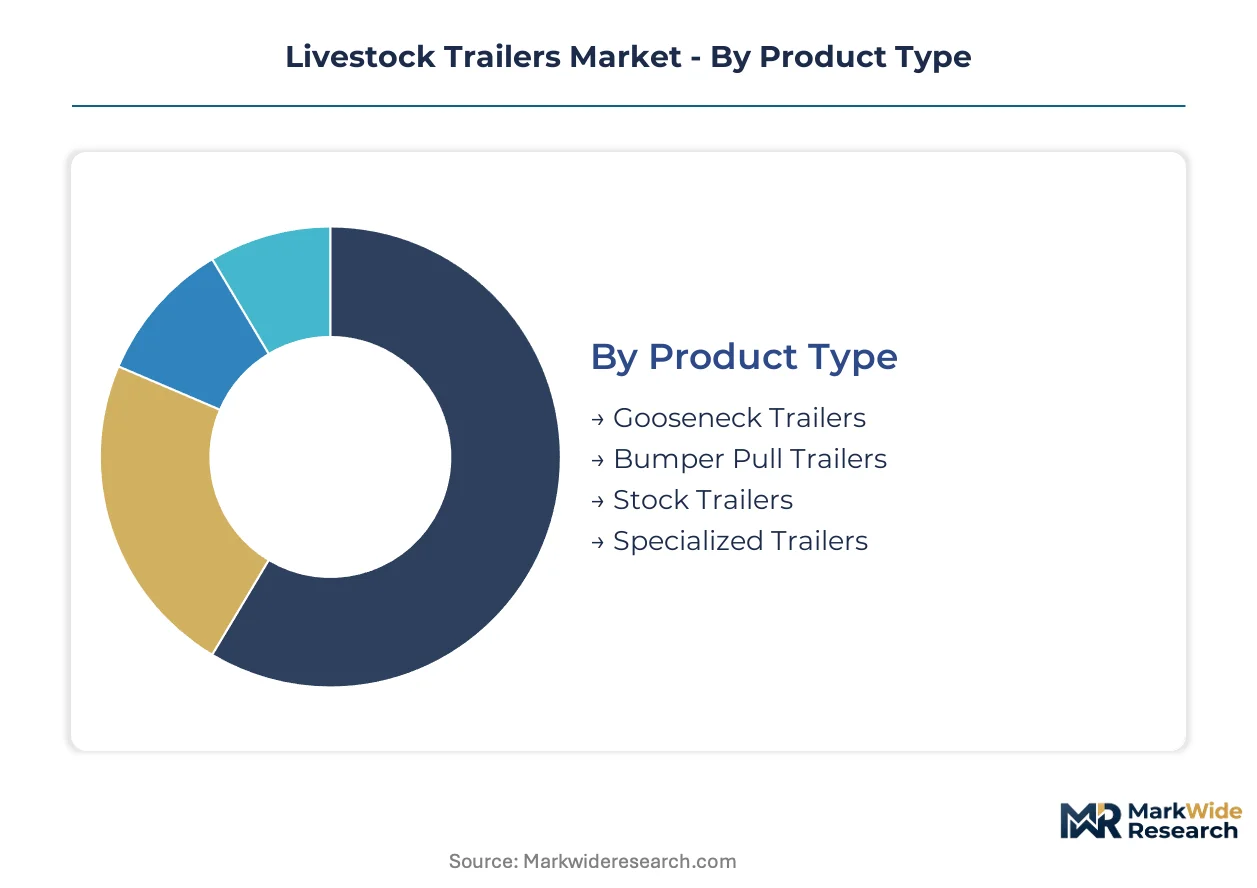
Livestock trailer procurement decisions hinge on distinct operational profiles across hauling distances, animal species, and regulatory exposure. Each segmentation dimension carries specific compliance burdens and total cost of ownership implications that reshape fleet investment priorities.
Product Type:
DOT and Transport Canada weight certification requirements vary sharply by hitch configuration and structural rating, with gooseneck designs facing enhanced brake system validation under FMVSS 121.
- Gooseneck Trailers:These configurations employ fifth-wheel couplings mounted above the tow vehicle rear axle, distributing weight across chassis rails for superior stability at interstate speeds. Demand concentrates among commercial livestock haulers operating the Texas-Oklahoma corridor, where processor just-in-time delivery mandates require maximum payload capacity and reduced loading turnaround times.
- Bumper Pull Trailers:Conventional ball-hitch designs attach to receiver mounts at the vehicle rear, limiting tongue weight but enabling operation with standard pickup trucks. Smaller herd farmers across Kansas and Nebraska prefer these units where lighter towing requirements align with seasonal auction transport rather than long-haul routes.
- Stock Trailers:Open-sided aluminum or steel constructions serve multi-species transport with slatted ventilation and non-slip flooring rated for cattle, swine, and sheep.
- Specialized Trailers:Custom-engineered units accommodate equine athletes, breeding stock, or veterinary transport with climate control and padded partitioning systems.
Leading the category by volume: Gooseneck Trailers. Growing fastest: Specialized Trailers.
End User:
Procurement sophistication varies dramatically across customer types, with commercial haulers negotiating fleet maintenance subscriptions while farmers prioritize acquisition cost over lifecycle optimization.
- Farmers:Small-to-midscale producers operating 50-200 head herds drive bumper pull and small stock trailer demand, with purchasing decisions centered on upfront capital constraints and seasonal use patterns rather than depreciation schedules.
- Ranchers:Large-scale cow-calf operations across Montana and Wyoming require gooseneck configurations rated for 30,000+ pound gross vehicle weights, often specifying aluminum construction for corrosion resistance in harsh winter conditions.
- Livestock Haulers:Commercial fleet operators serving meatpacking processors dominate aluminum gooseneck procurement, with DOT hours-of-service compliance driving investment in telematics-integrated trailers.
- Animal Breeders:Purebred cattle and equine operations demand specialized climate-controlled trailers with veterinary-grade flooring and partitioned compartments for high-value genetic stock.
Volume concentration sits with Livestock Haulers. Steepest expansion trajectory: Animal Breeders.
Material:
Material selection directly determines regulatory compliance pathways, with aluminum fabricators pursuing DOT structural certifications while steel builders navigate corrosion warranty limitations.
- Aluminum:Extruded and welded alloy construction delivers weight savings of 15-20 percent versus steel equivalents, enabling higher payload ratings under federal bridge formula limits. Premium-tier manufacturers in Oklahoma and Texas have vertically integrated aluminum fabrication to control input costs and lead times.
- Steel:Carbon and galvanized frame construction persists in value-oriented stock trailer segments, with powder-coat finishes addressing corrosion vulnerability in humid southeastern climates.
- Composite:Fiberglass-reinforced panel systems reduce thermal transfer and enable smoother interior surfaces for animal comfort.
- Fiberglass:Molded shell construction appears in specialized equine and show cattle trailers where aerodynamic profiles and cosmetic finish quality command price premiums.
Aluminum dominates revenue share. Composite materials are climbing the fastest.
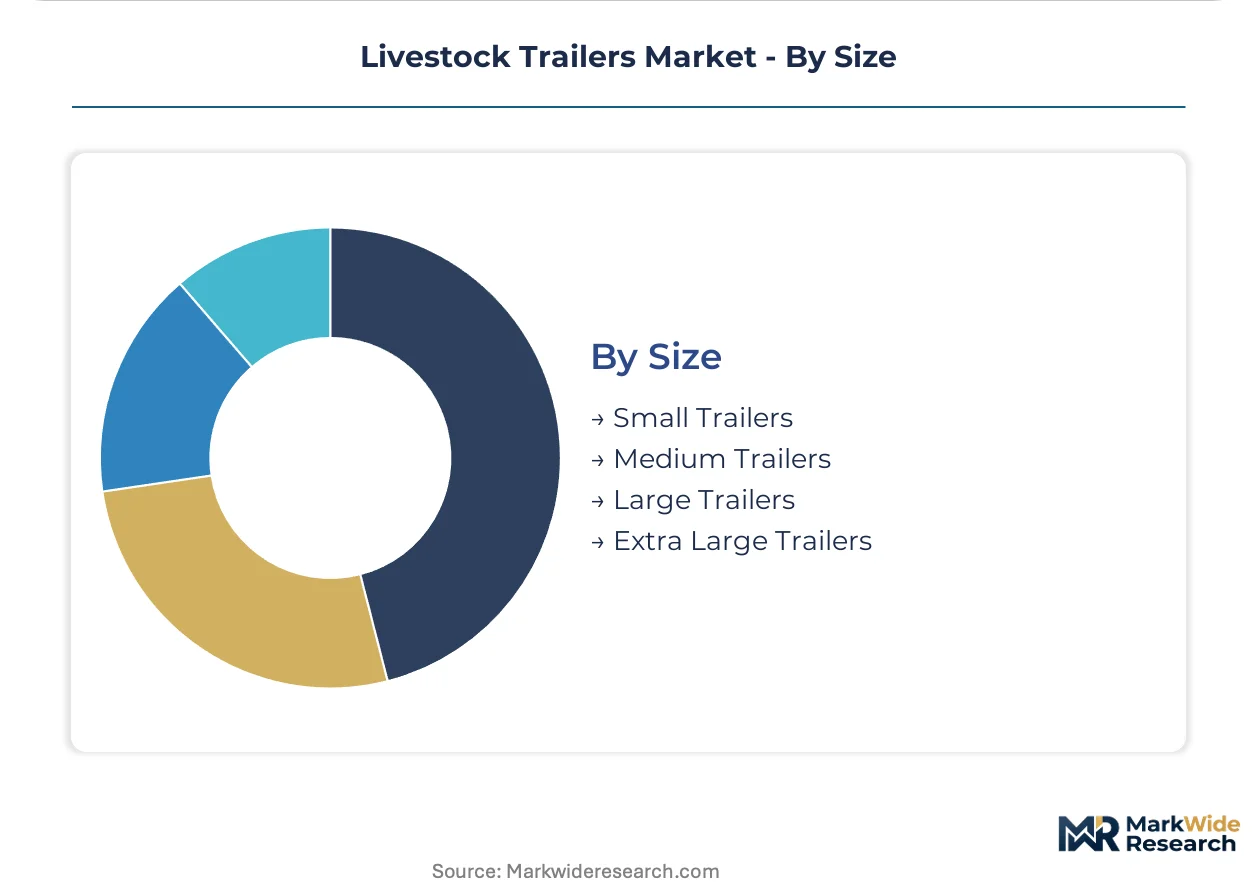
Size:
Dimensional classification determines NHTSA lighting and conspicuity requirements, with extra-large trailers facing enhanced rear-impact protection mandates.
- Small Trailers:Single-axle units rated below 10,000 pounds gross vehicle weight serve hobby farmers and 4-H exhibitors, with bumper pull hitches avoiding commercial driver licensing requirements.
- Medium Trailers:Tandem-axle configurations at 10,001-16,000 pounds bridge farmer and light commercial use, representing the most fragmented competitive landscape.
- Large Trailers:Triple-axle gooseneck designs at 16,001-25,000 pounds dominate interstate livestock hauler fleets, with air-ride suspension and onboard water systems becoming standard specifications.
- Extra Large Trailers:Heavy-haul configurations exceeding 25,000 pounds require commercial driver licensing and federal operating authority, with demand concentrated among dedicated livestock trucking companies serving major packing plants.
Large Trailers lead unit volume. Extra Large Trailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates livestock trailer production capacity, while consumption clusters in feedlot-dense corridors where processor proximity dictates fleet investment cycles. Canada maintains cross-border fleet commonality through regulatory alignment, though fabrication scales remain smaller. Mexico serves as an emerging assembly location for steel-frame exports into southwestern US markets.
United States
Commercial haulers in the Texas-Oklahoma corridor drive replacement demand for aluminum gooseneck configurations rated at 30,000+ pound gross vehicle weights. DOT Federal Motor Carrier Safety Administration hours-of-service rules compress transport windows, forcing investment in telematics-integrated trailers. Oklahoma City and Amarillo anchor the densest concentration of fleet operators serving major beef packing plants.
Canada
Ranchers across Alberta and Saskatchewan require corrosion-resistant aluminum construction for winter durability in harsh prairie conditions. Transport Canada NSC Standard 11 mirrors US brake and structural requirements, enabling seamless cross-border fleet operations. Calgary hosts specialized fabricators serving the Canadian cattle feeding industry concentrated in southern Alberta feedlots.
Mexico
Expanding cattle operations in Chihuahua and Sonora generate demand for value-oriented steel stock trailers suited to regional road infrastructure. The country's national transport regulator enforces weight compliance standards that increasingly align with US DOT specifications. Monterrey-based assembly operations supply cost-competitive units for southwestern US farmer segments.
Australia
Extensive cattle station operations in Queensland and the Northern Territory sustain demand for heavy-haul road trains capable of traversing remote outback routes. The Australian Transport Safety Bureau mandates enhanced rear-impact protection and conspicuity standards for multi-trailer combinations. Townsville serves as the primary distribution hub for livestock transport equipment serving northern beef supply chains.
Brazil
Rapidly consolidating feedlot operations in Mato Grosso and Goiás drive investment in larger-capacity trailers for long-haul routes to southern processing centers. ANVISA and the national agricultural regulator monitor animal welfare transport standards that increasingly influence trailer design specifications. Rondonópolis anchors the fastest-growing commercial hauler fleet serving the expanding integrated beef production system.
Livestock Trailers Market Competitive Landscape
Top-tier vendors anchor premium aluminum fabrication, while mid-market specialists compete on regional dealer density and configuration flexibility. The vendor base stratifies across three tiers: integrated manufacturers controlling in-house aluminum extrusion, regional assemblers sourcing commodity frames, and specialized custom builders serving equine and show cattle segments. Two dominant competitive moves define current positioning: captive supply of aluminum alloys to buffer input cost volatility, and modular interior platform development enabling rapid species conversion. Geographic expansion into feedlot-dense corridors and maintenance subscription bundling represent secondary competitive vectors.
Among Oklahoma and Texas-based fabricators, Cimarron Trailers, Sundowner Trailers, and Logan Coach occupy distinct positioning archetypes. Cimarron Trailers exemplifies the vertically integrated manufacturer archetype through captive aluminum fabrication capabilities. Sundowner Trailers represents the dealer-network density model with extensive southern plains distribution coverage. Logan Coach anchors the modular configuration specialist tier, serving diversified agricultural operators requiring rapid species adaptation. These three companies collectively illustrate how regional concentration, material control, and product flexibility segment competitive positioning in North American livestock trailer supply.
| Leading Market Players |
|---|
| Neckover Trailers |
| Frontier Trailers |
| Cimarron Trailers |
| Corn Pro |
| Eagle X Trailers |
| Sundowner Trailers |
| WW Trailers |
| Logan Coach |
| Big Bend Trailers |
| Others |
Pricing and Supply Chain Analysis
Aluminum extrusion automation across Oklahoma and Texas fabrication centers simultaneously compresses per-unit production costs and concentrates supply leverage among vertically integrated manufacturers. This technological shift enables premium-tier producers to buffer primary aluminum price volatility through captive alloy sourcing while value-oriented assemblers face margin compression from commodity steel frame procurement.
Pricing Analysis
Margin tightening in the value-oriented steel segment reflects persistent aluminum price premiums and DOT weight-compliance penalties on heavier configurations. Three-tier pricing structure across premium aluminum, mid-grade hybrid, and economy steel levels stratifies by certification grade and after-sales service bundling. Cost-down pressure on steel stock trailers accelerates because commercial haulers prioritize payload optimization over acquisition cost. Small herd farmers exhibit highest price sensitivity, while livestock haulers serving meatpacking processors demonstrate lowest sensitivity due to lifecycle total cost of ownership calculations.
Supply Chain Analysis
Primary aluminum supply rests on domestic smelters in Kentucky and Tennessee plus Canadian producers under USMCA tariff preferences. Extruded alloy components draw from Oklahoma-based captive fabrication and third-party Midwest processors. Steel frame assemblies hinge on Mexican roll-form operations serving southwestern assembler networks. Single-source vulnerability concentrates in specialized aluminum welding consumables from limited domestic suppliers. Distribution runs through independent dealer networks across the southern plains, with direct fleet sales gaining share among centralized commercial hauler procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The livestock trailer market functions as a vertical-integration race where control over aluminum alloy sourcing and modular platform development determines margin durability. Players are pursuing backward integration into extrusion capabilities as the decisive upstream lever.
For Market Incumbents: Anticipate regulatory compression from pending USDA animal welfare transport duration limits by pre-positioning onboard water system engineering and climate control retrofit service capabilities. Consolidate dealer network density across the Texas-Oklahoma corridor to lock in processor-aligned fleet replacement cycles. Defensive positioning requires aluminum fabrication capacity expansion before input cost volatility reshapes competitive cost structures. For New Entrants and Emerging Players: Enter via specialized equine and show cattle trailer segments where cosmetic finish quality and climate control specifications command price premiums underserved by volume-focused incumbents. Target animal breeder operations in Alberta and Montana requiring veterinary-grade flooring and partitioned compartments for high-value genetic stock. Go-to-market execution should emphasize direct digital configuration tools bypassing traditional dealer markup structures. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified transportation equipment manufacturers seeking livestock trailer platform capabilities. Long-term viability centers on aluminum-intensive production scale and maintenance subscription revenue attach rates. Acquisition target archetype: regional fabricators with captive extrusion capacity and established processor fleet relationships. Watch for DOT hours-of-service rule amendments as the signal indicating accelerated fleet replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aluminum Extrusion Investment | Oklahoma-based vertical integration buffers primary aluminum price volatility for premium-tier producers. |
| Modular Interior Platform Development | Partition systems adaptable across cattle, swine, and equine transport open fleet flexibility for diversified operators. |
| Maintenance Subscription Bundling | Brake monitoring and ventilation calibration packages recalibrate total cost of ownership budgeting for commercial haulers. |
| Telematics Integration Partnership | Real-time cargo monitoring automates compliance documentation chains for processor liability requirements. |
| Dealer Network Density Expansion | Southern plains coverage concentration locks in replacement demand from feedlot-dense corridor operators. |
Research Methodology
Document review covered DOT Federal Motor Carrier Safety Administration regulatory filings, Transport Canada NSC Standard 11 technical bulletins, and aluminum industry trade association capacity reports, complemented by interviews with commercial livestock hauler fleet managers, trailer manufacturer procurement directors, and independent dealer network principals. Secondary validation drew from NHTSA lighting standard updates, USDA animal welfare transport proposals, and SEC filings from publicly traded transportation equipment manufacturers. Bottom-up unit demand modeling triangulated against top-down market sizing from feedlot capacity and interstate haul volume data.
Segmented volume and value outputs across the projection horizon reflect disaggregation by hitch configuration, material construction, end-user archetype, and dimensional classification. The analytical framework incorporated gross vehicle weight rating distributions, replacement cycle timing, and aluminum-steel price spread elasticity. CAGRs were derived from regression analysis of historical fleet investment patterns against processor capacity expansion schedules and regulatory compliance cost trajectories. Industry-specific forecast inputs included DOT hours-of-service enforcement intensity and pending CFIA animal welfare rule implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under primary aluminum price spike scenarios or accelerated steel frame displacement regulations. Forecasts reflect assumptions regarding regulatory alignment continuity between US and Canadian transport standards, feedlot density concentration stability in the southern plains, and maintenance subscription adoption rates among commercial hauler procurement functions. A small set of named triggers warrants ongoing watch: DOT animal welfare transport duration final rules, aluminum alloy tariff schedule modifications, and processor just-in-time delivery mandate tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Animal Feeding Equipment Market
Livestock Equipment
Sheep Creep Feeder Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Hydraulic Squeeze Chute Market
Livestock Equipment
Nigeria Horse Riding Equipment Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Livestock Farm Equipment Market
Livestock Equipment
Starter Feed Market
Livestock Equipment
Chicken Coop Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Horse Stable Supplies Market
Livestock Equipment
Sheep Supplies Market