
 Cattle Supplies Market | 2026-2036
Cattle Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Supplies Market Outlook
Plant-based protein meals are restructuring traditional soybean-meal economics in cattle feed formulations. Cargill Inc. leverages its North American grain-handling infrastructure to secure cost-advantaged feedstock positions. De Heus Animal Nutrition anchors its European operations with specialized ruminant nutrition expertise. Alltech, Inc. differentiates through yeast-based additive technologies that improve feed conversion efficiency.
Cattle supplies encompass formulated feeds, nutritional supplements, grooming equipment, and veterinary health products designed to optimize bovine growth rates, reproductive performance, and overall herd productivity. Feed products typically incorporate crude protein levels between 12% and 16% alongside mineral premixes tailored to lifestage requirements. The feed segment dominates volume flows given its recurring purchase pattern and direct linkage to daily animal maintenance. Health products capture concentrated margin pools as regulatory compliance drives premiumization of vaccine and pharmaceutical formulations. Distribution through wholesale channels sustains the largest revenue share by serving commercial livestock operations with bulk procurement needs.
The USDA enforces feed-labeling standards under the Federal Food, Drug, and Cosmetic Act, while the EPA regulates manure-management practices affecting large-scale cattle operations. Brazil's MAPA oversees veterinary product registration, creating compliance thresholds for imported health supplies. Stakeholders must monitor evolving antibiotic-resistance policies across major producing jurisdictions to anticipate product-formulation requirements and market-access conditions.
Market Dynamics
Precision-formulated feed additives are restructuring cattle supply economics as ranchers modernize herd management systems. The EU's Farm to Fork Strategy is tightening antibiotic-use standards, forcing reformulation of veterinary health products across major producing regions.
Growth Catalysts
- Regulatory frameworks:The European Union's Farm to Fork Strategy mandates reduced antibiotic dependency in livestock production, creating pull for alternative feed additives and probiotic formulations.
- Technology adoption:Yeast-based additive technologies improve feed conversion efficiency in beef cattle operations, lowering unit production costs for commercial ranches.
- Geographic modernization:Brazil's Mato Grosso cattle belt is consolidating demand as ranchers invest in specialized ruminant nutrition expertise and precision feeding systems.
Market Restraints
- Input cost volatility:Soybean-meal prices fluctuate with weather patterns and trade flows, compressing margins for formulated feed producers dependent on plant-based protein inputs.
- Supply concentration risk:North American grain-handling infrastructure dominates cost-advantaged feedstock positions, limiting competitive entry for regional formulators elsewhere.
- Technical limitation:Mineral premix stability degrades under tropical storage conditions, restricting shelf-life and distribution reach in humid climates.
Strategic Opportunities
- Underpenetrated applications:Reproductive performance supplements for dairy transition cows represent an underserved segment with recurring purchase patterns.
- Regulatory tailwinds:Brazil's MAPA veterinary product registration reforms are streamlining market access for imported health supplies with documented efficacy data.
- Channel innovation:Direct-to-ranch digital procurement platforms bypass traditional wholesale markups, capturing margin from bulk commercial livestock operations.
Industry Challenges
- Skill scarcity:Formulation chemists with ruminant-specific expertise are concentrated among established nutrition houses, limiting new entrant product development velocity.
- Certification timelines:EPA manure-management compliance documentation for large-scale cattle operations extends facility permitting cycles.
- Integration complexity:Legacy herd management software lacks API connectivity with precision-feeding hardware, forcing manual data reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Supplies Market |
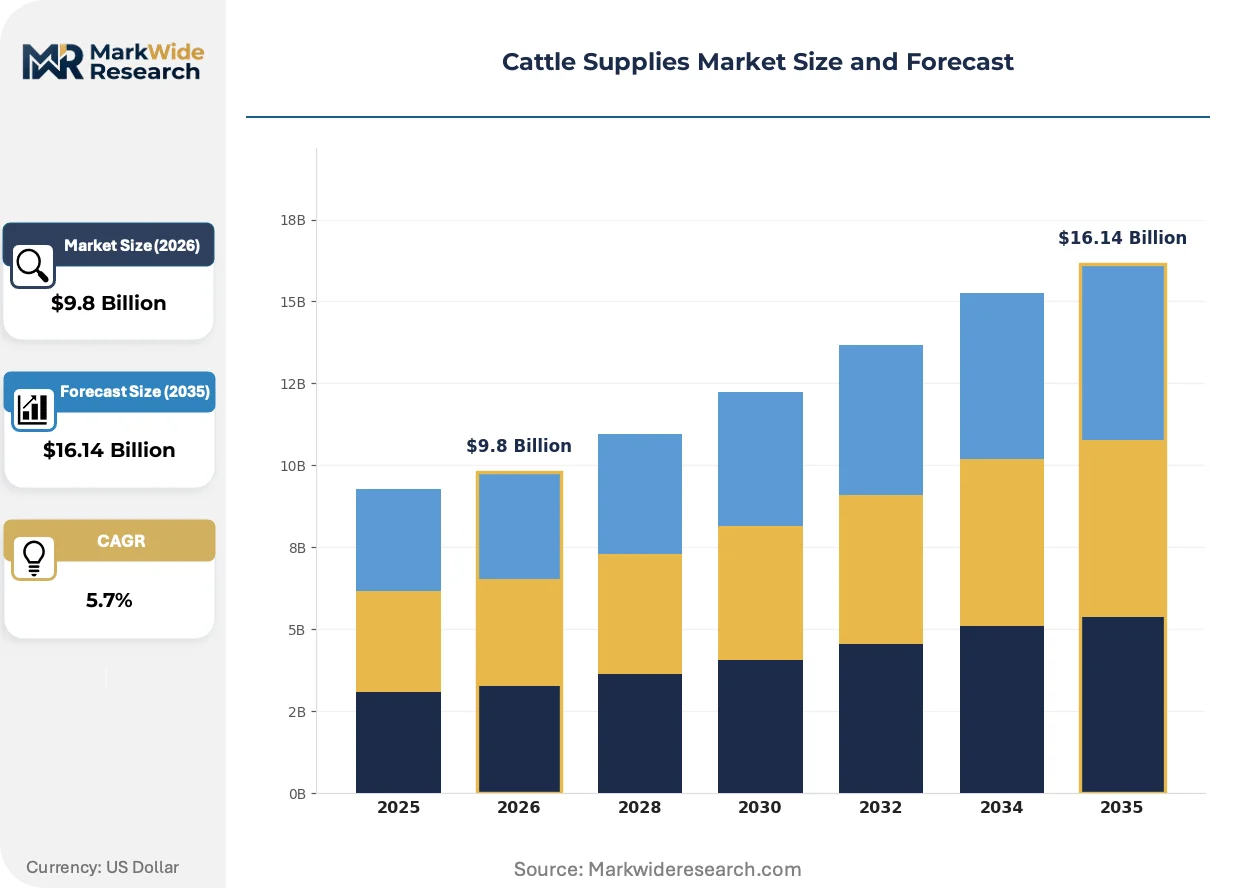
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed, Supplements, Grooming Supplies, Health Products End User: Dairy Farms, Beef Cattle Ranches, Hobby Farmers, Commercial Livestock Distribution Channel: Retail Stores, Online Sales, Direct Sales, Wholesale Application: Nourishment, Health Care, Breeding, Maintenance |
| Companies Covered | Cargill Inc., Archer Daniels Midland Company, ForFarmers N.V., De Heus Animal Nutrition, Land O'Lakes, Inc., Nutreco N.V., Alltech, Inc., Charoen Pokphand Group, Godrej Agrovet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Supplies Market Strategic Shifts
Feed additive technologies and regulatory compliance requirements are converging to reshape product development priorities. Ranchers now demand solutions that simultaneously optimize growth rates and satisfy tightening residue standards.
Yeast-derived nucleotides and cell-wall fractions are expanding into starter calf diets and receiving protocols for feedlot cattle. Commercial backgrounding operations in the US Plains states are adopting these additives at accelerating rates. The technology is expanding into regions previously dependent on antibiotic growth promoters now restricted by veterinary oversight rules.
The EPA's revised National Pollutant Discharge Elimination System permits impose stricter nutrient management planning on concentrated animal feeding operations. Large-scale feedlots must now document phosphorus and nitrogen flows in comprehensive manure management plans. Cattle operations exceeding one thousand head in the Texas Panhandle and Nebraska Sandhills are investing in lagoon covers and solids separation equipment to maintain permit compliance.
Consolidated procurement by integrated protein companies is displacing independent feed dealer networks. JBS SA and Marfrig Global Foods now specify exact additive inclusion rates and supplier approval lists for contracted ranchers. This concentration is most visible in Brazil's Center-West region where direct supply agreements cover seventy percent of finished cattle volumes.
Cattle Supplies Market Segmentation
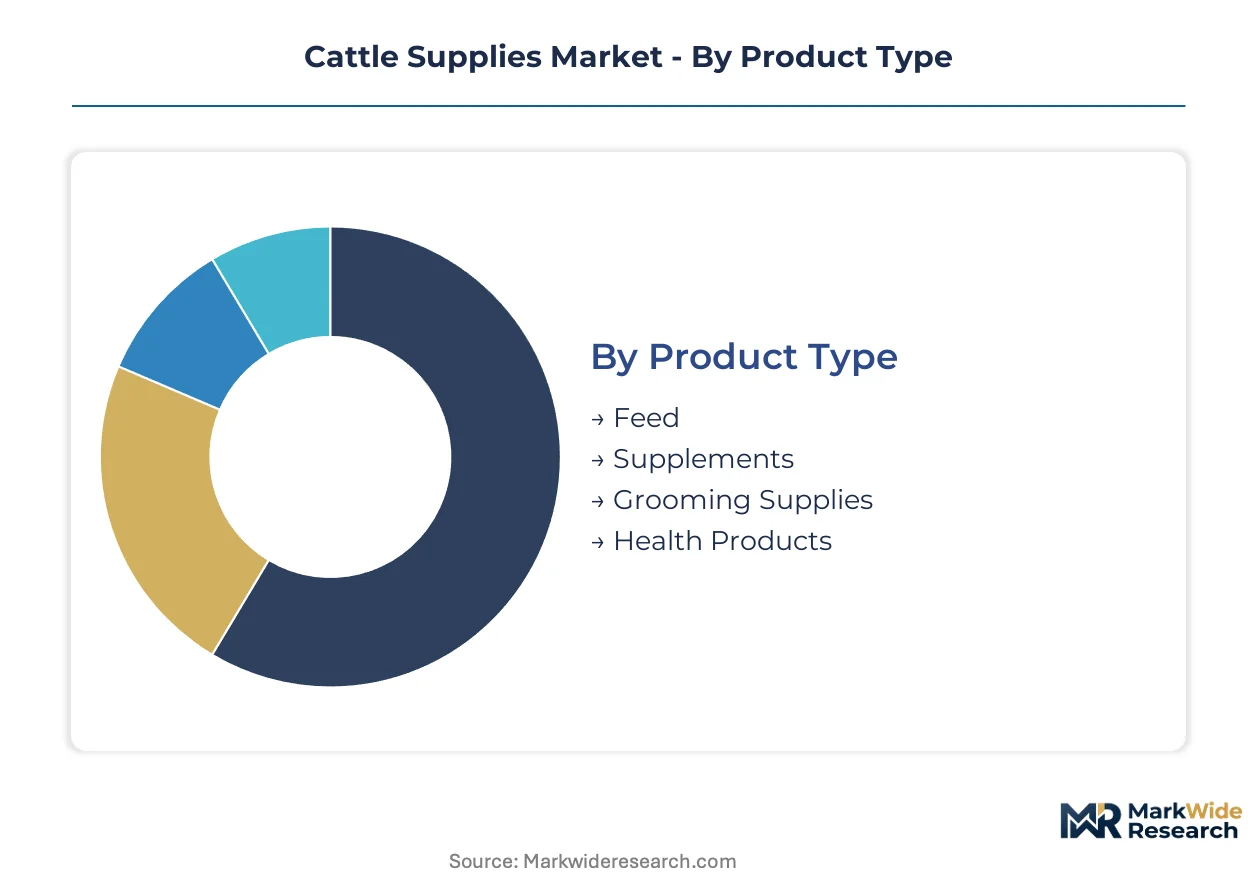
Cattle supplies serve distinct operational profiles across dairy, beef, and hobbyist segments with divergent purchase frequencies and technical specifications. Understanding how product categories align with end-user workflows and distribution economics reveals where margin pools concentrate and where volume flows stabilize.
Product Type:
Cost tier separates commodity bulk purchases from premium-formulated solutions with recurring technical support.
- Feed:Formulated rations incorporating 12-16% crude protein with mineral premixes calibrated to lifestage requirements. Demand concentrates in Brazil's Mato Grosso cattle belt where ranchers modernize precision feeding systems to optimize feed conversion ratios.
- Supplements:Targeted nutritional additives including yeast-based formulations that improve rumen efficiency and reduce antibiotic dependency. Beef cattle ranches in the US Plains states are expanding adoption as EPA manure-management regulations tighten nutrient discharge standards.
- Grooming Supplies:Equipment for coat maintenance, hoof care, and hygiene protocols in show cattle and registered breeding stock operations.
- Health Products:Vaccines, pharmaceuticals, and veterinary therapeutics subject to Brazil's MAPA registration requirements and EU Farm to Fork antibiotic restrictions.
Volume sits with Feed; growth tilts toward Supplements.
End User:
Application intensity varies from daily maintenance in commercial operations to episodic purchases among small-scale producers.
- Dairy Farms:High-frequency buyers of precision-formulated transition cow diets and reproductive performance supplements. Operations in the Upper Midwest US and Netherlands invest in specialized ruminant nutrition expertise to sustain milk yield curves.
- Beef Cattle Ranches:Backgrounding and feedlot operations driving bulk procurement of starter calf diets and receiving protocols. Brazilian Center-West ranchers under JBS SA and Marfrig Global Foods supply agreements specify exact additive inclusion rates.
- Hobby Farmers:Small-herd operators purchasing through retail channels with lower technical specification requirements.
- Commercial Livestock:Integrated protein companies consolidating procurement through direct supply agreements and bypassing independent dealer networks.
Procurement scale clusters with Commercial Livestock; margin capture favors Dairy Farms.
Distribution Channel:
Channel selection reflects order size, technical service needs, and geographic access to supply infrastructure.
- Retail Stores:Accessible points for hobby farmers and small ranches purchasing grooming supplies and basic health products. Rural feed stores in Texas Panhandle and Nebraska Sandhills maintain inventory for immediate livestock maintenance needs.
- Online Sales:Direct-to-ranch digital platforms gaining traction among commercial operations seeking transparent pricing and documented product specifications.
- Direct Sales:Technical representatives from nutrition houses providing formulation consulting to large-scale feedlots exceeding one thousand head.
- Wholesale:Bulk distribution serving commercial livestock operations with recurring volume requirements and centralized delivery logistics.
Revenue concentration remains with Wholesale; channel expansion is accelerating most quickly through Online Sales.
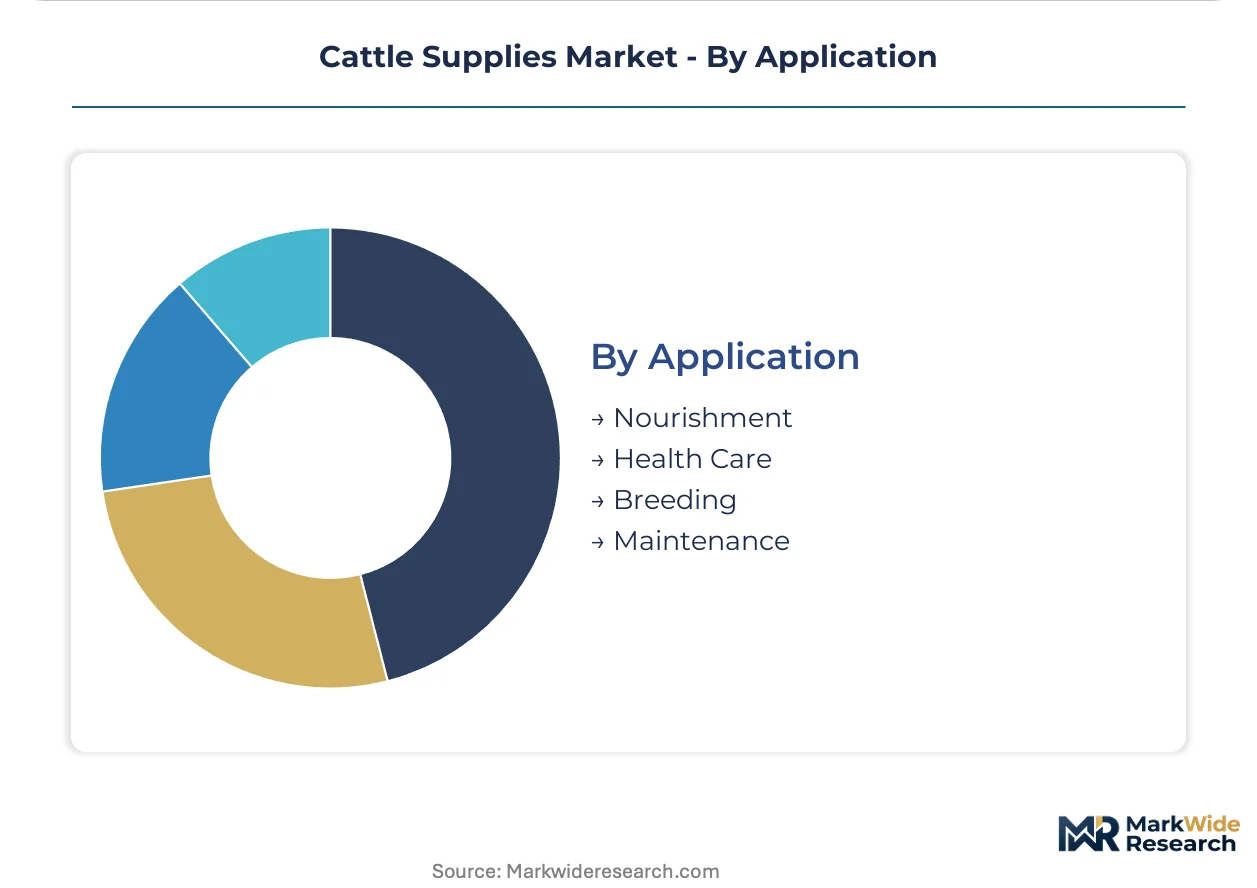
Application:
Functional priority determines formulation complexity and regulatory scrutiny intensity.
- Nourishment:Daily caloric and protein delivery through complete rations and forage supplements. Precision-formulated feed additives are restructuring economics as ranchers modernize herd management systems.
- Health Care:Disease prevention and therapeutic intervention subject to tightening veterinary oversight rules. The EU's Farm to Fork Strategy mandates reduced antibiotic dependency, forcing reformulation of pharmaceutical formulations.
- Breeding:Reproductive performance supplements for dairy transition cows and embryo transfer programs in registered seedstock operations.
- Maintenance:Routine care products sustaining animal welfare standards and operational compliance with facility permitting requirements.
Spend depth concentrates in Nourishment; regulatory pressure is intensifying fastest around Health Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beef cattle ranches in Brazil's Mato Grosso cattle belt are driving concentrated demand as ranchers modernize herd management systems. The United States maintains dominant feed production capacity through its North American grain-handling infrastructure. European dairy operations are restructuring procurement patterns under tightening antibiotic-use standards.
United States
Commercial feedlots in the Texas Panhandle and Nebraska Sandhills are expanding precision-feeding infrastructure to optimize feed conversion ratios. The EPA enforces revised National Pollutant Discharge Elimination System permits requiring comprehensive manure management documentation. Large-scale operations exceeding one thousand head are investing in lagoon covers and solids separation equipment to maintain regulatory compliance.
Brazil
Ranchers in the Center-West region under JBS SA and Marfrig Global Foods supply agreements are specifying exact additive inclusion rates for contracted cattle volumes. MAPA oversees veterinary product registration, creating compliance thresholds for imported health supplies. The Mato Grosso cattle belt is consolidating demand as integrated protein companies displace independent feed dealer networks through direct procurement arrangements.
Germany
Dairy farms in Lower Saxony and Bavaria are investing in specialized ruminant nutrition expertise to sustain milk yield curves under EFSA scrutiny. The EU's Farm to Fork Strategy mandates reduced antibiotic dependency, forcing reformulation of pharmaceutical formulations. Precision-formulated feed additives are gaining traction as operations seek alternatives to restricted growth promoters.
Netherlands
High-intensity dairy operations in Gelderland and Friesland are adopting yeast-based additive technologies to improve rumen efficiency. REACH compliance requirements govern chemical inputs in feed formulations, elevating documentation burdens for mineral premix suppliers. Dutch nutrition houses are leveraging technical service capabilities to defend margin positions against commodity feed imports.
India
Dairy cooperatives in Gujarat and Maharashtra are scaling commercial feed procurement as organized sector participation expands. FSSAI standards govern feed safety and labeling requirements for manufactured cattle rations. Punjab's grain surplus regions are emerging as formulation hubs serving northern dairy belts with cost-advantaged feedstock access.
Cattle Supplies Market Competitive Environment
Capacity expansion dominates the current landscape as established nutrition houses scale manufacturing footprints to capture Brazilian and Indian demand growth. The vendor base stratifies across three tiers: multinational grain traders with captive supply chains, regional specialists with ruminant formulation expertise, and commodity blenders serving price-sensitive segments. Strategic archetypes include infrastructure-heavy integrators controlling upstream grain positions, technology-led innovators commercializing yeast-derived additives, and service-intensive operators embedding nutritionists directly with large ranch clients. M&A activity and geographic licensing agreements represent the dominant competitive vectors as mid-cap players seek scale to match procurement leverage.
Among North American grain traders, Cargill Inc. and Archer Daniels Midland Company exemplify infrastructure-heavy archetypes with cost-advantaged feedstock positions. De Heus Animal Nutrition occupies a specialist tier anchored in European ruminant nutrition expertise. Alltech, Inc. represents the technology-led vector through its yeast-based additive portfolio. These three company structures illustrate how competitive positioning fragments across supply chain control, technical service depth, and biotechnology differentiation rather than consolidating around a single dominant model.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland Company |
| ForFarmers N.V. |
| De Heus Animal Nutrition |
| Land O'Lakes, Inc. |
| Nutreco N.V. |
| Alltech, Inc. |
| Charoen Pokphand Group |
| Godrej Agrovet |
| Others |
Value Chain & Pricing Dynamics
Formulation chemists with ruminant-specific expertise cluster in the Netherlands and Germany, creating labor-cost differentials that widen pricing spreads between premium-formulated additives and commodity bulk feeds. This concentration of technical talent in European nutrition houses elevates service-inclusive pricing tiers while compressing margins for blenders lacking comparable in-house capability.
Pricing Analysis
Volume concentrates in commodity feed rations while margins pool in specialized supplements. Three-tier pricing structure across premium, standard, and economy levels separates yeast-based additives with documented efficacy data from generic mineral premixes and unbranded commodity blends. Pricing pressure stems from soybean-meal cost volatility transmitted through formulated feed supply chains. Commercial livestock operations exhibit lowest price sensitivity due to procurement scale and direct supply agreements, while hobby farmers purchasing through retail channels face highest relative cost burdens.
Supply Chain Analysis
Brazil's MAPA veterinary product registration requirements and India's FSSAI feed safety standards are reshaping sourcing patterns for multinational suppliers seeking market access. Manufacturing concentration centers on the United States, Brazil, and the Netherlands, with North American grain-handling infrastructure anchoring cost-advantaged feedstock positions. Raw material flows draw from Midwest US corn belts, Mato Grosso soybean regions, and Punjab grain surplus zones. Single-source vulnerability runs through concentrated yeast-derived additive production. Distribution runs through wholesale channels serving bulk commercial operations, with direct-to-ranch digital platforms emerging as secondary pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around formulation chemists with ruminant-specific expertise prop pricing power for established nutrition houses, creating durable margin structures that resist commodity cyclicality.
For Market Incumbents: Deploy captive supply of yeast-based additive technologies to lock in feed conversion efficiency advantages as EPA manure-management regulations tighten. Consolidate technical service teams in Brazil's Center-West region to defend against integrated protein companies bypassing dealer networks. Counter emerging digital procurement platforms by embedding nutritionists directly with JBS SA and Marfrig Global Foods contracted ranchers. For New Entrants and Emerging Players: Yeast-derived nucleotides for dairy transition cows offer a technology-first wedge into an underserved segment with recurring purchase patterns and limited incumbent specialization. Target reproductive performance supplements in India's Gujarat and Maharashtra dairy cooperatives where organized sector expansion outpaces local formulation expertise. Pursue regulatory arbitrage through Brazil's MAPA registration streamlining for imported health supplies with documented efficacy data. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing ruminant formulation expertise given EU Farm to Fork antibiotic restrictions forcing portfolio reformulation. Long-term viability favors operators with backward integration into grain-handling infrastructure and captive additive technology pipelines. Watch for inflection signals in direct-to-ranch digital procurement platform adoption rates among commercial livestock operations exceeding one thousand head.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Handling | Cargill Inc. leverages North American infrastructure to secure cost-advantaged feedstock positions against regional blenders. |
| Yeast-Based Additive Technology Licensing | Alltech, Inc. commercializes rumen efficiency improvements that reduce antibiotic dependency under tightening EU veterinary oversight. |
| Direct-to-Ranch Digital Platform Launch | Online procurement bypasses wholesale markups while capturing margin from bulk commercial livestock operations in Texas Panhandle. |
| MAPA Registration Compliance Investment | Brazil's streamlined veterinary product access creates first-mover advantage for imported health supplies with documented efficacy data. |
| Technical Service Team Embedding | De Heus Animal Nutrition defends European margin positions through specialized ruminant expertise under EFSA scrutiny. |
Study Parameters
Multi-period observation of feed additive adoption rates, antibiotic-use compliance patterns, and integrated protein company procurement consolidation anchored the trend analysis, supplemented by interviews with ruminant nutritionists, feed mill operations managers, veterinary pharmaceutical registrars, and large-scale ranch procurement directors. Secondary validation drew from USDA feed-labeling enforcement records, EPA National Pollutant Discharge Elimination System permit databases, Brazil MAPA veterinary product registries, EU Farm to Fork Strategy implementation documents, and FSSAI cattle feed safety standards. Bottom-up volume estimates from product-level consumption patterns were triangulated against top-down market sizing derived from grain-handling infrastructure throughput and commercial livestock inventory data.
Segment-weighting approaches modeled product type splits across feed, supplements, grooming supplies, and health products alongside end-user differentiation between dairy farms, beef cattle ranches, hobby farmers, and commercial livestock operations. Distribution channel dynamics incorporated wholesale, retail, direct sales, and online sales penetration patterns. CAGRs were derived through regression analysis of historical volume trajectories adjusted for regulatory inflection points and technology adoption curves. Industry-specific forecast inputs included precision-feeding hardware installation rates and lagoon cover investment cycles tied to EPA compliance deadlines.
Several conditions sit outside the modeled scope, including extreme weather events disrupting soybean-meal supply chains, abrupt antibiotic-resistance policy reversals in major producing jurisdictions, and currency volatility effects on Brazilian and Indian import economics. Forecasts reflect assumptions around continued regulatory tightening without catastrophic discontinuities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Horse Bunk Feeder Market
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Hog Feeder Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Animal Feeding Equipment Market
Livestock Equipment
Automatic Hog Feeder Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
Robotics Milking Systems Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Milking Equipment Market