
 Automatic Goat Waterer Market | 2026-2036
Automatic Goat Waterer Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Goat Waterer Market Outlook
Polyethylene is displacing galvanized steel in trough construction and is realigning unit economics across the supply base. Ritchie Industries leverages its heated product line to sustain margins in northern climates. Nelson Manufacturing anchors its position through direct veterinary channel relationships. Behlen Country competes on feed-equipment bundling rather than standalone waterer sales.
An automatic goat waterer is a thermostatically controlled or valve-regulated drinking system designed to maintain fresh water availability for caprine livestock, typically incorporating float mechanisms, heating elements, or pressure sensors operating between 30-60 psi. Its primary commercial purpose is reducing labor hours in herd management while preventing dehydration-related productivity losses in dairy and meat operations. Heated units lead the product type category due to cold-climate dependency, while stainless steel commands the material segment's margin pool through veterinary-grade durability requirements. Agricultural cooperatives represent the fastest-growing end user channel as group purchasing consolidates replacement cycles.
USDA Animal Welfare Act provisions and state agricultural extension water quality standards shape product certification requirements across domestic distribution. EPA Clean Water Act runoff provisions affect outdoor installation designs in concentrated animal feeding operations. Stakeholders must monitor evolving state-level livestock facility codes and cooperative procurement consolidation patterns to align capacity planning with channel migration toward farm supply stores and direct sales.
Market Dynamics
Polyethylene trough construction is overtaking galvanized steel across the Upper Midwest, compressing unit economics while USDA livestock handling guidelines tighten installation standards for automated systems.
Growth Catalysts
- USDA Animal Welfare Act provisions:Stricter audit requirements for commercial dairy farms in Wisconsin and Vermont are mandating consistent water access, forcing upgrades from manual to thermostatically controlled systems.
- Caprine dehydration losses:Dairy cooperatives in the Pacific Northwest are quantifying milk yield drops from intermittent water access, creating direct ROI calculations for automated installation.
- Heated element reliability:Northern climate dependency on freeze-resistant systems between 30-60 psi operation is locking in replacement cycles every 7-10 years across Minnesota and North Dakota herds.
Market Restraints
- Stainless steel input volatility:Veterinary-grade durability requirements for dairy-grade units expose manufacturers to nickel and chromium price swings that compress margin pools on premium SKUs.
- EPA Clean Water Act runoff friction:Outdoor installation designs in concentrated animal feeding operations face additional permitting layers that extend project timelines by 4-6 months in watershed-sensitive counties.
- Manual bucket systems:Small-scale meat goat operations under 50 head continue using gravity-fed buckets as a zero-capex substitute, capping penetration in the hobby farm segment.
Strategic Opportunities
- Vermont and New York sub-regions:Artisanal cheese cooperatives with 200-500 head operations remain underpenetrated by automated systems, presenting white space for mid-capacity heated units.
- Pressure sensor convergence with IoT:Valve-regulated systems integrating remote flow monitoring are enabling predictive maintenance contracts that shift revenue from hardware to recurring service.
- Agricultural cooperative procurement consolidation:Group purchasing organizations in the Upper Midwest are standardizing replacement cycles, creating volume commitments that favor direct manufacturer relationships over farm supply store distribution.
Industry Challenges
- Veterinary certification timelines:State agricultural extension water quality standards require third-party validation of float mechanism hygiene, adding 90-120 days to product launch schedules.
- Legacy electrical integration:Retrofitting heated units into barns with 1950s-era wiring requires licensed electrician coordination that bottlenecks installation capacity during autumn pre-winter rushes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Goat Waterer Market |
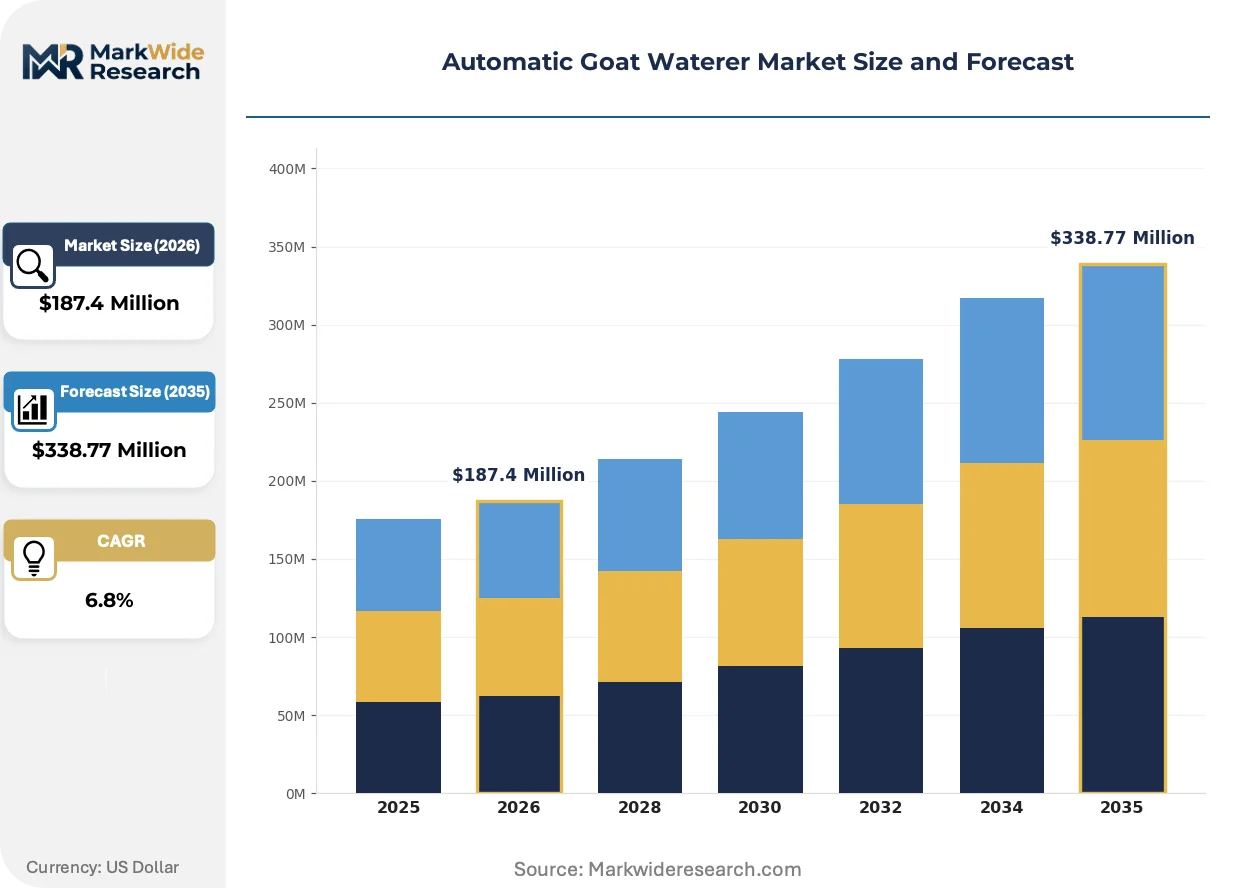
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heated, Float Valve, Pressure Regulator, Automatic Fill End User: Farmers, Livestock Owners, Agricultural Cooperatives, Veterinary Clinics Material: Plastic, Stainless Steel, Galvanized Steel, PVC Distribution Channel: Online Retail, Farm Supply Stores, Agricultural Shows, Direct Sales |
| Companies Covered | Ritchie Industries, Nelson Manufacturing, Behlen Country, Bar-Bar-A, Miller Manufacturing Company, HiCamer, The LaLa Farm, Horse Drinker, DP Waterer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Goat Waterer Market Strategic Shifts
Material substitution and regulatory digitization are compressing traditional supply chains while buyer behavior shifts toward consolidated procurement channels.
Thermoplastic polymer construction is overtaking metal fabrication in trough manufacturing. Float mechanisms molded from UV-stabilized polyethylene resist corrosion in high-mineral water regions while cutting shipping weight by 60%. Commercial dairies in Idaho and Oregon are specifying polymer units for new barn construction. This material shift is enabling modular designs that reduce field installation labor from two days to four hours.
USDA livestock handling guidelines are mandating documented water access intervals for animal welfare audits. The guidelines require timestamped verification of system functionality, pushing manufacturers to integrate basic data logging. Dairy cooperatives in Washington state are piloting systems with USB-exportable records. This regulatory pressure is accelerating adoption of sensor-equipped units even in cost-sensitive meat goat operations.
Group purchasing through agricultural cooperatives is consolidating replacement decisions across 15-30 member farms. The Upper Midwest Dairy Goat Association now negotiates annual volume contracts that bypass traditional farm supply stores. Direct manufacturer relationships are replacing distributor markups. This channel migration is most visible in Wisconsin where three cooperatives represent 40% of regional replacement demand.
Automatic Goat Waterer Market Segmentation
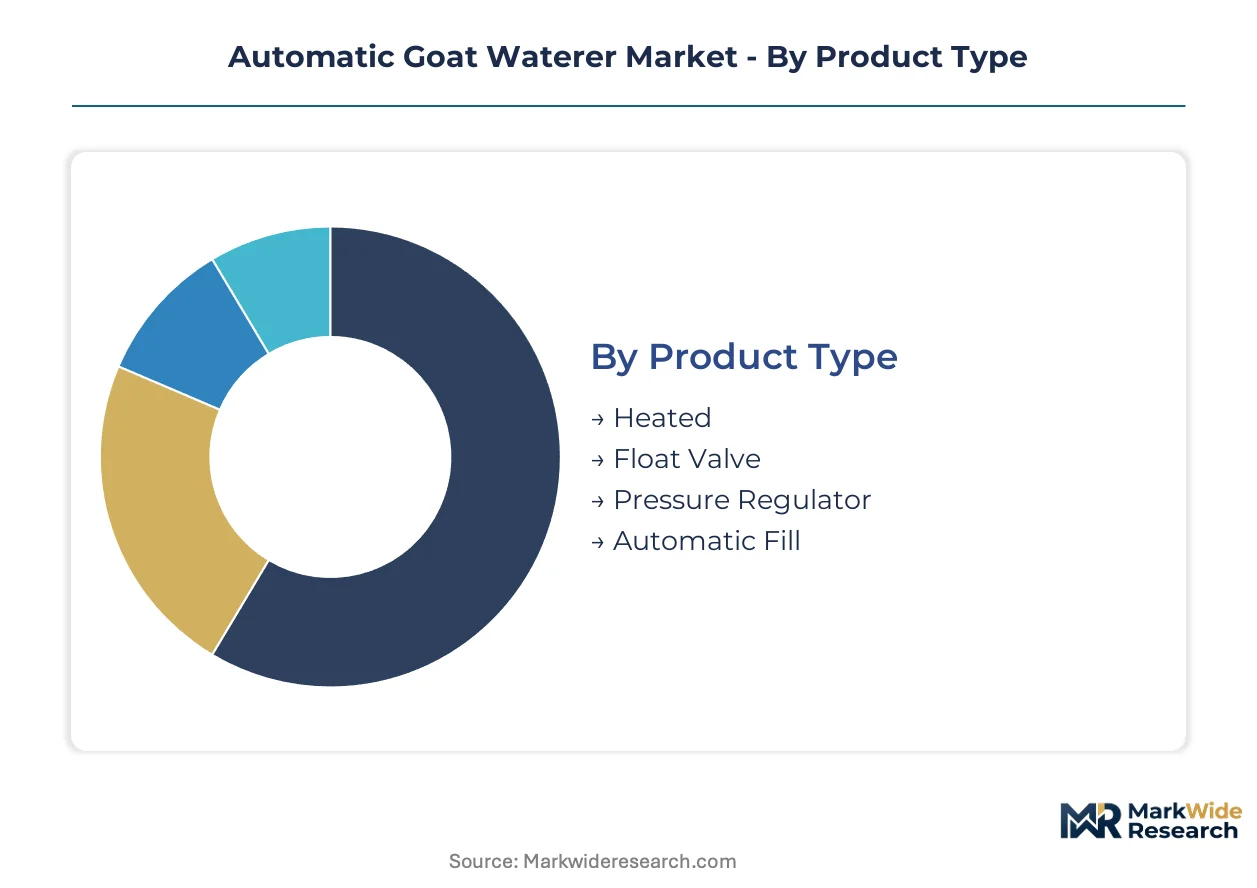
Segmentation in the automatic goat waterer market reveals how material substitution and channel migration are reshaping procurement patterns across dairy and meat operations. Understanding these divisions exposes where margin pools concentrate and which customer groups are consolidating purchasing power.
Product Type:
Supply concentration in freeze-resistant systems has locked northern climate producers into predictable replacement cycles, while valve technology advances are opening service-based revenue models.
- Heated:Thermostatically controlled units with integrated heating elements maintain water temperature above freezing in sub-zero conditions. Demand clusters in Minnesota, North Dakota, and Wisconsin dairy cooperatives where USDA Animal Welfare Act audits mandate uninterrupted water access during winter months.
- Float Valve:Mechanical float mechanisms regulate water level through simple buoyancy action, requiring no electrical infrastructure. These units dominate retrofit installations in older barns across Vermont and New York artisanal cheese operations where electrical upgrades are cost-prohibitive.
- Pressure Regulator:Valve-regulated systems operating between 30-60 psi enable consistent flow rates across variable barn pressure conditions.
- Automatic Fill:Timer-based or sensor-triggered refill systems reduce labor hours in large-scale operations.
Today's leader: Heated. Tomorrow's challenger: Pressure Regulator.
End User:
Cost tier stratification separates capital-rich dairy cooperatives from price-sensitive hobby farmers, with veterinary clinics emerging as specification gatekeepers for premium installations.
- Agricultural Cooperatives:Group purchasing organizations consolidate replacement demand across 15-30 member farms, negotiating direct manufacturer contracts that bypass traditional distribution markups. The Upper Midwest Dairy Goat Association now coordinates annual volume commitments representing 40% of regional replacement cycles.
- Farmers:Commercial dairy operations with 200-500 head herds drive heated unit adoption through quantified ROI calculations linking consistent water access to milk yield stability.
- Livestock Owners:Small-scale meat goat operations under 50 head continue using manual systems, capping penetration in the hobby farm segment.
- Veterinary Clinics:Large-animal practices specify equipment for client barns, functioning as indirect sales channels for premium stainless steel units.
Volume concentrates with Agricultural Cooperatives. Margin concentrates with Veterinary Clinics.
Material:
Geography determines material preference, with mineral-heavy water regions accelerating corrosion-driven replacement cycles and polymer adoption.
- Stainless Steel:Veterinary-grade 304 and 316 alloys deliver durability for dairy-grade installations requiring third-party hygiene validation. These units command premium positioning in Washington state and Oregon where state agricultural extension water quality standards mandate corrosion-resistant construction.
- Plastic:UV-stabilized polyethylene troughs resist mineral corrosion while cutting shipping weight by 60% versus metal alternatives. Idaho and Oregon commercial dairies specify polymer units for new barn construction.
- Galvanized Steel:Zinc-coated carbon steel remains common in legacy installations though polyethylene is displacing it across the Upper Midwest.
- PVC:Rigid polyvinyl chloride components serve specific plumbing integration applications in custom installations.
Stainless Steel anchors premium positioning. Plastic gains share fastest.
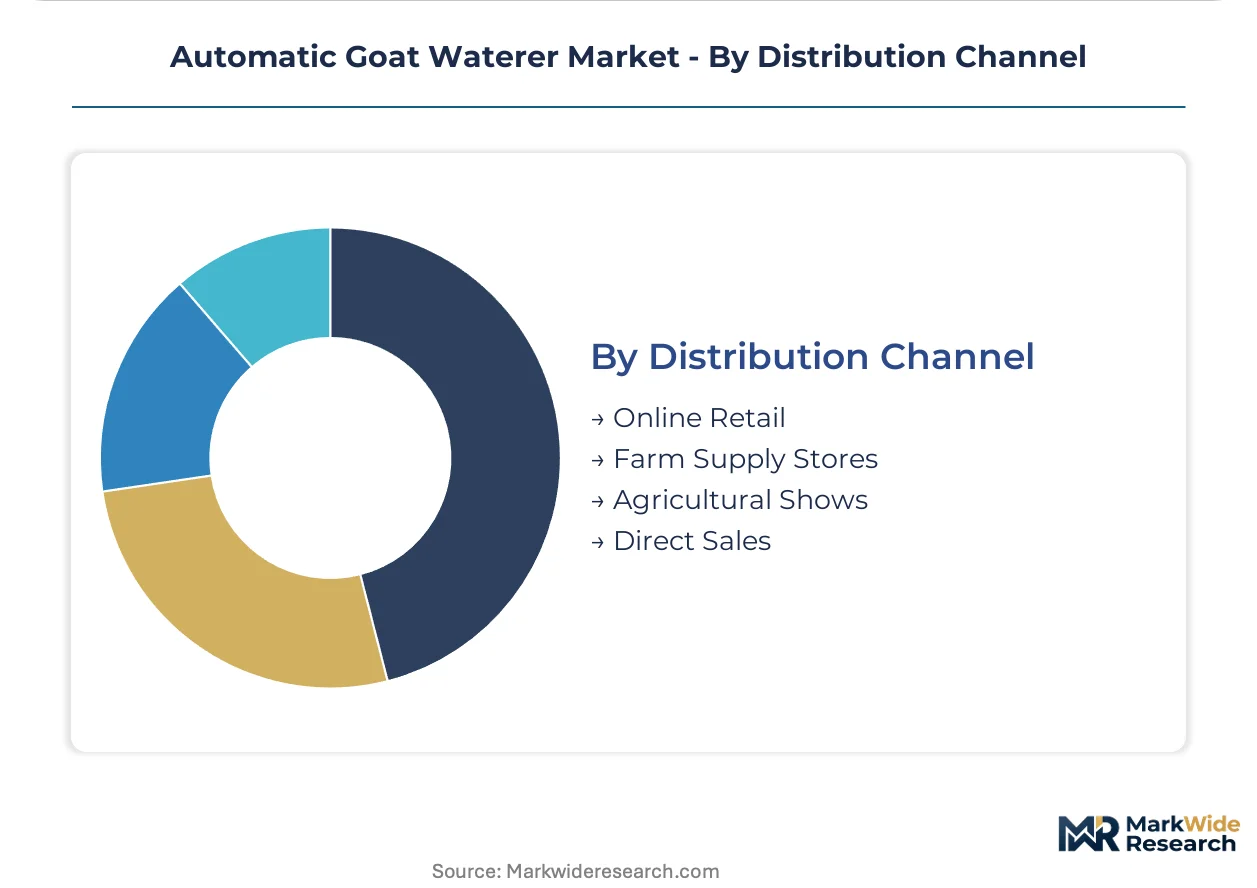
Distribution Channel:
Customer type migration is forcing channel restructuring, with cooperative procurement consolidation threatening traditional farm supply store relevance.
- Direct Sales:Manufacturers are building relationships with agricultural cooperatives, eliminating distributor markups through volume commitments. Wisconsin-based producers now route 40% of regional volume through three cooperative purchasing agreements.
- Farm Supply Stores:Traditional retail channels serve emergency replacement demand and small-scale operators outside cooperative networks.
- Online Retail:E-commerce platforms capture price-sensitive comparison shopping for standardized polymer units.
- Agricultural Shows:Regional livestock exhibitions function as demonstration venues for heated product lines targeting northern climate producers.
Direct Sales is expanding most quickly. Farm Supply Stores defend emergency replacement positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Upper Midwest dairy belt anchors automatic goat waterer demand through Wisconsin and Minnesota cooperatives operating 200-500 head herds. USDA Animal Welfare Act audit requirements and state agricultural extension water quality standards are tightening installation specifications across northern climate zones.
United States
Wisconsin dairy cooperatives drive heated unit replacement cycles every 7-10 years through quantified milk yield loss calculations. USDA Animal Welfare Act provisions mandate timestamped water access verification for commercial herds over 50 head. The Upper Midwest Dairy Goat Association in Madison coordinates group purchasing agreements covering 40% of regional volume.
Canada
Ontario and Quebec goat cheese producers are retrofitting artisanal operations with float valve systems to bypass electrical infrastructure limitations. Health Canada veterinary equipment guidelines require corrosion-resistant materials for dairy-grade installations. The Ottawa Valley cooperative cluster is consolidating procurement for 30-member farms.
Germany
Baden-Württemberg specialty cheese producers are importing heated waterer designs adapted from North American cold-climate specifications. EU hygiene regulations for small ruminant dairy operations mandate continuous water access documentation. The Black Forest artisanal dairy cluster is piloting pressure-regulated systems for variable barn pressure conditions.
France
Auvergne-Rhône-Alpes goat cheese appellations are specifying stainless steel units to meet veterinary-grade durability requirements for export certification. ANSM agricultural equipment standards govern float mechanism hygiene validation timelines. The Massif Central cooperative federation is standardizing replacement cycles across 25 member operations.
Australia
Victoria and New South Wales meat goat exporters are installing polymer trough units to reduce shipping weight and mineral corrosion in high-alkalinity water regions. TGA livestock welfare guidelines require documented water access for export accreditation. The Riverina intensive goat production zone is adopting modular designs to cut field installation labor.
Automatic Goat Waterer Market Competitive Environment
Global majors compete with regional champions across material specialization and climate-specific engineering. The vendor base separates into three tiers: heated-system specialists commanding premium positioning in northern markets, polymer-fabrication scale players compressing unit economics, and veterinary-channel anchoring firms capturing specification influence. Strategic moves concentrate on direct cooperative procurement relationships and material substitution R&D rather than acquisition-driven consolidation.
Among North American equipment fabricators, Ritchie Industries, Nelson Manufacturing, and Behlen Country exemplify distinct competitive archetypes. Ritchie Industries anchors the heated-system premium tier through cold-climate engineering concentration. Nelson Manufacturing occupies the veterinary-channel specification gatekeeper position. Behlen Country represents feed-equipment bundling strategy rather than standalone waterer specialization. These three firms collectively illustrate how regional market structure rewards climate-specific engineering, channel control, and portfolio adjacency over pure scale.
| Leading Market Players |
|---|
| Ritchie Industries |
| Nelson Manufacturing |
| Behlen Country |
| Bar-Bar-A |
| Miller Manufacturing Company |
| HiCamer |
| The LaLa Farm |
| Horse Drinker |
| DP Waterer |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators across Wisconsin and Iowa anchor production capacity, linking conservative balance-sheet discipline to stable contract pricing and limited spot-market exposure for heated unit lines.
Pricing Analysis
Input-cost pass-through from nickel and chromium volatility compresses margin pools on veterinary-grade stainless steel SKUs, forcing three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates USDA-certified heated systems from polymer retrofit units. Cost compression in the galvanized steel tier is intensifying because polyethylene displacement accelerates across Minnesota dairy cooperatives. Small-scale meat goat operations under 50 head exhibit highest price sensitivity, while agricultural cooperatives negotiating volume commitments show lowest.
Supply Chain Analysis
Heating element supply rests on Chinese and South Korean electrical component manufacturers, with thermoplastic polymer feedstock drawing from Texas and Louisiana petrochemical corridors. Float mechanism machining centers on Illinois and Ohio metalworking clusters. Single-source vulnerability concentrates in sub-zero thermostatic controllers sourced from a narrow supplier base in northern China. Distribution runs through direct cooperative procurement agreements that bypass traditional farm supply store markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by dairy cooperative demand shifting toward heated units with timestamped data logging for USDA Animal Welfare Act compliance.
For Market Incumbents: Extend veterinary-channel relationships into predictive maintenance service contracts, locking in replacement cycle visibility. Deepen backward integration into UV-stabilized polyethylene molding to defend against polymer-fabrication scale entrants. Prioritize certification investment for state agricultural extension water quality standards ahead of competitors. For New Entrants and Emerging Players: USDA Animal Welfare Act provisions in Wisconsin and Vermont open a window for mid-capacity heated units targeting 200-500 head artisanal cheese operations. The most penetrable segment remains underautomated New York and Vermont sub-regions with electrical infrastructure limitations favoring float valve retrofits. A direct-to-cooperative go-to-market angle bypasses entrenched farm supply store distribution. For Investors and Strategic Acquirers: Valuations sit cheapest among polymer-fabrication specialists with unexploited veterinary-channel access. Long-term viability over a 5-10 year window hinges on regulatory digitization tailwinds and cooperative procurement consolidation. Target acquisition archetype: heated-system engineering shops with cold-climate IP and underdeveloped service revenue. Watch state-level livestock facility code revisions as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Cooperative Procurement Agreements | Wisconsin's Upper Midwest Dairy Goat Association now routes 40% of regional volume through manufacturer-direct contracts, eliminating distributor markups. |
| Pressure Sensor IoT Integration | Valve-regulated systems with remote flow monitoring enable predictive maintenance contracts shifting revenue from hardware to recurring service. |
| Polymer Trough Manufacturing Scale-Up | Idaho and Oregon commercial dairies specify UV-stabilized polyethylene units cutting shipping weight by 60% versus metal alternatives. |
| Veterinary Channel Specification Control | Nelson Manufacturing anchors positioning through large-animal practice relationships functioning as indirect sales channels for premium installations. |
| Heated Product Line Cold-Climate Engineering | Ritchie Industries sustains margins in northern climates through thermostatic reliability engineering for Minnesota and North Dakota herds. |
Study Parameters
Direct dialogue with dairy cooperative procurement managers, agricultural extension water quality officers, veterinary equipment specifiers, and heated-system manufacturing engineers grounded qualitative findings. Secondary validation drew from USDA livestock handling guideline amendments, EPA Clean Water Act runoff enforcement records, state agricultural facility code filings, and agricultural cooperative purchasing disclosure documents. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segment-level projections across the analysis window model product type, material substitution trajectory, end-user channel migration, and regional regulatory cluster intensity. CAGRs derive from replacement cycle quantification, cooperative procurement consolidation velocity, and cold-climate dependency coefficients. Forecast inputs include USDA audit penetration rates and polyethylene displacement curves in trough construction.
Revisions become necessary when state-level livestock facility codes accelerate adoption timelines, nickel-chromium input volatility disrupts stainless steel tier economics, or cooperative procurement consolidation shifts faster than modeled. Forecasts reflect documented assumptions about regulatory digitization pace and material substitution elasticity. A small set of named triggers warrants ongoing watch: EPA enforcement intensity in watershed-sensitive counties, veterinary certification timeline compression, and electrical infrastructure retrofit bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Rabbit Hutches Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Egg Incubator Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Animal Feeding Equipment Market
Livestock Equipment
Cattle Handling Systems Market
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Silage Tube Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Starter Feed Market