
 Sheep Supplies Market | 2026-2036
Sheep Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Sheep Supplies Market Analytics
The split between premium precision equipment and basic commodity supplies is shifting as commercial producers automate while smallholders minimize capital outlay. Gallagher leverages its trans-Tasman manufacturing footprint to dominate electric fencing systems for rotational grazing. Zoetis anchors its position through veterinary pharmaceuticals and animal health monitoring tools that integrate with farm management software. Tru-Test competes in weigh-scale and data-capture hardware, sustaining R&D intensity in electronic identification systems.
Sheep supplies encompass the full range of inputs required for ovine husbandry, including formulated feed rations with crude protein specifications between 14-18%, wire mesh fencing rated to 1800 MPa tensile strength, straw or wood-shred bedding, and shearing equipment with blade speeds exceeding 2500 strokes per minute. These products serve the commercial management of flocks for fiber, meat, and dairy output. Feed and fencing together occupy the largest share of product-type spending, with feed margins tightening as grain price volatility persists and fencing benefiting from multi-year replacement cycles. Wool production applications lead absolute demand within the application dimension, though meat production commands faster growth as Middle Eastern and Asian import appetites expand.
USDA grazing permits on federal lands shape flock mobility and therefore fencing investment patterns across the American West. Australia's Biosecurity Act and NLIS (National Livestock Identification System) mandate electronic tagging, directly stimulating demand for compatible readers and data infrastructure. The EU's Farm to Fork Strategy tightens antibiotic use restrictions, redirecting veterinary spending toward preventive health supplies. Stakeholders must weigh backward integration into feed formulation against outsourcing risks as ingredient traceability requirements proliferate.
Market Dynamics
Automated feeding systems and electronic identification infrastructure are compressing operational labor requirements across commercial sheep operations, forcing suppliers to recalibrate hardware-software bundles toward data-integrated platforms rather than standalone equipment sales.
Growth Catalysts
- Australia's NLIS mandate:Electronic tagging requirements under the Biosecurity Act sustain replacement demand for RFID readers and data-logging infrastructure across the country's commercial flock.
- EU penning standards:Animal welfare regulations mandating improved housing density and flooring specifications drive capital expenditure on modular penning systems and automated ventilation.
- Rotational grazing intensity:New Zealand's large-scale wool and meat operations expand electric fencing procurement for pasture subdivision, favoring high-tensile wire and solar energizer configurations.
Market Restraints
- Grain price volatility:Formulated feed rations face margin compression as wheat and soybean meal costs fluctuate, squeezing compound feed producers unable to hedge input exposure.
- Steel supply concentration:Fencing wire production depends on concentrated Australian and Chinese metallurgical capacity, exposing buyers to alloy pricing shocks and freight cost spikes.
- Antibiotic restriction friction:The EU Farm to Fork Strategy redirects veterinary spending toward preventive health, but transition costs burden smallholders lacking technical advisory access.
Strategic Opportunities
- Sheep dairy expansion:Specialty cheese and infant formula processors in France and Spain create demand for automated milking parlors and cold-chain handling equipment.
- Carbon accounting integration:Methane monitoring sensors and feed additives qualifying for carbon credit schemes attract investment from sustainability-linked finance vehicles.
- Direct-to-producer digital channels:Equipment suppliers bypass traditional agricultural merchants through e-commerce platforms and subscription-based precision agriculture services.
Industry Challenges
- Data interoperability gaps:Proprietary farm management software from competing hardware vendors blocks seamless integration of weigh-scale, EID, and feeding system data streams.
- Skilled technician scarcity:Installation and calibration of automated shearing equipment and precision feeding systems outpaces vocational training pipeline output in rural regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheep Supplies Market |
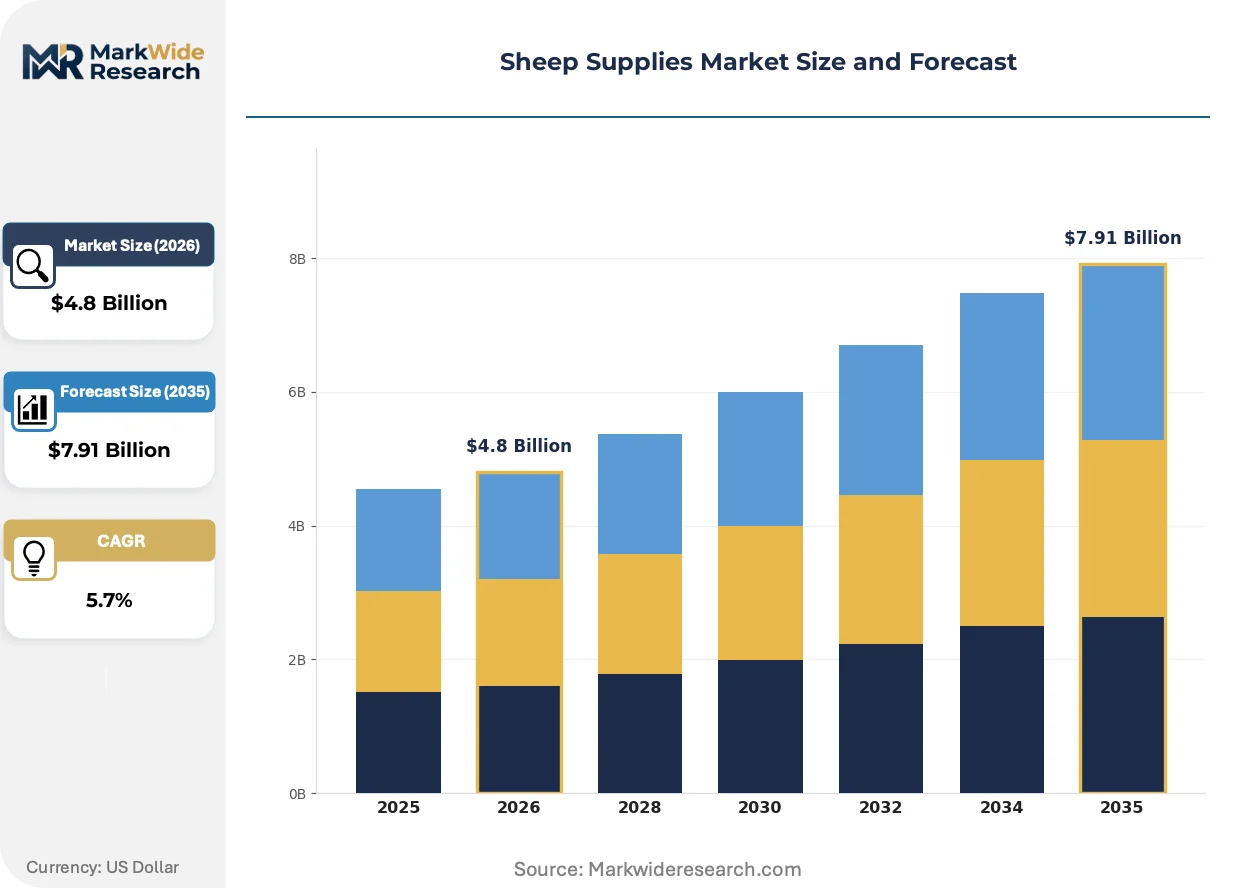
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed, Fencing, Bedding, Grooming Supplies Application: Livestock Management, Wool Production, Meat Production, Dairy Production End User: Farmers, Agricultural Cooperatives, Livestock Producers, Veterinarians Distribution Channel: Online Stores, Agricultural Supply Stores, Retail Chains, Direct Sales |
| Companies Covered | Gallagher, Premier 1 Supplies, Ritchie Agricultural, Tru-Test, Kerbl, Zoetis, MSD Animal Health, Boehringer Ingelheim, Patterson Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheep Supplies Market Evolving Landscape
Precision livestock technologies and traceability mandates are collapsing the distinction between equipment and data services, compelling suppliers to embed subscription analytics into hardware contracts.
Automated shearing platforms with computer vision guidance are rewriting labor economics in wool harvesting operations. Large-scale stations in Australia's Riverina and Western Plains districts deploy these systems to compress shearing windows and reduce contractor dependence. The technology is compressing seasonal labor peaks into continuous processing schedules that favor capital-intensive fleet ownership over traditional contractor pools.
REACH chemical registration requirements are tightening restrictions on antiparasitic active ingredients used in sheep dips and pour-ons. Formulation houses face reformulation costs and extended authorization timelines for legacy organophosphate and synthetic pyrethroid products. Veterinary pharmaceutical distributors in Germany and the Netherlands are pivoting toward bio-based and mineral alternatives to maintain product portfolios under tightened biocide frameworks.
Consolidated meat processors are imposing unannounced welfare audit requirements on supplying farms, forcing equipment procurement decisions through certification-driven specifications. Abattoir-linked procurement officers in the United Kingdom and Ireland now mandate CCTV coverage in handling facilities and documented training records for electric prod use. This behavioral shift channels smallholder spending toward compliance-verified handling systems rather than lowest-cost alternatives.
Sheep Supplies Market Segmentation
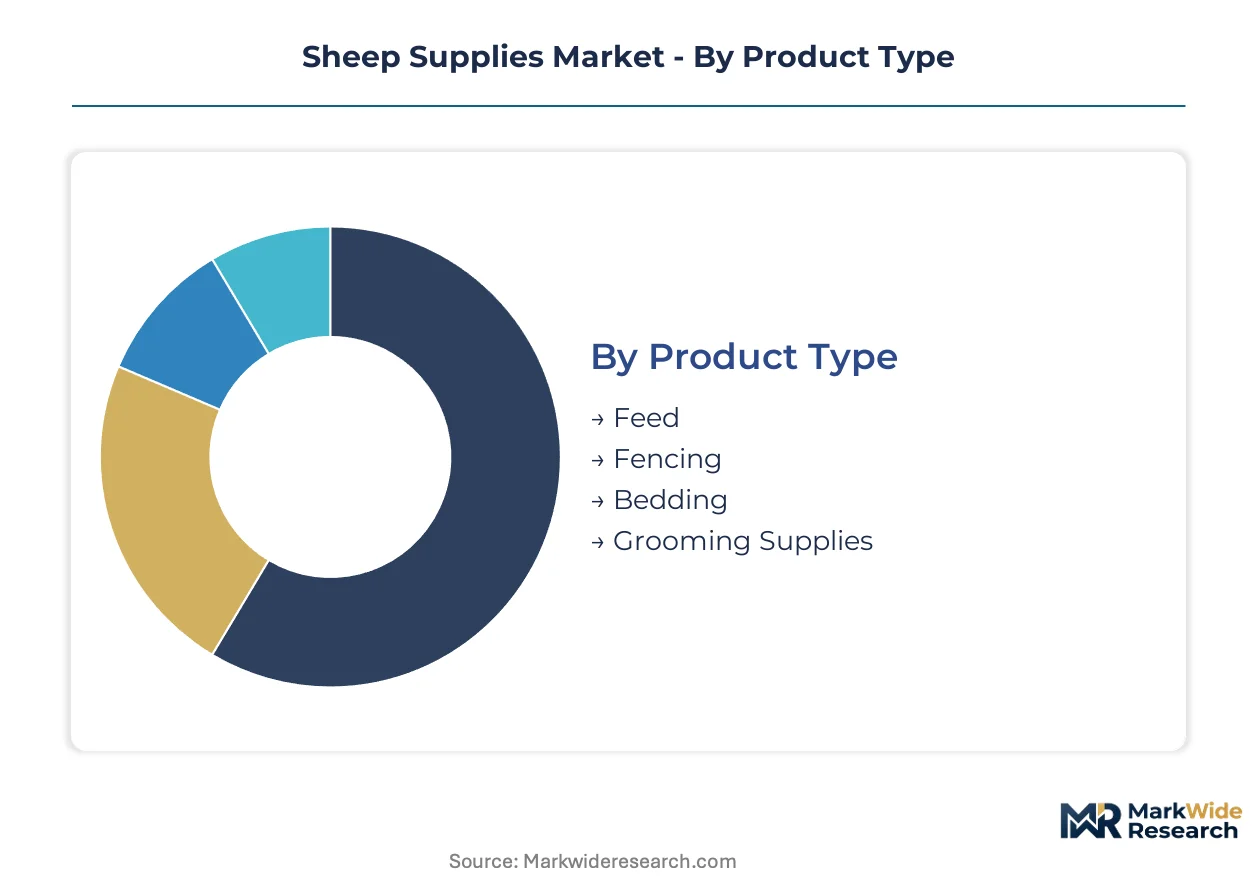
Segmentation in sheep supplies reveals divergent procurement patterns between capital-intensive commercial operations and cost-constrained smallholders. Equipment specifications, feed formulations, and distribution channels fragment sharply across flock size and output destination, forcing suppliers to maintain parallel product architectures.
Product Type:
Volume concentration favors bulk commodities with thin margins, while premium tiers concentrate in precision-engineered equipment with embedded data capabilities.
- Feed:Formulated rations specify crude protein between 14-18% for finishing lambs and breeding ewes. Australia's Riverina feedlots and New Zealand's South Island stations drive bulk procurement, though grain price volatility compresses compounder margins.
- Fencing:High-tensile wire mesh rated to 1800 MPa dominates rotational grazing infrastructure. New Zealand's large-scale wool and meat operations favor electric configurations with solar energizers for remote pasture subdivision.
- Bedding:Straw and wood-shred materials absorb moisture in lambing pens and finishing sheds. Demand clusters in EU member states with mandated housing density standards under welfare regulations.
- Grooming Supplies:Shearing equipment with blade speeds exceeding 2500 strokes per minute serves wool harvesting operations. Australia's Western Plains districts deploy automated platforms with computer vision guidance.
Mature deployment sits with Fencing. Newer deployment is concentrated in automated Grooming Supplies.
Application:
Output destination shapes equipment specifications, with fiber-focused operations prioritizing wool handling infrastructure and meat-oriented farms investing in finishing pen systems.
- Livestock Management:Electronic identification readers and data-logging infrastructure support Australia's NLIS compliance. RFID-compatible hardware sustains replacement demand across the country's commercial flock.
- Wool Production:Shearing platforms and wool handling equipment dominate capital expenditure. Australia's Riverina stations compress seasonal labor peaks through automated fleet ownership.
- Meat Production:Finishing pens with automated feeding systems serve Middle Eastern and Asian export markets. EU abattoirs impose unannounced welfare audits that mandate CCTV coverage and documented handling protocols.
- Dairy Production:Automated milking parlors and cold-chain handling equipment support sheep cheese and infant formula processors. France and Spain anchor specialty dairy equipment demand.
Traditional volume concentration rests with Wool Production. Steepest expansion trajectory appears in Meat Production.
End User:
Procurement scale fragments sharply, with institutional buyers leveraging volume contracts while independent operators prioritize flexibility and local service access.
- Farmers:Individual operators balance capital constraints against compliance requirements. Smallholders in the EU face transition costs from antibiotic restrictions under the Farm to Fork Strategy.
- Agricultural Cooperatives:Pooled purchasing power secures volume discounts on feed and fencing. New Zealand's cooperative structures drive bulk procurement for member stations.
- Livestock Producers:Commercial-scale operations invest in integrated hardware-software bundles. Australia's Biosecurity Act mandates drive electronic tagging infrastructure spending.
- Veterinarians:Preventive health supplies and diagnostic equipment redirect spending from therapeutic antibiotics. REACH registration requirements tighten antiparasitic formulation availability.
Established procurement patterns center on Farmers. Emerging concentration appears in Livestock Producers.
Distribution Channel:
Channel selection reflects customer technical sophistication and equipment complexity, with simple replenishment goods migrating online while precision hardware demands installation support.
- Online Stores:E-commerce platforms bypass traditional agricultural merchants for consumables and spare parts. Subscription-based precision agriculture services embed analytics into hardware contracts.
- Agricultural Supply Stores:Local merchants provide technical advisory and immediate availability for routine inputs. Rural technician scarcity limits support capacity for automated equipment calibration.
- Retail Chains:Standardized fencing and feed products reach smallholders through broadline agricultural retailers. Limited technical specialization constrains precision equipment sales.
- Direct Sales:Manufacturers deploy field engineers for automated shearing platforms and milking parlors. Installation complexity favors captive service networks over third-party distribution.
Longstanding channel dominance resides with Agricultural Supply Stores. Fastest channel shift appears in Direct Sales for precision equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canterbury Plains in New Zealand's South Island anchors commercial sheep supply procurement, with large-scale wool and meat operations driving bulk orders for fencing and husbandry equipment across the trans-Tasman region.
Australia
Riverina feedlots and Western Plains stations invest heavily in automated feeding systems and shearing platforms. The Biosecurity Act and NLIS mandate electronic tagging, sustaining demand for RFID readers and data-logging infrastructure. Victoria's Gippsland region concentrates precision agriculture adoption among commercial flock managers.
New Zealand
South Island stations prioritize electric fencing with solar energizers for rotational grazing across remote pastures. Agricultural cooperatives pool purchasing power for member bulk procurement. Otago and Southland districts lead automated milking parlor installation for sheep dairy operations serving specialty cheese processors.
United States
USDA grazing permits on federal lands shape flock mobility and fencing investment patterns across the American West. Texas and Colorado ranchers face margin pressure from grain price volatility in formulated feed procurement. California's Central Valley hosts precision livestock technology trials integrating methane monitoring sensors.
European Union
Germany and the Netherlands pivot veterinary pharmaceutical distribution toward bio-based antiparasitic alternatives under REACH tightening. France and Spain anchor sheep dairy equipment demand for infant formula and specialty cheese processing. The Farm to Fork Strategy redirects spending from therapeutic antibiotics to preventive health supplies.
United Kingdom
Abattoir-linked procurement officers mandate CCTV coverage in handling facilities and documented electric prod training records. Welsh and Scottish hill farms consolidate through cooperative structures to meet unannounced welfare audit requirements. Northern England processors impose certification-driven specifications on supplying farms.
Sheep Supplies Market Competitive Landscape
Premium-margin players sit above commodity-margin players across equipment sophistication tiers, with data-integrated hardware-software bundles commanding pricing power over standalone consumables. The vendor base separates into three strategic archetypes: trans-Tasman manufacturers with integrated regional supply chains, pharmaceutical anchors bundling animal health with monitoring tools, and precision hardware specialists sustaining R&D intensity in electronic identification. Competitive moves concentrate on backward integration into feed formulation and direct-to-producer digital channel expansion bypassing traditional agricultural merchants.
Within the trans-Tasman manufacturing tier, Gallagher exemplifies regional production footprint leverage for electric fencing systems. Tru-Test occupies a position in weigh-scale and data-capture hardware archetypes. Zoetis anchors the pharmaceutical-health monitoring integration segment. These three represent distinct competitive positioning vectors without overlapping core specializations.
| Leading Market Players |
|---|
| Gallagher |
| Premier 1 Supplies |
| Ritchie Agricultural |
| Tru-Test |
| Kerbl |
| Zoetis |
| MSD Animal Health |
| Boehringer Ingelheim |
| Patterson Companies |
| Others |
Value Network & Pricing Analysis
High-tensile steel wire costs cascade from Australian and Chinese metallurgical capacity through fencing equipment pricing tiers, with alloy pricing shocks compressing margins for compound feed producers unable to hedge grain exposure.
Pricing Analysis
Value-based pricing anchored to flock throughput and labor savings dominates automated shearing platforms and precision feeding systems. Three-tier pricing structure across premium, standard, and economy levels separates subscription-embedded analytics from standalone hardware and commodity consumables. Price differentiation hinges on certification grade for EU welfare compliance and volume scale for New Zealand cooperative procurement. Pricing pressure stems from grain price volatility squeezing formulated feed margins, while smallholders exhibit acute price sensitivity compared to commercial livestock producers investing in integrated bundles.
Supply Chain Analysis
REACH chemical registration and NLIS electronic tagging compliance gate veterinary pharmaceutical and data hardware distribution across the European Union and Australia. Manufacturing concentrates in Australia, China, and New Zealand for fencing wire and precision equipment. Raw material dependencies include high-grade steel alloys, formulated feed grains, and semiconductor components for RFID systems. Single-source vulnerability in Chinese metallurgical capacity exposes buyers to freight cost spikes. Distribution runs through agricultural supply stores for routine inputs and direct sales with captive service networks for automated equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as feed compounders pursue backward control over grain sourcing to insulate margins from price volatility.
For Market Incumbents: Deepen captive supply relationships with Australian and Chinese steel producers to secure alloy pricing stability against fencing wire cost spikes. Lock in multi-year service contracts for automated shearing platform calibration to offset rural technician scarcity. Consolidate position through certification pre-investment ahead of EU welfare audit mandate expansion.
For New Entrants and Emerging Players: Begin with sheep dairy equipment white space in France and Spain, where automated milking parlor penetration lags bovine operations. Target carbon credit-qualifying methane monitoring sensors as the most penetrable precision agriculture segment. Pursue direct-to-producer digital channels bypassing traditional agricultural merchants for consumables and spare parts.
For Investors and Strategic Acquirers: Australia's Biosecurity Act enforcement intensity is the leading indicator that electronic identification infrastructure spending will sustain replacement demand cycles. Long-term viability favors trans-Tasman manufacturers with integrated regional supply chains over pure-play pharmaceutical distributors facing REACH reformulation costs. Watch for consolidation signals when feed compounders acquire grain handling assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Formulation | Captive grain sourcing insulates compounders from wheat and soybean meal volatility. |
| Hardware-software Bundle Subscription | Embedded analytics contracts with Australian livestock producers reduce equipment sales cyclicality. |
| EU Welfare Certification Pre-investment | Modular penning systems positioned ahead of Farm to Fork Strategy enforcement capture compliance-driven replacement. |
| Direct-to-Producer Digital Channel | E-commerce platforms bypass New Zealand agricultural cooperatives for spare parts and consumables. |
| Carbon Credit-Linked Product Development | Methane monitoring sensors qualifying for sustainability-linked finance attract institutional capital. |
Research Methodology
Document review covered customs and trade databases, agricultural supply chain filings, and regulatory mandate texts, complemented by interviews with farm equipment procurement managers, veterinary pharmaceutical distributors, precision agriculture CTOs, and cooperative purchasing officers. Secondary validation drew from USDA grazing permit records, Australia's Biosecurity Act implementation reports, EU Farm to Fork Strategy documentation, and New Zealand agricultural export statistics. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Cross-referencing historical expenditure patterns with expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application destination, end-user scale, and distribution channel complexity. CAGRs derived from trend extrapolation adjusted for regulatory mandate timing and technology adoption S-curves. Industry-specific forecast inputs incorporated NLIS compliance deadlines and REACH chemical registration timelines.
Underlying measurement precision varies by segment; fencing and feed commodities carry tighter precision than emerging precision equipment categories. Forecasts reflect assumptions about regulatory enforcement consistency and grain price volatility persistence. A model refresh is warranted upon material change in EU welfare audit mandate expansion or Australian biosecurity enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Egg Incubator Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Robotics Milking Systems Market
Livestock Equipment
Cattle Handling Systems Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Horse Bunk Feeder Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Horse Corral Panels Market
Livestock Equipment
Milking Equipment Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Automatic Cattle Waterer Market
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Automated Feeding System Market