
 Poultry Processing Equipment Market | 2026-2036
Poultry Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Processing Equipment Market Intelligence
The gap between premium and commodity poultry processing equipment is consolidating around automation depth and traceability capability. Marel leverages its integrated software-hardware platforms to command positions in high-throughput integrator accounts. Bettcher Industries, Inc. sustains dominance in handheld pneumatic cutting tools for mid-scale facilities that prioritize flexibility over full-line automation. GEA Group Aktiengesellschaft anchors European demand with thermal processing and refrigeration systems that processors bundle with primary line equipment.
Poultry processing equipment encompasses machinery designed to transform live birds into portioned, packaged protein through controlled sequences of stunning, scalding, defeathering, evisceration, chilling, and cut-up operations, with line speeds typically calibrated to 70–140 birds per minute depending on facility scale and regulatory jurisdiction. Automated systems lead capital expenditure flows as integrators pursue labor reduction and yield optimization, while semi-automated units retain share among co-packers and regional processors balancing capital constraints against volume commitments. Conveyor systems constitute the backbone infrastructure connecting discrete operations, with sorting devices representing the fastest-growing sub-category as vision-based grading technology penetrates quality inspection stations.
USDA HACCP protocols and FDA Food Safety Modernization Act traceability mandates shape equipment specifications across United States processing facilities, while EU Regulation 853/2004 hygiene requirements and CE marking directives govern machinery design standards for European suppliers. Brazil's national agricultural regulator enforces equivalency standards for export-oriented plants, conditioning equipment procurement decisions for integrators serving international buyers. Stakeholders must monitor how pending updates to antimicrobial residue testing protocols and carbon footprint disclosure frameworks reshape capital allocation priorities across processor procurement committees.
Market Dynamics
Quick-service restaurant supply chains are compressing equipment replacement cycles by mandating throughput gains that legacy cut-up lines cannot deliver, forcing integrators to prioritize automation depth over incremental upgrades.
Growth Catalysts
- USDA HACCP Sanitization Mandates:Updated protocols for antimicrobial residue control are compelling North American processors to retrofit scalding and chilling systems with automated clean-in-place architectures.
- Vision-Based Grading Technology:Machine-vision sorting modules are penetrating quality inspection stations as integrators seek yield optimization beyond manual grading throughput ceilings.
- Brazil Export Modernization:National agricultural regulator equivalency standards for export-oriented plants are accelerating slaughterhouse capacity investments serving international buyers.
Market Restraints
- Stainless Steel Input Volatility:Equipment fabricators face margin compression from nickel and chromium price swings that distort capex quoting timelines for regional processors.
- European Component Supply Concentration:Specialized drive motors and pneumatic controls cluster among German and Italian suppliers, exposing lead-time risk during logistics disruptions.
- Technical Ceiling on Line Speeds:Evisceration accuracy degrades above 140 birds per minute regardless of automation depth, capping throughput gains for high-volume facilities.
Strategic Opportunities
- India Poultry Integration:Nascent organized processing capacity offers first-mover positioning for equipment vendors as FSSAI hygiene standards tighten on commercial operations.
- Carbon Footprint Disclosure Frameworks:Emerging EU CSRD and scope-3 reporting mandates create pull for energy-efficient scalding and refrigeration system retrofits.
- Convergence of Robotics and Cold Chain:Collaborative robotic deboning cells paired with intelligent chilling tunnels enable processors to consolidate footprint while expanding SKU flexibility.
Industry Challenges
- Mechatronics Talent Scarcity:Facilities struggle to staff maintenance functions requiring simultaneous expertise in pneumatic cutting tools, programmable logic controllers, and food safety protocols.
- Legacy System Integration Friction:Brownfield plants face extended commissioning timelines when threading automated sorting devices into existing conveyor backbones with mismatched control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Processing Equipment Market |
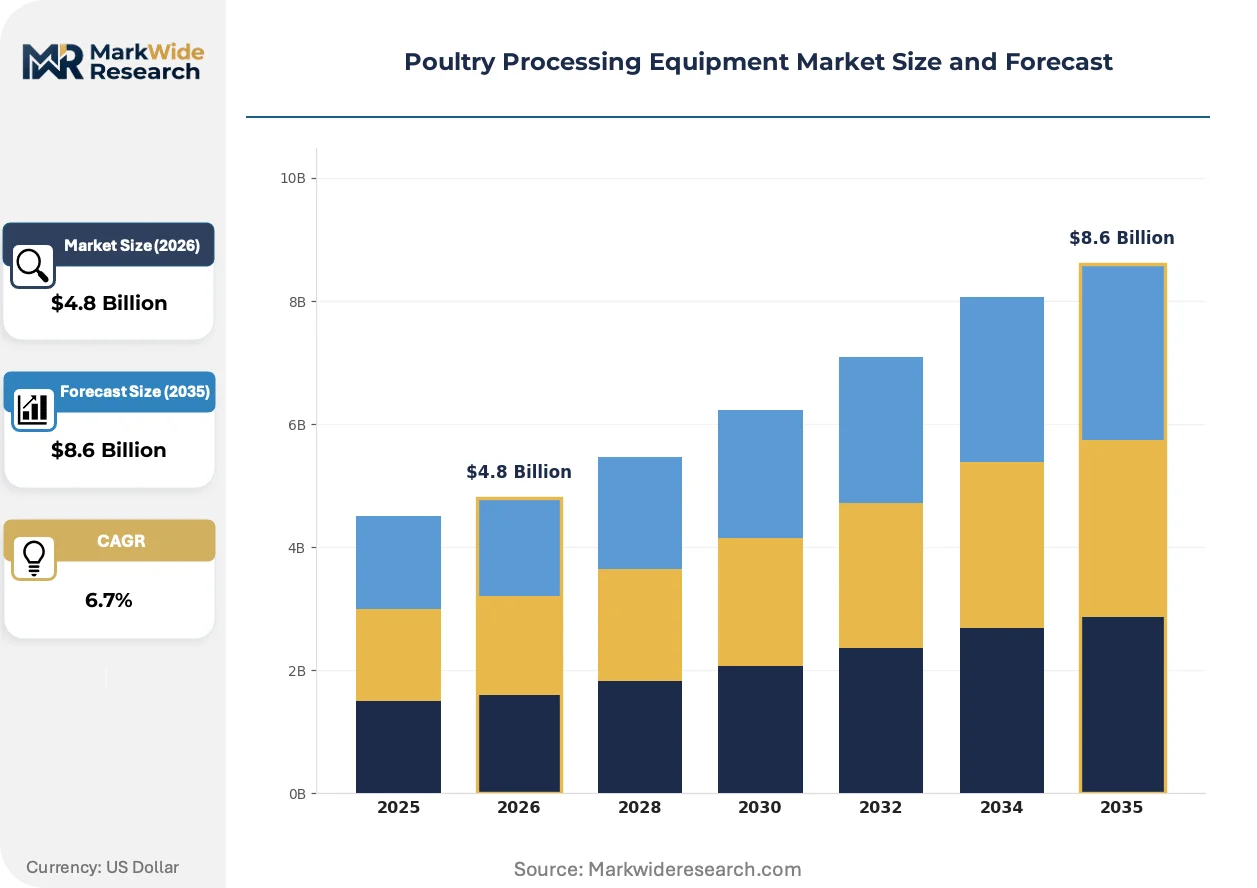
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalders, Defeathering Machines, Eviscerators, Cut-up Equipment, Sorting Devices Technology: Automated Systems, Semi-automated Units, Pneumatic Tools, Hydraulic Machines, Conveyor Systems Application: Slaughterhouses, Meat Processing Plants, Food Packaging Units, Quality Inspection Stations End User: Integrators, Co-packers, Foodservice Providers, Retail Distributors |
| Companies Covered | Baader Global SE, Bettcher Industries, Inc., Marel, The Middleby Corporation, Duravant LLC, GEA Group Aktiengesellschaft, Provisur Technologies Inc., Hellmann Poultry, John Bean Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Processing Equipment Market Strategic Shifts & Innovations
Equipment specification is pivoting from throughput metrics to traceability-enabling architectures as buyers anticipate regulatory exposure and brand liability downstream.
Hyperspectral imaging systems for real-time fat-to-lean ratio assessment are rewriting quality control economics in cut-up operations. High-throughput integrators in Brazil and the United States are deploying these modules at evisceration exit points to redirect birds into premium or commodity channels before chilling. The technology is compressing the value gap between automated and semi-automated lines by enabling yield capture that manual grading cannot replicate.
EU Regulation 853/2004 hygiene requirement amendments are mandating open-surface cleanability standards that favor welded stainless-steel frame architectures over bolted assemblies. European equipment suppliers are redesigning scalding tank geometries to eliminate crevices where biofilm accumulates. Thermal processing and refrigeration system buyers are bundling these compliant configurations with primary line purchases to preempt regulatory retrofit costs.
Buyer committees are unbundling after-sales service contracts from equipment procurement, shifting toward third-party maintenance aggregators or in-house technical teams. Mid-scale co-packers in regional United States markets are driving this disintermediation to reduce lifetime service cost exposure on pneumatic cutting tools and conveyor drives. The pattern concentrates where processor capital constraints outweigh vendor relationship premiums.
Poultry Processing Equipment Market Segmentation
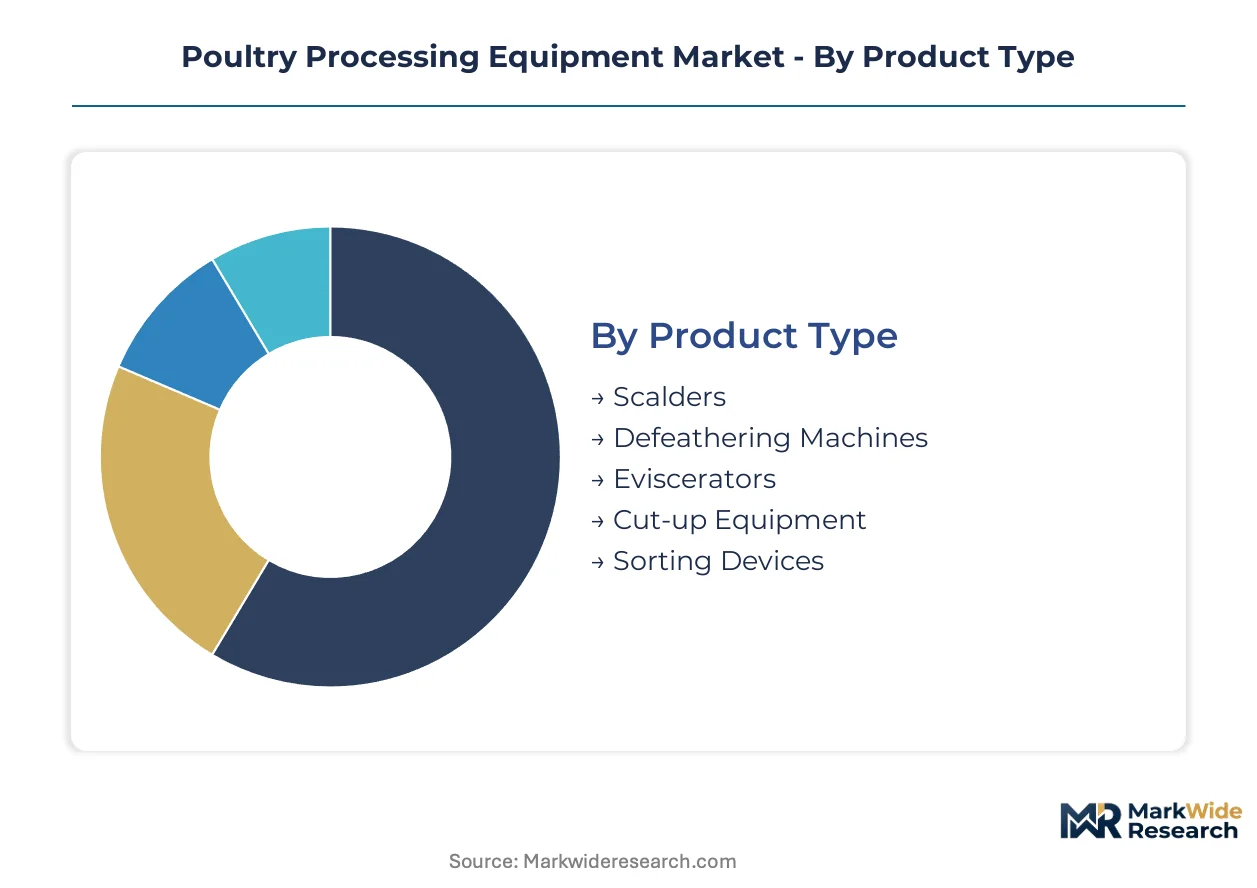
Equipment segmentation in poultry processing reflects divergent capital intensity, labor substitution potential, and regulatory compliance burdens across facility tiers. Procurement committees weight USDA HACCP alignment, EU hygiene directives, and export-equivalency standards when mapping segment investments to operational scale.
Product Type:
Certification requirements concentrate on thermal processing and cut-up equipment where USDA antimicrobial residue protocols and EU open-surface cleanability mandates apply most stringently.
- Scalders:Stainless-steel tank systems control water temperature and dwell time to loosen feather follicles before defeathering. Brazil's export-oriented integrators dominate procurement as ANVISA equivalency standards mandate precise thermal logging for international shipments.
- Defeathering Machines:Rotary rubber-finger plucking drums remove feathers through mechanical abrasion at line speeds up to 140 birds per minute. Mid-scale United States facilities prioritize retrofitting these units with automated clean-in-place architectures to satisfy updated USDA HACCP sanitization protocols without full line replacement.
- Eviscerators:Automated viscera removal systems integrate vacuum extraction and carcass washing stations.
- Cut-up Equipment:Portioning lines separate carcasses into wings, breasts, thighs, and drumsticks through fixed-blade or water-jet configurations.
- Sorting Devices:Vision-based grading modules with hyperspectral imaging capabilities redirect birds into premium or commodity channels.
Cut-up Equipment sits at the top of the volume ranking, with Sorting Devices climbing the fastest.
Technology:
Capital deployment patterns split along labor substitution depth, with fully automated lines commanding integrator budgets while pneumatic tools retain co-packer preference.
- Automated Systems:Integrated software-hardware platforms coordinate stunning through packaging with minimal operator intervention. Quick-service restaurant supply chains in the United States mandate these configurations to meet throughput floors that legacy equipment cannot satisfy.
- Semi-automated Units:Hybrid configurations blend mechanized conveying with manual intervention at evisceration and quality control stations. Regional processors across Brazil select these units to balance capital constraints against volume commitments to export buyers.
- Pneumatic Tools:Handheld cutting instruments powered by compressed air deliver flexibility for mixed-SKU operations.
- Hydraulic Machines:High-force actuation systems drive heavy-duty portioning and deboning operations.
- Conveyor Systems:Stainless-steel belt and chain mechanisms form the physical backbone connecting discrete processing stages.
Automated Systems capture the largest installed base, though Semi-automated Units are gaining share fastest among capital-constrained operators.
Application:
Facility type determines equipment specification intensity, with slaughterhouses facing the broadest regulatory exposure across USDA, FDA, and export-equivalency frameworks.
- Slaughterhouses:Primary processing facilities executing live receipt through chilling, subject to continuous USDA inspection presence and HACCP plan enforcement. Brazil's expanding export capacity drives the steepest investment trajectory as integrators modernize to serve international buyers.
- Meat Processing Plants:Secondary facilities receiving chilled carcasses for portioning, marinating, and further-processing. United States operations concentrate here as quick-service restaurant chains outsource cut-up and formulation to specialized contractors.
- Food Packaging Units:Tertiary operations focused on modified-atmosphere packaging and case-ready retail preparation.
- Quality Inspection Stations:Dedicated grading and contamination detection points integrated into line flow or operated as standalone facilities.
Slaughterhouses lead absolute equipment value, with Quality Inspection Stations expanding most quickly on vision-technology adoption.
End User:
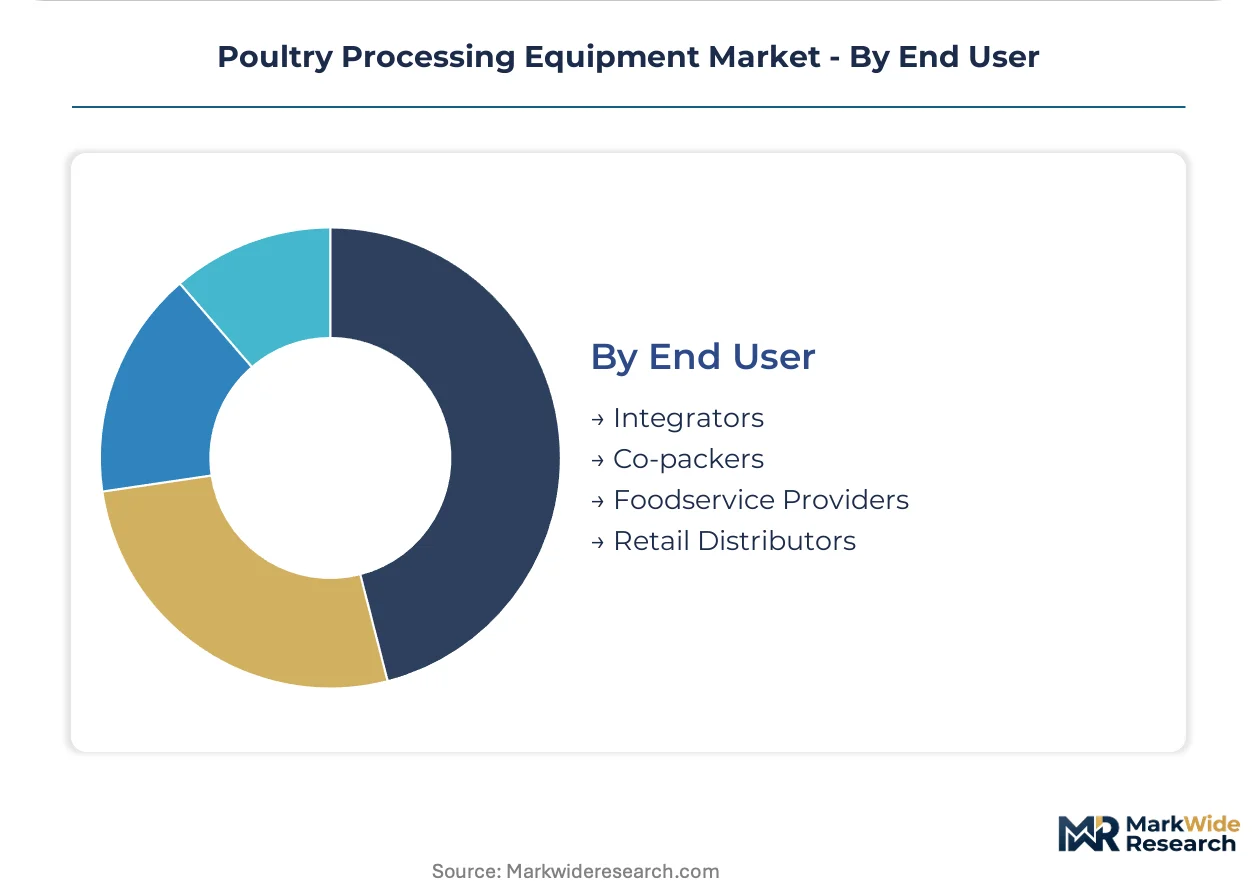
Customer scale and supply chain position reshape procurement priorities, from integrator pursuit of yield optimization to co-packer emphasis on SKU flexibility.
- Integrators:Vertically coordinated operations controlling breeding through retail placement, prioritizing throughput maximization and traceability architecture. United States and Brazilian integrators anchor demand for fully automated lines as they face quick-service restaurant throughput mandates and export-equivalency requirements.
- Co-packers:Contract processors serving multiple brand owners with variable product specifications. These operators favor semi-automated configurations and pneumatic tool flexibility to accommodate rapid changeovers without dedicated line investments.
- Foodservice Providers:Central kitchens and commissaries supplying restaurant chains with portioned protein.
- Retail Distributors:Supermarket chains and club stores operating private-label processing capacity.
Integrators command the dominant share of capital expenditure, while Co-packers are climbing fastest on contract manufacturing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled mechatronics technicians cluster in Germany's industrial belt, Brazil's southern manufacturing corridor, and the United States Midwest, anchoring equipment fabrication and technical service networks across three continents.
United States
Quick-service restaurant chains mandate throughput floors that legacy cut-up lines cannot satisfy, forcing integrators toward full automation retrofits. USDA HACCP sanitization protocols now require automated clean-in-place architectures on scalding and chilling systems. Georgia's poultry processing corridor concentrates modernized slaughterhouse investments serving domestic and export channels.
Brazil
Export-oriented integrators modernize slaughterhouse capacity to meet ANVISA equivalency standards for international buyers. The national agricultural regulator enforces thermal logging and antimicrobial residue controls that shape equipment specifications. São Paulo state's processing belt anchors the steepest capital deployment trajectory in Latin America.
Germany
EU Regulation 853/2004 hygiene amendments mandate open-surface cleanability standards favoring welded stainless-steel frame architectures. CE marking directives govern machinery design standards for European suppliers and export markets. Bavaria's industrial machinery cluster supplies specialized drive motors and pneumatic controls to integrators worldwide.
China
Domestic protein demand expansion drives mid-scale facility construction requiring semi-automated configurations. GB standards and SAMR technical regulations shape local equipment certification pathways. Shandong Province's agricultural machinery manufacturing base scales production for regional integrators and Southeast Asian export markets.
India
Nascent organized processing capacity offers first-mover positioning as FSSAI hygiene standards tighten on commercial operations. The national food safety regulator mandates structural upgrades that displace informal slaughter practices. Maharashtra's emerging poultry integration belt attracts equipment vendors establishing technical service presence.
Poultry Processing Equipment Market Key Industry Players
Top-tier vendors anchor high-throughput integrator accounts, while mid-scale fabricators compete on pneumatic tool flexibility and regional service proximity. The vendor base stratifies across three tiers: integrated software-hardware platforms commanding premium positioning, specialized thermal processing and refrigeration system suppliers bundling with primary lines, and handheld pneumatic tool specialists serving co-packer flexibility requirements. Consolidation pressure intensifies through M&A activity targeting vision-based grading capabilities and strategic partnerships bridging robotics with cold chain infrastructure.
Among European-headquartered conglomerates, GEA Group Aktiengesellschaft exemplifies the thermal processing and refrigeration bundling archetype, while Marel occupies a position representing integrated platform dominance in high-throughput accounts. Bettcher Industries, Inc. sits within the pneumatic tool specialist tier, anchoring mid-scale facility preference for cutting flexibility over full-line automation. These three entities collectively illustrate how competitive positioning fragments across automation depth, thermal system integration, and handheld equipment flexibility.
| Leading Market Players |
|---|
| Baader Global SE |
| Bettcher Industries, Inc. |
| Marel |
| The Middleby Corporation |
| Duravant LLC |
| GEA Group Aktiengesellschaft |
| Provisur Technologies Inc. |
| Hellmann Poultry |
| John Bean Technologies Corporation |
| Others |
Cost & Logistics Intelligence
Skilled mechatronics technicians in Germany's industrial belt anchor labor-cost differentials that widen pricing-tier spreads between premium integrated platforms and economy pneumatic tool configurations, with Brazilian and Chinese manufacturing corridors compressing mid-market equipment quotations.
Pricing Analysis
Bundled after-sales service contracts are unbundling from equipment procurement as buyer committees shift toward third-party maintenance aggregators or in-house technical teams. Three-tier pricing structure across premium, standard, and economy levels separates Marel's integrated software-hardware platforms from GEA's thermal processing bundles and Bettcher's handheld pneumatic tools. Price differentiation rests on automation depth and traceability certification grade, with USDA HACCP-aligned configurations commanding premiums. Cost compression in economy tiers is intensifying because stainless steel input volatility distorts capex quoting timelines. Co-packers exhibit highest price sensitivity; integrators serving quick-service restaurant chains show lowest.
Supply Chain Analysis
Freight cost escalation on specialized drive motors and pneumatic controls from German and Italian suppliers exposes lead-time risk during logistics disruptions. Equipment fabrication draws from stainless steel suppliers in China, precision motor manufacturers in Germany, and rubber-finger component producers in Brazil. Raw material dependencies center on nickel and chromium for tank fabrication, high-grade aluminum for conveyor framing, and specialized polymers for defeathering drums. Single-source vulnerability clusters among European pneumatic control suppliers. Distribution runs through integrator-direct procurement for large accounts and regional distributor networks for mid-scale facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poultry processing equipment margins are expanding through yield-optimization technology premiums that capture value beyond base machinery, with vision-based grading and automated clean-in-place architectures shifting procurement committees toward performance-based contracting.
For Market Incumbents: Lock in integrator accounts by embedding proprietary software-hardware platforms that raise switching costs, while acquiring vision-based grading specialists to preempt competitive encroachment. Threat of emerging robotics-cold chain convergence demands defensive patent positioning. Backward integration into stainless steel component fabrication in Brazil and Germany secures margin against nickel price volatility.
For New Entrants and Emerging Players: Enter via India's nascent organized processing capacity where FSSAI hygiene standard enforcement is displacing informal slaughter practices and first-mover technical service presence can anchor long-term relationships. White-space targets include collaborative robotic deboning cells for meat processing plants and energy-efficient scalding retrofits for EU CSRD compliance. Go-to-market angle: carbon footprint disclosure framework alignment as procurement differentiator.
For Investors and Strategic Acquirers: Thermal processing and refrigeration system suppliers are the most active acquirer category in this space, bundling complementary equipment to capture integrator capital expenditure flows. Long-term viability favors vendors with installed base scale in Brazil and United States export corridors. Acquisition target archetype: vision-based grading technology specialists with hyperspectral imaging IP. Signal to watch: quick-service restaurant chain mandation of traceability-enabling architectures as procurement floor.
| Strategic Initiative | Industry Significance |
|---|---|
| Vision-Based Grading Technology Acquisition | Captures yield optimization value that manual grading cannot replicate for Brazilian integrators. |
| Automated Clean-in-Place Architecture Deployment | Satisfies updated USDA HACCP sanitization mandates without full line replacement for US facilities. |
| India Technical Service Presence Establishment | Positions vendors ahead of FSSAI hygiene standard tightening on commercial operations. |
| EU CSRD-Aligned Energy Retrofit Program | Creates pull for efficient scalding and refrigeration systems among European processors. |
| Collaborative Robotics-Cold Chain Integration | Enables footprint consolidation while expanding SKU flexibility for meat processing plants. |
Research Approach
Bottom-up integrator and co-packer modeling reconciled against top-down equipment supplier production tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation from USDA regulatory filings, ANVISA equivalency standards, EU machinery directive databases, and SEC equipment manufacturer disclosures. Trade flow analysis across Brazilian, US, and German customs records triangulates against supplier shipment disclosures.
Historical trendline analysis of capital expenditure patterns across slaughterhouse, meat processing plant, and quality inspection station categories informs projection modeling. Segmentation dimensions include product type, automation technology tier, facility application, and end-user scale. CAGRs derive from equipment replacement cycle compression rates and export capacity expansion trajectories. Forecast inputs incorporate quick-service restaurant throughput mandates and antimicrobial residue testing protocol updates.
The model holds under continued regulatory enforcement of HACCP and EU hygiene directives; deviation in stainless steel commodity price spikes or logistics disruption severity would shift equipment procurement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Dal Mill Machine Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
North America Feed Pelletizing Agent Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Maize Milling Machine Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Global Nut Processing Equipment Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
India Rice Milling Market
Agricultural Processing Equipment
Egg Processing Machine Market