
 Europe Livestock Monitoring Market | 2026-2036
Europe Livestock Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Livestock Monitoring Market Intelligence
Dairy farmer adoption of automated monitoring systems is expanding across Northern Europe. DeLaval leverages its integrated milking-to-analytics platform to anchor premium positioning in Scandinavian markets. GEA Group sustains R&D intensity in sensor hardware for large-scale cooperative farms. Nedap N.V. specializes in cow identification and estrus detection technology, competing on farm-level data granularity.
Europe livestock monitoring encompasses sensor-based systems that track animal physiology, location, and behavior through wearable accelerometers, rumen boluses, and environmental IoT nodes with sub-meter precision. These technologies serve commercial livestock operations by reducing mortality rates, optimizing feed conversion, and automating labor-intensive health surveillance. Wearable devices and IoT sensors dominate hardware deployment, with RFID tags retaining strongholds in traceability-compliant supply chains. Software platforms and data analytics tools capture expanding margin pools as farms shift from point solutions to integrated herd management dashboards.
The EU Green Deal and Farm to Fork strategy shape product standards through mandatory animal welfare metrics and environmental reporting requirements. EMA guidelines on veterinary data interoperability and national regulators in Germany and France enforce cybersecurity protocols for connected farm equipment. Stakeholders must monitor evolving CE marking criteria for agricultural IoT devices and assess whether cloud service localization mandates fragment cross-border platform economics.
Market Dynamics
The EU Green Deal's Farm to Fork strategy compresses compliance timelines for animal welfare and environmental reporting, forcing dairy cooperatives to accelerate sensor deployment or face market exclusion from premium supply chains.
Growth Catalysts
- CE marking expansion for agricultural IoT:New harmonized standards for wearable livestock devices reduce technical barriers to cross-border sales within the single market, streamlining vendor certification costs.
- Precision dairy operations in the Netherlands:High-density farming clusters generate network effects for data-sharing platforms, lowering per-analytics costs and accelerating peer-to-peer technology diffusion.
- Cloud localization mandates:Germany's BSI IT-Grundschutz requirements and France's ANSSI cloud sovereignty rules create compliant hosting infrastructure that reduces cybersecurity friction for risk-averse cooperative buyers.
Market Restraints
- Semiconductor supply concentration:MEMS accelerometer fabrication concentrates in East Asian foundries, exposing European hardware vendors to lead-time volatility and input cost spikes.
- Legacy farm infrastructure incompatibility:Analog milking parlors built before 2010 lack digital interfaces, forcing costly retrofitting or full-system replacement for sensor integration.
- Substitution by manual veterinary labor:Eastern European dairy operations with lower labor costs retain veterinarian call-out models rather than automated health monitoring, capping addressable market penetration.
Strategic Opportunities
- Poland's underpenetrated beef sector:Cattle finishing operations in Masovia and Podlaskie regions currently deploy minimal wearable technology, presenting first-mover expansion potential for estrus detection vendors.
- CSRD-aligned sustainability reporting:The Corporate Sustainability Reporting Directive mandates Scope 3 agricultural emissions disclosure, creating pull-through demand for methane-monitoring rumen boluses from protein supply chain partners.
- Edge-to-cloud convergence:On-farm edge computing nodes paired with satellite connectivity reduce latency for real-time alerts in remote Scandinavian pastoral zones previously underserved by terrestrial broadband.
Industry Challenges
- Veterinary data science talent scarcity:Farms struggle to recruit analysts capable of interpreting behavioral algorithm outputs and integrating insights into treatment protocols.
- Multi-vendor platform integration complexity:Proprietary data formats from DeLaval, GEA, and Nedap systems resist interoperability, forcing buyers into single-vendor lock-in or expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Livestock Monitoring Market |
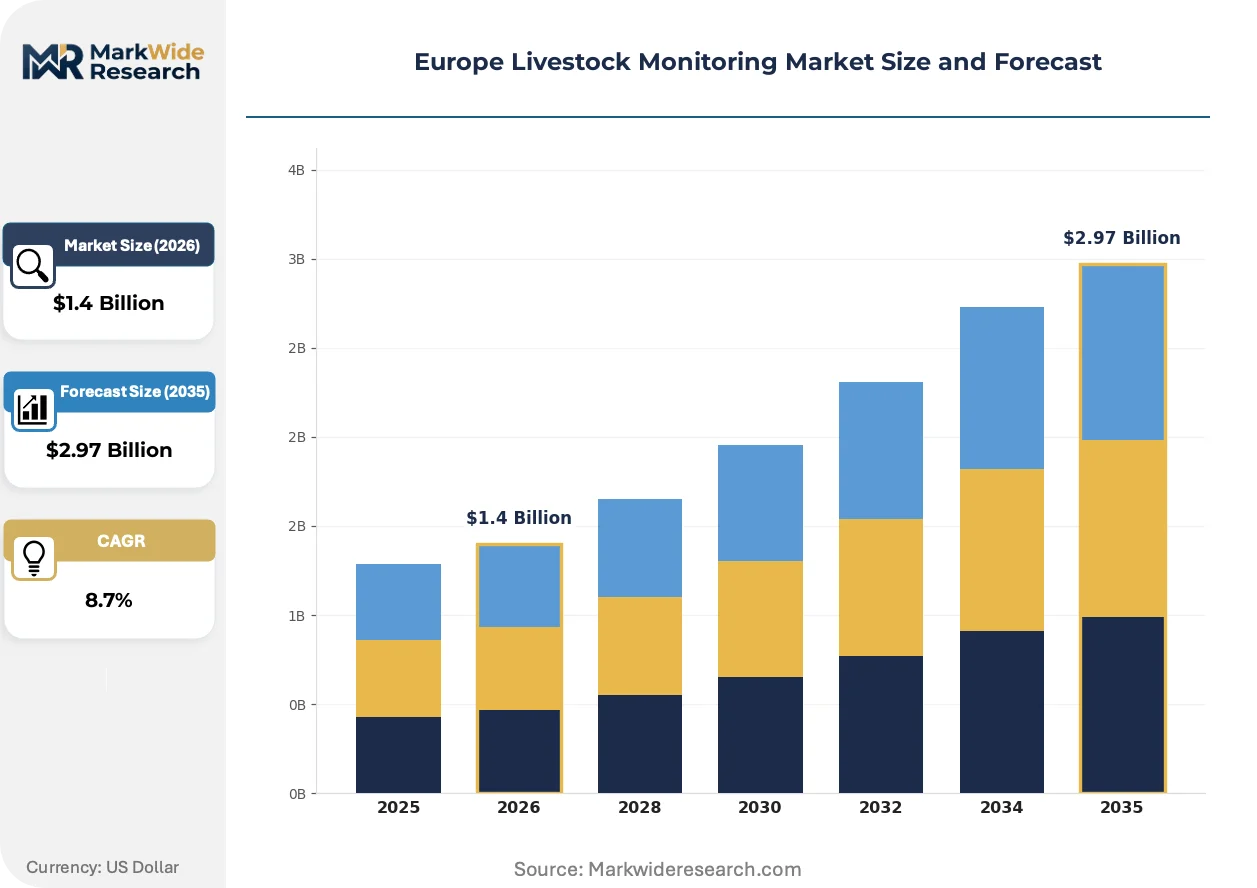
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wearable Devices, RFID Tags, Drones, IoT Sensors Application: Health Monitoring, Feeding Management, Breeding Management, Fertility Monitoring End User: Dairy Farmers, Meat Producers, Cooperative Farms, Veterinary Clinics Solution: Software Platforms, Data Analytics Tools, Cloud Services, Mobile Applications |
| Companies Covered | DeLaval, GEA Group, MSD Animal Health, Afimilk, BouMatic, Nedap N.V., Dairymaster, CowManager, smaXtec animal care GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Livestock Monitoring Market Strategic Shifts & Innovations
Sensor fusion architectures and AI-driven predictive models are compressing the gap between raw data collection and actionable herd management decisions, reshaping how commercial farms justify technology capital expenditure.
Machine learning algorithms processing accelerometer and rumen pH data streams are integrating estrus detection, lameness prediction, and ketosis early-warning into unified health dashboards. Large-scale cooperative farms in Denmark deploy these systems across 500-plus head operations, replacing siloed point solutions with centralized analytics platforms that reduce labor hours per animal.
The EU AI Act's risk classification framework for biometric identification systems imposes conformity assessment obligations on facial recognition and gait analysis tools used for individual animal tracking. Vendors targeting French and German markets must now document algorithmic transparency and bias mitigation measures, extending product development cycles by 12-18 months for computer vision-based monitoring hardware.
Service unbundling disrupts traditional equipment-leasing models as Dutch dairy processors begin procuring monitoring-as-a-service contracts directly, bypassing farm-level capital constraints. FrieslandCampina and Arla Foods now subsidize sensor deployment in exchange for guaranteed supply and verified welfare credentials, concentrating purchasing power upstream and marginalizing independent hardware distributors in the Benelux region.
Europe Livestock Monitoring Market Segmentation
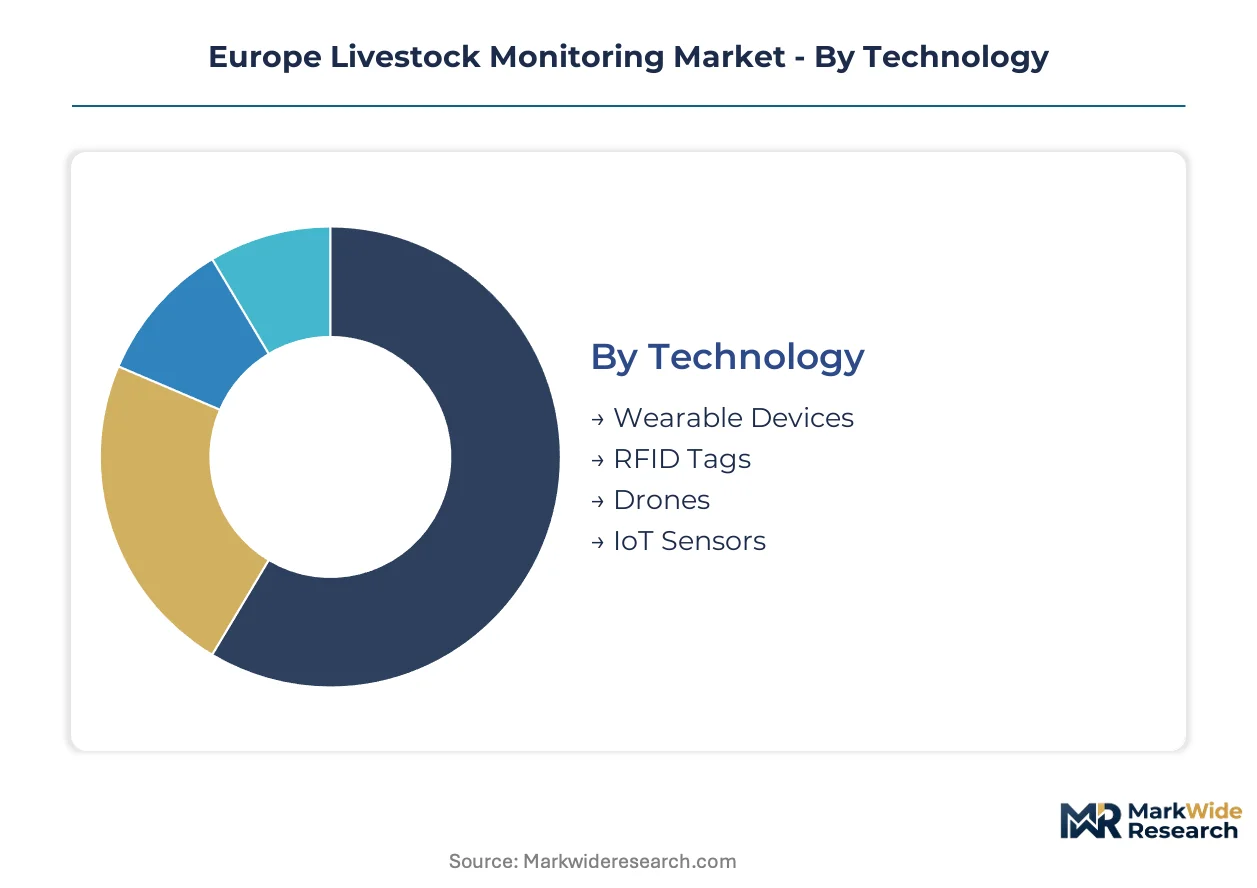
Technology choice determines capital deployment patterns across European livestock operations. Farm scale and regulatory pressure shape which segments absorb investment priority in Germany, France, and the Netherlands.
Technology:
Wearable devices demand the highest upfront capital outlay among hardware categories, followed by drone systems requiring aviation compliance investment.
- Wearable Devices:Collar-mounted accelerometers and ear-tag sensors capture real-time behavioral and physiological data with sub-meter precision. Dairy cooperatives in Denmark and the Netherlands deploy these across 500-plus head operations to automate estrus detection and lameness prediction, driven by EU Green Deal animal welfare compliance timelines.
- IoT Sensors:Environmental monitoring nodes track barn temperature, humidity, and air quality alongside animal-mounted units. German dairy farms prioritize these for automated ventilation control and methane concentration alerts, responding to BSI IT-Grundschutz cybersecurity mandates for connected infrastructure.
- RFID Tags:Passive and active identification systems anchor traceability-compliant supply chains from farm to processor.
- Drones:Aerial platforms monitor pasture utilization and herd location in remote Scandinavian pastoral zones.
Most installed capacity flows through Wearable Devices. Expansion is steepest in IoT Sensors.
Application:
Application focus varies by farm type, with precision dairy operations concentrating investment in fertility-linked functions while meat producers prioritize health surveillance.
- Health Monitoring:Integrated sensor fusion architectures detect ketosis, mastitis, and respiratory distress through rumen pH, temperature, and movement pattern analysis. Large-scale cooperative farms in France deploy these systems to reduce veterinarian call-out frequency and satisfy Farm to Fork strategy welfare documentation requirements.
- Fertility Monitoring:AI-driven algorithms process accelerometer data streams for estrus detection and optimal insemination timing. Dutch dairy processors subsidize deployment through monitoring-as-a-service contracts, bypassing farm-level capital constraints while securing guaranteed supply volumes.
- Feeding Management:Automated ration control systems optimize feed conversion ratios based on individual animal intake monitoring.
- Breeding Management:Genetic selection support tools integrate pedigree data with phenotypic sensor outputs.
Health Monitoring commands the largest installed base. Fertility Monitoring is gaining share fastest.
End User:
End user structure reflects farm scale polarization, with cooperatives driving platform standardization and independent meat producers lagging in sensor adoption.
- Cooperative Farms:Aggregated purchasing power enables centralized analytics platforms across multi-site operations. Danish and Dutch dairy cooperatives negotiate directly with processors for subsidized sensor deployment, concentrating demand and marginalizing independent distributors.
- Dairy Farmers:Individual operations under 200 head face capital constraints and legacy infrastructure incompatibility. German family farms accelerate retrofitting where CE marking expansion for agricultural IoT reduces cross-border equipment sourcing friction.
- Meat Producers:Beef and pork operations in Poland and Eastern Europe retain lower technology penetration due to labor cost advantages.
- Veterinary Clinics:Service providers adopt remote monitoring platforms to extend coverage across dispersed rural client bases.
Cooperative Farms absorb the majority of new installations. Dairy Farmers show the steepest expansion trajectory.
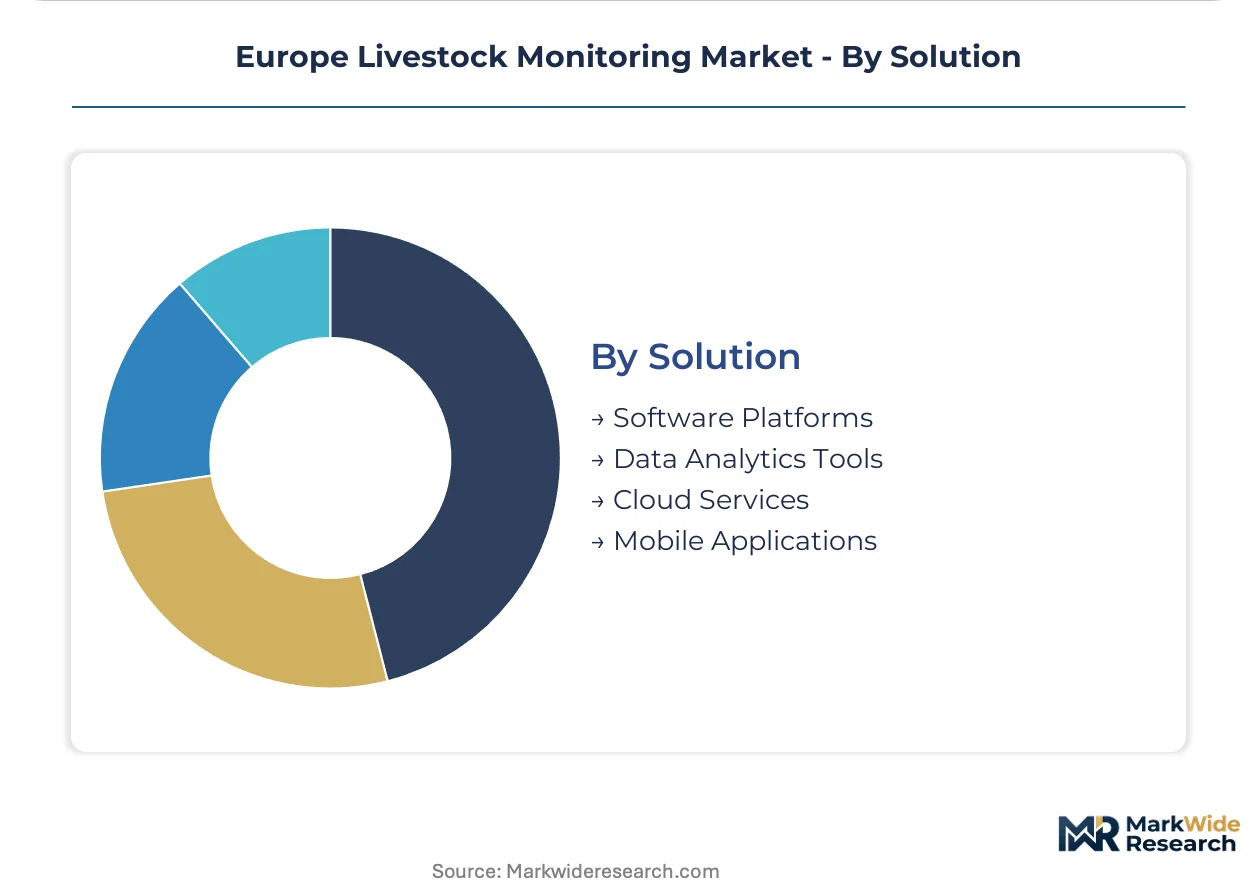
Solution:
Software and service margins expand as farms shift from point hardware purchases to recurring platform subscriptions.
- Software Platforms:Integrated herd management dashboards consolidate data from multiple hardware sources into unified decision interfaces. Vendors compete on interoperability as proprietary formats from DeLaval, GEA, and Nedap systems resist integration, forcing buyers into single-vendor lock-in or expensive middleware development.
- Cloud Services:Data hosting and processing infrastructure localizes to satisfy Germany's BSI requirements and France's ANSSI sovereignty rules. This compliant hosting architecture reduces cybersecurity friction for risk-averse cooperative buyers in Benelux and Scandinavian markets.
- Data Analytics Tools:Behavioral algorithm outputs require specialized veterinary data science talent for protocol integration.
- Mobile Applications:Field-accessible interfaces deliver real-time alerts to farm managers and veterinary staff.
Software Platforms capture the dominant revenue share. Cloud Services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity shifts toward jurisdictions with clearer compliance cost structures as EU Green Deal implementation tightens. Dairy cooperatives migrate sensor procurement to countries with localized cloud infrastructure and streamlined CE marking pathways. This arbitrage concentrates deployment in Northern European markets with mature precision farming ecosystems.
Germany
Precision dairy operations in Lower Saxony and Bavaria drive hardware demand for automated milking-to-analytics platforms. The BSI IT-Grundschutz framework mandates cybersecurity protocols for connected farm equipment, accelerating compliant hosting infrastructure investment. Stuttgart-based agricultural equipment clusters anchor R&D activity in sensor hardware for large-scale cooperative farms.
Netherlands
High-density farming clusters in Friesland and Gelderland generate network effects for data-sharing platforms that lower per-analytics costs. FrieslandCampina and Arla Foods subsidize sensor deployment through monitoring-as-a-service contracts, bypassing farm-level capital constraints. Eindhoven's agritech corridor concentrates edge-to-cloud convergence development for real-time herd management.
Denmark
Cooperative farms deploy centralized analytics platforms across 500-plus head operations to automate estrus detection and lameness prediction. National regulators enforce veterinary data interoperability standards that streamline cross-border platform economics. Copenhagen's precision agriculture research institutes anchor algorithm development for behavioral prediction models.
France
Dairy operations in Brittany and Normandy accelerate retrofitting of legacy milking parlors to meet Farm to Fork strategy welfare documentation requirements. ANSSI cloud sovereignty rules create compliant hosting infrastructure that reduces cybersecurity friction for risk-averse buyers. Lyon-based veterinary technology clusters specialize in rumen bolus development for methane monitoring applications.
Poland
Cattle finishing operations in Masovia and Podlaskie regions present first-mover expansion potential with minimal current wearable technology penetration. Lower labor costs in Eastern European dairy operations sustain manual veterinary call-out models, capping addressable market penetration. Warsaw's emerging agritech sector focuses on cost-optimized sensor hardware for price-sensitive beef producers.
Europe Livestock Monitoring Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors address multi-vendor platform integration complexity. The vendor base clusters around three tiers: integrated equipment manufacturers with milking-to-analytics platforms, specialized sensor hardware developers, and software-centric data analytics providers. Two archetypes anchor competitive positioning: Scandinavian-origin integrated system builders and Benelux-based identification technology specialists. Capacity expansion in edge computing infrastructure and technology licensing for algorithm portability represent the dominant competitive moves.
Within the integrated equipment tier, DeLaval and GEA Group exemplify full-stack platform builders that combine hardware manufacturing with proprietary analytics dashboards. Nedap N.V. occupies a distinct position as a Netherlands-based specialist in cow identification and estrus detection technology, competing on farm-level data granularity rather than equipment integration breadth. These three entities represent divergent strategic postures: equipment-centric vertical integration versus component-level specialization.
| Leading Market Players |
|---|
| DeLaval |
| GEA Group |
| MSD Animal Health |
| Afimilk |
| BouMatic |
| Nedap N.V. |
| Dairymaster |
| CowManager |
| smaXtec animal care GmbH |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's Farm to Fork strategy gates qualified supply and premium-tier pricing access by mandating CE-marked agricultural IoT devices and verified animal welfare credentials. Buyers without compliant sensor hardware face exclusion from FrieslandCampina and Arla Foods procurement networks, compressing margins for uncertified vendors while rewarding integrated platform providers with pricing power.
Pricing Analysis
Distributor margins in Benelux and Scandinavian markets absorb 15-25 point spreads between factory gate and farm-delivered hardware, though direct-to-cooperative contracts bypass this layer entirely. Pricing stratifies across premium, standard, and economy tiers based on algorithm sophistication and cloud localization compliance, with German BSI-certified platforms commanding 40% premiums over non-compliant alternatives. Cost compression in the economy tier intensifies because Warsaw-based sensor assemblers undercut Western European manufacturing, though Danish cooperative buyers show lowest price sensitivity due to processor-subsidized deployment models.
Supply Chain Analysis
Freight costs from East Asian MEMS foundries to Rotterdam and Hamburg anchor landed cost structures for accelerometer-dependent wearable devices, with air freight premiums eroding margins on urgent orders. Component supply concentrates in Taiwan, South Korea, and China for semiconductor fabrication, while final assembly clusters in the Netherlands, Germany, and Poland. Raw material dependencies span lithium-ion cells for collar-mounted units, medical-grade silicone for rumen bolus housings, and rare earth magnets for precision positioning. Single-source vulnerability in 200mm MEMS wafer supply exposes European hardware vendors to lead-time volatility. Distribution runs through agricultural equipment dealerships in France and Germany, direct processor contracts in Denmark and the Netherlands, and emerging e-commerce channels for Polish beef operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a stable compounder where regulatory compliance mandates generate recurring replacement demand and platform stickiness. The EU AI Act's conformity assessment obligations for biometric identification systems extend product development cycles, entrenching incumbents with certified portfolios.
For Market Incumbents: Deploy algorithm portability investments to neutralize multi-vendor platform integration complexity that currently locks buyers into single-vendor relationships. DeLaval and GEA Group should deepen backward integration into edge computing node production to reduce dependency on Taiwanese semiconductor supply. Nedap N.V. must accelerate CE marking pre-certification for next-generation gait analysis tools before EU AI Act enforcement tightens, defending against software-centric entrants with faster compliance pathways. For New Entrants and Emerging Players: Launch via monitoring-as-a-service contracts with Polish beef processors in Masovia and Podlaskie regions, where cattle finishing operations currently deploy minimal wearable technology. Target veterinary clinics as channel partners for remote monitoring platform distribution, exploiting talent scarcity that prevents farms from interpreting behavioral algorithm outputs independently. Price-sensitive meat producers in Eastern Europe represent the most penetrable segment, with cost-optimized rumen bolus hardware avoiding direct competition with integrated dairy platforms. For Investors and Strategic Acquirers: Roll-up economics work for specialized sensor hardware developers because proprietary data formats from DeLaval, GEA, and Nedap systems resist interoperability, creating acquisition value for middleware capabilities that bridge vendor silos. Over a five-to-ten year horizon, platform consolidation around processor-subsidized deployment models concentrates purchasing power upstream and marginalizes independent distributors. The signal to watch is FrieslandCampina and Arla Foods procurement contract terms, as direct sensor subsidies that expand to Eastern European markets would validate geographic expansion thesis for hardware-as-a-service models.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification | EU AI Act compliance for gait analysis tools extends development cycles 12-18 months in French and German markets. |
| Edge Computing Infrastructure | On-farm nodes paired with satellite connectivity reduce latency for Scandinavian pastoral zones underserved by terrestrial broadband. |
| Monitoring-as-a-Service Contracts | Dutch processors subsidize sensor deployment, bypassing farm-level capital constraints while securing guaranteed supply volumes. |
| Algorithm Portability Investment | Middleware development bridges proprietary data formats from DeLaval, GEA, and Nedap systems resisting interoperability. |
| Poland Market Entry | Cattle finishing operations in Masovia and Podlaskie regions present first-mover expansion potential with minimal wearable penetration. |
Research Approach
Direct dialogue with dairy cooperative procurement officers, precision livestock technology R&D directors, veterinary clinic practice managers, and agricultural equipment dealership principals grounded qualitative insights in operational reality. Secondary validation drew from EMA veterinary data interoperability guidelines, BSI IT-Grundschutz cybersecurity frameworks, ANSSI cloud sovereignty documentation, and EU Green Deal Farm to Fork strategy implementation reports. Bottom-up and top-down triangulation cross-referenced hardware shipment data from CE marking registries against processor-subsidized deployment disclosures.
Bottom-up modeling built from individual farm-scale sensor adoption curves, equipment replacement cycles, and cooperative purchasing patterns across Germany, the Netherlands, Denmark, France, and Poland. Segmentation dimensions spanned technology type, application function, farm scale archetype, and solution delivery model. CAGRs were derived from logistic diffusion curves fitted to historical adoption rates and regulatory compliance deadline impacts. Forecast inputs incorporated BSI and ANSSI infrastructure investment timelines, MEMS supply lead-time volatility indices, and veterinary data science labor market tightness.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or accelerated EU AI Act enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Sheep Creep Feeder Market
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Robotics Milking Systems Market
Livestock Equipment
Horse Bunk Feeder Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Nigeria Horse Riding Equipment Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Silage Tube Market
Livestock Equipment
Chicken Coop Market
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Poultry Feeder Market