
 China Horse Riding Equipment Market | 2026-2036
China Horse Riding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
China Horse Riding Equipment Market Insights
GB/T 19851 sports equipment certification is rotating supplier eligibility, forcing smaller workshops to upgrade testing capabilities or exit. Dongguan Shuyu Activewear leverages vertical integration from fabric weaving to finished garment production, sustaining cost advantages against import competition. Quanzhou UBI Garments dominates OEM contracts for European equestrian brands, while Zest Equestrian positions itself through direct-to-consumer channels on domestic platforms.
Horse riding equipment comprises saddles, bridles, reins, and stirrups engineered to rider biomechanics and equine welfare standards, with leather and synthetic fabric variants subjected to tensile strength testing exceeding 500N per GB protocols. The equipment serves competitive sport, recreational riding, and professional training across temperature ranges from minus 15 to 45 degrees Celsius. Saddles capture the largest value pool due to custom fitting requirements and leather craftsmanship premiums, while synthetic fabric materials represent the fastest-growing segment as amateur riders prioritize weather resistance and lower maintenance. Distribution through online retail channels is displacing traditional specialty stores among first-time buyers seeking price transparency.
SAMR enforces product quality law compliance for sports equipment sold domestically, while GB standards administered by the Standardization Administration specify material safety and dimensional tolerances. The CEA's sports industry development guidelines channel subsidies toward equestrian facility construction in second-tier cities. Stakeholders must monitor whether MIIT extends mandatory traceability requirements to riding equipment supply chains.
Market Dynamics
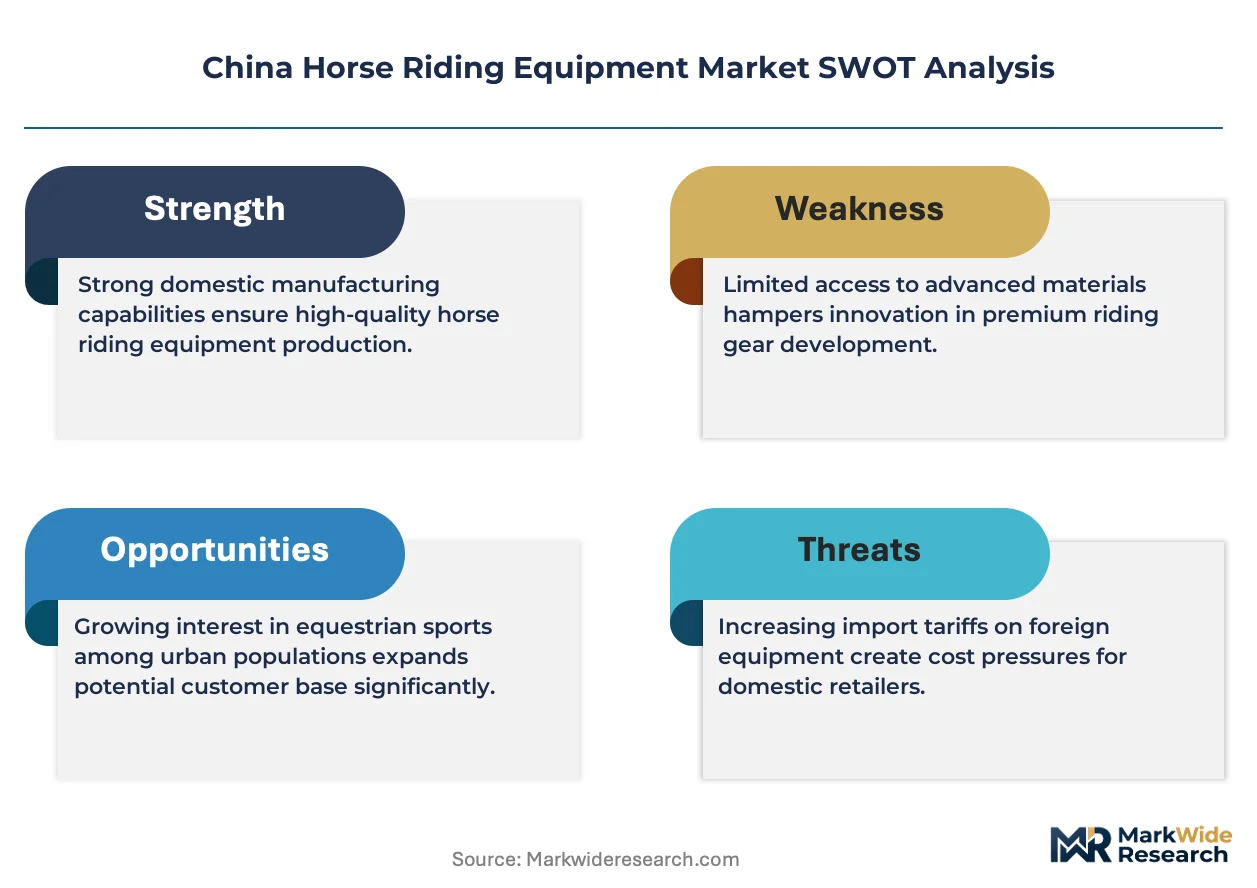
MIIT's GB/T 19851 certification rotation is compressing supplier eligibility, forcing domestic workshops to absorb testing capex or surrender market access to vertically integrated competitors with captive laboratories.
Growth Catalysts
- Leisure equestrian participation:Amateur riders in inland provinces are driving volume expansion beyond traditional coastal enclaves as disposable incomes rise in second-tier cities.
- CEA facility subsidies:The administration's sports industry development guidelines channel construction incentives toward equestrian centers in Chengdu, Wuhan, and Xi'an.
- Synthetic fabric adoption:Weather-resistant polymer composites are capturing preference among first-time buyers seeking lower maintenance burdens versus traditional leather.
Market Restraints
- Leather input volatility:Hide prices fluctuate with Argentine and Australian livestock cycles, compressing margin stability for saddle manufacturers dependent on full-grain materials.
- Guangdong supply concentration:Dongguan and Shenzhen clusters host over sixty percent of domestic production capacity, creating geographic vulnerability to regional logistics disruptions.
- GB testing timeline friction:SAMR's product quality law enforcement extends certification cycles by four to eight weeks versus pre-2023 baselines.
Strategic Opportunities
- Inland province penetration:Henan and Shaanxi provinces exhibit underpenetrated rider density relative to facility investment flows, presenting whitespace for equipment distribution.
- Direct-to-consumer platforms:Tmall and Douyin storefronts are displacing traditional specialty store networks among digital-native amateur segments.
- Dual carbon alignment:MEE's environmental compliance trajectory favors water-based tanning processes and recycled polymer feedstocks for synthetic lines.
Industry Challenges
- Master craftsman scarcity:Saddle tree shaping and leather hand-stitching skills concentrate among aging artisans in Guangdong, constraining custom production scaling.
- Traceability system integration:MIIT's prospective mandatory supply chain tracking requirements would force ERP upgrades across tier-two and tier-three component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Horse Riding Equipment Market |
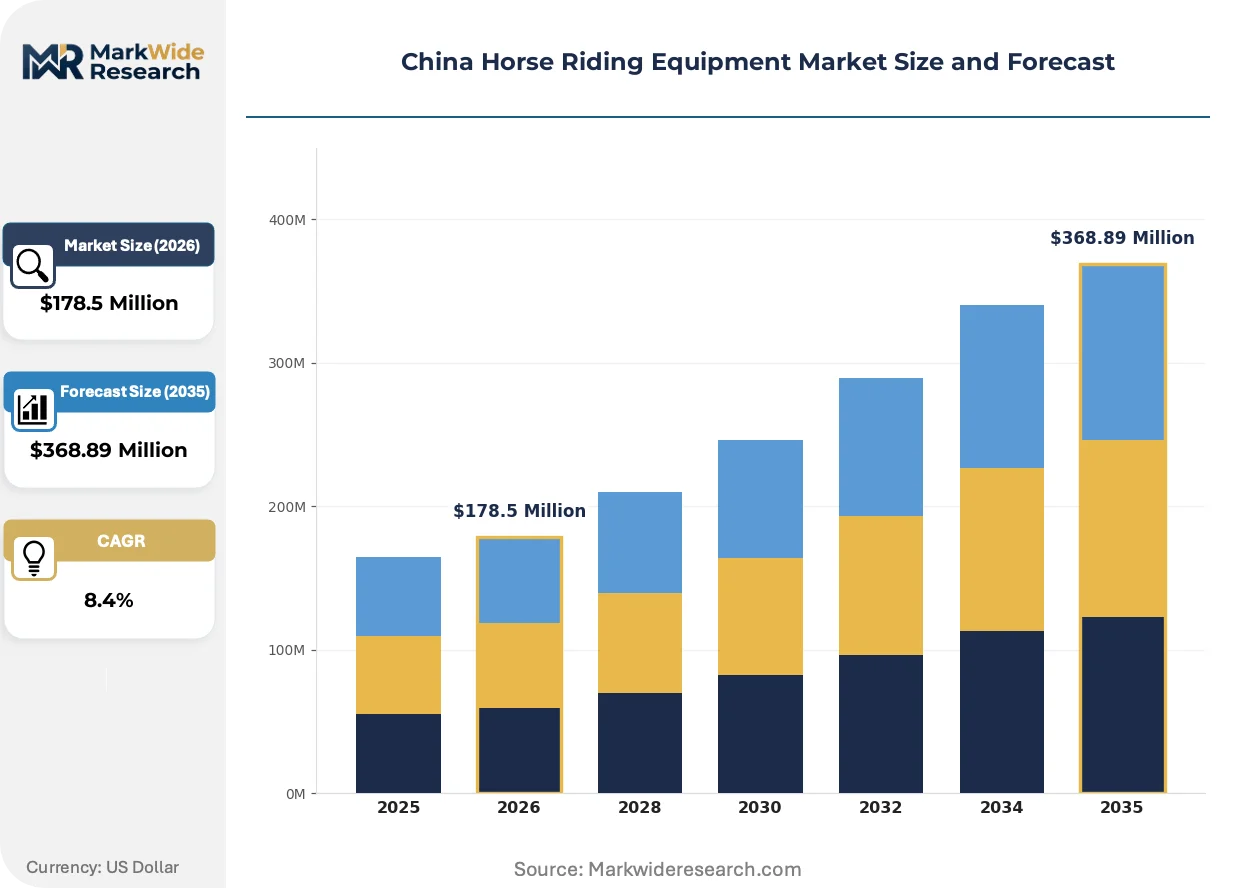
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $368.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saddles, Bridles, Reins, Stirrups End User: Amateur Riders, Professional Riders, Equestrian Centers, Trainers Material: Leather, Synthetic Fabrics, Nylon, Rubber Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Shops, Trade Shows |
| Companies Covered | Dongguan Shuyu Activewear Co., Ltd., Quanzhou UBI Garments Co., Ltd., Dongguan SGL Sports, Shenzhen MaRainbow Clothing Co., Ltd., Zest Equestrian, Equifactory, Dongguan Tianchen Garment Technology Co., Ltd., ChinaJumps, Guangzhou New Apparel Trade Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Horse Riding Equipment Market Trends and Innovations
Synthetic materials and digital distribution channels are compressing traditional leather craftsmanship premiums while regulatory compliance costs reshape competitive viability across the supplier base.
Advanced polymer saddle trees reinforced with carbon fiber composites are displacing traditional wood and fiberglass constructions in mid-market segments. Amateur riders purchasing through online channels prioritize weight reduction and climate stability over heritage leather aesthetics. This material shift is displacing artisan-dependent production models that required months-long fitting cycles.
MIIT's updated GB standards for sports equipment safety are elevating tensile strength thresholds above 500N for all load-bearing components. Domestic manufacturers must recalibrate material specifications and testing protocols to maintain market access. The certification burden falls heaviest on small workshops lacking in-house metallurgy and polymer laboratories.
First-time buyers are bypassing specialty equestrian retailers in favor of platform-based price discovery and peer review aggregation. Tmall's live-streaming commerce format enables real-time product demonstration for technical equipment like adjustable girth systems. This channel migration concentrates in Guangdong and Zhejiang provinces where digital payment penetration and logistics density enable same-day fulfillment.
China Horse Riding Equipment Market Segmentation
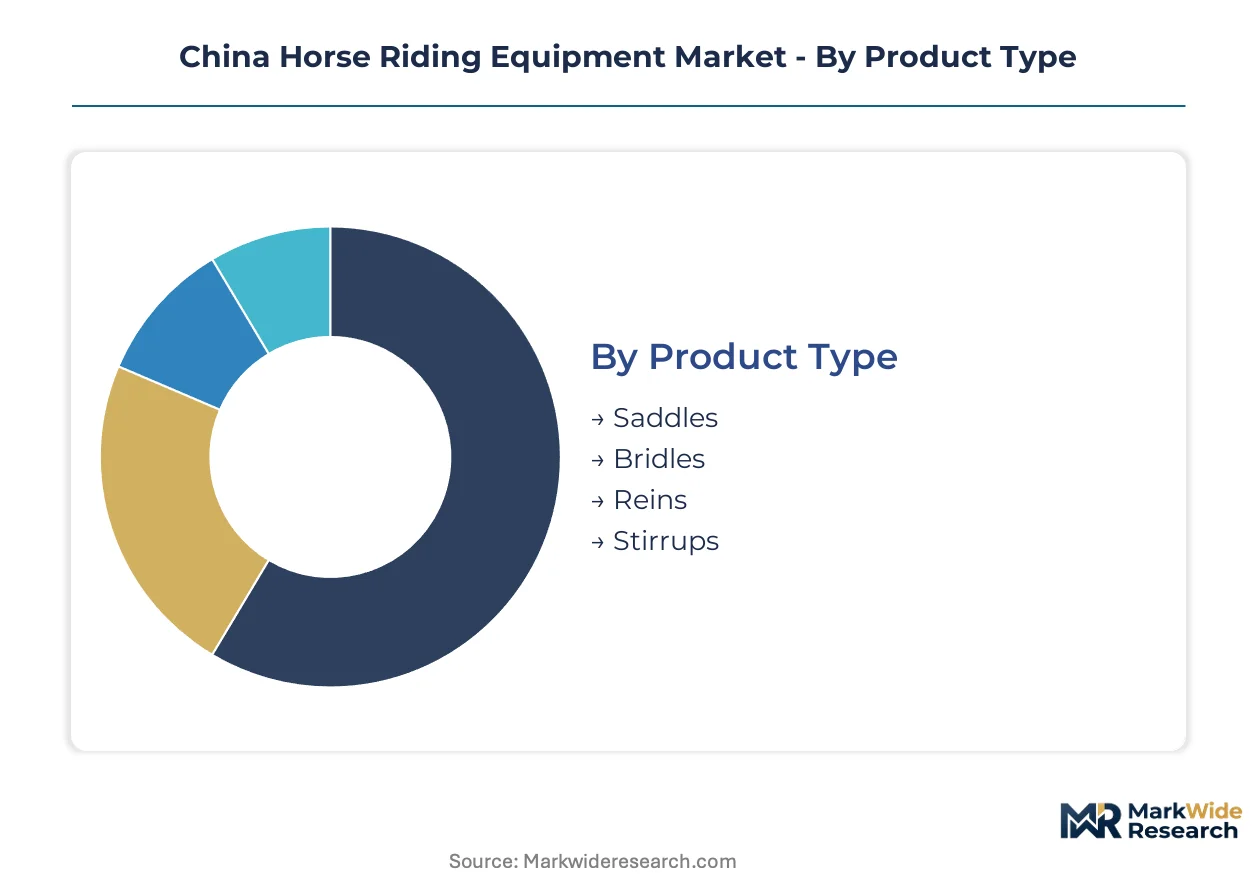
Equipment segmentation in China reveals divergent supply chain configurations across product categories. Domestic manufacturing clusters in Guangdong dominate leather-intensive segments while synthetic material lines increasingly serve export markets.
Product Type:
Domestic consumption concentrates in saddles and bridles where craftsmanship premiums sustain local production, whereas reins and stirrups face heavier import competition from Southeast Asian suppliers.
- Saddles:Custom-fitted leather or polymer tree constructions requiring biomechanical calibration to rider weight and equine back conformation. Demand clusters in Guangdong province where Dongguan workshops maintain captive tanning and stitching operations, though MIIT's GB/T 19851 certification timeline compresses margin recovery for small ateliers.
- Bridles:Headstall and bit assemblies combining leather cheekpieces with stainless steel hardware, subject to 500N tensile testing under updated GB protocols. Professional training centers in Chengdu and Wuhan drive specification-grade procurement as CEA facility subsidies expand inland equestrian infrastructure.
- Reins:Length-adjustable straps connecting bit to rider hand position, manufactured in webbing or rubberized grip variants. Quanzhou OEM producers supply European brand contracts with shorter certification cycles than domestic market entry requires.
- Stirrups:Foot support irons in aluminum alloy or polymer composites, standardized across price tiers with minimal customization. Mass production concentrates in Shenzhen electronics-adjacent metalworking clusters leveraging precision casting capabilities.
Saddles hold the largest share; momentum sits with stirrups as synthetic materials displace artisan-dependent production models.
End User:
Cost tier stratification separates premium professional equipment from volume amateur lines, with certification grade rather than feature count driving price differentiation.
- Amateur Riders:First-time participants in leisure equestrian programs across second-tier cities, prioritizing weather-resistant synthetics and platform-discovered pricing. Henan and Shaanxi provinces exhibit rider density growth outpacing equipment distribution infrastructure.
- Professional Riders:Competitive athletes requiring Fédération Equestre Internationale-compliant gear with documented material traceability. Guangdong-based suppliers with captive laboratories capture specification contracts despite higher unit costs.
- Equestrian Centers:Facility operators procuring durable equipment for rental fleets and lesson programs. CEA construction subsidies in Chengdu, Wuhan, and Xi'an concentrate institutional demand in central China.
- Trainers:Independent instructors selecting adjustable equipment accommodating multiple client body types. Direct-to-consumer platform purchasing displaces traditional wholesale relationships for this segment.
Amateur riders command volume leadership; professional riders maintain margin concentration through certification premiums.
Material:
Supply concentration in tanning and polymer feedstocks shapes regional production advantage, with environmental compliance trajectories favoring water-based processes.
- Leather:Full-grain hides from Argentine and Australian livestock cycles, processed in Guangdong tanneries facing MEE wastewater discharge scrutiny. Saddle manufacturers absorb input volatility through long-term hide purchasing contracts.
- Synthetic Fabrics:Weather-resistant polymer composites capturing preference among digital-native amateurs seeking reduced maintenance. Dongguan Shuyu Activewear's vertical fabric-to-garment integration sustains cost advantage against import competition.
- Nylon:High-tenacity webbing for reins and girth straps, sourced from domestic petrochemical supply chains with shorter lead times than leather alternatives.
- Rubber:Grip-enhanced compounds for rein handles and stirrup treads, manufactured in standard formulations with minimal customization requirements.
Leather retains value pool dominance; synthetic fabrics are climbing the fastest as amateur participation expands beyond coastal enclaves.
Distribution Channel:
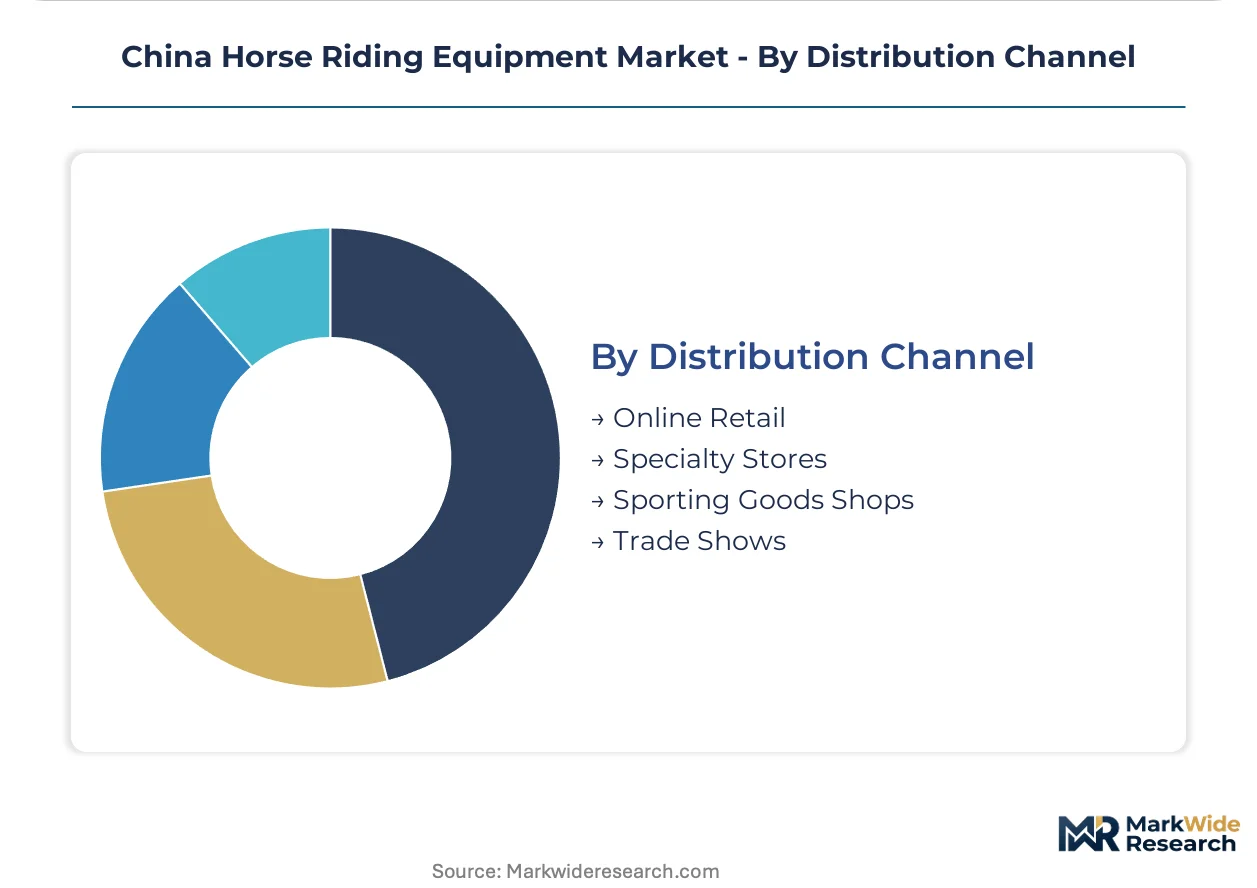
Channel migration accelerates where logistics density enables same-day fulfillment, compressing traditional specialty retail networks.
- Online Retail:Tmall and Douyin storefronts with live-streaming product demonstration for technical equipment like adjustable girth systems. Zest Equestrian positions through direct-to-consumer channels capturing price-transparent first-time buyers.
- Specialty Stores:Physical fitting services for custom saddles requiring biomechanical assessment. Aging master craftsman scarcity in Guangdong constrains scalable service delivery.
- Sporting Goods Shops:Generalist retailers stocking entry-level equipment for casual participants, limited by inventory carrying costs for low-turnover equestrian SKUs.
- Trade Shows:Annual exhibition circuits in Beijing and Shanghai for B2B procurement between OEM manufacturers and European brand licensors. Quanzhou UBI Garments dominates contract acquisition at these venues.
Online retail holds transaction volume leadership; specialty stores defend margin through irreplaceable fitting services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA facility subsidies channel construction incentives toward equestrian centers in Chengdu, Wuhan, and Xi'an, accelerating equipment procurement across central China provinces. Guangdong's manufacturing clusters retain supply dominance while inland markets exhibit underpenetrated rider density.
Guangdong Province
Dongguan and Shenzhen clusters host over sixty percent of domestic production capacity, concentrating leather tanning and synthetic fabric weaving operations. MIIT's GB/T 19851 certification rotation compresses margin recovery for small ateliers lacking captive laboratories. Dongguan Shuyu Activewear leverages vertical integration from fabric weaving to finished garment production, sustaining cost advantages against import competition.
Sichuan Province
Chengdu's equestrian infrastructure expansion under CEA sports industry guidelines drives specification-grade bridle and saddle procurement. Professional training centers prioritize Fédération Equestre Internationale-compliant gear with documented material traceability. Local distribution networks remain underdeveloped relative to facility investment flows, creating whitespace for equipment suppliers.
Hubei Province
Wuhan's emerging equestrian centers attract amateur rider participation as disposable incomes rise in second-tier cities. SAMR product quality law enforcement extends certification cycles, favoring suppliers with established testing protocols. Henan province exhibits rider density growth outpacing equipment distribution infrastructure, presenting expansion opportunities.
Shaanxi Province
Xi'an's CEA-subsidized facility construction concentrates institutional demand for durable rental fleet equipment. Amateur riders in inland provinces prioritize weather-resistant synthetics over traditional leather craftsmanship. Regional logistics networks enable platform-based purchasing through Tmall and Douyin storefronts, displacing traditional specialty retail.
Zhejiang Province
Digital payment penetration and logistics density in Hangzhou and Ningbo enable same-day fulfillment for online retail channels. First-time buyers bypass specialty equestrian retailers in favor of platform-discovered pricing and peer review aggregation. Synthetic fabric lines increasingly serve domestic consumption as leather input volatility compresses margin stability.
China Horse Riding Equipment Market Competitive Landscape
Player mix skews toward vertically integrated fabricators with captive laboratory capabilities and OEM contract manufacturers serving European brand licensors. Market structure exhibits tiered concentration around certification-compliant suppliers and cost-optimized synthetic specialists. Strategic archetypes include: vertically integrated activewear producers controlling fabric-to-garment workflows; OEM contractors dominating European brand relationships; and direct-to-consumer platform operators capturing digital-native amateur segments. Dominant competitive moves encompass backward integration into polymer feedstock and tanning operations, plus channel expansion through live-streaming commerce formats.
Within the vertically integrated tier, Dongguan Shuyu Activewear Co., Ltd. exemplifies cost leadership through captive supply chain control. Quanzhou UBI Garments Co., Ltd. occupies a position representing OEM contract concentration for European equestrian brands. Zest Equestrian anchors the direct-to-consumer archetype through platform-based positioning on domestic retail channels. These three company structures illustrate the competitive divergence between manufacturing-scale efficiency and brand-direct customer acquisition.
| Leading Market Players |
|---|
| Dongguan Shuyu Activewear Co., Ltd. |
| Quanzhou UBI Garments Co., Ltd. |
| Dongguan SGL Sports |
| Shenzhen MaRainbow Clothing Co., Ltd. |
| Zest Equestrian |
| Equifactory |
| Dongguan Tianchen Garment Technology Co., Ltd. |
| ChinaJumps |
| Guangzhou New Apparel Trade Company Limited |
| Others |
Pricing and Supply Chain Analysis
Synthetic polymer composites displacing full-grain leather in amateur saddlery are redrawing procurement geography toward Guangdong's petrochemical corridors while collapsing traditional craftsmanship premiums that once anchored three-tier pricing structures.
Pricing Analysis
Cost-plus contracts with Argentine and Australian hide price indexation dominate leather saddle procurement, though certification grade under GB/T 19851 now outweighs material quality as the primary price differentiation driver. Pricing pressure intensifies in the standard tier as vertically integrated fabricators absorb testing capex that smaller ateliers cannot shoulder. Amateur riders purchasing through Tmall and Douyin exhibit highest price sensitivity, while professional training centers accepting FEI-compliant gear show lowest sensitivity due to documented traceability requirements.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Dongguan synthetic fabric weavers serving domestic platform retailers, whereas leather saddle manufacturers maintain strategic hide stockpiles to buffer Argentine livestock cycle volatility. Supply concentrates in China, with secondary tanning operations in Vietnam and component metalworking in Taiwan. The chain rests on full-grain hides, carbon fiber composites, and high-tenacity nylon webbing. Single-source vulnerability concentrates in Guangdong's captive laboratory infrastructure for GB certification. Distribution runs through Tmall flagship stores, Douyin live-streaming storefronts, and residual specialty equestrian retailers in Chengdu and Beijing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where Douyin's live-streaming commerce infrastructure and Tmall's same-day fulfillment networks are displacing specialty retail intermediaries, compressing margin capture toward vertically integrated manufacturers with direct consumer access.
For Market Incumbents: Compound certification compliance advantages by extending captive laboratory services to tier-two component suppliers, locking in supply chain control before MIIT mandates traceability ERP upgrades. Absorb strategic hide inventories through long-term Argentine purchasing contracts to buffer input volatility that synthetic competitors exploit. Channel defense requires preemptive platform storefront expansion before amateur rider acquisition costs escalate.
For New Entrants and Emerging Players: Lead with weather-resistant synthetic lines targeting Henan and Shaanxi provinces where rider density growth outpaces equipment distribution infrastructure. Capture whitespace in inland equestrian center procurement by offering CEA facility subsidy-aligned rental fleet packages with durability guarantees. Deploy direct-to-consumer positioning through Douyin live-streaming demonstration formats that bypass incumbent wholesale relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated fabricators with captive laboratory capabilities and platform-native customer acquisition infrastructure. Long-term viability over the coming decade hinges on backward integration into polymer feedstock or tanning operations that insulate margin from input volatility. Watch for MIIT's prospective mandatory traceability requirements as the inflection signal that would accelerate ERP upgrade capex burdens across fragmented tier-two suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Dongguan fabricators secure cost advantage against import competition through captive synthetic material supply. |
| GB/T 19851 Certification Investment | MIIT's rotating standards elevate laboratory infrastructure as competitive moat excluding smaller workshops. |
| Direct-to-Consumer Platform Launch | Tmall and Douyin storefronts capture price-transparent amateur riders bypassing specialty retail. |
| Inland Distribution Network Expansion | Henan and Shaanxi whitespace exploitation aligns with CEA facility subsidy flows into central China. |
| Water-Based Tanning Process Transition | MEE environmental compliance trajectory favors sustainable leather processing capturing dual carbon alignment premiums. |
Research Methodology
Operator-level perspectives from equestrian center procurement managers, saddle workshop production heads, platform retail category buyers, and CEA facility development officers anchored the qualitative base. Primary fieldwork combined with secondary validation through SAMR product quality law enforcement records, MIIT GB standards documentation, CEA sports industry guideline publications, and provincial customs export data. Bottom-up equipment shipment analysis triangulated against top-down provincial disposable income and facility construction permit aggregates.
Sensitivity analysis tested forecast robustness across leather input volatility scenarios, certification timeline compression assumptions, and platform channel penetration rates. Segmentation modeling spanned product type, end user archetype, material composition, and distribution channel across the projection horizon. CAGRs derived from equipment replacement cycle analysis, rider population growth trajectories, and synthetic material substitution elasticity estimates. Industry-specific inputs incorporated FEI compliance documentation requirements and MEE wastewater discharge trajectory assumptions.
The analysis sits within stated boundaries; outcomes outside sustained CEA subsidy flows, stable Argentine hide supply, or continued platform logistics density expansion would require recalibration. Forecasts reflect documented assumptions regarding amateur participation growth and certification compliance cost absorption capacity. Revision becomes warranted when MIIT traceability mandates or MEE environmental enforcement intensity crosses thresholds that fundamentally reshape supplier viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Cattle Feeder Panels Market
Livestock Equipment
Milking Equipment Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Automated Feeding System Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Nigeria Horse Riding Equipment Market
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Chicken Coop Market
Livestock Equipment
Animal Cage Market