
 Silage Tube Market | 2026-2036
Silage Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Silage Tube Market Intelligence
Skilled polymer processing labor is reorganizing competitive dynamics across the silage tube supply chain as extrusion and multi-layer coextrusion expertise becomes scarcer in European manufacturing clusters. RKW Group leverages captive film production capabilities across German facilities to sustain margin control from resin through finished tube. Silo Bags International Limited anchors its position through specialized seven-layer barrier film formulations that dominate high-moisture forage applications in Ireland and the United Kingdom. Ipesa - Rio Chico S.A. competes aggressively on agricultural retailer channel density across Argentina's Pampas, where brand recognition among cattle ranchers runs deep.
A silage tube is a cylindrical, flexible storage vessel manufactured from polyethylene, polypropylene, or multi-layer coextruded films, typically 60 to 120 microns thick, designed to exclude oxygen and create anaerobic conditions for fermenting chopped forage crops. The tube's primary purpose is to preserve nutritional value in grass, maize, or legume silage while minimizing dry matter losses during outdoor storage periods. Multi-layer films command the strongest margin pools due to their oxygen barrier properties and extended storage durability under variable climatic stress. Dairy farming applications generate the most concentrated demand volume, though biodegradable films represent the fastest-expanding product category as organic certification requirements tighten across European dairy supply chains.
REACH compliance and the EU F-Gas Regulation shape material selection and additive formulations for silage tubes sold across European member states, while Germany's KBA-equivalent agricultural equipment standards influence load-bearing and UV-stability specifications. France's ANSM-aligned feed safety oversight extends to storage vessel integrity requirements that protect against mycotoxin contamination pathways. Stakeholders must monitor evolving biodegradability certification thresholds under the EU Green Deal's agricultural plastics framework, as these standards will determine which film technologies retain market access across core dairy-producing regions.
Market Dynamics
EU Green Deal methane reduction mandates are compressing demand toward sealed anaerobic storage systems, while polymer processing labor scarcity in European manufacturing clusters is reorganizing competitive positioning across the supply chain.
Growth Catalysts
- EU F-Gas Regulation:Stringent fluorinated gas controls are accelerating farmer migration from bunker silos to tube-based storage systems that eliminate fermentation gas leakage.
- Multi-layer coextrusion:Seven-layer barrier films with oxygen transmission rates below 5 cm³/m²/day are extending storage windows for high-moisture forage in Ireland and the United Kingdom.
- Bavaria's dairy belt:Cooperative procurement consortia across southern Germany are consolidating order volumes and standardizing specifications for UV-stabilized tube formats.
Market Restraints
- Polyethylene resin volatility:Ethylene feedstock price swings tied to naphtha cracking economics compress margin predictability for extrusion-dependent manufacturers.
- German polymer processing labor:Skilled coextrusion technician shortages in Baden-Württemberg and North Rhine-Westphalia constrain capacity expansion for precision film production.
- Bunker silo substitution:Concrete clamp storage retains cost advantage for large-scale operations with permanent infrastructure, limiting tube penetration among industrial dairies.
Strategic Opportunities
- Biodegradable film certification:EU Green Deal agricultural plastics framework creates first-mover advantage for compostable tube formulations meeting EN 13432 biodegradability thresholds.
- Argentina's Pampas:Underpenetrated cattle ranching regions outside Buenos Aires province present volume expansion potential through agricultural retailer channel density.
- Organic dairy supply chains:Certification-driven demand for petroleum-free storage solutions is opening premium positioning for polylactic acid and starch-based barrier films.
Industry Challenges
- REACH additive compliance:Re-registration timelines for UV stabilizers and slip agents create formulation uncertainty and supply discontinuity risks.
- Seven-layer extrusion expertise:Thin-film coextrusion operator training cycles extend 18-24 months, constraining workforce scalability for barrier film production ramps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silage Tube Market |
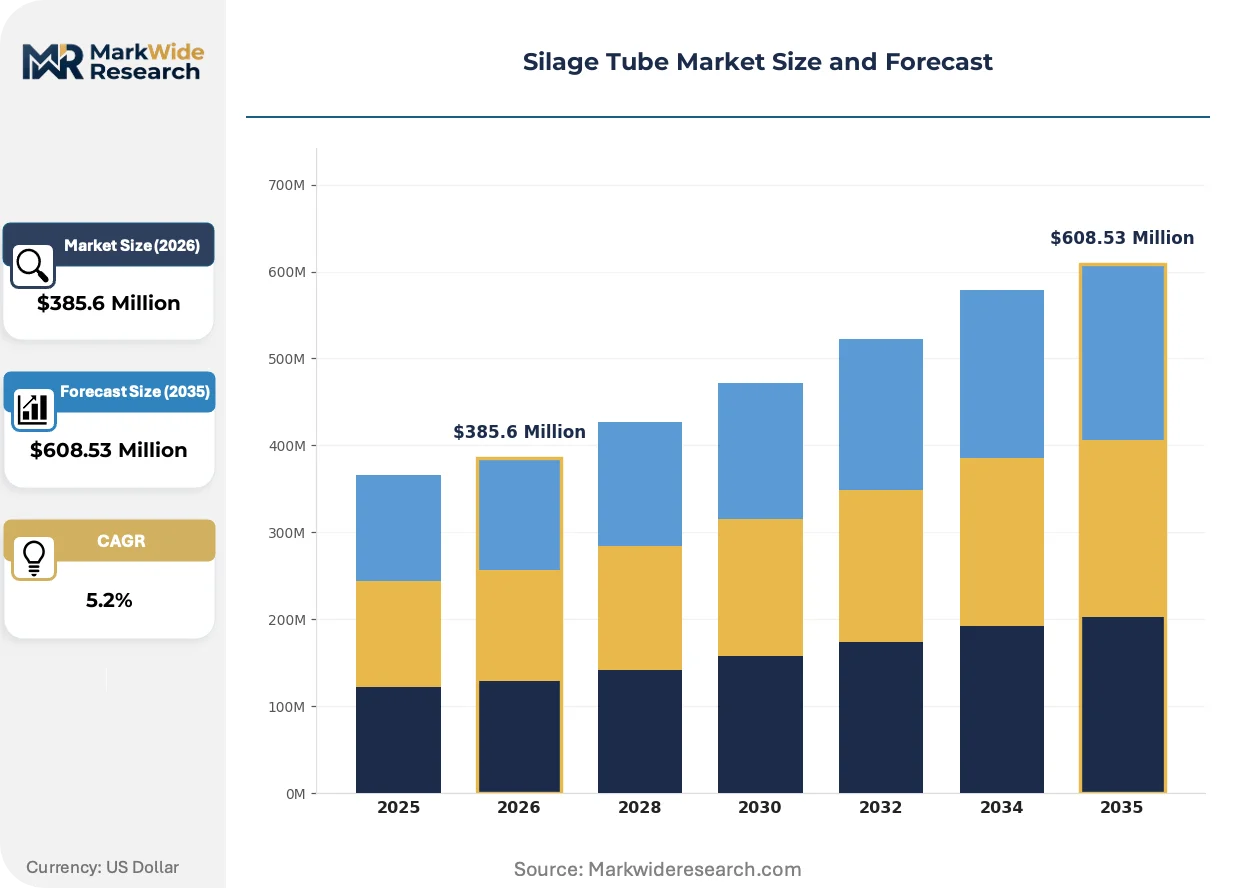
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $608.53 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Multi-layer Films, Biodegradable Films Application: Livestock Feed Storage, Agricultural Byproduct Storage, Dairy Farming, Poultry Feed, Fish Farming Storage End User: Farmers, Agricultural Cooperatives, Feed Manufacturers, Ranch Operators, Organic Farms Distribution Channel: Direct Sales, Agricultural Retailers, Online Marketplaces, Wholesale Distributors, Equipment Dealers |
| Companies Covered | Silo Bags International Limited, Grain Bags Canada, Silo Bags India, Ipesa - Rio Chico S.A., The Panama Group, Flex Pack, Silo Bag Grain, Hellagro S.A., RKW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silage Tube Market Strategic Shifts & Innovations
Material science advances and regulatory compliance architectures are actively restructuring product development priorities across silage tube manufacturing.
Barrier film technology is bifurcating between conventional polyethylene multi-layer constructions and emerging bio-based alternatives with comparable oxygen exclusion performance. Organic-certified dairy operations in Denmark and the Netherlands are piloting polylactic acid-starch composite tubes at 15-20% cost premiums. This technology split is compressing R&D resource allocation and forcing parallel qualification tracks for resin suppliers.
REACH compliance documentation requirements are extending additive approval cycles and restricting formulation flexibility for UV stabilizers and anti-block agents. ECHA substance evaluation workflows now demand full supply chain transparency for silage contact materials. German compounders are responding by consolidating additive portfolios around pre-approved substance lists, reducing formulation customization for regional climatic conditions.
Retailer-led specification consolidation is displacing farm-level procurement autonomy across European dairy cooperatives. Agricultural supply chains in France and Belgium are shifting toward centralized tube procurement with standardized diameter and thickness requirements. This behavioral pivot concentrates negotiating leverage with distributors and compresses manufacturer margin pools for customized product lines.
Silage Tube Market Segmentation
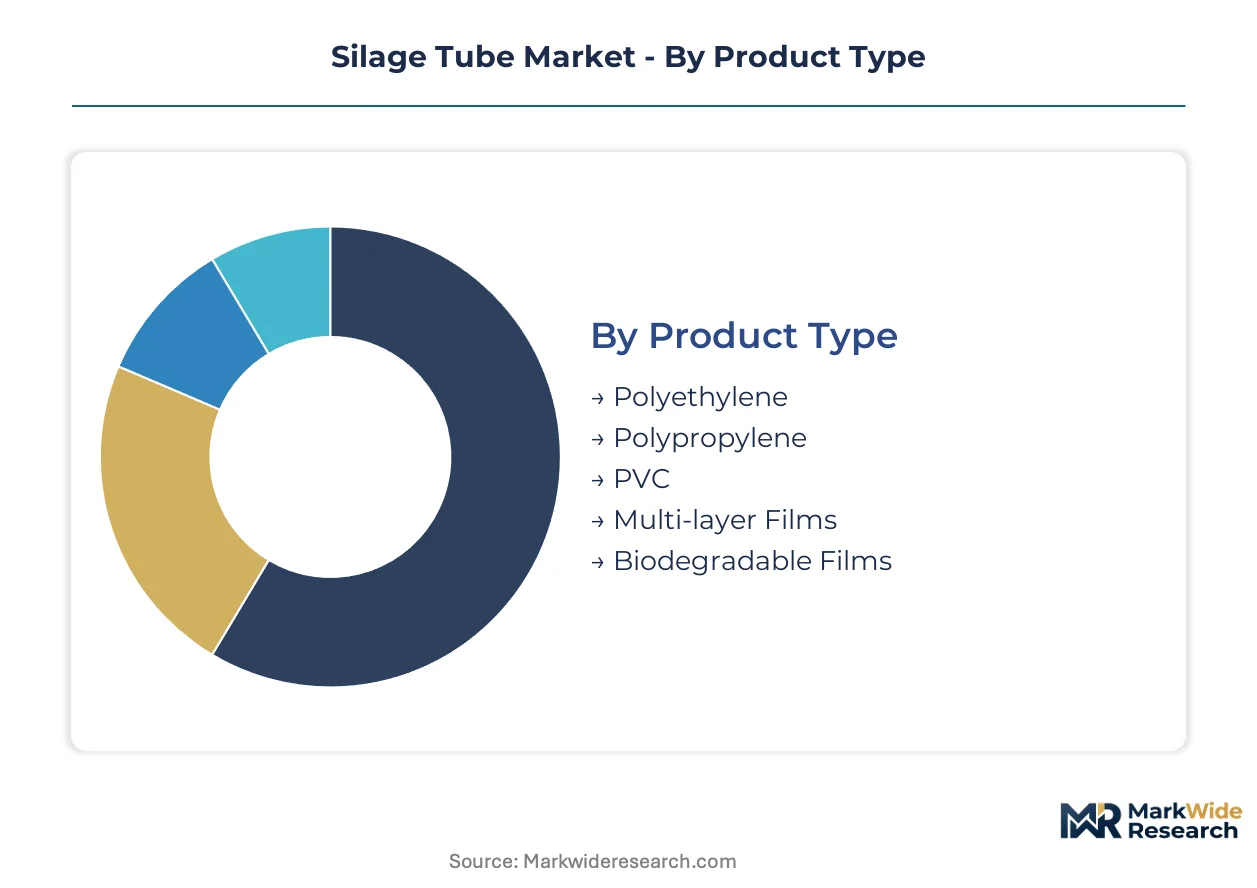
Silage tube segmentation reveals how material chemistry, farm operational scale, and channel structure fragment demand across European dairy belts and export-oriented agricultural economies. Understanding these divides exposes where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Domestic European consumption clusters around multi-layer and biodegradable formulations driven by REACH compliance and organic certification requirements, while polyethylene and polypropylene tubes dominate export volumes to price-sensitive agricultural markets in South America and Eastern Europe.
- Multi-layer Films:Seven-layer coextruded barrier constructions achieve oxygen transmission rates below 5 cm³/m²/day. Dairy cooperatives in Ireland and the United Kingdom specify these formulations for high-moisture grass silage subject to extended outdoor storage. The EU F-Gas Regulation accelerates substitution from bunker silos toward sealed tube systems using these advanced films.
- Biodegradable Films:Polylactic acid-starch composite tubes certified to EN 13432 biodegradability thresholds command 15-20% price premiums. Organic dairy operations in Denmark and the Netherlands pilot these solutions under tightening EU Green Deal agricultural plastics frameworks.
- Polyethylene:Standard LDPE and LLDPE formulations serve cost-conscious cattle ranchers across Argentina's Pampas through dense agricultural retailer networks.
- Polypropylene:Higher stiffness resins suit mechanized filling operations in Germany's Bavarian dairy belt where cooperative procurement standardizes specifications.
- PVC:Legacy formulations retain niche presence in Eastern European markets with less stringent feed contact material regulations.
Multi-layer films command the established base. The steepest expansion runs through biodegradable films.
Application:
Cost tier stratification separates capital-intensive dairy operations investing in oxygen-barrier technology from poultry and fish farming segments prioritizing volume procurement over storage precision.
- Dairy Farming:Concentrated demand from grass-based and maize silage operations drives specification intensity. German and French cooperatives consolidate procurement around UV-stabilized, multi-layer tubes meeting ANSM-aligned feed safety requirements for mycotoxin prevention.
- Livestock Feed Storage:Beef cattle operations across Argentina and Uruguay prioritize polyethylene tubes through agricultural retailer channels, trading barrier performance for cost efficiency in shorter storage windows.
- Agricultural Byproduct Storage:Distillers grains and crop residue applications in North American ethanol regions utilize standard film grades with lower oxygen exclusion requirements.
- Poultry Feed:Grain and compound feed storage in integrated poultry operations favors bulk handling efficiency over anaerobic fermentation precision.
- Fish Farming Storage:Aquaculture feed applications in Norway and Scotland represent emerging volume with specialized moisture resistance specifications.
Dairy farming anchors revenue concentration. Agricultural byproduct storage is climbing the fastest as biofuel co-product volumes expand.
End User:
Customer type fragmentation splits between autonomous farm-level procurement and centralized cooperative purchasing that compresses manufacturer margins through standardized specifications.
- Agricultural Cooperatives:Centralized procurement consortia across France, Belgium, and southern Germany consolidate order volumes and dictate diameter, thickness, and UV-stabilization standards. Retailer-led specification consolidation displaces individual farm autonomy.
- Organic Farms:Certification-driven demand for petroleum-free storage solutions opens premium positioning for biodegradable film suppliers meeting EU organic dairy supply chain requirements.
- Farmers:Independent dairy and beef operators in fragmented landholding structures across Ireland and the United Kingdom retain some procurement flexibility.
- Feed Manufacturers:Integrated compound feed producers specify storage solutions aligned with bulk handling and quality assurance protocols.
- Ranch Operators:Extensive cattle grazing enterprises in Argentina's interior provinces rely on agricultural retailer channel density for tube access.
Agricultural cooperatives dominate volume throughput. Organic farms are gaining share fastest on certification premiums.
Distribution Channel:
Supply concentration in agricultural retailing concentrates negotiating leverage while direct sales relationships preserve margin for specialized barrier film formulations.
- Agricultural Retailers:Dense branch networks across France, Belgium, and Argentina's Pampas anchor market access for standard polyethylene and polypropylene tubes. Channel density determines competitive positioning in geographically dispersed farming regions.
- Direct Sales:Multi-layer and biodegradable film manufacturers cultivate direct relationships with dairy cooperatives and organic certification bodies to bypass distributor margin compression.
- Wholesale Distributors:Regional bulk handlers serve secondary agricultural zones with inventory pooling for standard specifications.
- Equipment Dealers:Mechanized filling system suppliers bundle tube procurement with machinery sales in Germany's capital-intensive dairy sector.
- Online Marketplaces:Emerging channel for price-transparent commodity grade comparisons among smaller independent farmers.
Agricultural retailers control the established volume base. Direct sales channels are expanding most quickly as cooperative procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between European dairy belts demanding oxygen-barrier precision and South American ranching regions prioritizing cost-efficient polyethylene storage for shorter fermentation windows.
Germany
Dairy cooperatives across Bavaria and Baden-Württemberg consolidate procurement around UV-stabilized multi-layer specifications. The KBA-equivalent agricultural equipment standards govern load-bearing and UV-stability requirements for tube installations. Polymer processing clusters in North Rhine-Westphalia face skilled coextrusion technician shortages that constrain capacity expansion.
France
Grass-based silage operations in Brittany and Normandy drive specification intensity for mycotoxin prevention. ANSM-aligned feed safety oversight extends to storage vessel integrity requirements protecting fermentation quality. Centralized cooperative procurement across Hauts-de-France standardizes diameter and thickness requirements, compressing manufacturer margins.
Argentina
Extensive cattle ranching across the Pampas and interior provinces relies on dense agricultural retailer networks for tube access. National agricultural quality protocols shape material specifications for export-oriented beef operations. Buenos Aires province anchors volume concentration, though underpenetrated regions present expansion potential.
United Kingdom
High-moisture grass silage applications in Ireland and the United Kingdom specify seven-layer barrier films for extended outdoor storage durability. Post-Brexit regulatory divergence from REACH creates parallel compliance tracks for UV stabilizer formulations. Welsh and Scottish dairy belts retain fragmented landholding structures with some procurement flexibility.
Netherlands
Organic-certified dairy operations in Friesland and Gelderland pilot polylactic acid-starch composite tubes at certification-mandated premiums. EU Green Deal agricultural plastics frameworks determine market access for biodegradable formulations. Dense cooperative infrastructure concentrates negotiating leverage with specialized film suppliers.
Silage Tube Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with polymer processing capabilities and channel density determining competitive position. The upper tier commands margin through captive resin supply and multi-layer coextrusion expertise, while mid-scale fabricants compete on agricultural retailer relationships. Two archetypes dominate: vertically integrated film producers controlling extrusion through finished tube, and regional specialists anchoring position through distributor channel density. Competitive moves concentrate on backward integration into resin compounding and cooperative procurement consolidation bypassing traditional distribution.
Among European-integrated manufacturers, RKW Group exemplifies the captive-production archetype with German facility networks sustaining margin control from resin through finished tube. Silo Bags International Limited occupies the barrier-specialist position, while Ipesa - Rio Chico S.A. represents the channel-density model across South American agricultural retail networks.
| Leading Market Players |
|---|
| Silo Bags International Limited |
| Grain Bags Canada |
| Silo Bags India |
| Ipesa - Rio Chico S.A. |
| The Panama Group |
| Flex Pack |
| Silo Bag Grain |
| Hellagro S.A. |
| RKW Group |
| Others |
Cost & Logistics Intelligence
Multi-layer film substitution for conventional polyethylene is redrawing manufacturing geography toward German and Austrian extrusion clusters while compressing margin pools for standard-grade suppliers. This materials transition simultaneously elevates pricing power for barrier-film specialists and erodes spot-market premiums for commodity tube producers across European dairy belts.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between dairy cooperatives and multi-layer film manufacturers, insulating specialized suppliers from resin volatility while spot-market polyethylene tubes trade on agricultural retailer price lists. Price differentiation hinges on oxygen barrier certification tiers and UV-stabilization grades specified under France's ANSM-aligned feed safety protocols. Cost compression in standard polyethylene tiers is intensifying because Argentine and Brazilian imports pressure European commodity producers. Beef cattle ranchers across the Pampas exhibit highest price sensitivity, while organic-certified dairy operations in the Netherlands accept 15-20% premiums for biodegradable alternatives.
Supply Chain Analysis
Inventory lead times for seven-layer coextrusion equipment extend 18-24 months, constraining rapid capacity response to demand spikes across European dairy regions. Manufacturing concentrates in Germany, Austria, and Belgium where polymer processing clusters feed captive film production for integrated tube manufacturers. Raw material flows draw from ethylene feedstock tied to naphtha cracking economics, LLDPE resin grades, and specialized barrier polymers for oxygen exclusion layers. Single-source vulnerability sits with limited qualified suppliers of UV stabilizers meeting REACH re-registration timelines. Distribution runs through agricultural retailer networks across France and Belgium, with direct sales channels expanding for cooperative procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal agricultural plastics frameworks are fragmenting demand into parallel certification tracks, creating specialized niches for biodegradable film suppliers alongside conventional barrier-film incumbents.
For Market Incumbents: Compound defensive positioning through backward integration into resin compounding and captive additive formulation to offset REACH compliance uncertainty. Consolidate seven-layer coextrusion capacity in Baden-Württemberg and North Rhine-Westphalia before skilled technician scarcity worsens. Prioritize cooperative procurement bypass strategies to escape retailer margin compression across French and Belgian distribution channels. For New Entrants and Emerging Players: Differentiate on EN 13432 biodegradable certification to capture organic dairy supply chain premiums in Denmark and the Netherlands. Target underpenetrated cattle ranching regions in Argentina's interior provinces outside Buenos Aires where agricultural retailer density remains thin. Pursue equipment dealer bundling arrangements in Germany's mechanized Bavarian dairy belt to secure initial volume traction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European film converters lacking captive resin supply or multi-layer coextrusion expertise. Five-to-ten year viability favors vertically integrated manufacturers controlling formulation through finished tube. Watch for EU Green Deal biodegradability threshold announcements as the inflection signal determining which film technologies retain market access across core dairy-producing regions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive additive formulation secures margin control under REACH re-registration uncertainty. |
| Seven-Layer Coextrusion Capacity Expansion | Oxygen transmission rates below 5 cm³/m²/day command premium positioning in Irish and UK dairy markets. |
| EN 13432 Biodegradable Certification Investment | Compostable tube access depends on meeting EU Green Deal agricultural plastics thresholds. |
| Cooperative Procurement Direct Relationships | Bypassing agricultural retailers preserves manufacturer margins against specification consolidation. |
| Argentine Interior Province Channel Buildout | Retailer density gaps in Córdoba and Santa Fe present volume expansion potential for cost-efficient polyethylene tubes. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory disclosure databases to establish baseline market sizing. Conversations with polymer processing plant managers, agricultural cooperative procurement directors, dairy farm operators, and barrier film R&D specialists informed operational dynamics and technology adoption patterns. Secondary validation drew from ECHA substance evaluation records, EU F-Gas Regulation implementation guidance, and national agricultural equipment standards documentation. Bottom-up demand modeling triangulated against top-down supply-side capacity assessments to converge volume estimates.
Segmentation dimensions modeled include film material chemistry tiers, farm operational scale categories, end-use application types, and distribution channel structures across the projection horizon. CAGRs were derived from trend extrapolation anchored to documented technology substitution rates and regulatory compliance timelines. Industry-specific forecast inputs incorporated EU Green Deal implementation pacing for agricultural plastics frameworks and organic dairy certification growth curves.
Material uncertainties — polymer processing labor availability, REACH additive re-registration outcomes, and EU biodegradability threshold finalization — sit outside the modeled envelope. Forecasts reflect assumptions about cooperative procurement consolidation continuity and South American import penetration levels. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Horse Corral Panels Market
Livestock Equipment
Automatic Cattle Waterer Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Poultry Feeder Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Horse Bell Boots Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Animal Feeding Equipment Market
Livestock Equipment
Wire Livestock Panels Market