
 Cow Lifting Harness Market | 2026-2036
Cow Lifting Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Cow Lifting Harness Market Outlook
A shift from single-source procurement to multi-source supplier relationships is pivoting how dairy equipment buyers manage cow lifting harness availability. DeLaval International AB leverages its integrated dairy systems portfolio to bundle harness sales with milking parlour installations. GEA Group AG anchors its position through veterinary equipment distribution networks across European dairy cooperatives. BouMatic LLC competes on aftermarket service density in the Upper Midwest dairy belt.
A cow lifting harness is a mechanical restraint and support device constructed from woven nylon or polyester webbing with metal D-rings and adjustable buckles, designed to suspend or mobilize recumbent cattle using hoists or tractor-mounted lifting equipment. The device distributes load across the sternum, pelvis, and hindquarters to prevent tissue damage during extraction or treatment of downer cows. Standard harness configurations still dominate unit sales across price-sensitive livestock operations, though veterinary harness variants command premium positioning due to diagnostic access panels and sanitizable coatings. Nylon materials lead volume shipments for on-farm deployment given tensile strength and moisture resistance, while polyester gains traction in mobile veterinary units requiring faster drying cycles.
The USDA Animal Welfare Act and FDA veterinary medical device guidelines shape product safety testing and interstate commerce requirements for harness manufacturers serving the United States. REACH compliance and CE marking obligations under EU machinery directives govern material composition and load-rating disclosures for European market access. Stakeholders must monitor evolving animal welfare audit standards from third-party certifiers like Validus and FARM, as these programs increasingly score downer cow handling protocols in supplier assessments.
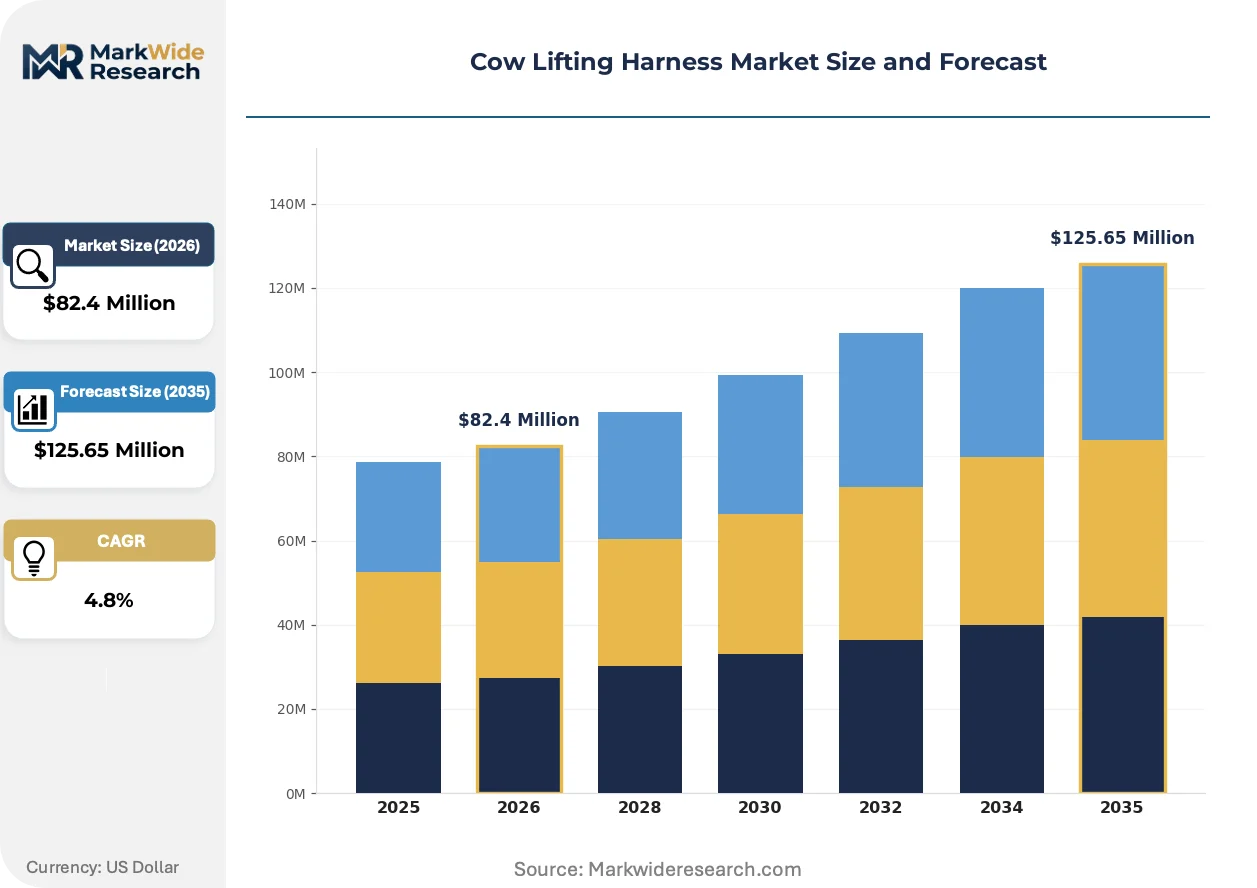
Market Dynamics
The cow lifting harness market is being fundamentally reshaped by the mechanization imperative in large-scale dairy operations, where herd management automation now extends to veterinary intervention protocols for downer cattle.
Growth Catalysts
- EU Animal Welfare Mandates:European Union regulations requiring humane handling protocols for non-ambulatory livestock are compelling dairy cooperatives in Germany and the Netherlands to standardize mechanical lifting equipment across their facilities.
- Polyester Webbing Adoption:Mobile veterinary units are driving demand for faster-drying harness materials that reduce turnaround times between farm calls and improve equipment utilization rates.
- Large-Herd Concentration:North American dairy operations exceeding 500 head are integrating lifting harnesses into standard downer cow management protocols to reduce labor injury risk and veterinary response times.
Market Restraints
- Nylon Input Cost Volatility:Petrochemical-derived webbing materials expose manufacturers to crude oil price fluctuations that compress margin stability on standard-grade harness configurations.
- Veterinary Equipment Distribution Concentration:European market access depends heavily on specialized agricultural veterinary supply networks concentrated in dairy cooperative purchasing structures.
- Manual Restraint Substitution:Smallholder operations in price-sensitive segments continue relying on traditional rope-and-pulley methods that limit addressable market expansion.
Strategic Opportunities
- Diagnostic-Access Panel Integration:Veterinary-grade harness variants with sanitizable coatings and examination ports command premium positioning in university teaching hospitals and specialty clinics.
- CE Marking Expansion:EU machinery directive compliance creates pathway for standardized load-rating disclosures that reduce regulatory friction across member state borders.
- Aftermarket Service Density:Preventive maintenance contracts and rapid replacement part availability represent underdeveloped revenue streams beyond initial equipment sales.
Industry Challenges
- Veterinary Equipment Technician Shortage:Specialized installation and calibration expertise for hoist-integrated harness systems limits deployment velocity in remote dairy regions.
- Third-Party Audit Alignment:Validus and FARM certification programs impose evolving scoring criteria for downer cow handling that require continuous protocol documentation and staff retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cow Lifting Harness Market |
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $125.65 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Harness, Adjustable Harness, Heavy-Duty Harness, Veterinary Harness Material: Nylon, Polyester, Cotton, Metal End User: Dairy Farms, Veterinary Clinics, Rescue Organizations, Livestock Farms Deployment: On-Farm, Mobile Units, Veterinary Services, Agricultural Shows |
| Companies Covered | Premier 1 Supplies, Ritchie Industries, MS Schippers, KONG USA, XIANERS, DeLaval International AB, GEA Group AG, Lely Holding S.A.R.L., BouMatic LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cow Lifting Harness Market Strategic Shifts
Material science advances and regulatory transparency requirements are converging to redefine product differentiation in livestock handling equipment, shifting competitive advantage from basic durability toward specialized clinical functionality.
Polyester webbing is overtaking nylon as the preferred material for mobile veterinary deployments due to its accelerated drying properties and reduced bacterial retention between farm calls. Large-animal practitioners operating across multiple sites daily are prioritizing equipment turnaround efficiency over the marginal tensile strength advantages of traditional nylon constructions. This material transition is compressing the addressable market for commodity-grade harness suppliers while expanding margins for specialized veterinary equipment manufacturers.
REACH compliance obligations under EU chemical regulations are mandating detailed material composition disclosures for all load-bearing textile components entering European dairy supply chains. Manufacturers must now document phthalate content, heavy metal traces, and biodegradation profiles to maintain market access. German and Dutch dairy cooperatives are responding by consolidating procurement around suppliers with pre-validated regulatory documentation, creating preferential access barriers for new market entrants.
Service unbundling is fragmenting traditional equipment-plus-installation bundles as sophisticated buyers separate capital procurement from ongoing maintenance obligations. Independent dairy consultants are increasingly specifying harness brands while sourcing installation and calibration services through regional agricultural mechanics. This purchasing pattern shift is most pronounced in Wisconsin and Minnesota, where dense networks of independent dairy service providers enable modular supplier relationships.
Cow Lifting Harness Market Segmentation
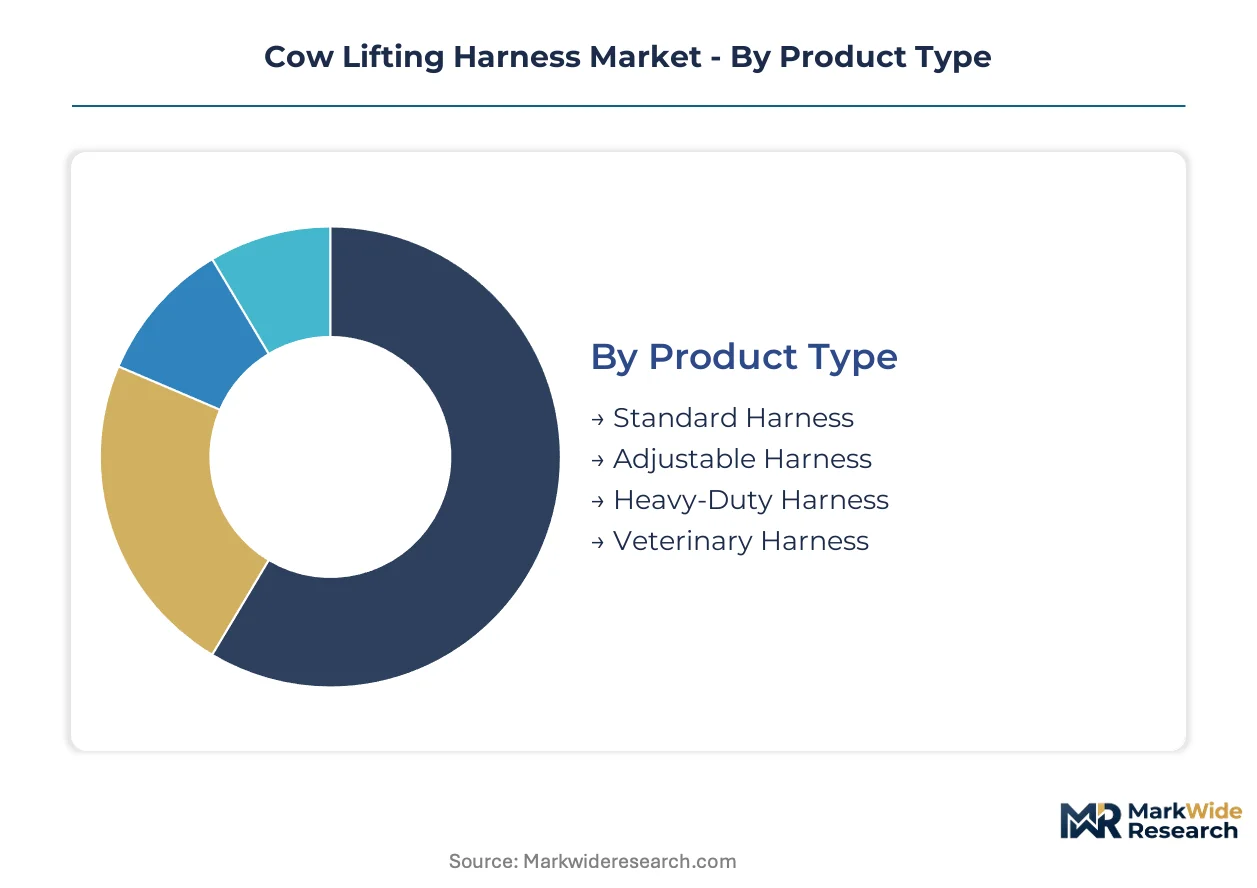
Cow lifting harness segmentation reflects divergent technical requirements across veterinary intervention intensity and operational scale. Material specifications and load-bearing configurations determine suitability for routine farm management versus emergency clinical deployment.
Product Type:
Load-rating specifications and adjustment mechanisms differentiate harness architectures for distinct cattle handling scenarios.
- Standard Harness:Fixed-configuration webbing assemblies with pre-set sternum and pelvic support zones serve routine downer cow extraction in mid-scale dairy operations. Demand concentrates in Wisconsin and Minnesota where 200-500 head farms prioritize capital efficiency over specialized features.
- Veterinary Harness:Examination-compatible designs incorporate sanitizable polymer coatings and removable access panels for diagnostic procedures during suspension. German university teaching hospitals and Dutch cooperative veterinary networks drive specification requirements for clinical-grade variants.
- Adjustable Harness:Modular buckle systems accommodate cattle weight ranges from 400kg to 900kg across mixed livestock operations.
- Heavy-Duty Harness:Reinforced D-ring assemblies and double-layer webbing target bull handling and emergency rescue scenarios.
Mature deployment sits with Standard Harness configurations. Newer deployment is concentrated in Veterinary Harness variants.
Material:
Moisture management properties and tensile strength specifications govern material selection for distinct operational environments.
- Nylon:Petrochemical-derived polyamide construction delivers superior tensile strength and abrasion resistance for permanent on-farm installations. Dairy operations in the Upper Midwest specify nylon for high-frequency use despite extended drying times between applications.
- Polyester:Hydrophobic fiber structure enables 40% faster moisture evaporation than nylon alternatives. Mobile veterinary units across the Netherlands and northern Germany prioritize polyester for same-day multi-farm deployment schedules.
- Cotton:Natural fiber construction offers biodegradability advantages for organic certification compliance in specialty dairy segments.
- Metal:Stainless steel chain-link assemblies provide extreme load capacity for research facilities and zoological applications.
Volume concentration favors Nylon for fixed installations. Steepest expansion trajectory belongs to Polyester for mobile service models.
End User:
Purchasing authority and intervention protocols shape equipment specifications across institutional buyer categories.
- Dairy Farms:Owner-operated procurement of standard-grade harnesses for routine downer cow management dominates unit volume. German cooperative purchasing structures aggregate demand across multi-farm memberships to negotiate equipment standardization.
- Veterinary Clinics:Clinical-grade specifications with documentation for CE marking compliance command premium positioning. Dutch large-animal practices require diagnostic-access compatibility for university hospital referral networks.
- Rescue Organizations:Emergency response protocols demand rapid-deployment harness systems for highway and barn accident scenarios.
- Livestock Farms:Beef cattle operations in extensive grazing systems specify lighter-weight portable configurations.
Procurement scale concentrates with Dairy Farms. Specification complexity is climbing fastest among Veterinary Clinics.
Deployment:
Equipment mobility requirements and usage frequency determine capital allocation and maintenance protocols.
- On-Farm:Permanent hoist-integrated installations with scheduled inspection cycles serve high-volume dairy operations. Minnesota farms exceeding 500 head incorporate harness systems into standard operating procedures for downer cow protocols.
- Mobile Units:Tractor-mounted or portable hoist configurations enable rapid response across dispersed farm locations. German veterinary service cooperatives deploy mobile harness systems to reduce emergency response times in rural dairy regions.
- Veterinary Services:Contract-based equipment provision separates capital ownership from clinical service delivery.
- Agricultural Shows:Exhibition-grade harness demonstrations support equipment manufacturer marketing at regional livestock events.
Capital investment depth is greatest for On-Farm deployment. Service model innovation is expanding fastest through Mobile Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock clusters in the US Gulf Coast and synthetic fiber production centers in Germany anchor the cow lifting harness supply chain. These material hubs shape manufacturing economics and distribution reach across key dairy markets.
United States
Large-scale dairy operations in Wisconsin and Minnesota drive equipment standardization for downer cow protocols. The USDA Animal Welfare Act mandates humane handling standards that mechanical lifting systems must satisfy. Minneapolis-St. Paul serves as the densest service network hub where independent dairy mechanics support modular procurement patterns.
Germany
Dairy cooperatives in Lower Saxony and Bavaria aggregate procurement across multi-farm memberships to negotiate harness standardization. REACH compliance and CE marking under EU machinery directives govern material composition disclosures for all load-bearing components. The Emsland region concentrates veterinary equipment distribution networks serving cooperative purchasing structures.
Netherlands
Mobile veterinary units across Friesland and Gelderland prioritize polyester harness configurations for same-day multi-farm deployment schedules. EU animal welfare regulations compel standardization of mechanical lifting equipment across cooperative facilities. Wageningen University teaching hospitals drive specification requirements for clinical-grade harness variants with diagnostic access panels.
Canada
Dairy operations in Ontario and Quebec integrate lifting harnesses into herd management automation for operations exceeding 500 head. Health Canada veterinary medical device guidelines align with FDA frameworks for cross-border equipment commerce. The Ottawa Valley cluster anchors distribution networks serving eastern Canadian dairy cooperatives.
Australia
Extensive grazing systems in Victoria and New South Wales specify lighter-weight portable configurations for beef cattle operations. The country's national agricultural regulator enforces animal welfare audit standards that score downer cow handling protocols. The Murray Dairy region concentrates demand for mobile veterinary service models across dispersed farm locations.
Cow Lifting Harness Market Competitive Environment
Global majors compete with regional champions across integrated dairy systems versus specialized equipment distribution. The vendor base spans three tiers: diversified agricultural technology conglomerates with harness bundling capabilities, veterinary equipment specialists with cooperative network access, and regional fabricators competing on aftermarket service density. Consolidation pressure favors players with pre-validated regulatory documentation for EU market access. Dominant competitive moves include strategic partnerships with dairy cooperative purchasing structures and geographic expansion through veterinary supply network acquisitions.
Within the diversified systems tier, DeLaval International AB and GEA Group AG exemplify contrasting approaches to market access—DeLaval through integrated dairy equipment bundling and GEA through veterinary distribution network anchoring. BouMatic LLC occupies a position among regional service-density specialists targeting the Upper Midwest dairy belt. MS Schippers represents the cooperative-aligned archetype prevalent in Dutch and German dairy procurement structures.
| Leading Market Players |
|---|
| Premier 1 Supplies |
| Ritchie Industries |
| MS Schippers |
| KONG USA |
| XIANERS |
| DeLaval International AB |
| GEA Group AG |
| Lely Holding S.A.R.L. |
| BouMatic LLC |
| Others |
Value Chain & Pricing Dynamics
Specialized veterinary equipment technicians concentrated in the Upper Midwest dairy belt create labor-cost differentials that widen pricing-tier spreads between premium clinical-grade harnesses and economy farm configurations. These skill premiums compress margins for standard-grade suppliers while insulating premium-positioned manufacturers from price erosion.
Pricing Analysis
Warranty and preventive maintenance bundling separates capital procurement from service obligations across buyer segments. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking compliance status and diagnostic-access panel inclusion. Price differentiation hinges on sanitizable coating certification and aftermarket service density. Cost compression in standard-grade nylon configurations is intensifying because petrochemical feedstock volatility transfers directly to webbing material costs. Smallholder operations in price-sensitive segments exhibit highest price sensitivity, while university teaching hospitals demonstrate lowest sensitivity due to grant-funded procurement protocols.
Supply Chain Analysis
Reverse-logistics flows for harness refurbishment and component replacement remain underdeveloped, with most worn webbing assemblies exiting to landfill rather than remanufacturing streams. Manufacturing concentration centers on Germany, the United States, and China, with synthetic fiber production anchored in the Emsland region and US Gulf Coast petrochemical clusters. Raw material dependencies rest on polyamide and polyester polymer feedstocks, metal D-ring forgings, and polymer coating formulations. Single-source vulnerability in specialized veterinary equipment distribution networks creates supply chain risk for European market access. Distribution runs through dairy cooperative purchasing structures in Germany and the Netherlands, independent agricultural mechanics in Wisconsin and Minnesota, and veterinary supply wholesalers serving mobile service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH compliance documentation requirements and CE marking validation costs force weaker regional fabricators toward exit or acquisition.
For Market Incumbents: Hedge against margin compression in standard-grade nylon configurations by accelerating polyester webbing capacity expansion for mobile veterinary segments. Secure backward integration into synthetic fiber weaving to reduce petrochemical price volatility exposure. Anchor market position through preemptive certification investment for evolving FARM and Validus audit standards that score downer cow handling protocols. For New Entrants and Emerging Players: Veterinary service cooperatives represent the most accessible channel partner type for market penetration without direct confrontation with bundled dairy equipment majors. Target aftermarket service density gaps in dispersed Australian grazing regions and underserved Canadian prairie provinces where mobile veterinary models expand fastest. Pursue white-label manufacturing arrangements with established cooperative-aligned distributors to bypass upfront regulatory validation costs. For Investors and Strategic Acquirers: Re-rating potential sits with veterinary-grade harness specialists given diagnostic-access panel integration and university hospital specification capture. Long-term viability over the projection horizon favors manufacturers with pre-validated EU regulatory documentation and established cooperative network relationships. Acquisition target archetype: mid-cap regional fabricators with installed base density but lacking certification infrastructure. Monitor polyester webbing adoption rates in German and Dutch mobile veterinary fleets as inflection indicator for material-transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Expansion | Standardized load-rating disclosures reduce regulatory friction across EU member state borders. |
| Diagnostic-Access Panel Integration | Examination-compatible designs command premium positioning in Wageningen University teaching hospitals. |
| Aftermarket Service Density Buildout | Preventive maintenance contracts unlock recurring revenue beyond initial equipment sales in Minnesota. |
| Polyester Webbing Capacity Addition | Faster-drying configurations capture mobile veterinary demand across Netherlands same-day deployment schedules. |
| Cooperative Purchasing Structure Partnership | Aggregated procurement in Lower Saxony dairy networks enables equipment standardization at scale. |
Study Parameters
Multi-period observation of veterinary equipment procurement patterns, material substitution rates, and cooperative purchasing consolidation anchored the trend analysis, supplemented by interviews with large-animal veterinary practitioners, dairy cooperative procurement officers, agricultural equipment distributors, and aftermarket service technicians. Secondary validation drew from USDA Animal Welfare Act guidance documents, FDA veterinary medical device filings, EU machinery directive compliance databases, REACH chemical registration records, and trade flow data for synthetic textile inputs. Bottom-up segment sizing triangulated against top-down dairy herd statistics and equipment penetration assumptions.
Input-output matrix modeling connected raw material cost indices, regulatory compliance burden estimates, and end-user purchasing behavior parameters to generate volume and value projections. Segmentation dimensions spanned product architecture, material composition, end-user institution type, and deployment mobility configuration across the modeling period. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns in comparable livestock handling equipment categories. Forecast inputs incorporated veterinary workforce density projections and evolving third-party audit standard scoring weights.
Caveats apply where REACH chemical regulation amendments, abrupt petrochemical price shocks, or veterinary technician training pipeline disruptions could materially shift the outlook. Practitioners should monitor FARM and Validus audit standard revision schedules for early signals of compliance burden escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Rabbit Hutches Market
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Livestock Farm Equipment Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Egg Incubator Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Automatic Hog Feeder Market
Livestock Equipment
Hydraulic Squeeze Chute Market
Livestock Equipment
Starter Feed Market
Livestock Equipment
Automated Feeding System Market
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Cattle Supplies Market