
 Meat Processing Equipment Market | 2026-2036
Meat Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Processing Equipment Market Intelligence
Stainless steel replacement by antimicrobial alloy surfaces is recalibrating equipment lifecycle economics across premium processing lines. GEA Group leverages its refrigeration-integration expertise to anchor large-scale plant contracts in Northern Europe. Marel sustains technology leadership through sensor-embedded cutting systems that reduce yield loss. JBT Corporation dominates cooking and freezing equipment segments with in-house production of thermal processing units.
Meat processing equipment encompasses machinery designed to transform raw animal proteins into consumer-ready or intermediate food products, operating at throughputs from artisan-scale batch processing to continuous-line systems exceeding 15,000 kg per hour. Choppers and grinders constitute mature, price-competitive segments where margin pools have compressed to single-digit percentages. Automated technology lines represent the fastest-expanding category as labor-cost arbitrage and lot-traceability requirements intensify. Smart equipment incorporating real-time fat-analysis sensors commands premium positioning within the technology dimension.
The USDA enforces pathogen-reduction and HACCP compliance standards that dictate equipment washdown protocols and sanitary design specifications across US facilities. The EU F-Gas Regulation and REACH chemical restrictions are reshaping refrigerant choices and surface-coating formulations in European plants. Stakeholders must monitor how evolving ESG disclosure rules under CSRD will alter capital allocation toward lower-carbon processing infrastructure.
Market Dynamics
Labor-cost arbitrage and lot-traceability mandates are compressing replacement cycles for batch equipment while accelerating continuous-line adoption across protein processing corridors. Refrigerant-phaseout deadlines under EU F-Gas Regulation are forcing parallel capital deployment into cold-chain retrofits.
Growth Catalysts
- Automated Technology Lines:Food manufacturers in Germany are expanding sensor-embedded cutting systems that reduce yield loss and enable real-time fat analysis. Premium processing lines absorb these installations to offset wage inflation.
- EU F-Gas Regulation:The refrigerant-phaseout mandate is accelerating equipment replacement cycles in cold-chain-linked processing plants across Northern Europe. Retrofit demand concentrates in integrated poultry facilities.
- Brazil's Poultry Corridor:Demand for high-throughput continuous systems exceeding 15,000 kg per hour is concentrating in Brazil's vertically integrated protein processing belt.
Market Restraints
- Nickel Alloy Input Volatility:Antimicrobial surface coatings depend on specialized stainless-steel alloys whose feedstock costs swing with nickel futures. Equipment lifecycle economics recalibrate when alloy premiums spike.
- Refrigerant Supply Concentration:Low-GWP alternative refrigerants for retrofitted freezing equipment source from a concentrated supplier base in East Asia. Lead times extend when regional production faces disruption.
- Yield Sensor Technical Limitations:Real-time fat-analysis sensors in cutting systems struggle with variable marbling patterns in grass-fed beef. Accuracy gaps persist against laboratory reference methods.
Strategic Opportunities
- Antimicrobial Alloy Surfaces:Equipment manufacturers with captive metallurgy capabilities can wedge into premium line contracts by guaranteeing surface sanitization performance across extended duty cycles.
- CSRD-Driven Capital Rotation:The EU's Corporate Sustainability Reporting Directive is altering capital allocation toward lower-carbon processing infrastructure. Early movers capture ESG-linked financing advantages.
- Refrigeration-Integration Convergence:Cooking and freezing equipment segments are absorbing thermal processing units that bundle energy recovery. Bundled system contracts displace standalone equipment procurement.
Industry Challenges
- Sanitary Design Engineering Talent:USDA HACCP washdown protocols and EPA effluent standards require specialized mechanical designers. The talent pool for dual-compliant equipment engineering remains shallow.
- Legacy System Integration Complexity:Sensor-embedded cutting systems must interface with decade-old plant SCADA architectures. Retrofit commissioning timelines stretch when proprietary protocols conflict.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Processing Equipment Market |
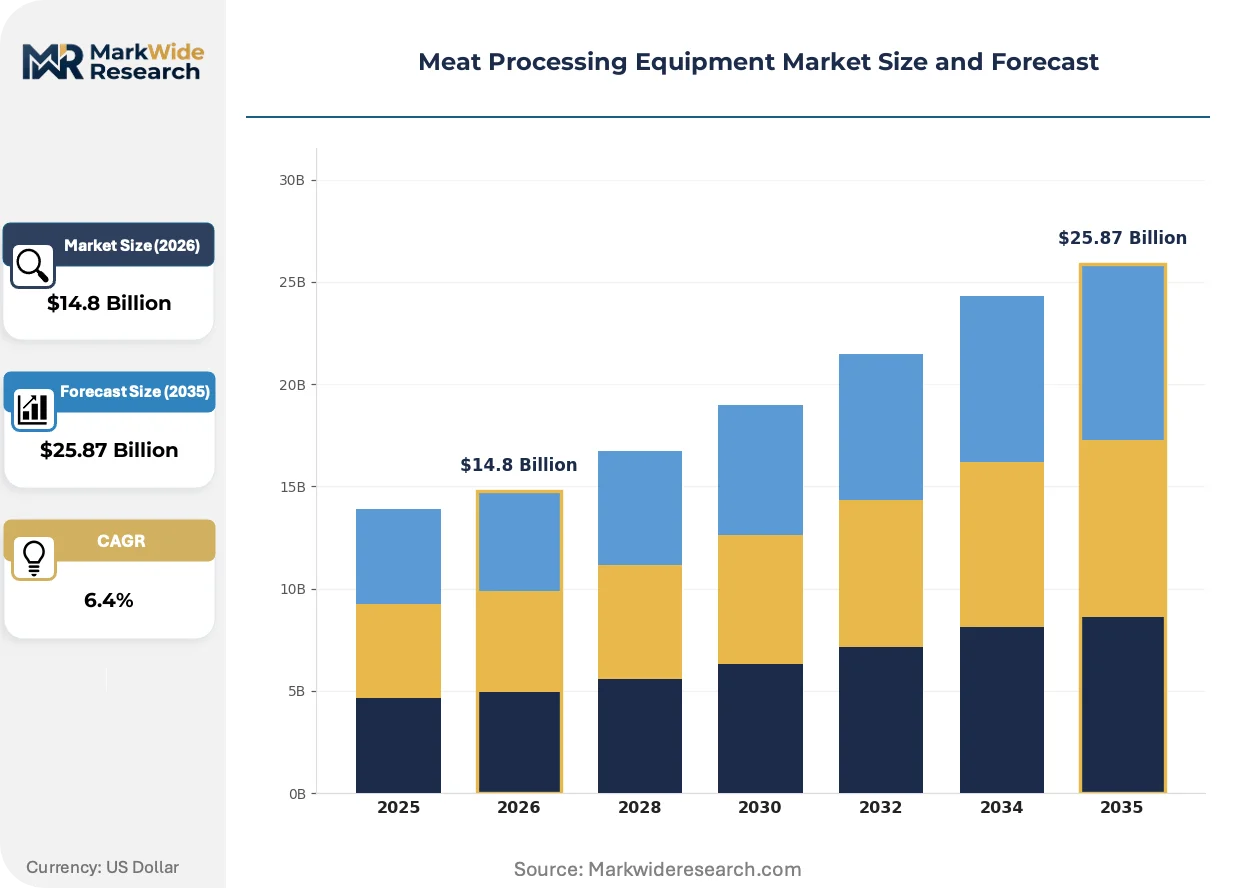
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Choppers, Mixers, Sausage Stuffers, Grinders Application: Processing, Packaging, Cutting, Cooking End User: Food Manufacturers, Butcher Shops, Supermarkets, Restaurants Technology: Mechanical, Electric, Smart, Automated |
| Companies Covered | GEA Group, BAADER, Marel, Mepaco, Handtmann Maschinenfabrik, The Middleby Corporation, Bettcher Industries, Minerva Omega Group, JBT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Processing Equipment Market Strategic Shifts & Innovations
Equipment intelligence is migrating from peripheral monitoring to embedded process control, reshaping how protein processors justify capital expenditure. Surface material science and refrigerant chemistry are converging with automation architecture.
Antimicrobial alloy surfaces are absorbing capital allocation from conventional stainless-steel equipment across premium processing lines. Brazilian and German integrators specify these surfaces for high-value beef and pork operations. The technology is absorbing margin pressure from commodity-grade chopper and grinder segments by creating defensible premium tiers.
REACH chemical restrictions are reshaping surface-coating formulations in European meat processing plants. ECHA substance-of-very-high-concern listings are eliminating legacy anti-corrosion treatments from approved material lists. Northern European cold-chain facilities are responding by qualifying alternative coatings ahead of sunset dates.
Buyers are unbundling after-sales service from initial equipment procurement in mature equipment categories. Large protein processors in Germany and Brazil now contract maintenance separately through multi-vendor service aggregators. This pattern is most visible in chopper and grinder segments where margin pools have compressed to single-digit percentages.
Meat Processing Equipment Market Segmentation
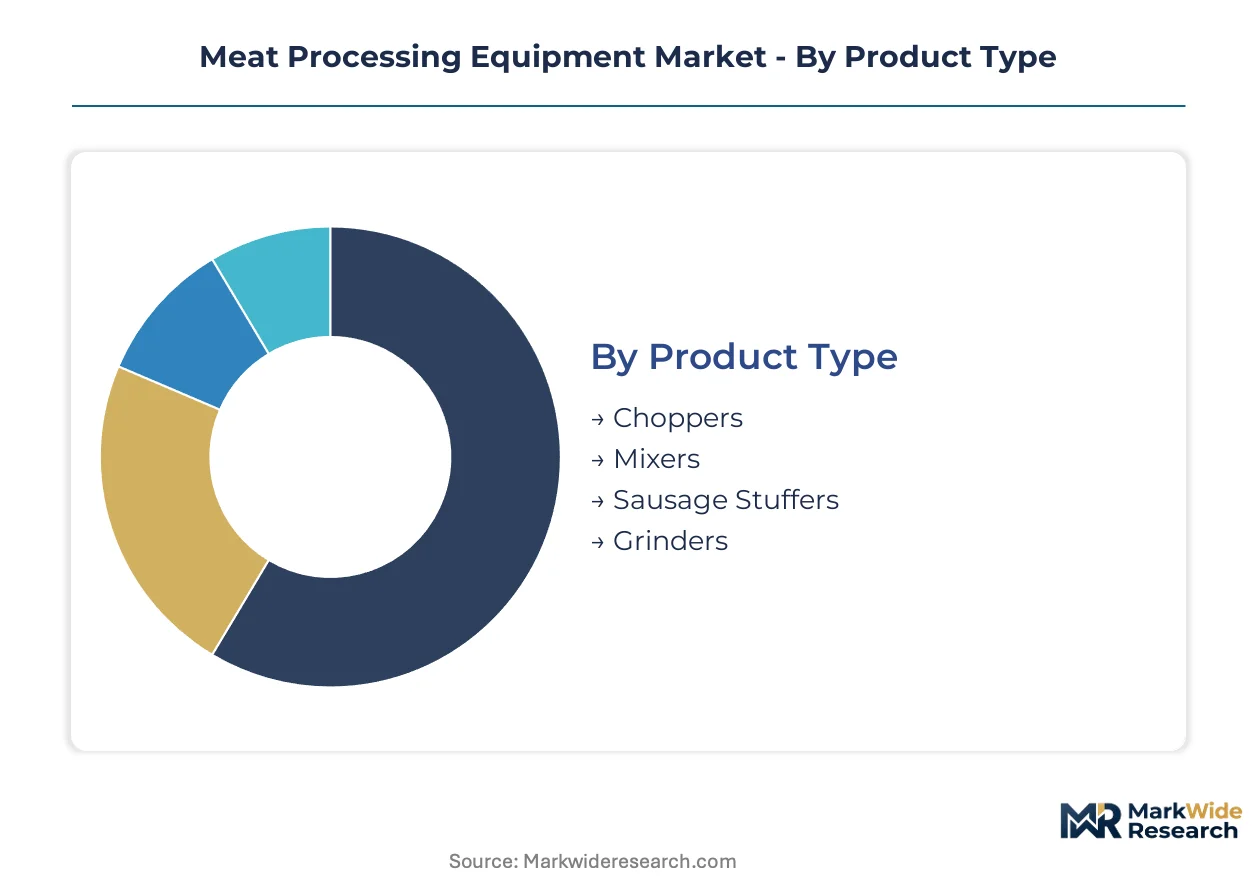
Equipment segmentation in meat processing tracks how capital flows between standalone batch units and integrated continuous systems. The technology-product-application matrix determines whether processors achieve labor-cost arbitrage or remain trapped in low-margin commodity tiers.
Product Type:
Standalone equipment dominates small-batch operations, while integrated lines embed these functions into continuous-flow architectures.
- Choppers:These machines reduce meat blocks to uniform particle sizes through rotating knife assemblies or bowl cutters. Demand concentrates in Germany's artisan sausage sector, where medium-capacity units offset wage inflation in traditional butcher shops. REACH chemical restrictions are forcing coating reformulations on contact surfaces.
- Mixers:Paddle, ribbon, or vacuum configurations blend proteins with fat, seasonings, and functional additives. Brazilian poultry integrators specify high-shear vacuum mixers for emulsified products, driven by export-grade texture requirements. Antimicrobial alloy specifications are recalibrating lifecycle economics.
- Sausage Stuffers:Piston or vacuum-fed systems force emulsion into casings at controlled pressures. Hydraulic units retain share in European cured-meat traditions.
- Grinders:Auger-driven reduction systems with plate-and-knife configurations. Margin compression to single-digit percentages has triggered unbundled after-sales service contracts.
Volume placements concentrate in grinders; the faster expansion belongs to mixers.
Application:
Cost-tier stratification separates capital-intensive thermal operations from mechanical preparation stages.
- Processing:Encompasses grinding, mixing, emulsifying, and forming operations that transform raw material into intermediate formats. Northern European cold-chain facilities are absorbing integrated processing-cooking-freezing bundles under EU F-Gas retrofit mandates.
- Cutting:Portioning and trimming operations ranging from manual bandsaws to sensor-embedded automated systems. Real-time fat-analysis sensors command premium positioning in high-value beef operations, though accuracy gaps persist with grass-fed marbling variability.
- Packaging:Vacuum, modified-atmosphere, and shrink systems extending shelf life. German food manufacturers specify washdown-compatible designs meeting USDA HACCP protocols for export qualification.
- Cooking:Thermal processing including smoking, roasting, and pasteurization. JBT Corporation's in-house production of thermal units anchors bundled system contracts displacing standalone procurement.
Capital intensity peaks in cooking; packaging gains share fastest through ESG-linked financing advantages.
End User:
Customer-type fragmentation creates divergent specification requirements across volume tiers.
- Food Manufacturers:Large-scale integrated processors operating continuous lines exceeding 15,000 kg per hour. Germany's automated line expansion concentrates demand for sensor-embedded yield-optimization systems.
- Butcher Shops:Artisan-scale operations preserving traditional methods. These buyers prioritize equipment durability over throughput metrics.
- Supermarkets:In-store processing departments requiring compact, washdown-friendly designs. Multi-vendor service aggregators now contract maintenance separately from procurement.
- Restaurants:Central kitchens and commissary operations balancing speed with footprint constraints. Procurement patterns favor countertop grinders and mixers with rapid changeover capabilities.
Specification complexity concentrates with food manufacturers; supermarket in-store processing climbs the fastest.
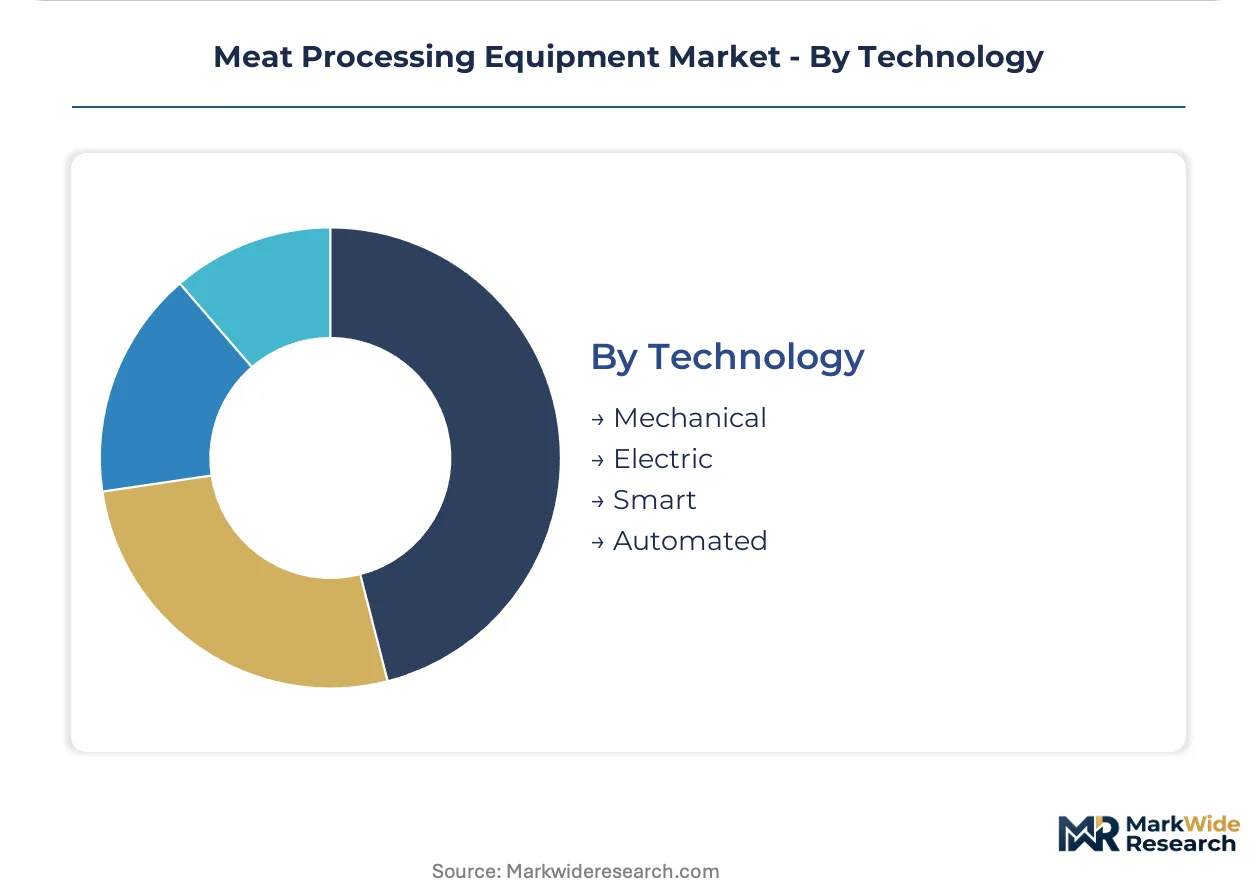
Technology:
Maturity gradients separate established electromechanical platforms from emerging intelligence layers.
- Automated:Continuous-line systems integrating multiple unit operations with centralized control. Brazil's vertically integrated poultry corridor specifies these for labor-cost arbitrage and lot-traceability compliance.
- Smart:Equipment embedding real-time sensors, edge computing, and predictive maintenance algorithms. Fat-analysis sensors and yield-optimization modules command premium positioning within this tier.
- Electric:Conventional motor-driven systems dominating replacement cycles in mature markets. Nickel alloy input volatility recalibrates equipment lifecycle economics when stainless-steel premiums spike.
- Mechanical:Hand-cranked or simple gear-driven units persisting in emerging markets and specialty applications. These systems absorb minimal capital allocation in premium processing corridors.
Installed base concentrates in electric; automated lines show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's automated line installations, Brazil's vertically integrated poultry belt, and Northern Europe's cold-chain retrofit corridors. Equipment procurement patterns diverge sharply between wage-inflation-driven automation in mature economies and throughput-maximizing continuous systems in export-oriented protein hubs.
Germany
Food manufacturers in Bavaria and North Rhine-Westphalia are expanding sensor-embedded cutting systems to offset wage inflation in traditional butcher operations. The EU F-Gas Regulation is accelerating refrigerant system retrofits in cold-chain-linked processing plants across the country. Stuttgart's precision engineering cluster supplies antimicrobial alloy surface technologies to premium beef and pork processing lines.
Brazil
Vertically integrated poultry processors in São Paulo and Paraná specify high-throughput continuous systems exceeding 15,000 kg per hour for export-grade production. ANVISA's sanitary certification requirements dictate equipment washdown protocols across the integrated protein processing belt. Santa Catarina's processing corridor is absorbing capital allocation toward automated deboning and portioning lines.
United States
USDA HACCP enforcement and pathogen-reduction standards are compressing replacement cycles for batch equipment in Midwestern beef and pork facilities. EPA effluent standards reshape surface-coating formulations in Great Lakes region plants. Nebraska's packing corridor is deploying real-time fat-analysis sensors despite accuracy gaps with grass-fed marbling variability.
Netherlands
CSRD-driven capital rotation is altering investment patterns toward lower-carbon processing infrastructure in Randstad food manufacturing clusters. ECHA REACH restrictions are eliminating legacy anti-corrosion treatments from approved material lists. Eindhoven's ag-tech ecosystem is qualifying alternative surface coatings ahead of regulatory sunset dates.
China
Dual carbon goals under MEE oversight are reshaping refrigerant choices in Yangtze River Delta cold-chain facilities. GB standards compliance is forcing coating reformulations on contact surfaces in Shandong Peninsula meat processing plants. Guangdong's protein processing belt is absorbing electric-driven batch equipment for domestic consumption tiers.
Meat Processing Equipment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium continuous-line systems consolidating around integrated solution providers while commodity choppers and grinders fragment across regional fabricators. The vendor base organizes into three archetypes: refrigeration-integration specialists, sensor-embedded automation leaders, and thermal processing bundlers. Dominant competitive moves include backward integration into captive metallurgy capabilities and multi-vendor service aggregation for aftermarket revenue capture.
Among Northern European refrigeration-integration specialists, GEA Group anchors large-scale plant contracts through bundled system architectures. Marel and JBT Corporation exemplify divergent automation strategies—Marel occupies a position within sensor-embedded yield optimization, while JBT represents thermal processing bundlers combining cooking and freezing equipment segments. These three entities collectively illustrate how technology-product convergence is reshaping procurement patterns across protein processing corridors.
| Leading Market Players |
|---|
| GEA Group |
| BAADER |
| Marel |
| Mepaco |
| Handtmann Maschinenfabrik |
| The Middleby Corporation |
| Bettcher Industries |
| Minerva Omega Group |
| JBT Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap fabricators in Northern Italy and Southern Germany anchor supply behavior across chopper and grinder segments, where pricing discipline erodes when nickel alloy premiums spike and procurement managers unbundle after-sales service to compress total cost of ownership.
Pricing Analysis
Volume placements concentrate in commodity-grade electric grinders where margin pools have compressed to single-digit percentages, while premium positioning belongs to sensor-embedded cutting systems with real-time fat-analysis modules. Three-tier pricing structure across premium, standard, and economy levels separates antimicrobial alloy specifications from conventional stainless-steel surfaces and basic mechanical units. Cost compression in batch equipment segments is intensifying because large protein processors in Germany and Brazil now contract maintenance separately through multi-vendor service aggregators. Food manufacturers operating continuous lines exceeding 15,000 kg per hour exhibit the least price sensitivity, whereas artisan-scale butcher shops prioritize equipment durability over throughput metrics and absorb sticker shock poorly.
Supply Chain Analysis
Single-source vulnerability sits with East Asian suppliers of low-GWP alternative refrigerants for retrofitted freezing equipment, where lead times extend when regional production faces disruption. Component manufacturing draws from Germany, Italy, and China, with precision engineering clusters in Stuttgart and Bologna supplying sensor-embedded automation modules while Chinese fabricators dominate electric motor and control system production. Nickel alloy feedstock costs swing with futures markets, creating margin volatility for antimicrobial surface coating applications. Distribution runs through OEM direct sales for large-scale integrated lines and regional equipment distributors serving artisan-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU F-Gas refrigerant-phaseout deadlines and REACH chemical restrictions are forcing capital-constrained regional fabricators into distressed exit scenarios.
For Market Incumbents: Lock in captive metallurgy capabilities to guarantee antimicrobial alloy surface performance across extended duty cycles, insulating premium line contracts from nickel input volatility. Secure multi-vendor service aggregation partnerships to capture aftermarket revenue streams as procurement managers unbundle maintenance from initial equipment purchases. The priority lever centers on refrigeration-integration convergence, bundling thermal processing units to displace standalone cooking and freezing equipment procurement. For New Entrants and Emerging Players: CSRD-driven capital rotation in the Netherlands and Germany opens a window for ESG-linked financing advantages by qualifying lower-carbon processing infrastructure ahead of legacy competitors. Target supermarket in-store processing departments with compact, washdown-friendly designs requiring rapid changeover capabilities, the fastest-climbing specification tier. A direct go-to-market angle positions smart equipment with predictive maintenance algorithms as operational expenditure reductions rather than capital outlays. For Investors and Strategic Acquirers: Distressed asset sales among REACH-noncompliant coating specialists in Northern Europe is the leading indicator that regulatory compliance arbitrage opportunities are peaking. The viable acquisition archetype combines captive metallurgy with sensor-embedded automation engineering talent, scarce given shallow pools for dual USDA HACCP and EPA effluent-compliant mechanical designers. Watch for refrigerant supply concentration disruptions as the inflection signal that cold-chain retrofit demand is accelerating beyond incumbent capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Metallurgy | Guarantees antimicrobial alloy supply for premium beef processing lines in Germany and Brazil. |
| Refrigeration-Integration Bundling | Combines cooking and freezing equipment to displace standalone procurement in Northern European cold-chain retrofits. |
| Multi-Vendor Service Aggregation | Captures aftermarket revenue as Brazilian and German processors unbundle maintenance contracts. |
| ESG-Linked Financing Qualification | Secures capital allocation advantages under CSRD disclosure rules for lower-carbon infrastructure. |
| Sensor-Embedded Yield Optimization | Reduces yield loss in high-value beef operations despite grass-fed marbling accuracy gaps. |
Research Approach
Multi-period observation of equipment replacement cycles, refrigerant-phaseout compliance timelines, and antimicrobial alloy adoption rates anchored the trend analysis, supplemented by interviews with plant engineers at integrated poultry processors, procurement directors at German food manufacturers, aftermarket service heads at regional distributors, and regulatory affairs specialists at equipment OEMs. Secondary validation drew from EU F-Gas Regulation implementation reports, ECHA REACH substance-of-very-high-concern listings, USDA HACCP enforcement data, and customs records for nickel alloy feedstock trade flows. Bottom-up unit economics triangulated against top-down capital expenditure surveys across protein processing corridors.
Input-output matrix framing modeled equipment shipments, installed base depreciation, and technology substitution elasticities across the projection horizon. Segmentation dimensions included product type, application stage, end-user scale tier, and technology maturity level, with regional regulatory clusters treated as distinct demand shapers. CAGRs were derived from slope consistency checks against historical capital expenditure patterns and forward-looking procurement intention surveys. Industry-specific forecast inputs incorporated EU F-Gas retrofit deadlines and CSRD capital rotation disclosure requirements.
The model assumes a particular technology adoption path for sensor-embedded automation; alternative pathways for real-time fat-analysis sensor accuracy improvements would alter the outlook for premium equipment positioning. Forecasts reflect assumptions about regulatory enforcement intensity, alloy feedstock price stability, and labor-cost arbitrage thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Global Egg Processing Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Destoner Machine Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Global Square Straw Baler Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Oil Mill Machine Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Dal Mill Machine Market