
 GCC Poultry Meat Market | 2026-2036
GCC Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Poultry Meat Market Foresight
Fresh-chilled and antibiotic-free tier upgrades is rotating the GCC poultry trade toward higher-margin SKUs. Tanmiah Food Company leverages its vertically integrated hatchery-to-retail network across Saudi Arabia. Almarai Food Company anchors premium branded poultry through controlled cold-chain distribution in the UAE and Saudi markets. BRF S.A. competes via frozen processed poultry exports that occupy hypermarket freezer space across smaller Gulf states.
GCC poultry meat comprises avian muscle tissue harvested from broiler chickens, turkeys, and waterfowl, processed under halal slaughter protocols with specific pH, temperature, and microbial load parameters to ensure shelf stability and religious compliance. The product serves commercial food preparation, retail protein provisioning, and institutional nutrition programs across the Arabian Peninsula. Broiler chicken dominates volume throughput due to feed conversion efficiency and consumer familiarity, while turkey and quail segments attract premium positioning in hotel and resort channels. Foodservice application leads absolute demand as restaurant chains and catering operators standardize portion-controlled SKUs, whereas online retailers represent the fastest-growing distribution vector through same-day chilled delivery platforms.
Saudi Food and Drug Authority (SFDA) halal certification mandates and UAE Ministry of Climate Change and Environment import inspection protocols govern slaughter standards, residue testing, and labeling requirements across the Gulf. These frameworks elevate compliance costs for non-integrated traders while creating protected market access for certified domestic producers. Stakeholders must monitor evolving Gulf Standards Organization (GSO) harmonization talks, as unified technical regulations would reshape cross-border sourcing patterns and testing redundancy.
Market Dynamics
Hotel and resort procurement expansion across the Arabian Peninsula is compressing traditional wholesale channels while elevating margin capture for halal-certified chilled poultry suppliers with controlled cold-chain capabilities.
Growth Catalysts
- SFDA Halal Certification Mandates:Saudi Arabia's national food regulator enforces slaughter standards and microbial load protocols that protect domestic integrated producers from import competition.
- Foodservice SKU Standardization:Restaurant chains and catering operators across the Dubai-Abu Dhabi corridor are consolidating purchases around portion-controlled premium chilled lines.
- Same-Day Chilled Delivery Platforms:Online retailers in the UAE and Saudi Arabia are building captive cold-chain networks that bypass traditional distributor markups.
Market Restraints
- Feed Input Volatility:Soybean and corn price swings in global commodity markets transmit directly into broiler production cost structures across Gulf cooperative farms.
- Water Scarcity Constraints:Desalination-dependent agriculture in Qatar, Kuwait, and Bahrain limits domestic hatchery expansion and perpetuates import reliance.
- Slaughter Capacity Concentration:Processing infrastructure clusters in Saudi Arabia's Eastern Province and Riyadh, creating logistics bottlenecks for UAE and Oman distributors.
Strategic Opportunities
- Antibiotic-Free Tier Positioning:UAE Ministry of Climate Change and Environment residue-testing protocols create premium positioning for certified-clean supply chains in Dubai's hotel procurement.
- Quail and Turkey Premium Segments:Underdeveloped waterfowl categories in Kuwait and Bahrain offer margin expansion for specialized breeders with halal certification.
- GSO Harmonization Talks:Pending Gulf Standards Organization unified technical regulations would eliminate redundant cross-border testing for Saudi and UAE integrated producers.
Industry Challenges
- Halal Certification Timeline Compression:SFDA and UAE import inspection protocols require multi-stage documentation that delays product release for non-integrated traders.
- Cold-Chain Capex Intensity:Chilled poultry distribution requires continuous temperature monitoring infrastructure that strains mid-scale distributor balance sheets.
- Veterinary Talent Scarcity:Gulf veterinary schools produce insufficient halal slaughter certification specialists to match processing plant expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Poultry Meat Market |
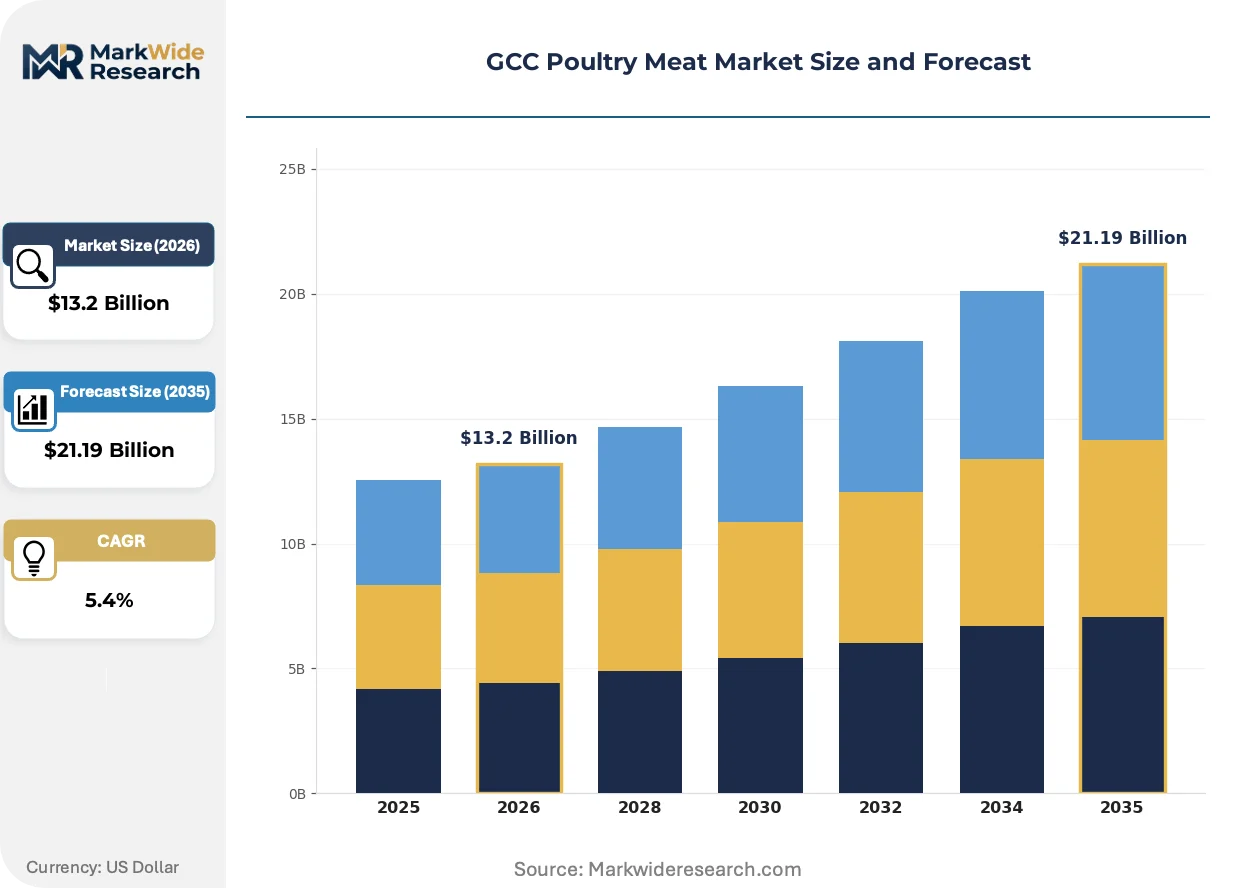
| Market Size in 2026 | $13.2 Billion |
| Market Size in 2035 | $21.19 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broiler Chicken, Turkey, Duck, Quail, Guinea Fowl Distribution Channel: Supermarkets, Hypermarkets, Local Butchers, Online Retailers, Foodservice Application: Household Consumption, Restaurants, Catering, Food Processing, Institutional Feeding Customer Type: End Consumers, Food Manufacturers, Wholesale Traders, Exporters, Hotels & Resorts |
| Companies Covered | Tanmiah Food Company, The Savola Group, Al-Watania Poultry, Fakieh Poultry Farms, Al Kabeer Group, Almarai Food Company, Emirates National Food LLC, Addoha Poultry, BRF S.A., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Poultry Meat Market Shifts & Advancements
Automation in slaughter and portioning is redrawing labor economics while blockchain traceability systems penetrate buyer qualification requirements across premium hotel and resort channels.
Robotic deboning and precision-cut portioning systems are fragmenting traditional manual processing labor pools in Saudi slaughterhouses. Five-star hotel chains in Jeddah and Riyadh now specify machine-cut consistency in procurement tenders. This technology compression is eroding cost advantages of low-wage import-dependent processing models.
UAE Ministry of Climate Change and Environment import inspection protocols now mandate blockchain-anchored halal certificates with timestamped slaughter documentation. Exporters to Dubai must integrate with approved traceability platforms or face automatic detention. Smaller Bahrain and Oman traders are consolidating through third-party certification agents to meet this compliance burden.
Foodservice operators in the Dubai-Abu Dhabi corridor are unbundling after-sales technical support from product supply contracts. Kitchen staff training on thawing protocols and yield optimization now sells separately through specialized culinary service firms. This service-layer separation is most visible in premium resort procurement where executive chefs demand documented HACCP compliance support.
GCC Poultry Meat Market Segmentation
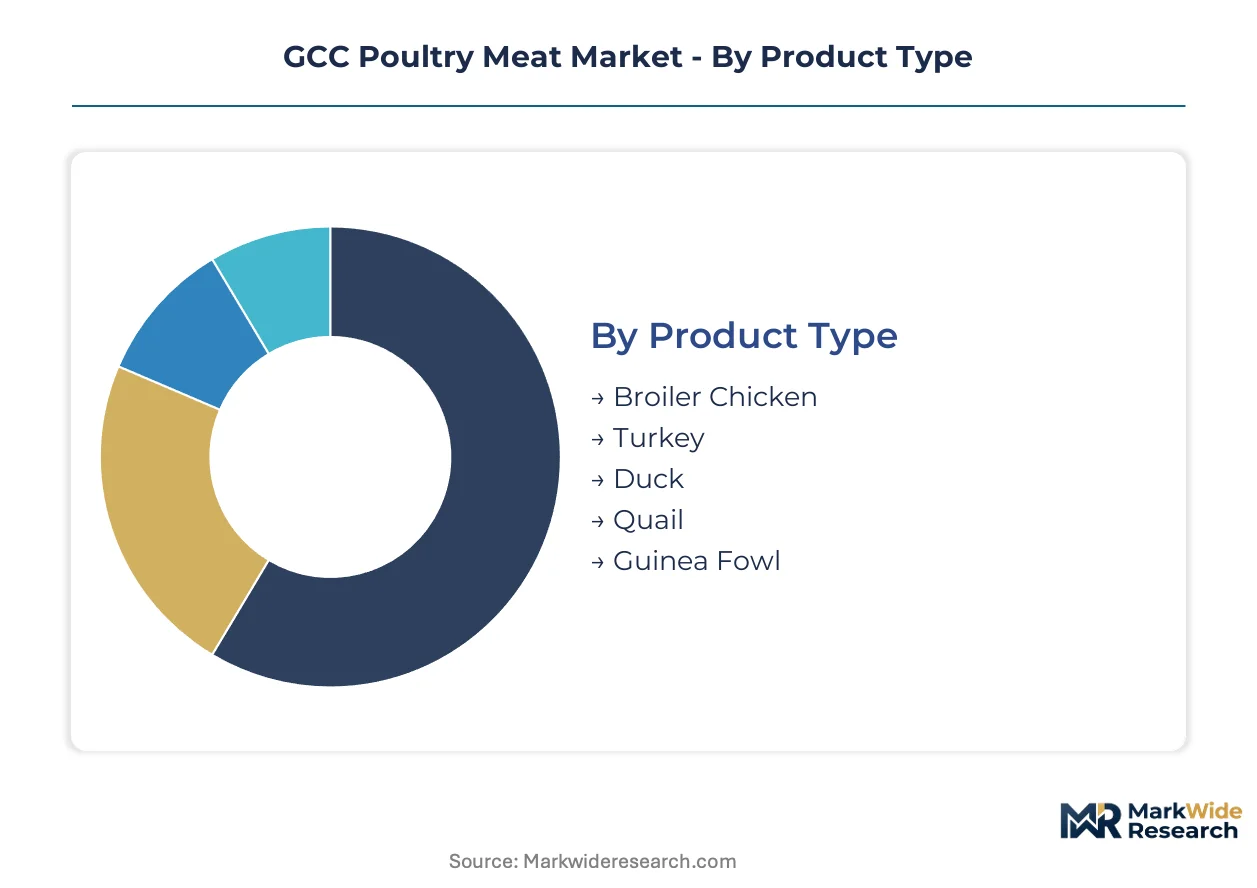
Segmentation in the GCC poultry meat market reveals how halal certification tiers, cold-chain infrastructure, and buyer procurement power fragment margin capture across species and channels. Each category exposes distinct competitive moats and vulnerability points for suppliers targeting the Arabian Peninsula.
Product Type:
Margin pools concentrate in species with feed conversion efficiency advantages and hotel channel premiumization potential.
- Broiler Chicken:Standard Cobb and Ross genetic lines dominate volume throughput with 1.6:1 feed conversion ratios under controlled-environment housing. Demand concentrates in Saudi Arabia's Qassim and Riyadh regions where integrated producers operate captive hatchery-to-slaughter networks, though margin compression from Brazilian frozen imports limits pricing power for non-certified traders.
- Turkey:Broad-breasted white varieties occupy premium positioning in Dubai's five-star hotel procurement tenders, with whole-bird and breast-muscle SKUs commanding chilled distribution premiums. UAE Ministry of Climate Change and Environment residue-testing protocols favor domestic integrated suppliers with antibiotic-free certification, rotating volume toward Jebel Ali corridor cold-chain operators.
- Duck:Pekin and Muscovy crosses serve niche Chinese restaurant demand in Dubai International City and Riyadh's Al-Murabba district.
- Quail:Coturnix japonica lines attract health-positioned retail in Kuwait's The Avenues mall food halls and Bahrain's City Centre hypermarkets.
- Guinea Fowl:Limited commercial breeding in Qatar's Al-Shahaniya cooperative farms supplies ceremonial occasion demand during Ramadan and Eid periods.
Broiler chicken holds installed capacity across Saudi Arabia's Eastern Province slaughter complexes. Turkey is rotating up the share rankings in UAE hotel procurement specifications.
Distribution Channel:
Cost tier stratification separates capital-intensive cold-chain operators from traditional wholesale markups.
- Foodservice:Portion-controlled IQF and chilled SKUs supply Dubai-Abu Dhabi corridor restaurant chains with standardized yield specifications and HACCP documentation bundles. Procurement consolidation around Al Islami, Americana, and regional catering operators compresses distributor margins while elevating supplier technical service requirements.
- Online Retailers:Same-day chilled delivery platforms in Riyadh and Jeddah bypass traditional three-layer distribution, building captive last-mile temperature monitoring infrastructure. Talabat, Jahez, and Noon Food vertical integration into poultry sourcing creates disintermediation pressure for legacy wholesale traders.
- Supermarkets:Carrefour, Lulu, and Panda retail networks standardize private-label chilled lines with SFDA halal certification front-of-pack.
- Hypermarkets:Bulk frozen Brazilian and Ukrainian imports occupy freezer space with price-competitive whole-bird positioning.
- Local Butchers:Traditional slaughterhall channels persist in Omani interior towns and Saudi Arabia's Asir region with live-bird selection and on-site processing.
Foodservice holds installed capacity through long-term catering contracts. Online retailers are climbing the fastest in share rankings with venture-funded cold-chain buildout.
Application:
Customer type maturity separates institutional procurement discipline from fragmented household purchasing.
- Restaurants:Quick-service chains and fine-dining operators across Kuwait's Salmiya and Bahrain's Seef districts specify chilled breast-muscle consistency with blockchain-anchored halal traceability. Kitchen staff training on thawing protocols and yield optimization now unbundles as a separate service layer in premium procurement.
- Catering:Hajj and Umrah seasonal demand concentrates in Mecca and Medina with mass-feeding portion control and 72-hour shelf-life requirements.
- Household Consumption:Weekly fresh purchases dominate Saudi and UAE retail with whole-bird and cut-up preferences varying by national origin.
- Food Processing:Further-processed nugget, patty, and sausage lines supply industrial kitchens in Qatar's Education City and Saudi Aramco residential compounds.
- Institutional Feeding:Military, prison, and hospital nutrition programs prioritize lowest-unit-cost frozen supply with basic halal documentation.
Restaurants hold installed capacity through brand-standard procurement manuals. Catering is expanding most quickly with religious tourism volume recovery.
Customer Type:
Supply concentration geography dictates procurement power asymmetries across buyer categories.
- Hotels & Resorts:Jeddah, Riyadh, and Dubai Palm Jumeirah properties specify machine-cut portion consistency with executive chef-level technical support requirements. Five-star procurement tenders now mandate robotic deboning certification and blockchain slaughter documentation as baseline qualification.
- Food Manufacturers:Further-processors in Saudi Arabia's Second Industrial City and Dubai Industrial Park demand volume-scale frozen supply with consistent specifications for nugget and patty production lines.
- End Consumers:Fragmented purchasing across national segments with freshness preference gradients between Emirati, Saudi, and expatriate households.
- Wholesale Traders:Bahrain and Oman distributors rely on Saudi Eastern Province slaughter capacity with logistics bottlenecks creating margin capture for cold-chain specialists.
- Exporters:Re-export trade from Jebel Ali Free Zone to East Africa and Central Asia faces GSO harmonization uncertainty on testing redundancy.
Hotels & Resorts hold installed capacity through multi-year supply agreements. Food Manufacturers are rotating up the share rankings with industrial kitchen automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Slaughter capacity concentrates in Saudi Arabia's Eastern Province and Riyadh, while UAE cold-chain operators capture premium margins through Dubai-Abu Dhabi corridor logistics. National regulators enforce divergent halal protocols that fragment cross-border sourcing patterns across the Arabian Peninsula.
Saudi Arabia
Qassim and Riyadh regions drive volume through integrated hatchery-to-retail networks serving domestic consumption and religious tourism feeding. SFDA halal certification mandates protect domestic producers from Brazilian frozen import competition. Eastern Province slaughter complexes process the majority of GCC broiler throughput, creating logistics bottlenecks for neighboring distributors.
United Arab Emirates
Dubai's five-star hotel procurement tenders specify machine-cut portion consistency with blockchain-anchored halal traceability requirements. UAE Ministry of Climate Change and Environment import inspection protocols mandate timestamped slaughter documentation for all chilled poultry entries. Jebel Ali Free Zone cold-chain operators increasingly supply re-export markets to East Africa and Central Asia.
Qatar
Desalination-dependent agriculture limits domestic hatchery expansion, perpetuating reliance on Saudi Eastern Province slaughter capacity. The country's national food security program subsidizes strategic grain reserves to buffer feed input volatility. Al-Shahaniya cooperative farms maintain limited commercial breeding for ceremonial occasion demand during Ramadan.
Kuwait
The Avenues mall food halls and Salmiya restaurant districts attract premium quail and antibiotic-free broiler positioning. Water scarcity constraints prevent meaningful domestic production scale, forcing import dependence on UAE and Saudi suppliers. Local distributors consolidate purchases around SFDA-certified chilled lines to satisfy retail private-label requirements.
Oman
Interior towns preserve traditional live-bird slaughterhall channels with on-site processing for freshness-preference households. Logistics bottlenecks from Saudi Eastern Province create margin capture opportunities for cold-chain specialists with temperature-controlled transport. The country's national food regulator maintains halal documentation requirements aligned with GSO harmonization talks.
GCC Poultry Meat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the GCC poultry meat market. Vertically integrated Saudi producers dominate volume throughput with captive hatchery-to-slaughter networks, while UAE-based cold-chain specialists capture premium positioning through controlled distribution infrastructure. Three strategic archetypes define competitive positioning: domestic integrated producers with regulatory protection, Brazilian and Ukrainian frozen exporters competing on price, and regional cold-chain operators building last-mile delivery platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as players respond to foodservice SKU standardization and online retail growth.
Within the domestic integrated tier, Tanmiah Food Company and Almarai Food Company exemplify archetypes with captive supply chain control from breeding through retail distribution. BRF S.A. represents the scale-driven import-export model, leveraging frozen processed poultry production for hypermarket freezer placement across smaller Gulf states. These three anchors illustrate how regulatory compliance burden and cold-chain capital requirements stratify competitive positioning between protected domestic operators and cost-optimized international suppliers.
| Leading Market Players |
|---|
| Tanmiah Food Company |
| The Savola Group |
| Al-Watania Poultry |
| Fakieh Poultry Farms |
| Al Kabeer Group |
| Almarai Food Company |
| Emirates National Food LLC |
| Addoha Poultry |
| BRF S.A. |
| Others |
Supply & Pricing Matrix
Eastern Province slaughter complex scale economies compress unit processing costs while elevating price floors for non-integrated traders lacking SFDA certification. This concentration dynamic protects domestic Saudi producers from Brazilian frozen import competition while forcing UAE distributors to absorb logistics premiums for chilled product access.
Pricing Analysis
SFDA halal certification mandates dictate the pricing tier structure across the GCC poultry trade. Three-tier pricing structure across premium chilled, standard frozen, and economy whole-bird levels separates antibiotic-free hotel procurement from bulk institutional supply. Price differentiation rests on certification grade and cold-chain integrity, with Dubai five-star properties least sensitive and Omani interior households most responsive to spot-price fluctuations. Cost compression in standard frozen tiers intensifies because Brazilian exporters leverage depreciated real exchange rates.
Supply Chain Analysis
Jebel Ali port congestion and container availability constraints on the Asia-Gulf trade lane elevate inbound logistics costs for non-regional suppliers. Geographic supply concentrates in Saudi Arabia, Brazil, and Ukraine, with raw material dependencies on Argentine soybean meal, US corn, and domestic hatchery genetics. Single-source vulnerability centers on Eastern Province processing infrastructure, which feeds from captive grain reserve programs. Distribution runs through layered wholesaler networks in Bahrain and Oman, bypassed by UAE same-day delivery platforms building captive last-mile cold chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based protein substitutes and cultivated meat ventures threaten medium-term displacement of conventional poultry in premium UAE foodservice channels. Incumbents must navigate this substitution pressure while defending halal-certified supply positions.
For Market Incumbents: Consolidate slaughter capacity control through backward integration into hatchery genetics and grain milling in Saudi Arabia's Qassim region. Deepen cold-chain captive supply to defend margin position against Brazilian frozen price erosion in hypermarket channels.
For New Entrants and Emerging Players: UAE Ministry of Climate Change and Environment blockchain traceability fast-track offers qualification acceleration for specialized quail and turkey breeders. Target Kuwait's The Avenues mall food halls with antibiotic-free positioning, leveraging third-party certification agents to bypass multi-stage documentation delays.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cold-chain operators with robotic deboning deployment and hotel procurement contract tenure. Long-term viability rests on automation capex recovery windows and religious tourism volume trajectories. Monitor GSO harmonization implementation as inflection signal for cross-border testing cost elimination.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Deboning Deployment | Five-star hotel chains in Jeddah and Dubai now specify machine-cut consistency in procurement tenders. |
| Blockchain Traceability Integration | UAE import inspection protocols mandate timestamped halal certificates for all chilled poultry entries. |
| Backward Integration into Hatchery Genetics | Tanmiah and Almarai leverage captive breeding programs to secure Cobb and Ross genetic line supply. |
| Same-Day Delivery Platform Buildout | Talabat and Jahez vertical integration creates disintermediation pressure for legacy wholesale traders. |
| Antibiotic-Free Certification Investment | UAE residue-testing protocols rotate hotel procurement toward certified-clean supply chains. |
Research Methodology
A standing panel of poultry processing plant managers, foodservice procurement directors at Dubai hotel chains, SFDA regulatory affairs specialists, and cold-chain logistics operators provided ongoing calibration across the research cycle. Primary interviews combined with secondary validation from Saudi customs trade data, SFDA halal certification registries, UAE Ministry of Climate Change and Environment import inspection records, and Gulf Standards Organization technical documentation. Bottom-up volume modeling and top-down value reconciliation ensured cross-method consistency.
Outputs were validated against external benchmarks including regional grain reserve disclosures, religious tourism feeding volume estimates, and venture-funded delivery platform capex announcements. Segmentation dimensions spanned species type, distribution channel, application, and customer procurement power across the modeling period. CAGRs were derived from installed capacity trajectories, regulatory implementation timelines, and technology adoption curves for automation and traceability systems.
Underlying assumptions cover stable feed input costs, sustained religious tourism recovery, and GSO harmonization progress, with deviation risk concentrated in Brazilian real volatility and desalination energy cost spikes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Sophora Japonica Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Forage Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Organic Feed Market