
 Livestock Carrier Market | 2026-2036
Livestock Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Livestock Carrier Market Foresight
Modular pen configurations and adjustable deck systems is shifting buyer choice toward vessels that handle multiple species without reconfiguration. Wellard leverages its integrated fleet ownership to control voyage scheduling across Australian export routes. Siba Ships anchors its position through specialized livestock vessel construction at European yards. Livestock Express differentiates via dedicated animal welfare staffing protocols on long-haul Middle East routes.
A livestock carrier is a purpose-built vessel or road vehicle designed to transport live animals across maritime or overland routes, featuring ventilated holds, non-slip decking, automated feeding systems, and waste management infrastructure rated for species-specific density limits. Its primary function is to move cattle, sheep, and other livestock from production centers to slaughter or breeding facilities while minimizing mortality and stress-induced weight loss. Medium-capacity carriers dominate revenue flows in maritime segments where port infrastructure constraints limit vessel sizing, while container-based road transport captures expanding share among dairy farmers seeking direct-to-farm delivery flexibility. Extra-large vessels serving Australian and South American export corridors concentrate margin pools through economies of scale on 20-plus-day voyages.
The Australian Maritime Safety Authority enforces strict vessel stability and ventilation standards that shape newbuild specifications for Pacific-Indian Ocean routes. The EU's Council Regulation 1/2005 on animal protection during transport mandates journey time limits and rest periods that constrain vessel routing options from European ports. Saudi Arabia's SFDA and the UAE's MOHAP coordinate live animal import health protocols that determine quarantine infrastructure requirements at destination. Stakeholders must monitor evolving national biosecurity frameworks and carbon intensity benchmarks for fleet renewal decisions.
Market Dynamics
The EU's updated Council Regulation on animal transport during sea journeys is compressing certification timelines for vessel operators while Australian and Brazilian exporters race to secure fleet capacity for Middle Eastern food security programs.
Growth Catalysts
- EU animal welfare mandates:The EU's Council Regulation 1/2005 on animal protection during transport is forcing fleet renewal toward vessels with automated ventilation and non-slip decking systems.
- Modular pen configurations:Adjustable deck systems that handle multiple species without reconfiguration are pulling buyer preference toward flexible-capacity vessels.
- Middle Eastern import programs:Saudi Arabia's SFDA and the UAE's MOHAP coordinate state-backed live animal procurement that sustains long-haul voyage demand.
Market Restraints
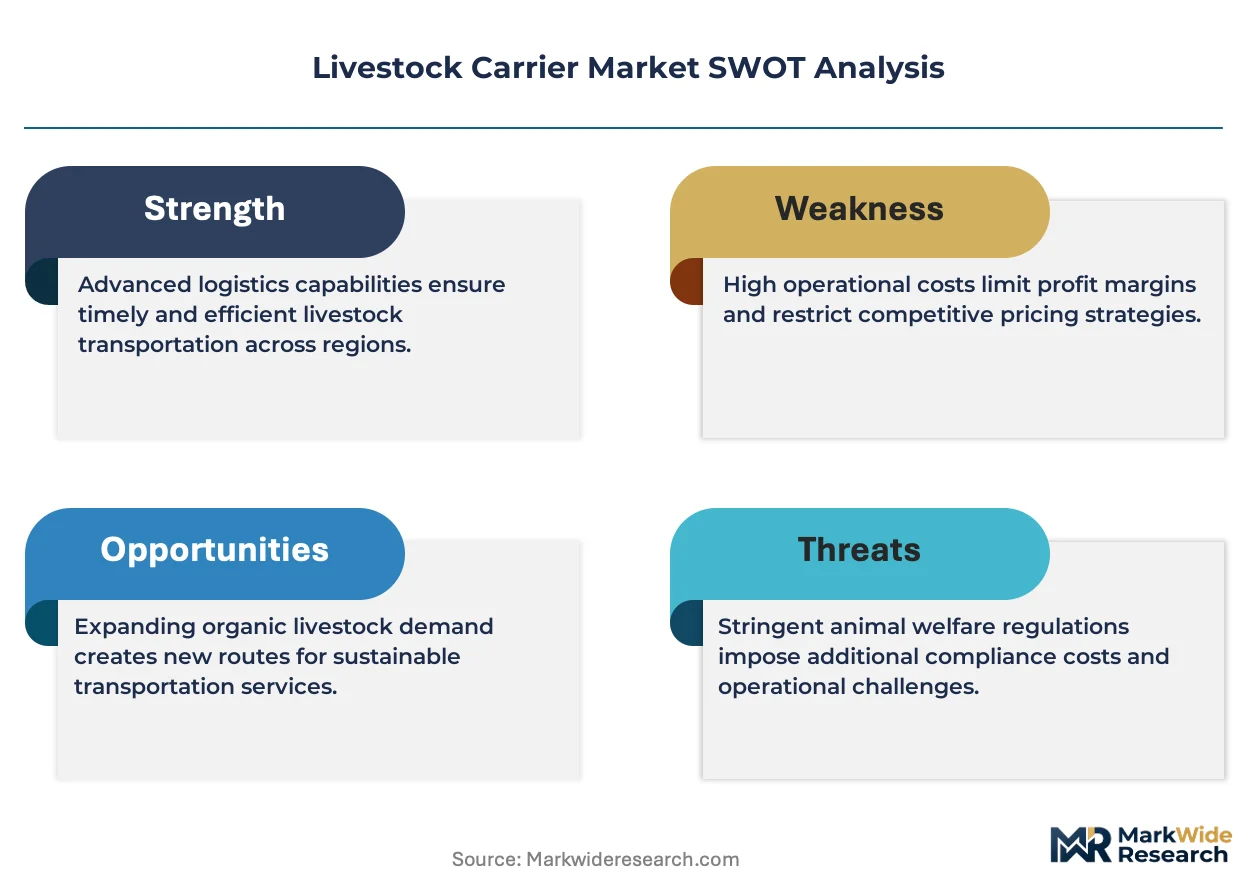
- Specialized steel and marine-grade aluminum volatility:Hull construction material costs fluctuate with commodity markets, squeezing newbuild margins for European and Asian yards.
- Australian route concentration:Pacific-Indian Ocean corridors dominate viable long-haul economics, leaving limited alternative voyage options during seasonal disruptions.
- Journey time limits:EU-mandated rest periods constrain routing flexibility from European ports, compressing feasible destination sets.
Strategic Opportunities
- Dairy farmer direct-to-farm delivery:Container-based road transport segments are capturing expanding share among producers seeking supply chain control.
- Carbon intensity benchmarking:Emerging fleet renewal frameworks in Australia and the EU favor early adopters of energy-efficient propulsion and waste management systems.
- Quarantine infrastructure partnerships:Destination port biosecurity investments in Saudi Arabia and the UAE create captive service revenue pools for integrated operators.
Industry Challenges
- Marine veterinary certification timelines:Australian Maritime Safety Authority stability and ventilation approvals require extended lead times that delay vessel deployment.
- Animal welfare staffing standards:Dedicated livestock handling protocols on 20-plus-day voyages demand specialized crew training programs with limited training provider pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Livestock Carrier Market |
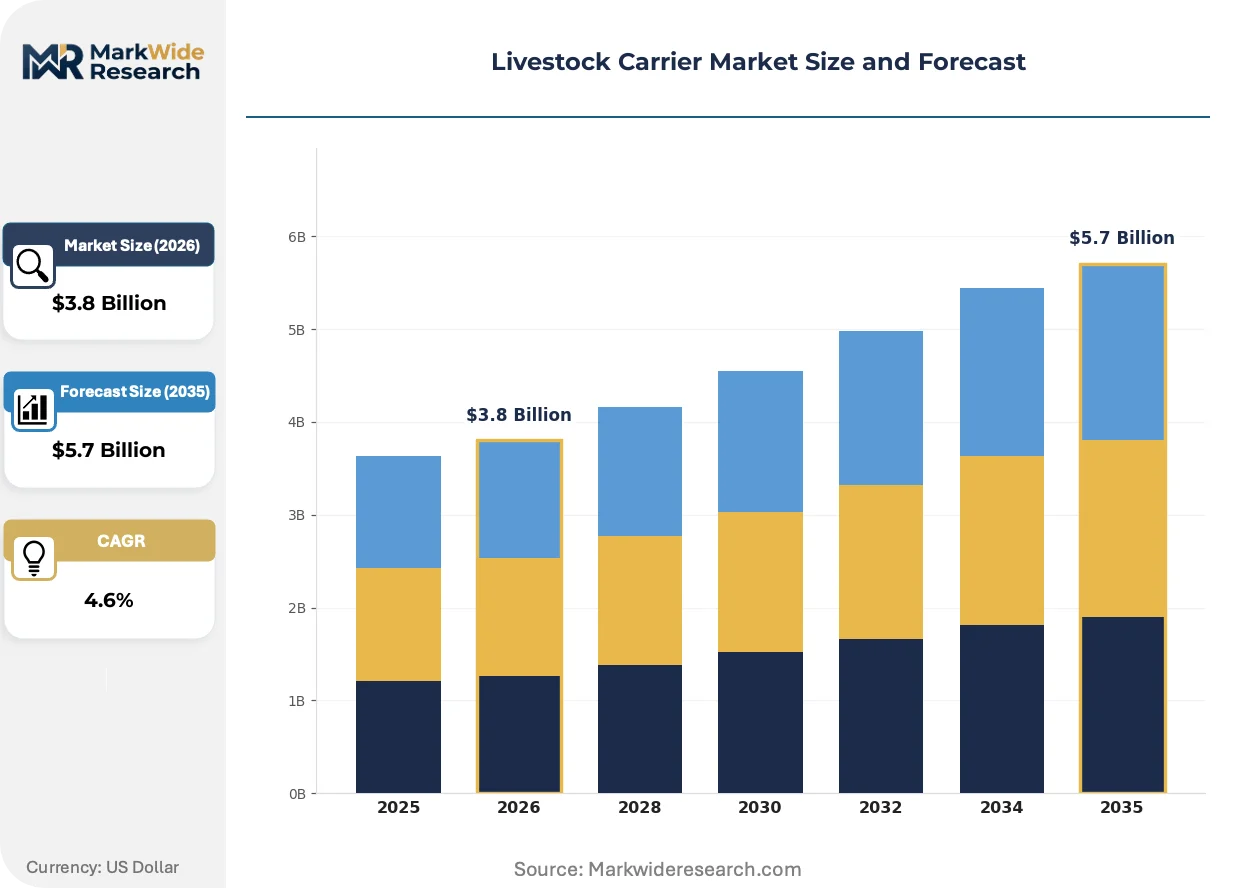
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Truck, Trailer, Van, Container Application: Transport, Export, Import, Logistics End User: Dairy Farmers, Meat Producers, Exporters, Transport Companies Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Siba Ships, AsstrA, Livestock Express, World Wide Livestock Express, Amigo Logistics, Wellard, Livestock Shipping Services, Kambara Kisen, Al Mawashi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Livestock Carrier Market Shifts & Advancements
Automation in feeding and waste management systems is compressing crew requirements while digital monitoring tools reshape voyage economics. Three developments are restructuring competitive positioning.
Sensor-integrated climate control systems that regulate temperature, humidity, and ammonia levels in real time are rewriting vessel operating economics. Australian export route operators are retrofitting existing fleets with these systems to reduce mortality rates and weight loss penalties. The technology is compressing the performance gap between newbuild specifications and secondhand vessel viability.
REACH chemical safety protocols and EU Green Deal carbon intensity benchmarks are tightening material specifications for vessel interiors and coating systems. European yard construction faces extended compliance verification that stretches delivery schedules. Australian and South American export corridors are absorbing the regulatory divergence by sourcing from yards with dual-certification capability.
Integrated voyage scheduling platforms that coordinate loading, feeding, and discharge windows are consolidating buyer relationships around fleet owners with captive terminal access. Traditional charter markets face displacement as exporters seek supply chain control. The shift concentrates contract volumes among operators with owned port infrastructure in Western Australia and Queensland.
Livestock Carrier Market Segmentation
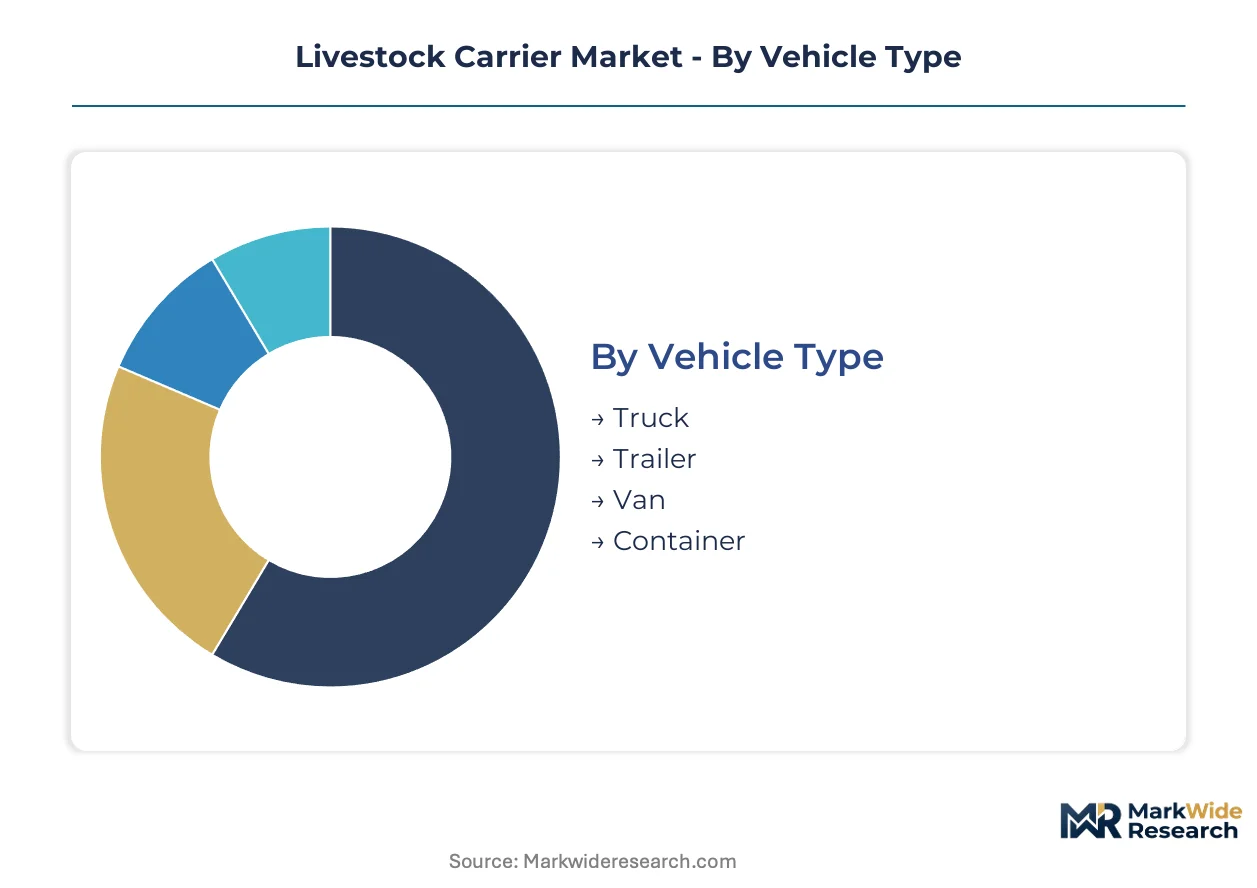
Livestock carrier procurement splits sharply between maritime fleet operators managing 20-day voyages and road-based distributors serving last-mile dairy supply chains. Each segment tier demands distinct certification regimes, crew competencies, and capital deployment timelines that reshape vendor economics.
Vehicle Type:
Buyers in this category diverge by route length and species mix, with maritime operators prioritizing hull stability certification while road distributors chase container interchangeability.
- Truck:Rigid-body configurations dominate short-haul dairy collection routes across Queensland and Victoria. Australian dairy farmers favor cab-over designs with hydraulic tail lifts for direct-to-farm access where farmgate infrastructure limits trailer maneuverability.
- Trailer:Articulated units with modular internal partitions capture expanding share among Brazilian meat producers exporting to Middle Eastern markets. The EU's Council Regulation 1/2005 mandates adjustable ventilation panels that trailer manufacturers now pre-install at European assembly plants.
- Van:Compact thermal-controlled units serve urban veterinary transport and high-value breeding stock movements. Saudi Arabia's SFDA requires GPS tracking integration for all van-class vehicles entering quarantine zones.
- Container:Intermodal boxes with climate control systems enable seamless rail-sea-road transfers. Australian exporters to UAE markets leverage container standardization to bypass port congestion at Fremantle and Dampier.
Volume sits with Trailer configurations serving export corridors; growth tilts toward Container systems capturing intermodal flexibility demand.
Application:
Application selection tracks regulatory exposure intensity, with export-facing operators absorbing the heaviest certification burdens while domestic logistics players optimize for turnaround velocity.
- Transport:Domestic movements of finished livestock from feedlots to processing facilities. Australian road operators face Australian Maritime Safety Authority cross-compliance checks when vehicles access port loading zones.
- Export:Long-haul maritime and overland movements to foreign slaughter or breeding facilities. Brazilian exporters to Saudi Arabia navigate SFDA health protocol verification that adds 48-72 hours to pre-loading timelines.
- Import:Inbound live animal procurement for domestic herd replenishment. UAE's MOHAP coordinates quarantine infrastructure requirements that determine viable vessel discharge windows at Jebel Ali and Khalifa Port.
- Logistics:Third-party coordination of multi-leg journeys across modal boundaries. Integrated operators with captive terminal access in Western Australia are consolidating contract volumes away from traditional charter markets.
Export commands the revenue pool; Logistics is climbing fastest as exporters seek supply chain control over voyage scheduling.
End User:
End user type determines financing structure and equipment ownership models, with corporate exporters favoring fleet ownership while smaller producers rely on contracted haulage.
- Dairy Farmers:Small-to-medium herd operators prioritizing animal welfare compliance for milk quality premiums. Direct-to-farm delivery flexibility drives preference for container-based road transport among Australian producers.
- Meat Producers:Feedlot operators and integrated processors managing live cattle supply chains. Brazilian meat producers expanding exports to Middle Eastern markets are securing dedicated vessel capacity amid tightening animal welfare protocols.
- Exporters:Specialist trading houses coordinating cross-border live animal movements. These operators absorb the full weight of EU Council Regulation compliance and destination quarantine negotiations.
- Transport Companies:Fleet operators providing contracted haulage services under shipper direction. Medium-capacity carriers dominate their maritime procurement where port infrastructure constraints limit vessel sizing.
Meat Producers hold the equipment investment lead; Transport Companies are expanding fastest as vertical disintegration spreads across export supply chains.
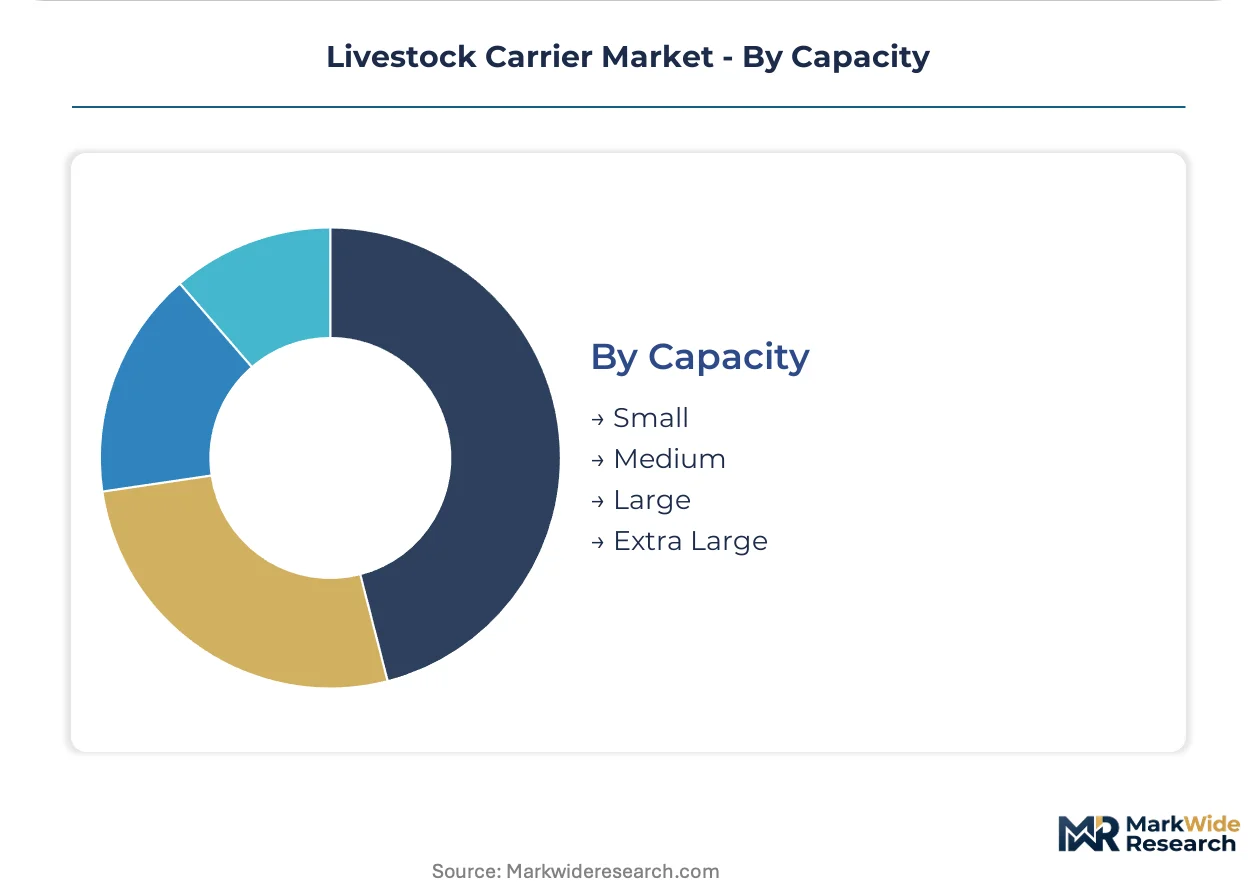
Capacity:
Capacity tier selection reflects port infrastructure constraints and voyage economics, with scale advantages concentrating in extra-large vessels while flexibility premiums accrue to smaller units.
- Small:Units under 500 square meters of deck space serving coastal island routes and niche breeding stock movements. Australian island-state operators use small carriers for Tasmania-mainland transfers under AMSA stability waivers.
- Medium:Configurations between 500-2,000 square meters dominating viable long-haul economics where draft limitations restrict larger vessels. Medium-capacity carriers generate dominant revenue flows across Pacific-Indian Ocean corridors.
- Large:Vessels exceeding 2,000 square meters serving high-volume Brazilian and Australian export routes. These units concentrate margin pools through economies of scale on extended voyages to Saudi Arabia and the UAE.
- Extra Large:Specialized newbuilds above 5,000 square meters with automated ventilation and waste management systems. EU animal welfare mandates are forcing fleet renewal toward this tier for European-flag operations.
Medium carriers anchor current fleet deployment; Extra Large vessels are gaining share fastest as Australian and Brazilian exporters race to secure capacity for Middle Eastern food security programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia and Brazil concentrate live cattle production for maritime export, while Saudi Arabia and the UAE drive import demand through state-backed food security programs. This production-to-consumption divide shapes vessel deployment patterns across Pacific-Indian Ocean corridors.
Australia
Fremantle and Dampier ports handle the majority of live cattle shipments to Middle Eastern markets under Australian Maritime Safety Authority oversight. AMSA enforces strict vessel stability and ventilation standards that reshape newbuild specifications for Pacific-Indian Ocean routes. Queensland feedlot operators coordinate loading windows with vessel operators to minimize pre-voyage holding periods.
Brazil
Meat producers in Mato Grosso and Goiás are expanding live cattle exports to Saudi Arabia and the UAE amid tightening animal welfare protocols. Brazilian exporters navigate extended pre-loading timelines for SFDA health protocol verification. Santos port infrastructure constraints limit vessel sizing, favoring medium-capacity carriers for Atlantic-Indian Ocean transits.
Saudi Arabia
The Saudi Food and Drug Authority coordinates state-backed live animal procurement that sustains long-haul voyage demand from Australian and Brazilian suppliers. Jeddah Islamic Port and King Abdullah Port feature dedicated quarantine infrastructure determining viable discharge windows. Riyadh-based procurement offices manage annual import tenders tied to domestic food security targets.
United Arab Emirates
MOHAP coordinates live animal import health protocols that determine quarantine infrastructure requirements at Jebel Ali and Khalifa Port. Dubai-based logistics operators are consolidating contract volumes through integrated voyage scheduling platforms. Abu Dhabi investment funds back port biosecurity upgrades that create captive service revenue pools for integrated vessel operators.
Netherlands
Rotterdam serves as a regulatory compliance hub for EU-flagged livestock vessels facing Council Regulation 1/2005 journey time limits. Dutch shipyards specialize in modular pen configurations and adjustable deck systems for multi-species handling. Eindhoven Region fabricators supply sensor-integrated climate control systems retrofitting existing fleets.
Livestock Carrier Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across vessel construction and voyage operations. Market structure tilts toward concentration among integrated fleet owners with captive terminal access, while fragmented charter markets face displacement. Three archetypes dominate: Australian route specialists with owned port infrastructure, European yard-affiliated constructors, and Middle Eastern destination-integrated operators. Competitive moves center on fleet renewal for EU animal welfare compliance and quarantine infrastructure partnerships at Saudi and UAE ports.
Among Australia-based integrated operators, Wellard exemplifies the fleet-ownership archetype controlling voyage scheduling across export corridors. European constructors are represented by Siba Ships, occupying a position tied to specialized livestock vessel construction at yards with dual-certification capability. Livestock Express anchors the dedicated animal welfare staffing tier for long-haul Middle East routes. These three companies collectively represent the strategic positioning vectors reshaping contract concentration away from traditional charter markets.
| Leading Market Players |
|---|
| Siba Ships |
| AsstrA |
| Livestock Express |
| World Wide Livestock Express |
| Amigo Logistics |
| Wellard |
| Livestock Shipping Services |
| Kambara Kisen |
| Al Mawashi |
| Others |
Supply & Pricing Matrix
Family-owned European shipyards with multi-generational yard histories anchor vessel construction supply, concentrating pricing power among yards with dual-certification capability for EU and Australian regulatory compliance. Their captive relationships with specialized steel and marine-grade aluminum distributors compress newbuild margins while sustaining premium pricing for vessels with automated ventilation systems.
Pricing Analysis
Margin tightening in extra-large vessel tiers reflects specialized steel and marine-grade aluminum commodity volatility squeezing European and Asian yard economics. Three-tier pricing structure across premium newbuilds, retrofitted medium-capacity carriers, and secondhand standard vessels stratifies buyer segments by certification grade and voyage automation level. Price erosion runs through standard-tier charter markets as integrated fleet owners with captive terminal access consolidate contract volumes away from fragmented operators. Dairy farmers and small-scale exporters exhibit highest price sensitivity, while state-backed Middle Eastern procurement programs absorb premium-tier vessel rates with limited elasticity.
Supply Chain Analysis
Hull construction materials rest on European and East Asian specialty steel producers, with marine-grade aluminum extrusion concentrated among German and South Korean fabricators. Sensor-integrated climate control systems draw from Eindhoven Region electronics clusters, while automated feeding mechanisms source from Dutch agricultural equipment specialists. Single-source vulnerability concentrates in European yard capacity for EU Council Regulation 1/2005 compliant newbuilds. Distribution runs through integrated vessel operators with owned port infrastructure in Western Australia and Queensland, displacing traditional charter brokerage channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-integrated climate control systems are displacing legacy manual ventilation and feeding infrastructure, compressing the performance gap between newbuild specifications and retrofitted secondhand vessels across Pacific-Indian Ocean export corridors.
For Market Incumbents: Cement fleet renewal pipelines by securing dual-certification yard slots for EU animal welfare compliance ahead of tightening Council Regulation timelines. Deepen upstream control over quarantine infrastructure partnerships at Jeddah Islamic Port and Khalifa Port to lock in captive service revenue pools against emerging destination-integrated competitors. For New Entrants and Emerging Players: Begin with container-based intermodal road transport segments serving Australian dairy farmers seeking direct-to-farm delivery flexibility, where fragmented haulage contracts and limited integrated operator presence create white-space opportunity. Target quarantine infrastructure service contracts at Saudi and UAE ports as a go-to-market angle that bypasses capital-intensive vessel ownership barriers. For Investors and Strategic Acquirers: EU Council Regulation 1/2005 enforcement timelines accelerating beyond 2026 are the leading indicator that fleet renewal demand will concentrate among yards with proven dual-certification track records. Position acquisition screening toward European constructors with modular pen configuration expertise and Australian route specialists with captive terminal infrastructure, watching AMSA stability approval backlogs as the signal for vessel deployment constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Renewal for EU Compliance | Automated ventilation and non-slip decking systems satisfy Council Regulation 1/2005 mandates for European-flag operations. |
| Quarantine Infrastructure Partnership | Captive terminal access at Jeddah Islamic Port and Khalifa Port secures discharge window priority for long-haul voyages. |
| Sensor-Integrated Climate Control Retrofit | Real-time ammonia and humidity monitoring reduces mortality penalties on Australian export routes to Saudi Arabia. |
| Container-Based Intermodal Expansion | Standardized climate-controlled boxes bypass Fremantle and Dampier congestion for UAE dairy supply chains. |
| Modular Pen Configuration Development | Adjustable deck systems enable multi-species handling without reconfiguration, capturing flexible-capacity vessel demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews involving livestock vessel operators, Australian Maritime Safety Authority certification officers, Middle Eastern port quarantine managers, and European shipyard procurement leads. Australian Bureau of Agricultural and Resource Economics export statistics, EU Council Regulation implementation notices, and Saudi Food and Drug Authority import tender documentation supplied volume and route-specific benchmarks. Bottom-up vessel deployment tracking across Pacific-Indian Ocean corridors reconciled against top-down market value estimates.
Segment-level modeling deployed capacity-tier granularity for small through extra-large vessel classes, with application splits across transport, export, import, and logistics functions. End-user economics differentiated dairy farmer direct-to-farm delivery patterns from meat producer long-haul export procurement. Vehicle type segmentation captured truck, trailer, van, and container intermodal dynamics. CAGRs derived from vessel orderbook analysis and port throughput projections across the analysis window, with regulatory compliance cost curves and steel price volatility indices informing margin trajectory assumptions.
EU animal welfare mandate enforcement delays, Australian route weather disruptions, and Middle Eastern import policy recalibrations are the dominant revision risks to fleet deployment timelines. Forecasts reflect documented assumptions on certification timeline compression and commodity input cost trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
Russia Horse Riding Equipment Market
Livestock Equipment
Animal Feeding Equipment Market
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Automated Feeding System Market
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Cow Lifting Harness Market
Livestock Equipment
Starter Feed Market
Livestock Equipment
Automatic Cattle Waterer Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Silage Tube Market
Livestock Equipment
Milking Equipment Market
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Europe Livestock Monitoring Market