
 Ski Gear and Equipment Market | 2026-2036
Ski Gear and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ski Gear and Equipment Market Intelligence
Market Context with Strategic Players
Capital-intensity divergence between in-house composite manufacturing and outsourced assembly is redrawing competitive tiers in ski gear. K2 Sports leverages captive carbon fiber layup facilities to control ski flex profiles from raw prepreg through finished laminate. Amer Sports anchors its premium pricing through proprietary binding integration systems that reduce field-adjustment failure rates. Atomic Austria GmbH dominates race-stock production with tight vertical control over Austrian wood core sourcing and CNC milling operations.
Technical Definition and Structural Segments
Ski gear and equipment encompasses engineered snow-sport products built from laminated sandwiches of fiberglass, carbon fiber, wood cores, and steel edges, with torsional rigidity measured in Newton-meters per degree of twist and dampening tuned through rubber or elastomer interlayers for controlled vibration absorption at speed. The category serves commercial purposes spanning recreational resort skiing, competitive alpine racing, backcountry touring, and terrain park freestyle. Skis and snowboards claim the dominant revenue share due to replacement cycles tied to edge wear and base degradation, while carbon fiber material grades command margin premiums as athletes and advanced skiers trade up for reduced swing weight. Rental shops represent a structurally growing distribution channel as destination resorts outsource fleet ownership to specialized operators who negotiate volume procurement contracts directly with manufacturers.
Regulatory Frame and Forward-Looking Close
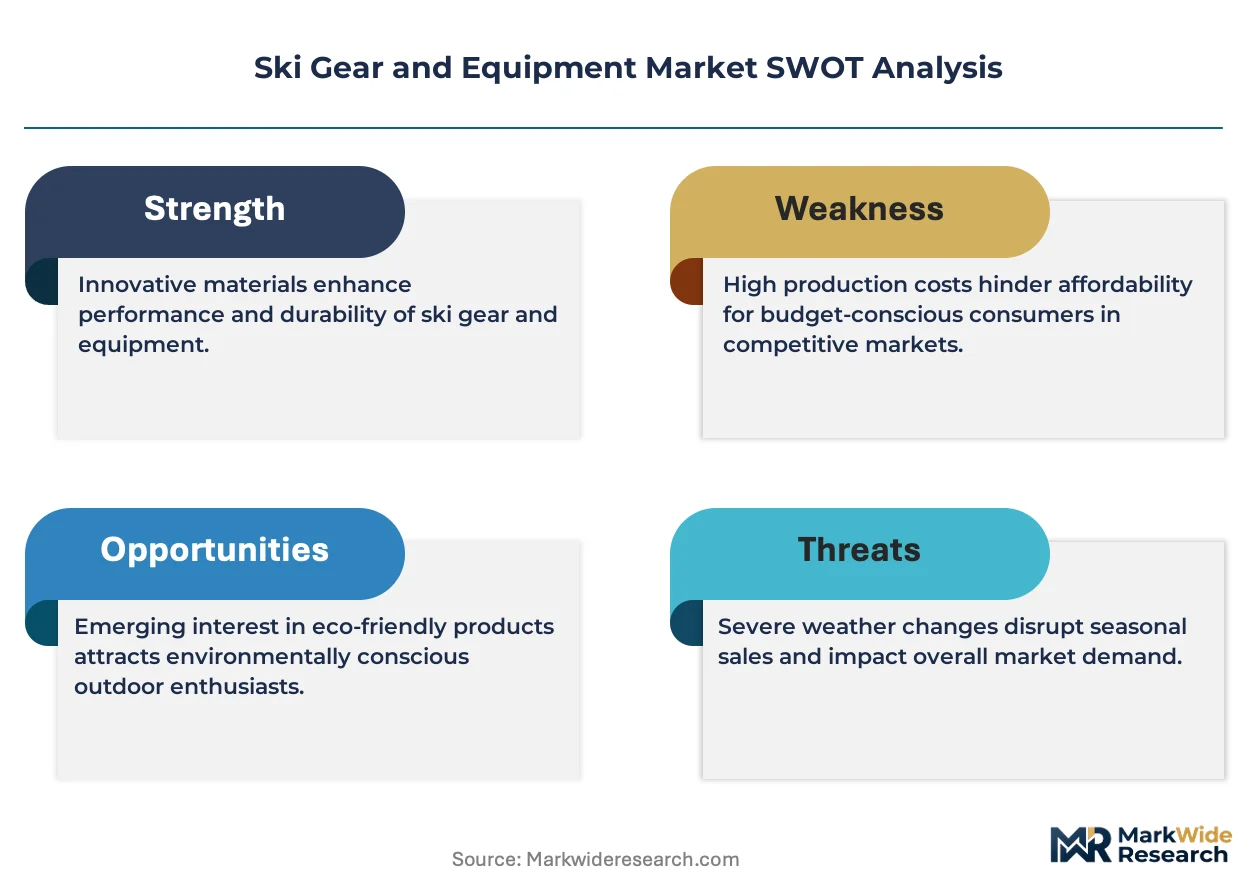
The EU F-Gas Regulation and REACH chemical restrictions are forcing reformulation of ski base waxes and topsheet resins, compelling manufacturers to certify alternative fluorocarbon-free compounds through ECHA-registered testing protocols. The EPA in the United States monitors per- and polyfluoroalkyl substance discharge from composite manufacturing, adding compliance cost layers for brands with North American production footprints. Stakeholders must monitor how binding release torque standards evolve under ISO 9462 and DIN 7881 revisions, as liability exposure shifts with each incremental tightening of retention-safety thresholds.
Market Dynamics
The EU Green Deal's fluorinated wax ban is forcing manufacturers to rebuild base material supply chains from raw chemistry through finished product certification, compressing R&D timelines while opening premium positioning for early bio-based compound adopters.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon production under EU F-Gas Regulation is redirecting capital toward plant-based paraffin and hydrocarbon wax alternatives, creating first-mover advantages for certified suppliers.
- Destination resort rental consolidation:Specialized fleet operators in the French Alps corridor are negotiating direct procurement contracts that bypass traditional wholesale distribution, expanding manufacturer margin capture.
- Carbon fiber grade advancement:T700 and T800 modulus fiber availability from Toray and Hexcel is enabling swing weight reduction in all-mountain skis without torsional rigidity loss.
Market Restraints
- Wood core supply concentration:Race-stock and premium ski production depends on tight vertical control over Austrian beech and poplar sourcing, exposing brands to harvest cycle volatility and regional climate impacts.
- Binding release torque recertification:Pending ISO 9462 and DIN 7881 revisions require full indemnification testing for existing inventory, creating stranded certification costs and liability exposure.
- Per- and polyfluoroalkyl substance monitoring:EPA discharge oversight of composite manufacturing in the United States adds compliance layers for brands with captive North American production facilities.
Strategic Opportunities
- Backcountry touring equipment:Alpine touring bindings and pin-tech systems represent underpenetrated white space as recreational skiers migrate from resort lift access to human-powered ascent models.
- CSRD-aligned sustainability reporting:The EU Corporate Sustainability Reporting Directive creates competitive differentiation for manufacturers with verified Scope 3 supply chain data and circular design protocols.
- Direct-to-consumer channel expansion:Subscription-based ski lease programs and seasonal refresh models are capturing younger demographics outside traditional specialty retail.
Industry Challenges
- Composite layup technician scarcity:Captive carbon fiber prepreg handling and autoclave operation require specialized craft skills concentrated in Austrian and German manufacturing clusters, constraining production scaling.
- ECHA registration timelines:Alternative fluorocarbon-free base compounds must complete REACH chemical safety dossiers before commercial deployment, extending reformulation cycles.
- Legacy binding mount pattern incompatibility:Proprietary integrated binding systems fragment aftermarket upgrade paths, complicating inventory planning for rental fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ski Gear and Equipment Market |
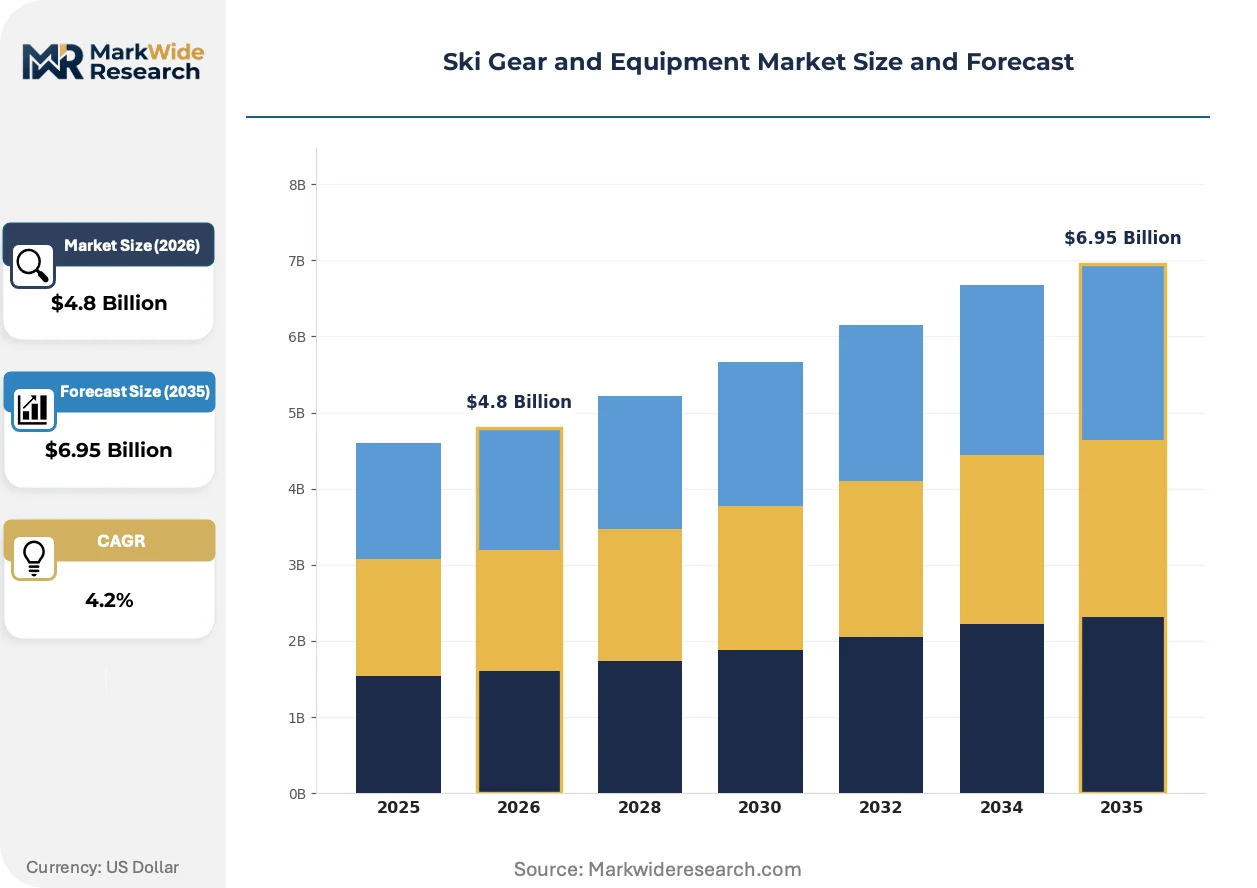
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skis, Snowboards, Boots, Poles Material: Fiberglass, Carbon Fiber, Wood, Aluminum End User: Recreational Skiers, Professional Athletes, Children, Beginners Distribution Channel: Online Retail, Specialty Stores, Department Stores, Rental Shops |
| Companies Covered | K2 Sports, Head Skis, Amer Sports, Black Diamond, Atomic Austria GmbH, Groupe Rossignol, Fischer Beteiligungsverwaltungs GmbH, Blizzard Sport GmbH, Tecnica Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ski Gear and Equipment Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry mandates are converging to reshape product architecture, with bio-based substitutes gaining performance parity and procurement models fragmenting traditional channel structures.
Fluoro-free base materials incorporating ceramic microspheres and plant-derived hydrocarbons are achieving glide coefficients comparable to perfluorinated waxes across variable snow temperatures. Austrian and German race departments are validating these compounds for World Cup use during the 2024-2025 competition season. The technology is supplanting century-old paraffin-fluorocarbon blending as the default formulation for premium ski bases.
REACH chemical restrictions and the EU F-Gas Regulation are compelling reformulation of topsheet resins and base waxes through ECHA-registered testing protocols. Manufacturers must certify alternative compounds for skin contact safety and environmental persistence before commercial release. Race-stock production lines in Salzburg and Innsbruck are experiencing the most acute compliance timeline pressure.
Rental fleet operators are consolidating procurement through specialized third-party managers who negotiate volume contracts directly with manufacturers, disintermediating traditional wholesale distributors. This channel restructuring concentrates buying power in fewer hands while demanding custom fleet specifications and integrated maintenance service bundles. The French Alps corridor exhibits the most advanced operator consolidation, with Chamonix and Val d'Isère clusters leading contract innovation.
Ski Gear and Equipment Market Segmentation
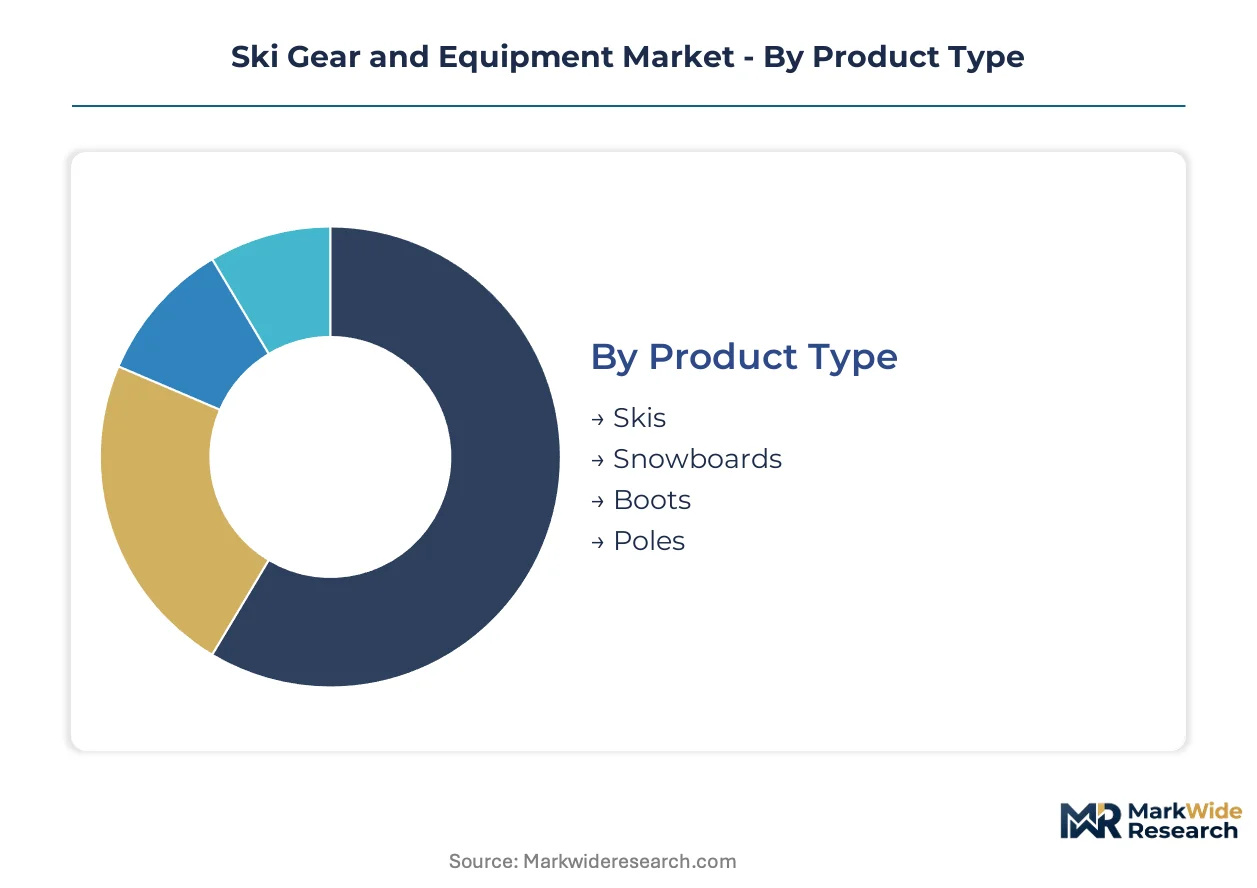
Ski gear segmentation reveals how product architecture, material grades, and user sophistication map to distinct procurement channels. Channel-mix patterns determine margin capture and inventory velocity for manufacturers and retailers alike.
Product Type:
Specialty stores dominate premium ski and snowboard sales, while rental shops capture high-turnover recreational equipment and department stores anchor entry-level price tiers.
- Skis:Laminated sandwich construction of fiberglass, carbon fiber, and wood cores with steel edges defines performance characteristics. French Alps rental fleet operators negotiate direct volume contracts for all-mountain and carving models, bypassing wholesale intermediaries.
- Snowboards:Directional and twin-tip profiles serve freestyle and freeride disciplines with distinct flex patterns and sidecut radii. Demand concentrates in North American resort corridors where terrain park infrastructure drives replacement cycles among younger demographics.
- Boots:Thermoplastic polyurethane shells with heat-moldable liners and adjustable cuff geometry.
- Poles:Aluminum and carbon fiber shafts with ergonomic grips and carbide tips.
By volume, Skis leads. By growth pace, Snowboards is climbing the fastest among hardgoods categories.
Material:
Cost tiers stratify sharply across material grades, with carbon fiber commanding premium positioning and fiberglass anchoring mass-market production.
- Carbon Fiber:T700 and T800 modulus grades from Toray and Hexcel enable swing weight reduction without torsional rigidity loss. Professional athletes and advanced recreational skiers in Austrian and German manufacturing clusters drive specification upgrades.
- Wood:Austrian beech and poplar cores provide dampening and longitudinal flex control. Race-stock production lines depend on tight vertical control over regional harvest cycles, exposing brands to climate-driven supply volatility.
- Fiberglass:E-glass and S-glass weaves form the structural backbone of entry-level and mid-tier skis.
- Aluminum:Extruded and drawn alloys serve pole shafts and binding components.
Carbon Fiber captures the highest margin tier. Fiberglass maintains the largest production volume across all price segments.
End User:
Application intensity varies dramatically across user types, from occasional resort visitors to daily training regimens.
- Recreational Skiers:Weekend and vacation skiers using rental fleets or owned equipment for groomed-trail skiing. French Alps destination tourism sustains premium equipment pull through rental shop procurement and direct-to-consumer lease programs.
- Professional Athletes:World Cup competitors and sponsored athletes requiring race-stock specifications. Austrian race departments validate fluorocarbon-free base compounds for competition use, driving material science adoption downstream.
- Children:Growing users requiring frequent size progression and durability-focused construction.
- Beginners:First-time skiers prioritizing rental access and forgiving flex profiles over performance characteristics.
Recreational Skiers generate the highest absolute revenue. Professional Athletes set the technology trajectory that filters to broader markets.
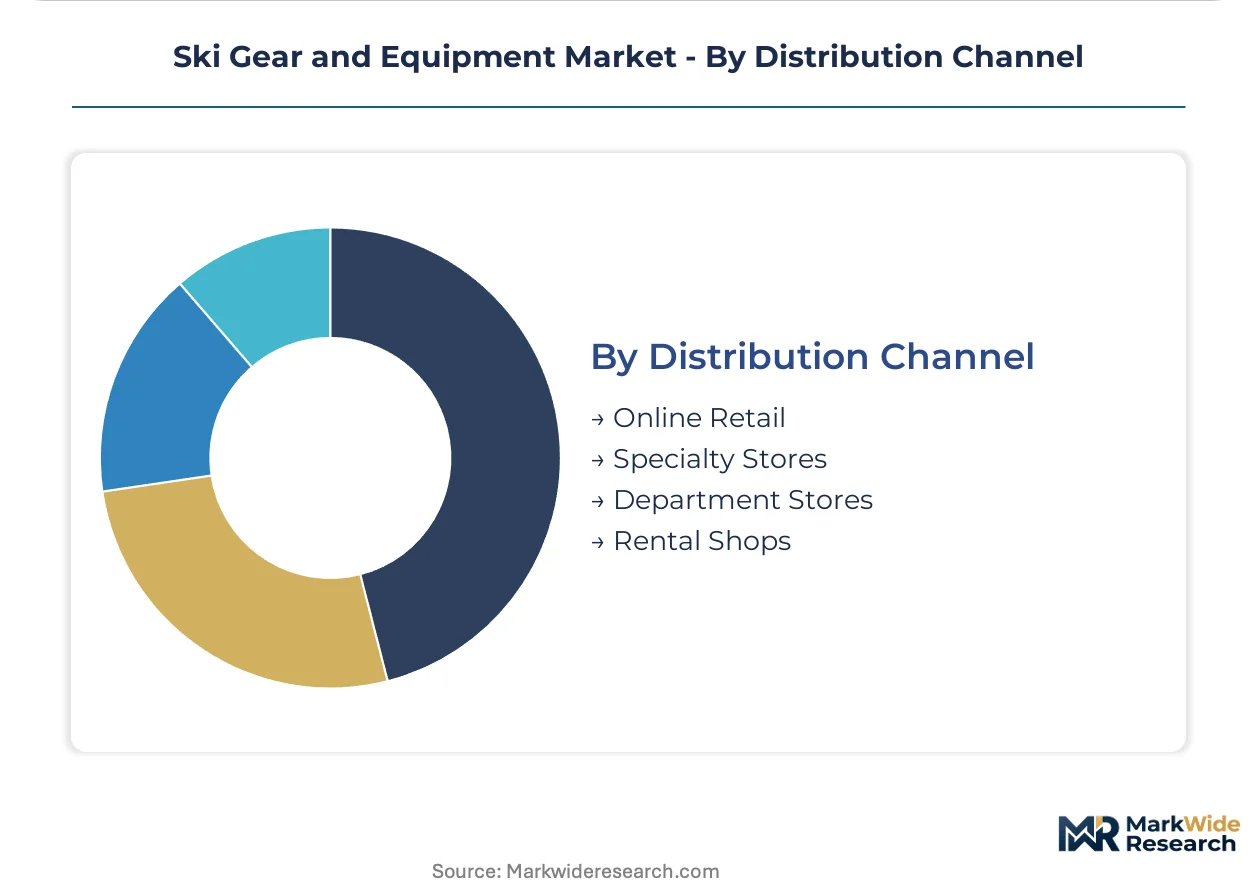
Distribution Channel:
Customer type and purchase frequency reshape channel economics, with subscription models disrupting traditional ownership patterns.
- Rental Shops:Specialized fleet operators consolidate procurement through direct manufacturer contracts. Chamonix and Val d'Isère clusters lead contract innovation with integrated maintenance service bundles.
- Specialty Stores:Independent retailers with boot-fitting expertise and binding mount services. These outlets capture premium ski and boot combinations through technical consultation and custom specification.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators serving replacement part and accessory demand.
- Department Stores:Mass-market retailers with seasonal ski equipment programs targeting entry-level buyers.
Rental Shops are expanding share fastest. Specialty Stores retain the highest margin capture per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in ski gear track manufacturing concentration against destination resort demand. Austrian and German producers supply premium equipment to North American and Asian markets while importing raw carbon fiber from Japan and the United States.
United States
Destination resort infrastructure in Colorado and Utah drives equipment turnover through rental fleet renewal cycles. EPA discharge oversight of composite manufacturing adds compliance layers for domestic production facilities. The Pacific Northwest hosts specialized carbon fiber prepreg handling operations serving premium ski assembly.
Germany
Bavarian manufacturing clusters anchor race-stock production with tight control over wood core sourcing and CNC milling operations. REACH chemical restrictions compel reformulation of topsheet resins through ECHA-registered testing protocols. The Black Forest region concentrates binding system integration and quality certification facilities.
France
Destination tourism in the French Alps corridor sustains premium equipment pull through rental shop procurement and direct-to-consumer lease programs. EU F-Gas Regulation phases down hydrofluorocarbon production in base wax formulations. Chamonix and Val d'Isère clusters lead contract innovation with integrated maintenance service bundles.
Austria
Salzburg and Innsbruck production lines experience acute compliance timeline pressure from fluorocarbon-free compound certification. The EU Green Deal redirects R&D budgets toward bio-based base materials for race-stock validation. Austrian beech and poplar harvest cycles expose brands to climate-driven supply volatility in regional wood core sourcing.
Japan
Toray and Hexcel supply T700 and T800 modulus carbon fiber enabling swing weight reduction in all-mountain skis. METI standards govern material safety certification for imported equipment. Hokkaido resort development expands distribution channel demand for rental fleet operators.
Ski Gear and Equipment Market Key Industry Players
Concentration sits with vertically integrated specialists controlling raw material conversion through finished laminate production. Austrian and German manufacturing clusters host captive carbon fiber layup facilities and autoclave operations that constrain production scaling. Three archetypes dominate: composite manufacturing integrators with in-house prepreg handling, binding system specialists with proprietary integration protocols, and race-stock producers with tight vertical control over regional wood sourcing. Competitive moves center on direct procurement contract negotiation with rental fleet operators and fluorocarbon-free compound certification for premium positioning.
Among Austrian-based fabricators, Atomic Austria GmbH and Fischer Beteiligungsverwaltungs GmbH occupy positions within the race-stock production tier. K2 Sports exemplifies the composite manufacturing integrator archetype with captive carbon fiber operations. Amer Sports anchors the binding system specialist category through proprietary integration approaches.
| Leading Market Players |
|---|
| K2 Sports |
| Head Skis |
| Amer Sports |
| Black Diamond |
| Atomic Austria GmbH |
| Groupe Rossignol |
| Fischer Beteiligungsverwaltungs GmbH |
| Blizzard Sport GmbH |
| Tecnica Group |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Austrian autoclave facilities shapes margin floors across premium ski tiers, concentrating pricing power among manufacturers with in-house carbon fiber prepreg handling while compressing returns for outsourced assembly operations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates race-stock T800 carbon fiber specifications from rental fleet E-glass constructions, with brand premium and ISO 9462 certification tier as secondary drivers. Pricing pressure stems from EPA discharge compliance costs at North American production facilities. Rental fleet operators exhibit highest price sensitivity, while World Cup race departments demonstrate lowest elasticity.
Supply Chain Analysis
Austria and Germany anchor race-stock ski production through captive wood core milling and composite layup operations. Raw material inputs draw from Japanese Toray T700/T800 carbon fiber, Austrian beech and poplar harvests, and ECHA-registered fluorocarbon-free wax compounds. Single-source vulnerability concentrates in regional wood core sourcing exposed to climate-driven harvest volatility. Distribution runs through direct manufacturer contracts with consolidated rental fleet operators in the French Alps corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ski gear demand tracks destination resort visitation cycles, with French Alps tourism recovery and North American season pass growth supporting equipment turnover expansion.
For Market Incumbents: Compound defensive positioning through captive carbon fiber prepreg handling and autoclave capacity expansion in Salzburg manufacturing clusters. Secure long-term Austrian beech and poplar supply agreements to mitigate harvest cycle volatility. Accelerate ECHA-registered fluorocarbon-free compound certification to capture premium positioning ahead of EU F-Gas Regulation enforcement. For New Entrants and Emerging Players: Anchor in backcountry touring equipment white space, specifically alpine touring bindings and pin-tech systems serving recreational skiers migrating from resort lift access. Target direct-to-consumer subscription lease programs in North American mountain towns. Pursue CSRD-aligned sustainability reporting differentiation to unlock EU procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors composite manufacturing integrators with backward integration into carbon fiber conversion and race-stock producers with tight vertical control over regional wood sourcing. Long-term viability hinges on fluorocarbon-free material science leadership and rental fleet direct contract penetration. Monitor EU F-Gas Regulation enforcement timelines as inflection indicator for bio-based compound adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorocarbon-Free Compound Certification | ECHA-registered bio-based wax validation unlocks premium positioning under EU F-Gas Regulation constraints. |
| Direct Rental Fleet Contracting | Chamonix and Val d'Isère operator consolidation enables margin capture bypassing wholesale distribution. |
| Carbon Fiber Grade Advancement | T800 modulus adoption from Toray reduces swing weight without torsional rigidity compromise. |
| Backcountry Touring Expansion | Pin-tech binding systems address underpenetrated human-powered ascent equipment demand. |
| CSRD Sustainability Reporting | Verified Scope 3 supply chain data creates competitive differentiation in EU procurement. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed equipment manufacturers, EU ECHA chemical registration databases, and destination resort visitation statistics. Primary interviews engaged composite manufacturing engineers, rental fleet procurement managers, alpine racing program directors, and specialty retail buyers. Bottom-up equipment shipment analysis triangulates against top-down resort expenditure modeling.
Segmentation dimensions modeled include product architecture tier, carbon fiber material grade, end-user application intensity, and distribution channel structure across the analysis window. CAGRs derive from equipment replacement cycle analysis, rental fleet renewal scheduling, and material cost trajectory assumptions. Race-stock production volume and fluorocarbon-free compound adoption velocity serve as industry-specific forecast inputs.
Material uncertainties — regulatory enforcement timing, harvest cycle disruption, and binding torque standard revision — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and North American resort infrastructure investment. Recalibration cycles align with material shifts in fluorocarbon-free certification timelines and rental fleet consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market
Outdoor and Adventure Activities
Fat Bike Market