
 Recreation Services Market | 2026-2036
Recreation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Recreation Services Market Analytics
Market Context
Digital ticketing platforms are restructuring revenue capture across the recreation services landscape, replacing legacy gate-based models with dynamic yield management. Merlin Entertainments Group leverages its portfolio of branded attractions to sustain premium pricing power across European and North American markets. The Walt Disney Company anchors its competitive position through backward integration into content, streaming, and experiential retail that drives repeat visitation. Live Nation Entertainment controls live event distribution infrastructure, extending its reach from ticket sales into artist management and venue operations.
Technical Definition and Segment Structure
Recreation services encompass the organized provision of leisure, entertainment, fitness, and experiential activities delivered through staffed facilities, guided programs, or ticketed events, typically measured by visitor throughput, occupancy rates, and per-capita spending metrics. The primary commercial purpose centers on converting discretionary time and household entertainment budgets into monetized experiences through controlled-access environments. Adventure sports and aquatic services command the highest marginal returns due to equipment intensity and specialized staffing requirements, while community recreation programs occupy the volume tier supported by municipal subsidy structures. Fitness programs compete for share against digital home alternatives, pressuring facility operators to differentiate through hybrid coaching models and social programming.
Regulatory Framework and Outlook
FDA guidelines on pool sanitation and water quality govern aquatic service operators, while OSHA standards shape staffing ratios and safety protocols for adventure sports and climbing facilities. EPA regulations on chemical handling and waste discharge constrain operational design for water parks and outdoor recreation sites, elevating compliance costs for smaller independents. Stakeholders must monitor evolving municipal liability frameworks and accessibility mandates that threaten to reshape capital deployment timelines for new facility development.
Market Dynamics
AI-driven personalization engines are restructuring how recreation providers engage customers and optimize capacity utilization across ticketed attractions and membership-based facilities. This technology shift compresses booking friction while expanding yield management precision.
Growth Catalysts
- OSHA Safety Protocol Expansion:Federal workplace wellness mandates in the United States are accelerating employer procurement of team-building and stress-reduction programs from commercial recreation operators.
- Dynamic Yield Algorithms:Machine learning models for real-time pricing are enabling water parks and ski resorts to capture marginal demand during off-peak windows.
- Municipal Subsidy Structures:Local government funding pools in Germany and Japan are sustaining community recreation center operations that anchor volume-tier participation rates.
Market Restraints
- Specialized Labor Scarcity:Certified adventure sports instructors and aquatic safety directors command premium wages that compress margins for independent operators.
- EPA Chemical Handling Compliance:Waste discharge and water treatment regulations elevate capital requirements for outdoor recreation sites in the United States.
- Digital Home Fitness Substitution:Connected equipment and streaming workout platforms are capturing discretionary fitness budgets that previously flowed to facility-based programs.
Strategic Opportunities
- Hybrid Coaching Convergence:Integration of in-person instruction with asynchronous digital programming opens subscription revenue streams beyond physical visit dependency.
- Experiential Retail Partnerships:Co-location with food and beverage operators and merchandise concepts extends per-capita spending at destination resorts.
- Accessibility Mandate Tailwinds:ADA and equivalent European accessibility standards are creating retrofit demand and new facility design specifications.
Industry Challenges
- Seasonal Revenue Volatility:Weather-dependent outdoor operators face cash flow compression during low-occupancy periods that strain fixed cost coverage.
- Legacy System Integration Friction:Migration from gate-based ticketing to cloud-native platforms requires retraining frontline staff and reconciling disparate data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreation Services Market |
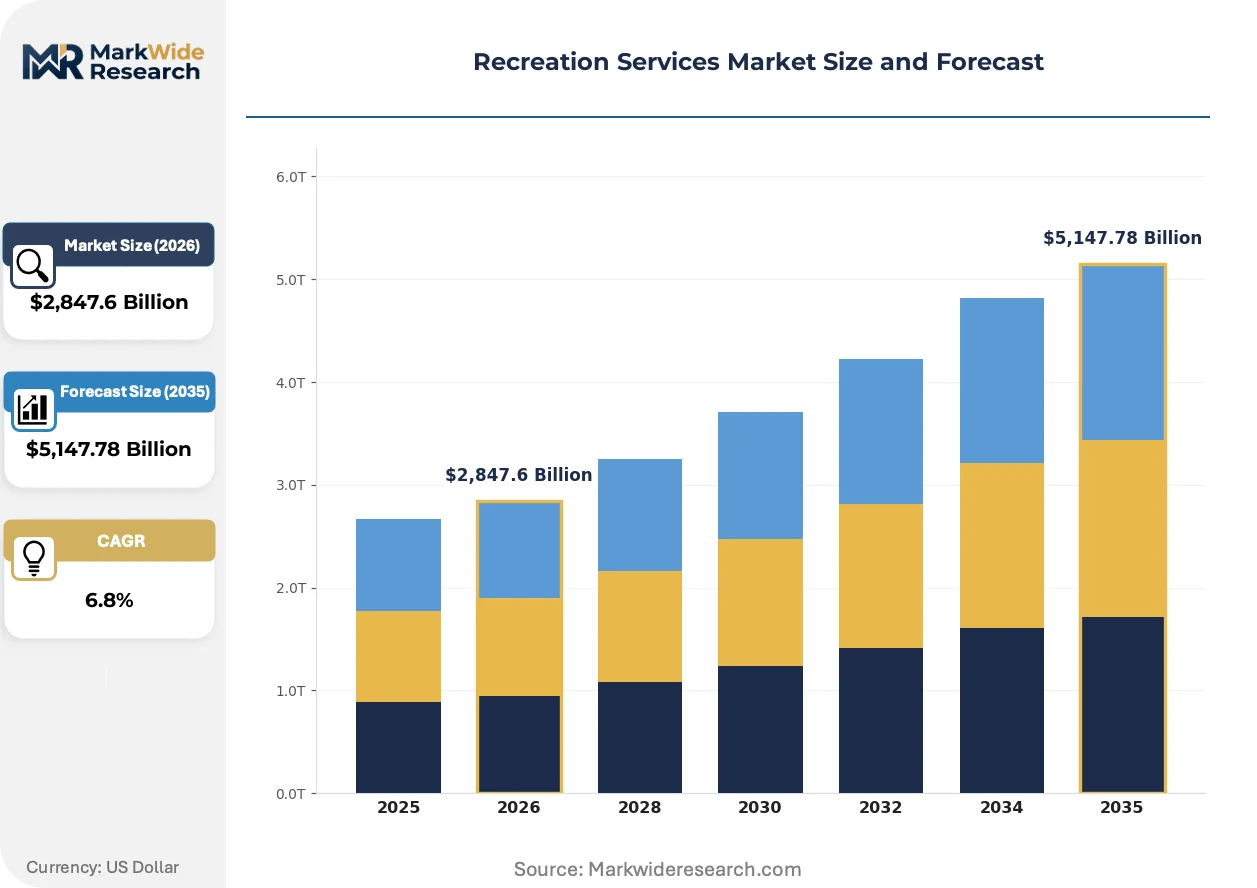
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $5,147.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Adventure Sports, Aquatic Services, Community Recreation, Fitness Programs Customer Type: Families, Individuals, Corporates, Schools End User: Fitness Enthusiasts, Casual Users, Tourists, Event Participants Facility Type: Public Parks, Recreation Centers, Gyms, Sports Complexes |
| Companies Covered | Merlin Entertainments Group, SeaWorld Entertainment, The Walt Disney Company, Live Nation Entertainment, Six Flags Entertainment Corporation, Universal Destinations & Experiences, MGM Resorts, Cedar Fair, Las Vegas Sands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreation Services Market Evolving Landscape
Digital infrastructure is redistributing control over customer relationships and revenue capture away from traditional intermediaries toward direct operator channels. This shift compresses distribution costs while expanding data ownership.
Mobile-native booking platforms with embedded AI recommendation engines are decentralizing customer acquisition away from third-party aggregators. Mid-sized attraction operators in the United States and United Kingdom are deploying these tools to bypass legacy travel distribution networks. The structural consequence is compressing commission structures while expanding first-party data assets for repeat marketing.
REACH chemical safety frameworks in the European Union are mandating material substitutions for pool sanitation and surface coatings used in aquatic facilities. Industrial consequence includes reformulation costs and supplier qualification delays for water park operators. German and French facility managers are responding by consolidating procurement with REACH-certified chemical distributors to streamline compliance documentation.
Corporate wellness procurement teams are unbundling annual recreation contracts into modular program purchases with usage-based pricing. Human resources departments in technology and financial services verticals are displacing fixed-fee wellness subscriptions with per-employee-activity accounting. This pattern is most visible in the United States, where self-insured employers seek direct attribution between recreation spending and healthcare cost reduction.
Recreation Services Market Segmentation
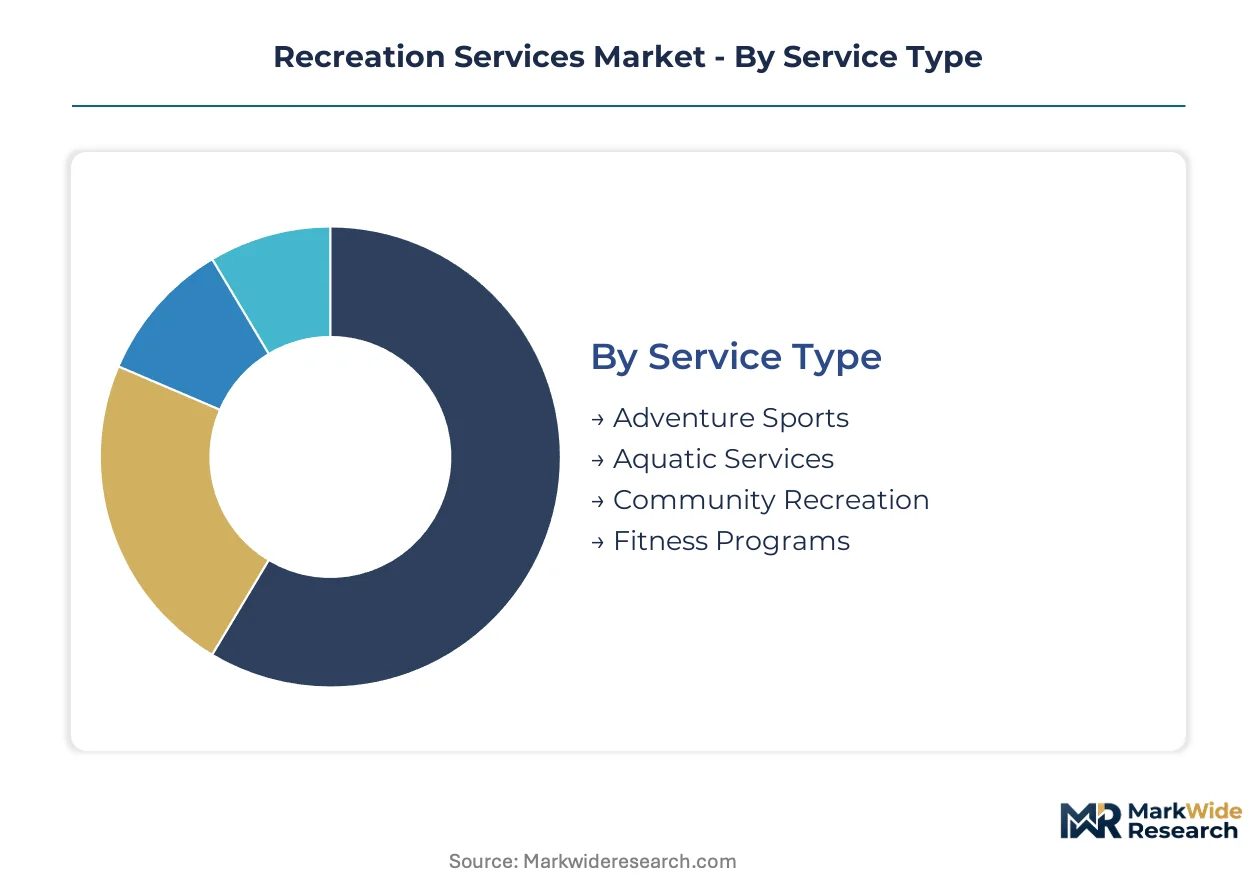
Recreation services operators configure pricing, staffing, and capital deployment differently across segment boundaries. Understanding these divides reveals where yield management algorithms extract premium returns versus where municipal subsidies sustain volume operations.
Service Type:
Buyer selection hinges on risk tolerance and equipment intensity rather than proximity alone.
- Adventure Sports:High-thrill activities requiring certified instructors and specialized gear such as climbing walls, zip lines, and guided expeditions. Corporate procurement teams in the United States prioritize these programs for executive retreats and team-building budgets, paying premium rates for liability-insured operators.
- Aquatic Services:Pool-based programming, water parks, and swim instruction governed by FDA sanitation guidelines and EPA chemical handling mandates. German facility managers consolidate procurement with REACH-certified distributors to streamline compliance documentation for surface coatings and treatment chemicals.
- Community Recreation:Subsidized public programming including youth leagues, senior activities, and neighborhood facility access. Municipal funding pools in Japan sustain operations that anchor participation rates in volume-tier demographics.
- Fitness Programs:Structured exercise classes, personal training, and wellness coaching delivered through staffed facilities. Connected equipment and streaming platforms are capturing discretionary budgets that previously flowed to facility-based programs.
Community Recreation leads on scale; Adventure Sports leads on momentum.
Customer Type:
Contract structure and payment timing vary sharply across buyer categories.
- Families:Multi-generational units purchasing seasonal passes, birthday party packages, and holiday camp enrollments. United Kingdom attractions deploy mobile-native booking platforms to capture this segment away from legacy travel distributors.
- Individuals:Solo participants seeking flexible membership terms and drop-in access. This segment shows highest price sensitivity and churn risk during economic contraction.
- Corporates:Employers procuring wellness subscriptions, team-building events, and stress-reduction programming. Human resources departments in United States technology and financial services verticals are displacing fixed-fee contracts with per-employee-activity accounting.
- Schools:Educational institutions booking field trips, athletic facility rentals, and physical education partnerships. Procurement cycles align with academic calendars, creating predictable seasonal demand clusters.
Corporates drive margin expansion; Families anchor revenue stability.
End User:
Frequency of visit and per-capita spending separate casual participants from committed enthusiasts.
- Fitness Enthusiasts:High-frequency users purchasing premium memberships and personal training packages. Hybrid coaching models integrating in-person instruction with asynchronous digital programming retain this cohort beyond physical visit dependency.
- Casual Users:Infrequent visitors motivated by social occasions or seasonal promotions. Dynamic yield algorithms capture marginal demand from this segment during off-peak windows at water parks and ski resorts.
- Tourists:Out-of-market visitors spending at destination resorts and live entertainment complexes. Per-capita outlays exceed local participants through extended stays and ancillary purchases.
- Event Participants:Ticketed attendees at single occasions including concerts, competitions, and festivals. Live Nation Entertainment controls distribution infrastructure extending from sales into artist management and venue operations.
Tourists maximize per-visit yield; Fitness Enthusiasts maximize lifetime value.
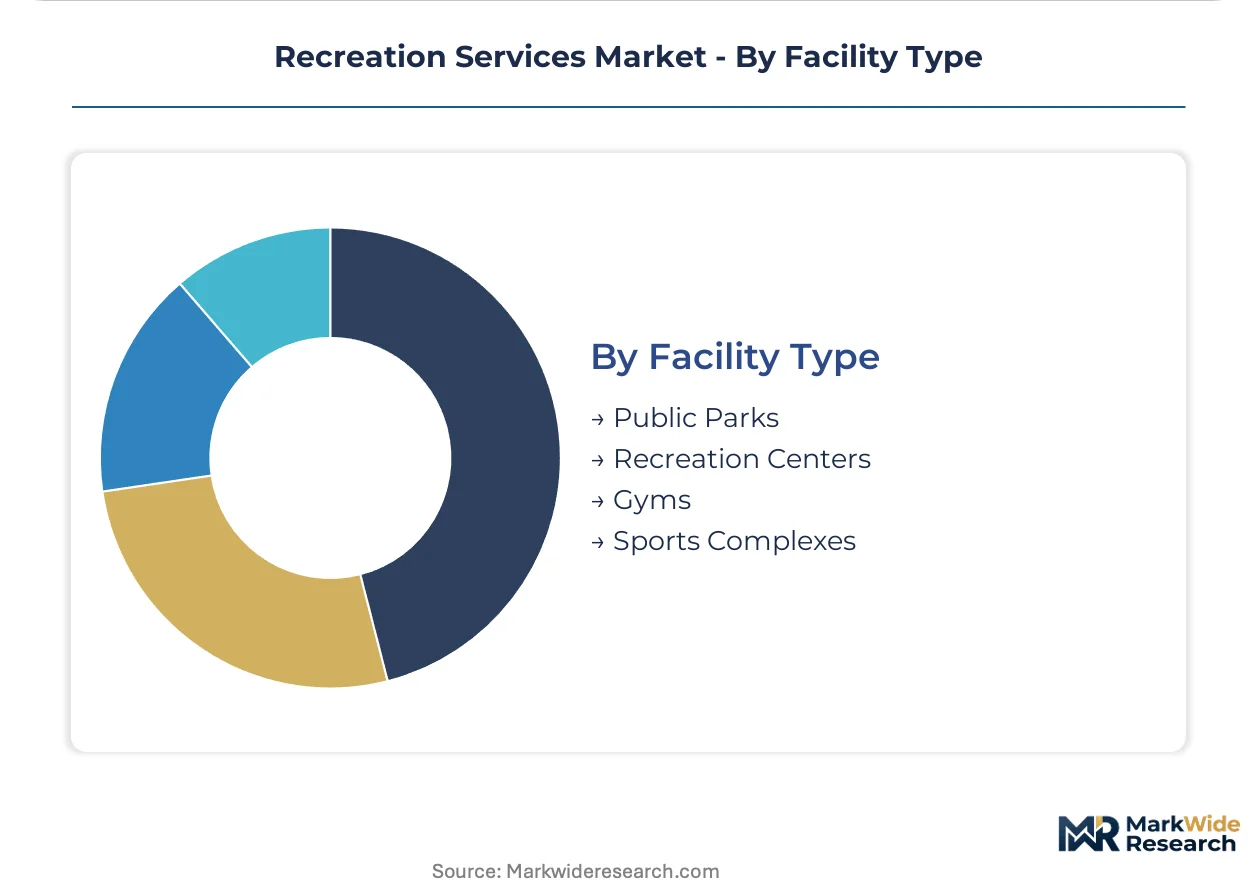
Facility Type:
Capital intensity and regulatory exposure shape operator economics across physical footprints.
- Public Parks:Open-access outdoor spaces maintained through municipal budgets with minimal gate revenue. EPA waste discharge regulations constrain operational design for sites with water features or chemical treatment systems.
- Recreation Centers:Multi-purpose indoor facilities offering programming diversity under single management. ADA accessibility mandates are creating retrofit demand and new design specifications for United States operators.
- Gyms:Fitness-dedicated spaces competing against digital home alternatives through social programming and hybrid coaching. OSHA workplace wellness mandates are accelerating employer procurement of team-building and stress-reduction programs.
- Sports Complexes:Large-scale venues hosting tournaments, leagues, and spectator events. These facilities command highest capital deployment and carry concentrated weather-dependent revenue volatility risk.
Recreation Centers balance reach and flexibility; Sports Complexes concentrate revenue and risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orlando's concentration of destination resorts and live entertainment complexes anchors the United States recreation services landscape, while digital booking platforms diffuse operational models across national boundaries. Municipal subsidy structures and federal workplace wellness mandates are reshaping procurement patterns in distinct geographies.
United States
Employer wellness budgets and corporate team-building procurement accelerate demand for adventure sports and stress-reduction programming. OSHA safety protocol expansion governs staffing ratios at climbing facilities and aquatic centers. Orlando and Las Vegas resort clusters deploy dynamic yield algorithms to capture marginal tourist demand during off-peak windows.
Germany
Municipal funding pools sustain community recreation center operations that anchor volume-tier participation rates across metropolitan regions. REACH chemical safety frameworks mandate material substitutions for pool sanitation and surface coatings used in aquatic facilities. Bavarian facility managers consolidate procurement with REACH-certified distributors to streamline compliance documentation.
Japan
Local government funding structures support public recreation programming that maintains high participation rates among senior demographics. METI guidelines shape facility safety standards and operational certifications for adventure sports operators. Tokyo and Osaka metropolitan areas concentrate private fitness facility development competing against digital home alternatives.
United Kingdom
Mobile-native booking platforms enable mid-sized attractions to capture family segment spending away from legacy travel distribution networks. GDPR compliance requirements constrain customer data utilization for personalization engines. London and Southeast England clusters lead deployment of AI-driven recommendation systems at ticketed attractions.
Australia
Destination resort operators target tourist segments with extended-stay packages and ancillary experiential retail partnerships. EPA waste discharge regulations constrain operational design for water parks and outdoor recreation sites with chemical treatment systems. Gold Coast and Sydney harbor concentrations anchor aquatic services development governed by federal water quality mandates.
Recreation Services Market Competitive Landscape
Global majors compete with regional champions across content integration and distribution infrastructure dimensions, creating a tiered competitive structure. Branded attraction portfolios and backward integration into streaming and experiential retail separate scale players from facility-dependent operators. Three archetypes dominate: content-integrated conglomerates, live event infrastructure controllers, and regional resort specialists. M&A activity concentrates venue networks and artist management capabilities, while technology licensing partnerships expand yield management access to mid-sized operators.
Within the content-integrated tier, The Walt Disney Company exemplifies backward integration across streaming, retail, and experiential assets that drive repeat visitation. Live Nation Entertainment occupies a position as infrastructure controller extending from ticket distribution into venue operations and artist management. Merlin Entertainments Group represents the branded attraction archetype, leveraging portfolio scale to sustain premium pricing power across European and North American markets.
| Leading Market Players |
|---|
| Merlin Entertainments Group |
| SeaWorld Entertainment |
| The Walt Disney Company |
| Live Nation Entertainment |
| Six Flags Entertainment Corporation |
| Universal Destinations & Experiences |
| MGM Resorts |
| Cedar Fair |
| Las Vegas Sands |
| Others |
Value Network & Pricing Analysis
Certified adventure sports operators command substantial premiums over community recreation programs, a bifurcation that manifests in divergent supply chain configurations and pricing architectures across the United States and Germany. Premium-tier providers absorb specialized labor costs and liability insurance burdens while municipal-subsidized facilities anchor volume-tier participation through consolidated chemical procurement and standardized staffing ratios.
Pricing Analysis
Input-cost pass-through from certified instructor wages and EPA-compliant chemical handling elevates rates at adventure sports and aquatic facilities across the United States. Three-tier pricing structure across premium, standard, and economy levels separates liability-insured corporate retreats from family seasonal passes and subsidized community access. Pricing pressure stems from digital home fitness substitution capturing discretionary wellness budgets. Individual drop-in users exhibit highest price sensitivity while corporate procurement teams demonstrate lowest elasticity due to wellness mandate attribution requirements.
Supply Chain Analysis
Logistics and freight costs for specialized adventure sports equipment concentrate supplier relationships in the United States, Germany, and Japan. Raw material dependencies span climbing gear composites, pool sanitation chemicals, and digital booking platform infrastructure. Supply chain risk centers on REACH-certified chemical distributor consolidation creating single-source vulnerability for European aquatic operators. Distribution runs through direct-to-consumer mobile platforms, bypassing legacy travel aggregators and compressing commission structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal subsidy differentials between Germany and the United States create geographic-arbitrage opportunities for facility operators seeking capital deployment efficiency. OSHA mandate expansion in the United States accelerates employer wellness procurement faster than equivalent European workplace health frameworks.
For Market Incumbents: Hedge against digital home fitness substitution by deepening hybrid coaching capabilities that tether asynchronous programming to physical facility access. Consolidate procurement with REACH-certified distributors to preempt chemical compliance documentation bottlenecks. Vertical integration into experiential retail partnerships extends per-capita spending at destination resorts.
For New Entrants and Emerging Players: ADA accessibility mandates in the United States open a window for retrofit specialists and new facility design consultants serving recreation center operators. White-space targets include modular corporate wellness programming with usage-based pricing models displacing fixed-fee contracts. Penetrate mid-sized United Kingdom attractions through mobile-native booking platforms bypassing legacy travel distribution networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where municipal subsidy structures sustain subscale community recreation operators unable to absorb EPA compliance cost escalations. Long-term viability favors branded attraction portfolios with backward integration into content and streaming assets. Acquisition target archetype: regional resort specialists with underutilized capacity and yield management infrastructure gaps. Signal to watch: corporate wellness procurement unbundling accelerating per-employee-activity accounting adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Coaching Platform Development | Integrates AI-driven personalization engines with physical facility access to retain fitness enthusiasts beyond visit dependency. |
| REACH-Certified Procurement Consolidation | Streamlines chemical compliance documentation for German aquatic operators facing material substitution mandates. |
| Dynamic Yield Algorithm Deployment | Enables water parks and ski resorts to capture marginal tourist demand during off-peak occupancy windows. |
| Experiential Retail Partnership Expansion | Co-locates food and beverage operators at destination resorts to extend per-capita spending metrics. |
| ADA Accessibility Retrofit Specialization | Addresses retrofit demand and new design specifications created by United States accessibility mandates. |
Research Methodology
Multiple input streams — facility operator interviews, corporate wellness procurement leads, municipal recreation directors, and digital platform engineers — were reconciled against regulatory filings and trade association data. Primary discussions with adventure sports safety directors, aquatic facility managers, and employer benefits administrators informed operational cost structures. Secondary sources included OSHA safety protocol documentation, EPA chemical handling guidelines, and REACH compliance registries. Bottom-up capacity utilization models and top-down household entertainment expenditure estimates underwent cross-validation.
Data-stream reconciliation across service type, customer category, end-user frequency, and facility format dimensions generated volume and value outputs. Segmentation modeling incorporated adventure sports intensity tiers, corporate contract structures, tourist versus local participation ratios, and public-private facility ownership splits. CAGRs were derived from trend extrapolation calibrated against historical municipal funding cycles and employer wellness budget expansion patterns. Forecast inputs included AI adoption curves in booking platforms and substitution elasticity estimates for digital fitness alternatives.
Revisions become necessary when municipal subsidy allocations shift, OSHA mandates expand coverage categories, or REACH chemical frameworks impose additional material restrictions. Forecasts reflect assumptions about discretionary entertainment budget stability and corporate wellness procurement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Rafting Equipment Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
Skiing Equipment Market