
 Recreational Use Water Chute Market | 2026-2036
Recreational Use Water Chute Market Size, Share, and Industry Trends Forecast 2026-2036
Recreational Use Water Chute Market Insights
Fiberglass composite is realigning recreational water chute construction economics as it displaces traditional vinyl shells in high-throughput installations. ProSlide Technology leverages captive manufacturing of custom mold systems to dominate premium permanent installations across North American water parks. Guangdong Dalang Water Park Equipment anchors its position through backward integration into fiberglass raw material processing, sustaining cost advantages in hybrid chute production for Asian resort developers.
Recreational use water chutes are engineered aquatic conveyance structures designed to transport riders via gravity-driven water flow through enclosed or open flume pathways, typically constructed with gel-coated fiberglass laminates achieving surface roughness below 0.5 millimeters to minimize friction drag and optimize rider velocity control. Fixed structure chutes command the largest installed base due to their decades-long service life and integration with municipal water park infrastructure, while inflatable chutes represent the fastest-expanding category as mobile entertainment operators seek rapid deployment models for seasonal festivals and private event circuits. Custom chutes concentrate margin pools through bespoke engineering contracts tied to branded intellectual property at major resort chains.
ASTM International publishes F2376 and F2461 standards governing water slide structural integrity and operational safety, while the Consumer Product Safety Commission monitors incident reporting databases to inform design mandate updates for public installations. China's GB standards for amusement ride safety, administered by the Standardization Administration, impose mandatory inspection protocols on fixed aquatic attractions exceeding defined height and throughput thresholds. Stakeholders must monitor evolving polymer emissions regulations in the European Union and pending state-level water conservation mandates in drought-prone U.S. regions as these frameworks will reshape material selection and operational permitting requirements.
Market Dynamics
Fiberglass composite substitution is compressing installed cost structures while ASTM F2376 compliance mandates force material specification upgrades across North American installations, creating divergent cost trajectories between premium permanent builds and mobile seasonal deployments.
Growth Catalysts
- Southeast Asian Tourism Corridors:Water park operators in Thailand, Vietnam, and Indonesia are expanding chute installations to capture inbound leisure travel recovery, with provincial governments funding aquatic recreation infrastructure through municipal bond programs.
- ASTM F2376 Material Compliance:Tightened safety standards for gel-coated laminate thickness and structural load testing are accelerating replacement cycles at aging North American facilities, generating retrofit demand for certified fiberglass systems.
- Hybrid Chute Engineering:Fixed-inflatable hybrid designs combining permanent foundation anchoring with seasonal modular components are enabling resort developers to optimize capital deployment across variable occupancy periods.
Market Restraints
- Petrochemical Input Volatility:Epoxy resin and fiberglass roving prices fluctuate with crude oil derivatives, compressing margin predictability for manufacturers without captive polymer supply or long-term feedstock contracts.
- Guangdong Raw Material Concentration:Backward-integrated producers in China's Pearl River Delta control upstream fiberglass processing capacity, creating supply dependency risks for non-integrated fabricators in Southeast Asia and Latin America.
- Height and Throughput Threshold Mandates:China's GB standards impose mandatory inspection protocols on fixed aquatic attractions exceeding defined parameters, adding compliance friction for imported installations.
Strategic Opportunities
- Provincial Entertainment Zones:China's third-tier cities are receiving dedicated fiscal allocations for large-scale aquatic recreation infrastructure, opening deployment corridors outside saturated coastal markets.
- EU Polymer Emissions Regulations:Evolving ECHA frameworks on styrene emissions and volatile organic compound limits are creating first-mover advantages for low-emission gel-coat formulations in European municipal procurement.
- Mobile Festival Circuits:Inflatable chute operators are penetrating private event and seasonal festival channels through rapid-deployment rental models, accessing revenue streams unavailable to fixed-installation competitors.
Industry Challenges
- Certified Fiberglass Lamination Workforce:Skilled technicians capable of achieving sub-0.5 millimeter surface roughness specifications remain concentrated in established manufacturing clusters, limiting geographic expansion of quality production.
- Dual Compliance Architecture:Manufacturers serving both North American and Chinese markets must maintain parallel certification pathways under ASTM F2376 and GB standards, extending product development timelines.
- Water Conservation Mandates:Drought-prone U.S. states are implementing operational permitting restrictions on aquatic attraction water throughput, forcing redesign of recirculation systems and filtration infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recreational Use Water Chute Market |
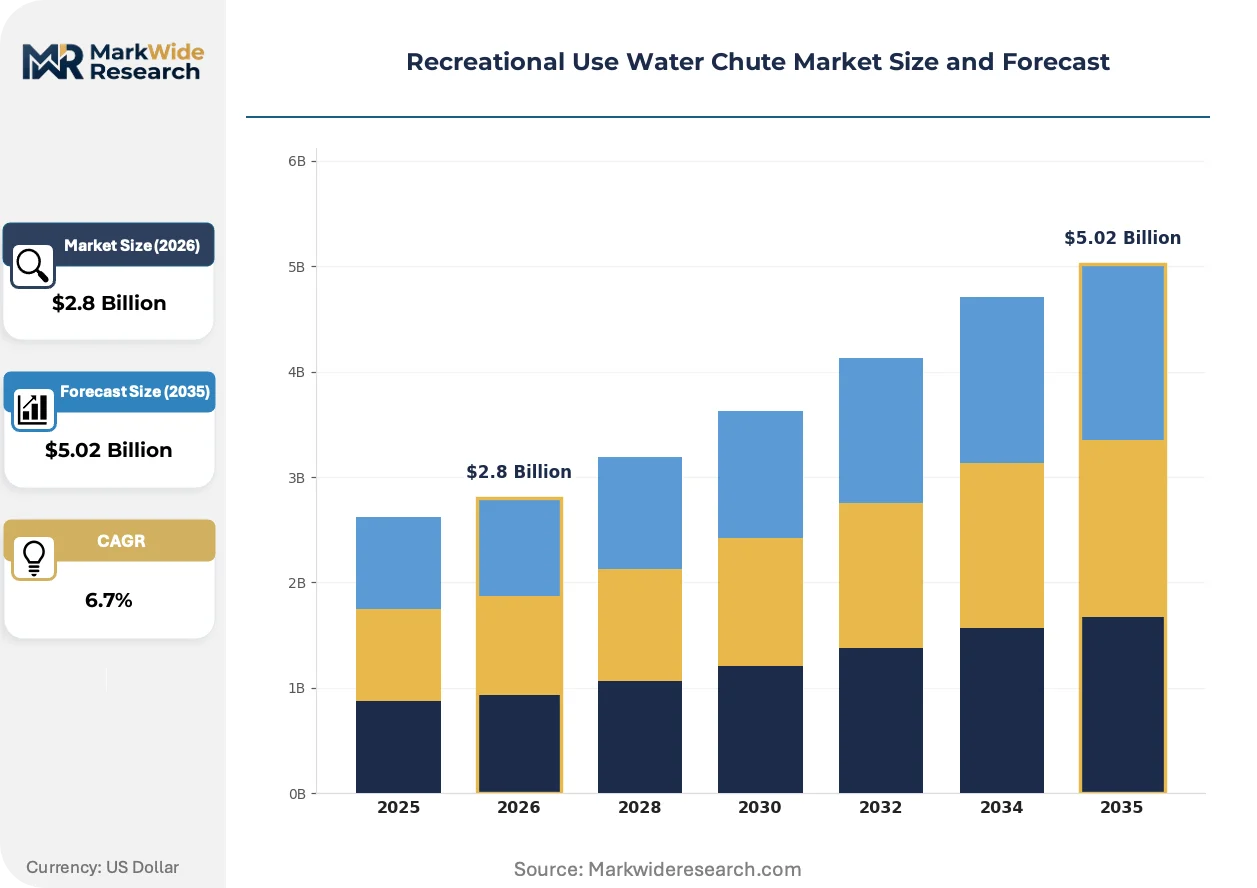
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Chutes, Fixed Structure Chutes, Hybrid Chutes, Custom Chutes Material: Vinyl, Fiberglass, Plastic, TPU End User: Water Parks, Amusement Parks, Resorts, Private Pools Installation Type: Permanent, Temporary, Mobile, Stationary |
| Companies Covered | Whitewater West, Guangdong Dalang Water Park Equipment, Wm International, Haisan, Polin Waterparks, McDergan Water Slides, ProSlide Technology, Aquatic Development Group, SplashTacular, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recreational Use Water Chute Market Trends and Innovations
Material science advances and regulatory harmonization pressures are converging to reshape competitive positioning, with differentiation increasingly tied to compliance velocity and sustainable manufacturing credentials rather than scale alone.
Automated CNC mold fabrication is overtaking manual plug-and-pattern methods in high-throughput chute production. Premium water park developers in the United States and United Arab Emirates are specifying CNC-milled mold systems for custom branded installations. This precision manufacturing is compressing design-to-installation cycles from months to weeks while enabling complex geometric features impossible with traditional hand-layup techniques.
REACH regulation amendments targeting styrene monomer emissions are forcing gel-coat reformulation across European supply chains. Manufacturers serving EU municipal buyers must now certify low-emission laminate systems or face procurement exclusion. German and French water park operators are prioritizing suppliers with ECHA-registered alternative resin platforms, creating compliance-based vendor selection criteria.
Seasonal rental procurement is fragmenting traditional capital-sales relationships between chute fabricators and entertainment operators. Mobile event companies in Brazil and Saudi Arabia are bypassing permanent installation vendors entirely, contracting directly with inflatable specialists for short-term deployment packages. This channel disintermediation is compressing manufacturer margins while expanding addressable event-market volume.
Recreational Use Water Chute Market Segmentation
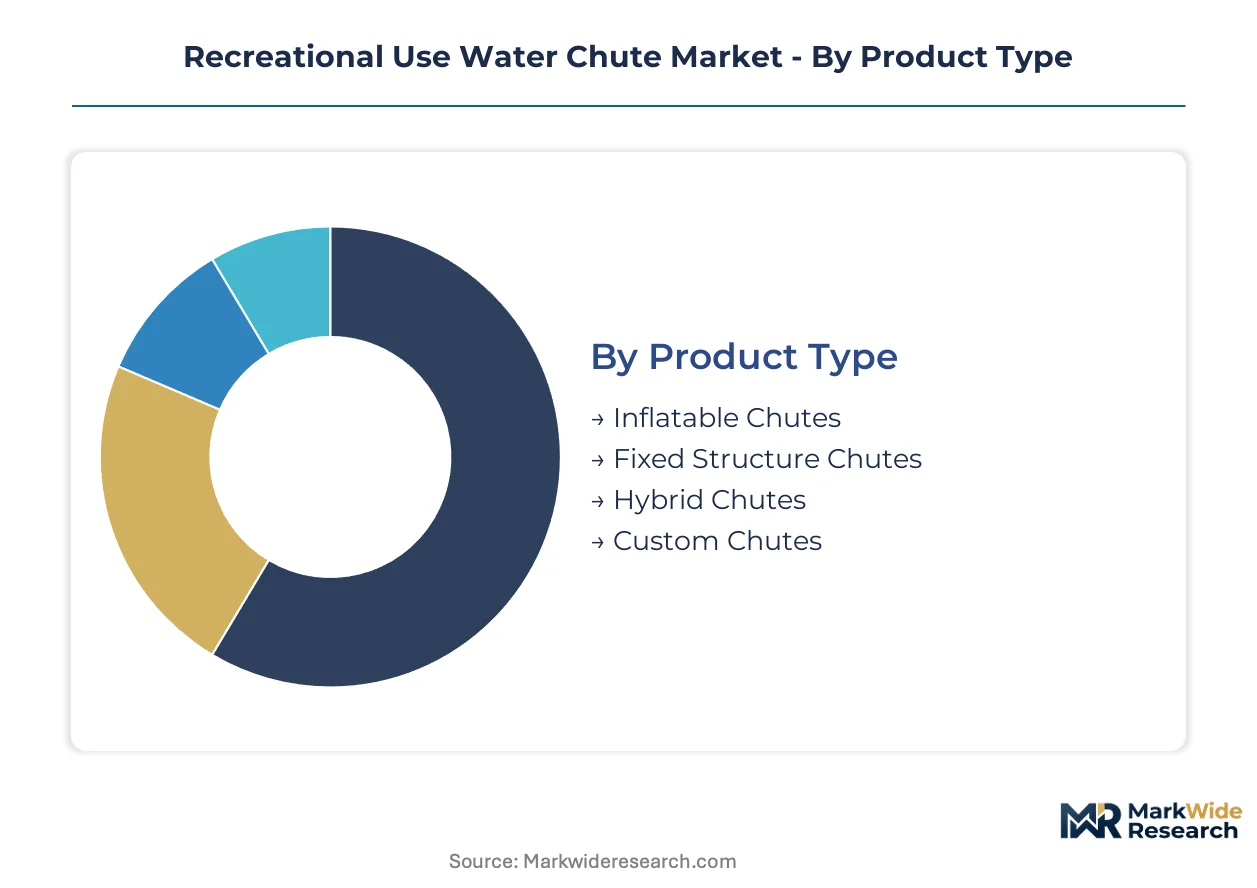
Water chute manufacturers configure product portfolios across four distinct dimensions, each carrying divergent margin profiles and capital intensity requirements. Segmentation discipline determines whether fabricators anchor in municipal infrastructure contracts, mobile entertainment rentals, or bespoke resort installations.
Product Type:
Standalone permanent installations dominate capital deployment patterns, while embedded modular systems penetrate seasonal and private-event channels with lower upfront commitment.
- Fixed Structure Chutes:Gel-coated fiberglass laminates with sub-0.5 millimeter surface roughness specifications anchor municipal water park infrastructure across Thailand, Vietnam, and Indonesia. Provincial government bond programs in Southeast Asian tourist corridors are concentrating procurement for these decades-long service life installations.
- Inflatable Chutes:TPU and reinforced vinyl constructions deploy via rapid-inflation systems for festival circuits and private event operators. Mobile entertainment companies in Brazil and Saudi Arabia are bypassing permanent vendors entirely, contracting directly with inflatable specialists for short-term deployment packages.
- Hybrid Chutes:Combine permanent foundation anchoring with seasonal modular components to optimize capital deployment across variable occupancy periods.
- Custom Chutes:Bespoke engineering contracts tied to branded intellectual property at major resort chains concentrate margin pools through exclusive design relationships.
Fixed structure chutes lead volumes today; inflatable chutes are gaining share fastest.
Material:
Cost tier stratification separates premium gel-coat systems from commodity vinyl alternatives, with regulatory compliance mandates reshaping specification trajectories in European and North American procurement.
- Fiberglass:Composite laminates with epoxy resin matrices displace traditional shells in high-throughput installations, achieving structural load tolerances required by ASTM F2376. ECHA REACH amendments on styrene emissions are forcing gel-coat reformulation across EU supply chains, creating compliance-based vendor selection criteria.
- Vinyl:PVC-based constructions serve budget-tier mobile and temporary installations where surface roughness specifications are less stringent.
- TPU:Thermoplastic polyurethane membranes enable rapid-deployment inflatable architectures with superior puncture resistance for repeated assembly cycles.
- Plastic:Rotomolded polyethylene components address entry-level residential and small-scale commercial applications with limited durability requirements.
Fiberglass commands the premium tier; TPU is climbing the fastest as mobile rental procurement fragments traditional capital-sales relationships.
End User:
Application concentration varies by throughput requirements, with high-volume municipal operators imposing certification burdens that exclude smaller facility categories.
- Water Parks:Municipal and privately operated aquatic recreation facilities with GB standards compliance requirements in China and ASTM F2376 mandates in the United States. These installations generate the largest absolute contract values and longest procurement cycles.
- Amusement Parks:Integrated entertainment complexes requiring dual certification under amusement ride safety frameworks and aquatic attraction standards.
- Resorts:Branded hospitality properties commissioning custom engineered installations tied to intellectual property differentiation strategies.
- Private Pools:Residential and semi-commercial installations with minimal regulatory oversight and compressed procurement timelines.
Water parks anchor procurement volumes today; resorts are expanding fastest through branded custom engineering contracts.
Installation Type:
Deployment duration determines supply chain configuration, with permanent builds requiring captive manufacturing relationships and temporary installations enabling rental-based revenue models.
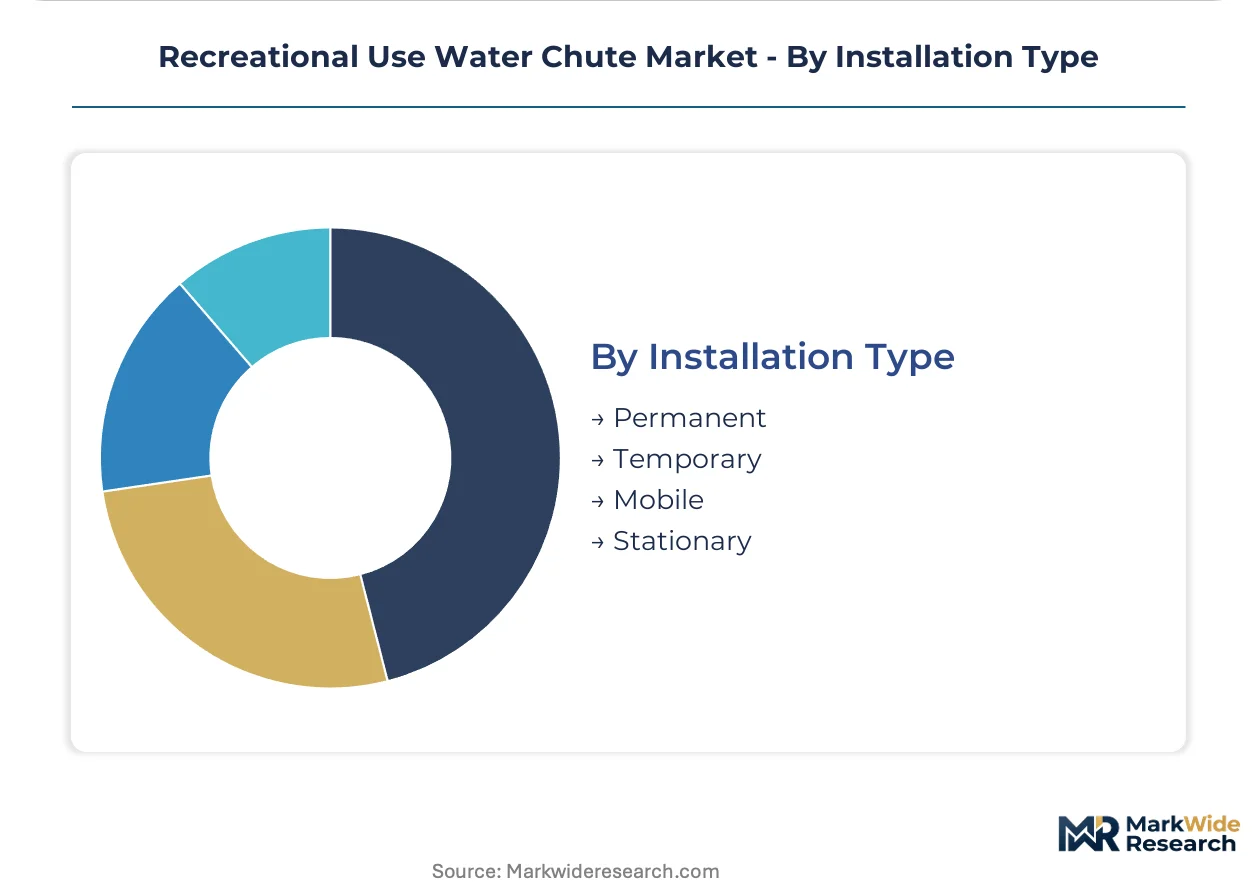
- Permanent:Foundation-anchored concrete and steel structures with integrated recirculation and filtration infrastructure, subject to China's GB mandatory inspection protocols for height and throughput thresholds.
- Mobile:Rapid-deployment systems transported between festival circuits and seasonal venues, penetrating private event channels unavailable to fixed-installation competitors.
- Temporary:Semi-permanent seasonal installations with modular anchoring systems for variable occupancy resort properties.
- Stationary:Fixed-location configurations without permanent foundation requirements, serving intermediate-duration commercial deployments.
Permanent installations dominate capital deployment today; mobile systems are expanding most quickly through event-market channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta anchors fiberglass composite fabrication capacity for recreational water chute manufacturing. Municipal bond programs across Southeast Asian tourist corridors and provincial entertainment zones in China's interior are redistributing demand geography. Regulatory divergence between ASTM F2376 mandates and China's GB standards is fragmenting certification pathways.
United States
Water park operators in Florida and Texas are replacing aging vinyl installations with gel-coated fiberglass systems. ASTM F2376 compliance mandates from the Consumer Product Safety Commission are accelerating retrofit cycles at facilities built before 2015. ProSlide Technology's captive mold manufacturing in Ontario, Canada serves premium permanent installations across the Sun Belt.
China
Third-tier cities in Sichuan and Hunan provinces are receiving dedicated fiscal allocations for aquatic recreation infrastructure. The Standardization Administration's GB standards impose mandatory inspection protocols on fixed attractions exceeding height and throughput thresholds. Guangdong Dalang Water Park Equipment's backward integration into fiberglass raw material processing sustains cost advantages in hybrid chute production.
Germany
Municipal water park procurement in Bavaria and North Rhine-Westphalia is prioritizing low-emission laminate systems. ECHA REACH amendments on styrene monomer emissions are forcing gel-coat reformulation across domestic supply chains. Polin Waterparks' engineering relationships with Dubai and Riyadh developers demonstrate German fabrication standards penetrating Gulf entertainment markets.
Thailand
Provincial governments in Phuket and Pattaya corridors are funding chute installations through tourism recovery bond programs. The country's national safety regulator aligns aquatic attraction standards with ASEAN harmonization frameworks. Whitewater West's design partnerships with Bangkok-based resort developers concentrate premium custom engineering contracts in coastal entertainment zones.
Brazil
Mobile entertainment operators in São Paulo and Rio de Janeiro states are bypassing permanent vendors for inflatable chute rental models. ANVISA monitoring of amusement ride incident databases informs municipal permitting requirements for seasonal deployments. Haisan's distribution relationships with Brazilian festival circuit operators illustrate Asian fabrication reaching Latin American event markets.
Recreational Use Water Chute Market Competitive Landscape
Global majors compete with regional champions across certification velocity and raw material integration depth. The vendor base stratifies between premium permanent installers, mobile rental specialists, and hybrid system fabricators. Three archetypes dominate: captive mold manufacturers with proprietary CNC systems, backward-integrated fiberglass processors, and rapid-deployment inflatable specialists. Competitive moves concentrate on geographic expansion through local certification partnerships and upstream control over epoxy resin supply chains.
Among North American fabricators, ProSlide Technology and SplashTacular exemplify the premium permanent installation archetype through engineering-intensive custom relationships. Guangdong Dalang Water Park Equipment occupies a position within the backward-integrated tier, anchoring cost structures through in-house fiberglass roving processing. Whitewater West sits across both premium and hybrid categories, representing diversified portfolio breadth spanning fixed infrastructure and seasonal modular systems. These three company patterns illustrate how competitive positioning ties to supply chain configuration rather than scale alone.
| Leading Market Players |
|---|
| Whitewater West |
| Guangdong Dalang Water Park Equipment |
| Wm International |
| Haisan |
| Polin Waterparks |
| McDergan Water Slides |
| ProSlide Technology |
| Aquatic Development Group |
| SplashTacular |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in China's Pearl River Delta anchor fiberglass roving supply and translate captive resin processing into pricing discipline across Asian procurement corridors. Their ownership concentration enables volume commitment leverage with epoxy suppliers that private-equity-rolled competitors in North America cannot replicate, compressing margin structures in export markets while sustaining premium positioning in domestic municipal contracts.
Pricing Analysis
Epoxy resin and fiberglass roving pass-through volatility compresses margin predictability for non-integrated fabricators lacking long-term petrochemical feedstock contracts. Three-tier pricing structure across premium, standard, and economy levels separates ASTM F2376-certified gel-coat systems from commodity vinyl alternatives, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from Guangdong Dalang's backward integration cost advantages in hybrid chute production. Municipal water park operators in China show least price sensitivity due to bond-funded procurement timelines, while mobile rental operators in Brazil exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Dual-sourcing requirements from major resort developers in the United States and United Arab Emirates mandate multi-supplier qualification for gel-coat laminate systems to mitigate single-source vulnerability. Geographic supply concentration centers on China, Germany, and Canada for precision mold fabrication and fiberglass composite processing. Raw material dependencies rest on epoxy resin, fiberglass roving, and gel-coat formulations from petrochemical derivatives. Tariff exposure on Chinese fiberglass imports into North America creates supply friction for non-integrated fabricators. Distribution runs through direct engineering relationships for permanent installations and rental platform intermediaries for mobile deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Recreational Use Water Chute Market functions as a geographic-arbitrage play where ASTM F2376 compliance costs in North America run substantially higher than GB standards inspection protocols in China, creating divergent margin profiles for dual-certified manufacturers.
For Market Incumbents: To counter Guangdong Dalang's backward integration cost advantages, ProSlide Technology and SplashTacular should deepen captive mold manufacturing relationships with Ontario-based CNC fabrication partners and accelerate ASTM F2376 certification velocity to capture retrofit cycles at aging Sun Belt facilities. Channel control through exclusive design partnerships with branded resort chains offers defensive moats against Asian cost competition. For New Entrants and Emerging Players: Festival circuit operators in Brazil and Saudi Arabia represent the most penetrable white-space target, as mobile rental procurement fragments traditional capital-sales relationships and bypasses incumbent permanent-installation vendors entirely. TPU inflatable specialists can access this channel through direct contracting with seasonal event companies, circumventing established distribution hierarchies. A rapid-deployment service model with short-term rental packages unlocks revenue streams unavailable to fixed-structure competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap fabricators with partial vertical integration into fiberglass processing but lacking full resin supply chain control. Long-term viability across the analysis window hinges on regulatory compliance velocity rather than scale alone, favoring targets with dual ASTM F2376 and GB standards certification pathways already operational. The signal to watch is ECHA REACH amendment implementation pace in European municipal procurement, which will force gel-coat reformulation investments and separate compliant from excluded vendor pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiberglass Roving | Guangdong Dalang sustains cost advantages in hybrid chute production for Asian resort developers. |
| Dual Certification Pathway Investment | Manufacturers serving both ASTM F2376 and GB standards extend product development timelines but capture cross-border procurement. |
| CNC Mold Fabrication Scale-Up | ProSlide Technology compresses design-to-installation cycles from months to weeks for premium permanent installations. |
| Low-Emission Gel-Coat Reformulation | ECHA REACH compliance creates first-mover advantages in European municipal procurement for certified laminate systems. |
| Mobile Rental Platform Development | Inflatable specialists in Brazil bypass permanent vendors entirely through seasonal festival circuit contracting. |
Research Methodology
Direct dialogue with water park operations directors, municipal procurement officers in Southeast Asian tourist corridors, fiberglass lamination technicians, and festival circuit rental operators grounded qualitative findings in operational reality. Secondary validation drew from ASTM International standards documentation, China's Standardization Administration GB protocol filings, ECHA REACH amendment registers, and municipal bond program disclosures across Thailand, Vietnam, and Indonesia. Bottom-up installation tracking and top-down infrastructure spending analysis triangulated market sizing.
Segmented outputs across product type, material specification, end-user category, and installation duration modeled demand fragmentation over the projection horizon. CAGRs derived from correlated infrastructure investment flows and regulatory compliance cycle timing. Key inputs included provincial entertainment zone fiscal allocation patterns in China's interior, petrochemical derivative price indices for epoxy resin, and height-throughput threshold inspection mandate expansion under evolving safety frameworks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA polymer emissions enforcement intensity and drought-driven water conservation mandate proliferation across U.S. states. Deviation in China's third-tier city bond issuance volume would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Snorkeling Market
Outdoor and Adventure Activities
India Spectator Sports Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Climbing Harness Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
Power Sports Market