
 Wakeboard Market | 2026-2036
Wakeboard Market Size, Share, and Industry Trends Forecast 2026-2036
Wakeboard Market Analytics
The EU Green Deal is repositioning material sourcing priorities across water-sports equipment, pushing manufacturers toward lower-carbon laminates and recyclable core substrates. Hyperlite Wake leverages its long-standing R&D pipeline to develop bio-epoxy compatible layups that sustain performance under repeated flex cycles. Liquidforce Wakeboards anchors its competitive stance through deep channel partnerships with North American specialty retailers and direct-to-consumer platforms.
A wakeboard is a short, broad water-ski designed for riding behind motorized towboats or cable systems, typically measuring 130–150 cm in length with continuous or three-stage rocker profiles that determine lift, pop, and landing characteristics; manufacturers bond fiberglass or carbon fiber skins around polyurethane or foam cores to achieve strength-to-weight ratios suited to aerial maneuvers and rail slides. Boat boards occupy the largest volume share given the installed base of inboard ski boats across freshwater lakes, while cable park boards represent the fastest-growing category as fixed-line installations expand across Europe and Southeast Asia. Foam boards command premium positioning in rental fleets and schools where durability and lower maintenance costs protect margin pools over seasonal turnover cycles.
The EPA oversees volatile organic compound emissions from fiberglass lamination facilities, constraining plant locations and curing process choices in the United States, while REACH compliance in Europe restricts certain phthalate plasticizers and isocyanate hardeners common in legacy core bonding systems. ISO 9001 quality management and ISO 14001 environmental certification increasingly gate access to major sporting goods chain procurement programs. Stakeholders must weigh capital allocation between cable park expansion markets and boat-dependent regions as infrastructure investment patterns diverge.
Market Dynamics
Cable park infrastructure expansion is fragmenting demand away from traditional boat-tow dependency, while bio-resin mandates under EU Green Deal and EPA VOC rules are forcing laminate chemistry redesigns across manufacturing footprints.
Growth Catalysts
- REACH and EU Green Deal compliance:European chemical restrictions on phthalate plasticizers and isocyanate hardeners are accelerating adoption of bio-epoxy systems in board lamination, creating first-mover advantages for compliant manufacturers.
- Cable park proliferation:Fixed-line installations across Florida, Thailand, and Germany are attracting recreational users who lack boat access, expanding addressable demand beyond traditional lake-house demographics.
- ISO 14001 certification:Environmental management system requirements from major sporting goods chains are gating procurement access, pushing suppliers toward certified low-carbon core substrates and recyclable manufacturing waste streams.
Market Restraints
- Petrochemical input volatility:Polyurethane foam cores and epoxy resin systems expose margins to crude-linked feedstock swings, compressing working capital flexibility for mid-tier producers.
- Chinese carbon fiber concentration:High-modulus fiber supply for performance boards clusters with domestic Chinese producers, creating single-source vulnerability for North American and European laminate facilities.
- Fiberglass lamination EPA constraints:Volatile organic compound emission limits restrict plant siting and curing process choices in the United States, raising compliance costs versus offshore competitors.
Strategic Opportunities
- Southeast Asia cable expansion:Thailand, Indonesia, and the Philippines host underpenetrated coastlines where fixed-line parks can replicate the European rental-school model without competing against established boat cultures.
- Recycled PET core substrates:Convergence of ocean-plastic recovery logistics and foam compression molding is enabling closed-loop board construction that satisfies retailer sustainability scorecards.
- Direct-to-consumer platforms:Specialty retailers are ceding share to manufacturer-owned digital channels that capture full margin and enable custom rocker-profile configuration for advanced riders.
Industry Challenges
- Composite technician scarcity:Hand-layup and vacuum-infusion skills for consistent fiber-resin ratios are aging out of the workforce faster than vocational programs replenish qualified laminators.
- ISO 9001 certification timelines:Quality management system audits for major chain procurement programs require 12-18 month implementation cycles that delay revenue recognition for new market entrants.
- Legacy boat-board inventory obsolescence:Continuous rocker profiles optimized for inboard ski boats face markdown pressure as three-stage rocker designs dominate cable park preference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wakeboard Market |
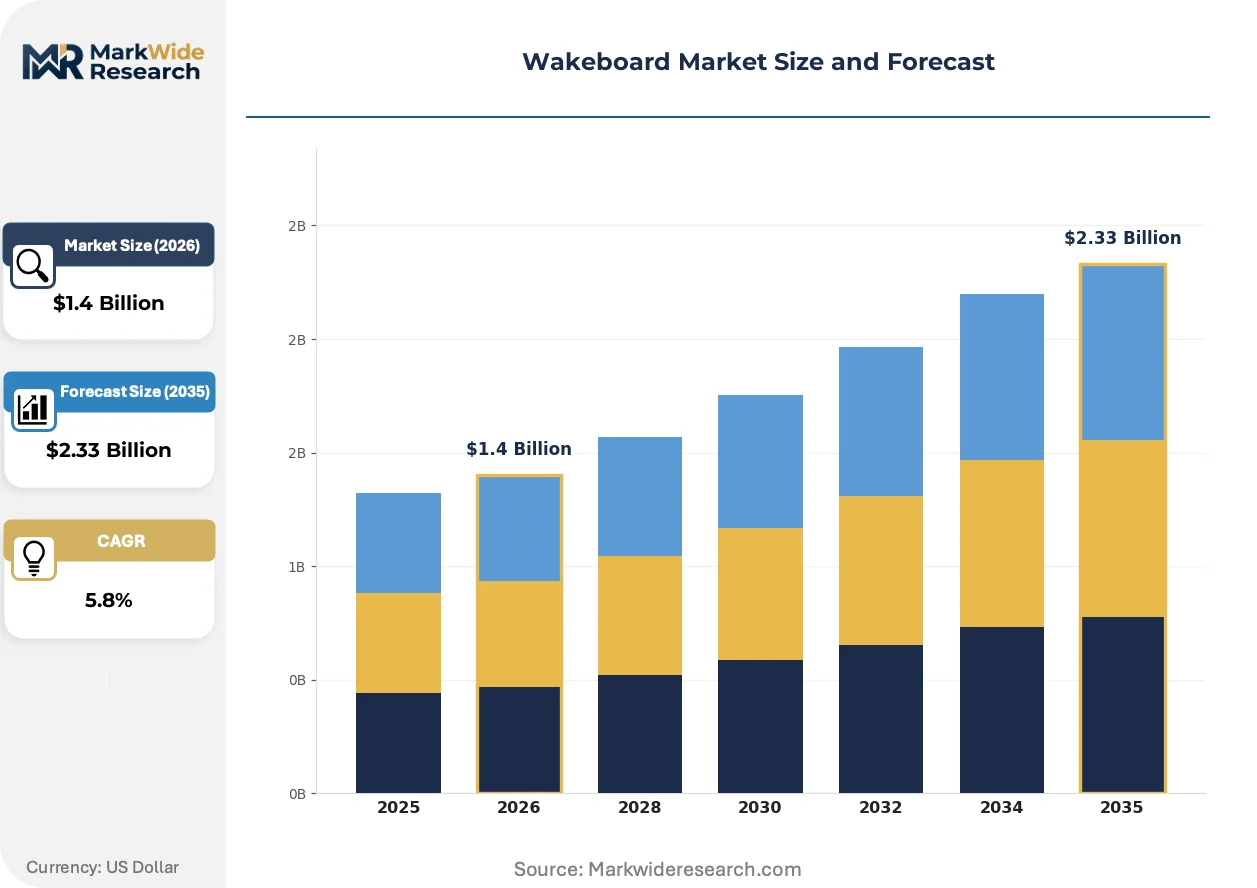
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Boards, Cable Park Boards, Boat Boards, Foam Boards Material: Fiberglass, Carbon Fiber, PVC, Wood End User: Recreational Users, Professional Athletes, Schools, Rental Shops Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Chains, Direct Sales |
| Companies Covered | Malibu Boats, Centurion Boats, Hyperlite Wake, Liquidforce Wakeboards, Axis Wake, Ronix, MasterCraft Boats, SlingShot, Supra Boats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wakeboard Market Evolving Landscape
Bio-based chemistry and automated manufacturing are compressing the traditional hand-craft production model, while regulatory chemistry restrictions and shifting rental procurement patterns are rewriting competitive requirements.
Flax fiber reinforcement is overtaking conventional E-glass in mid-range board laminates. European manufacturers have scaled bio-compatible layups that sustain flex fatigue performance across seasonal rental cycles. This material transition is overtaking price-competitive Asian imports in sustainability-focused procurement channels.
EPA VOC emission rules are constraining fiberglass lamination facility locations and curing process choices across the United States. Plant operators must install thermal oxidizers or switch to UV-cured resin systems, raising capital intensity for domestic production. Boat-board manufacturers with legacy solvent-based workflows face the steepest compliance retrofit burden.
Rental fleet procurement is consolidating toward multi-year durability contracts that unbundle board replacement from seasonal maintenance. Cable park operators in Germany and Texas are negotiating total-cost-of-ownership agreements that prioritize foam core density and rail reinforcement over initial unit price. This purchasing model shift is most visible in school and beginner-segment volume, where seasonal turnover rates determine lifetime margin calculations.
Wakeboard Market Segmentation
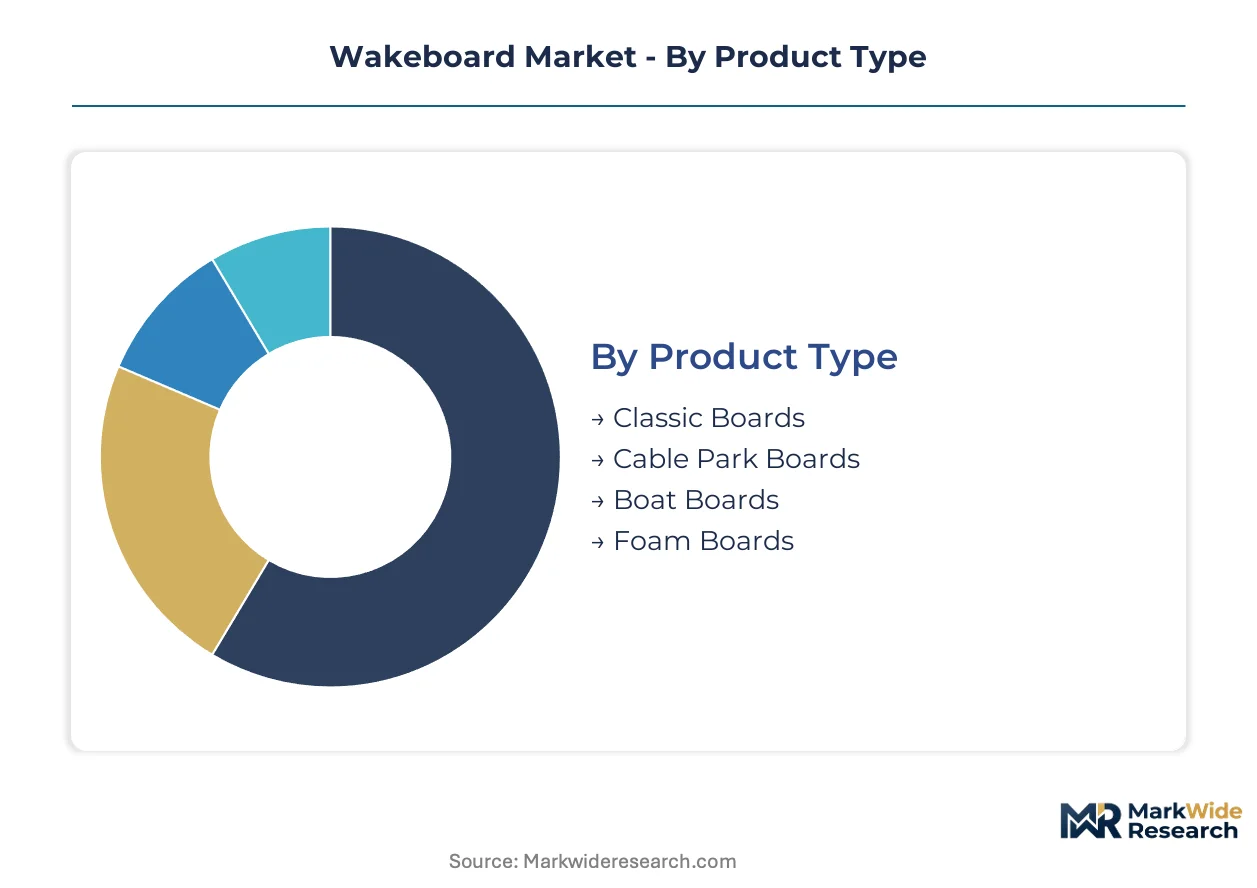
Wakeboard segmentation reveals divergent margin profiles across construction methods and user contexts. Product architecture, material chemistry, and channel access each reshape procurement economics for manufacturers and operators.
Product Type:
Integration depth separates standalone recreational equipment from purpose-built systems optimized for specific tow infrastructure.
- Boat Boards:Continuous rocker profiles with fiberglass-polyurethane construction dominate inboard ski boat pairings across freshwater lakes. Demand clusters in Texas, Florida, and California where private boat ownership sustains replacement cycles.
- Cable Park Boards:Three-stage rocker designs with reinforced rails withstand fixed-line tension and repetitive rail impacts. Thailand and Germany installations drive fleet procurement as rental-school models expand beyond traditional boat demographics.
- Classic Boards:Hybrid rocker configurations serve crossover users transitioning between boat and cable environments.
- Foam Boards:Compression-molded cores deliver durability for high-turnover rental operations with lower seasonal maintenance.
Volume placements concentrate in Boat Boards; the faster expansion belongs to Cable Park Boards.
Material:
Cost tier stratification separates premium performance laminates from volume-oriented constructions serving rental and entry segments.
- Fiberglass:E-glass layups with bio-epoxy compatibility dominate mid-range production under EU Green Deal chemistry mandates. EPA VOC constraints favor UV-cured resin workflows for domestic facilities.
- Carbon Fiber:High-modulus fiber reinforcement enables sub-6kg competition weights for professional aerial maneuvers. Chinese supply concentration creates procurement vulnerability for North American laminate shops.
- PVC:Closed-cell foam cores balance compressive strength with cost efficiency in school and beginner-tier boards.
- Wood:CNC-machined paulownia or bamboo cores deliver natural flex characteristics prized by custom builders and specialty retailers.
Revenue weighting favors Fiberglass for unit volume; Carbon Fiber claims the steepest expansion trajectory in premium performance tiers.
End User:
Customer type determines durability specifications, price sensitivity, and replacement frequency across the installed base.
- Recreational Users:Weekend riders at cable parks and lake communities prioritize versatility over specialization. Florida and Texas cable installations attract this demographic with session-based access eliminating boat ownership barriers.
- Schools:Institutional procurement emphasizes foam-core durability and rail reinforcement under multi-year total-cost-of-ownership contracts. German and Texan operators negotiate unbundled maintenance agreements.
- Professional Athletes:Custom rocker profiling and carbon fiber layups support competition-grade pop and landing stability.
- Rental Shops:Seasonal turnover economics favor replaceable consumables over premium construction.
Procurement volume concentrates in Recreational Users; Schools demonstrate the fastest procurement expansion under fleet consolidation trends.
Distribution Channel:
Channel maturity separates established specialty retail from emerging direct-to-consumer configurations capturing full margin.
- Specialty Stores:Deep inventory and fitting expertise sustain premium positioning in North American lake-house markets. Liquidforce Wakeboards anchors partnerships with regional retailers for boat-board distribution.
- Online Retail:Manufacturer-owned platforms enable custom rocker configuration and direct margin capture. Advanced riders configure three-stage profiles for cable-specific use cases.
- Sporting Goods Chains:ISO 14001 certification requirements gate procurement access for mass-market volume.
- Direct Sales:Bulk fleet contracts with cable park operators bypass retail markup for institutional placement.
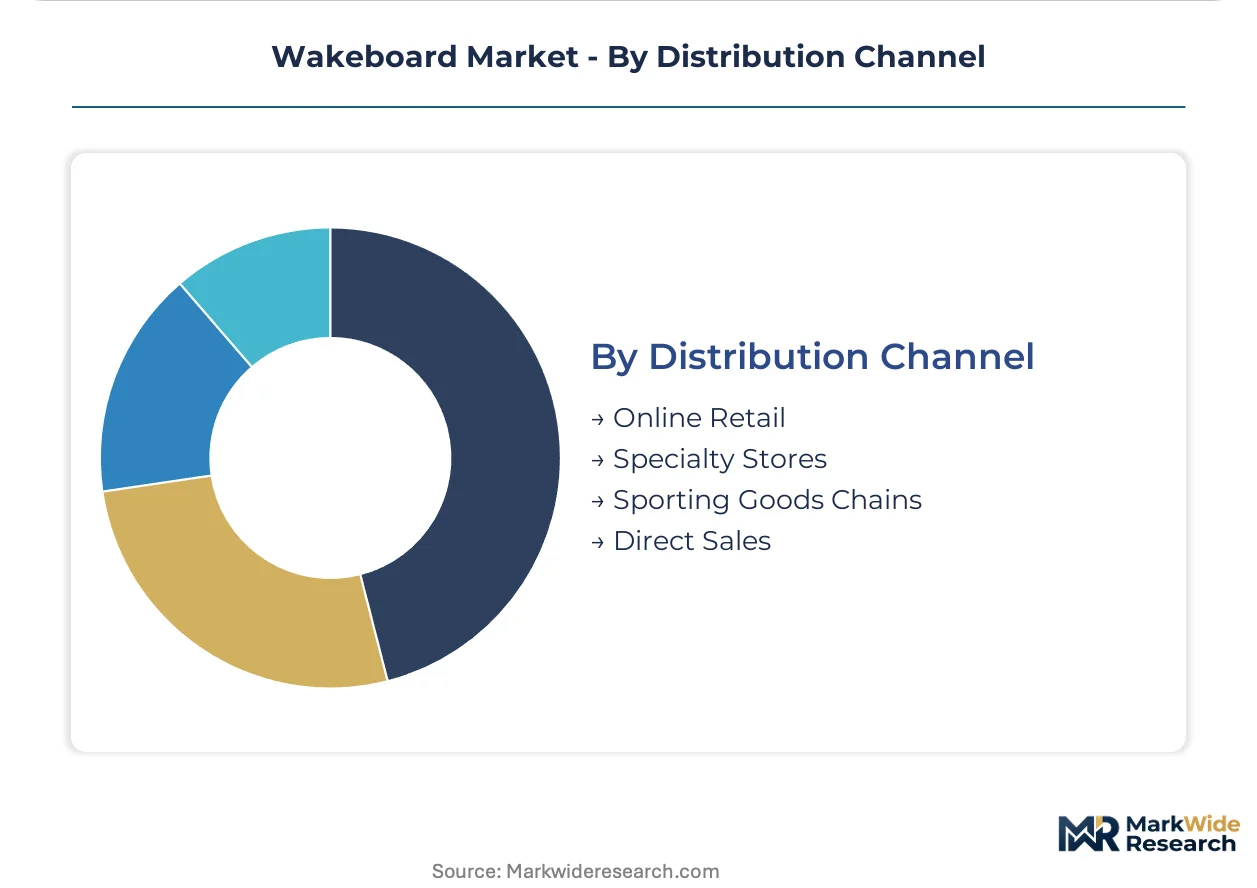
Transaction volume concentrates in Specialty Stores; Online Retail gains share fastest through configuration tools and geographic reach extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in coastal states with established marine industries, while consumption spreads inland through cable park proliferation. The United States dominates installed base volume, yet European regulatory pressure and Asian infrastructure buildout are redrawing competitive maps.
United States
Florida, California, and Texas host the densest cable park concentrations and competitive event calendars. EPA VOC emission rules constrain fiberglass lamination facility siting, pushing some production toward UV-cured resin workflows. Orlando and Austin metropolitan areas anchor rental-school procurement volume.
Germany
REACH compliance and EU Green Deal mandates accelerate bio-epoxy adoption among laminate shops serving European distribution. Berlin and Hamburg cable installations drive fleet procurement under multi-year durability contracts. Bavarian specialty retailers anchor premium-tier channel access.
Thailand
Bangkok-proximate cable parks attract recreational users lacking boat ownership across Southeast Asian markets. The country's national environmental regulator enforces emerging industrial emission standards for composite manufacturing. Phuket and Pattaya clusters expand rental-school infrastructure.
Australia
Coastal urban centers sustain boat-board replacement cycles alongside emerging cable installations. The Therapeutic Goods Administration and parallel state-level environmental agencies oversee chemical handling in manufacturing. Gold Coast and Sydney harbor concentrations support competitive athlete demand.
Canada
Great Lakes recreational boating sustains seasonal replacement demand for continuous rocker profiles. Health Canada and PMRA regulate chemical inputs in lamination processes. Ontario and British Columbia clusters balance domestic production with cross-border supply chain integration.
Wakeboard Market Competitive Landscape
The competitive structure tilts toward vertically integrated boat manufacturers with captive board lines alongside independent specialty fabricators. Consolidation pressure concentrates among inboard ski boat builders extending into complementary equipment, while mid-tier board specialists face margin compression from petrochemical input volatility. Two archetypes dominate: legacy marine OEMs leveraging distribution scale, and craft-oriented independents emphasizing custom profiling. Capacity expansion and bio-resin R&D partnerships constitute the primary competitive moves.
Among legacy marine OEMs, Malibu Boats and MasterCraft Boats exemplify the boat-builder archetype with integrated equipment portfolios. Hyperlite Wake occupies a position within the independent specialty tier, representing sustained R&D investment in bio-compatible layup systems. Liquidforce Wakeboards anchors the channel-partnership vector, exemplifying deep retailer integration alongside direct-to-consumer platform development.
| Leading Market Players |
|---|
| Malibu Boats |
| Centurion Boats |
| Hyperlite Wake |
| Liquidforce Wakeboards |
| Axis Wake |
| Ronix |
| MasterCraft Boats |
| SlingShot |
| Supra Boats |
| Others |
Value Network & Pricing Analysis
Polyurethane foam core costs cascade from petrochemical feedstock volatility through three distinct pricing tiers, compressing margins for mid-tier laminators while rewarding manufacturers with backward integration into bio-based resin systems. EPA VOC compliance burdens and Chinese carbon fiber concentration reshape procurement economics across domestic and offshore production footprints.
Pricing Analysis
Total-cost-of-ownership contracting anchors value-based pricing for cable park fleet procurement, where German and Texan operators negotiate multi-year durability agreements unbundling maintenance from unit replacement. Three-tier pricing structure across premium carbon fiber, standard fiberglass, and economy foam-core constructions stratifies by certification grade and rail reinforcement density. Pricing pressure stems from legacy boat-board inventory obsolescence as three-stage rocker designs displace continuous profiles. Schools and rental fleets exhibit highest price sensitivity; professional athletes demonstrate lowest sensitivity due to custom configuration requirements.
Supply Chain Analysis
High-modulus carbon fiber supply rests on Chinese specialty producers, creating single-source vulnerability for North American and European laminate facilities dependent on aerospace-grade fiber imports. Raw material flows draw from German bio-epoxy chemistry providers, Thai compression-molding operations, and domestic UV-cured resin formulators. Tariff exposure on Chinese fiber reinforcements compounds petrochemical input volatility for polyurethane core substrates. Distribution runs through specialty retailers in lake-house markets, direct-to-consumer platforms for custom profiling, and bulk fleet contracts with cable park operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite technician scarcity functions as the binding capacity constraint, propping pricing power for certified laminators while extending lead times for quality-audited production. This supply bottleneck sustains margin premiums for incumbents with established vocational training pipelines.
For Market Incumbents: Extend bio-resin R&D partnerships to lock in first-mover advantages under REACH and EU Green Deal compliance timelines. Anchor channel control through exclusive specialty retailer agreements in Florida and California lake-house markets. Add laminate capacity in low-VOC jurisdictions to circumvent EPA emission constraints on domestic plant siting.
For New Entrants and Emerging Players: Southeast Asian recreational users lacking boat ownership represent the most penetrable buyer archetype for cable park board specialization. Target Thailand and Indonesia coastal installations with foam-core durability positioning under rental-school procurement models. Pursue direct-to-consumer platform entry with custom rocker configuration tools for advanced rider segments.
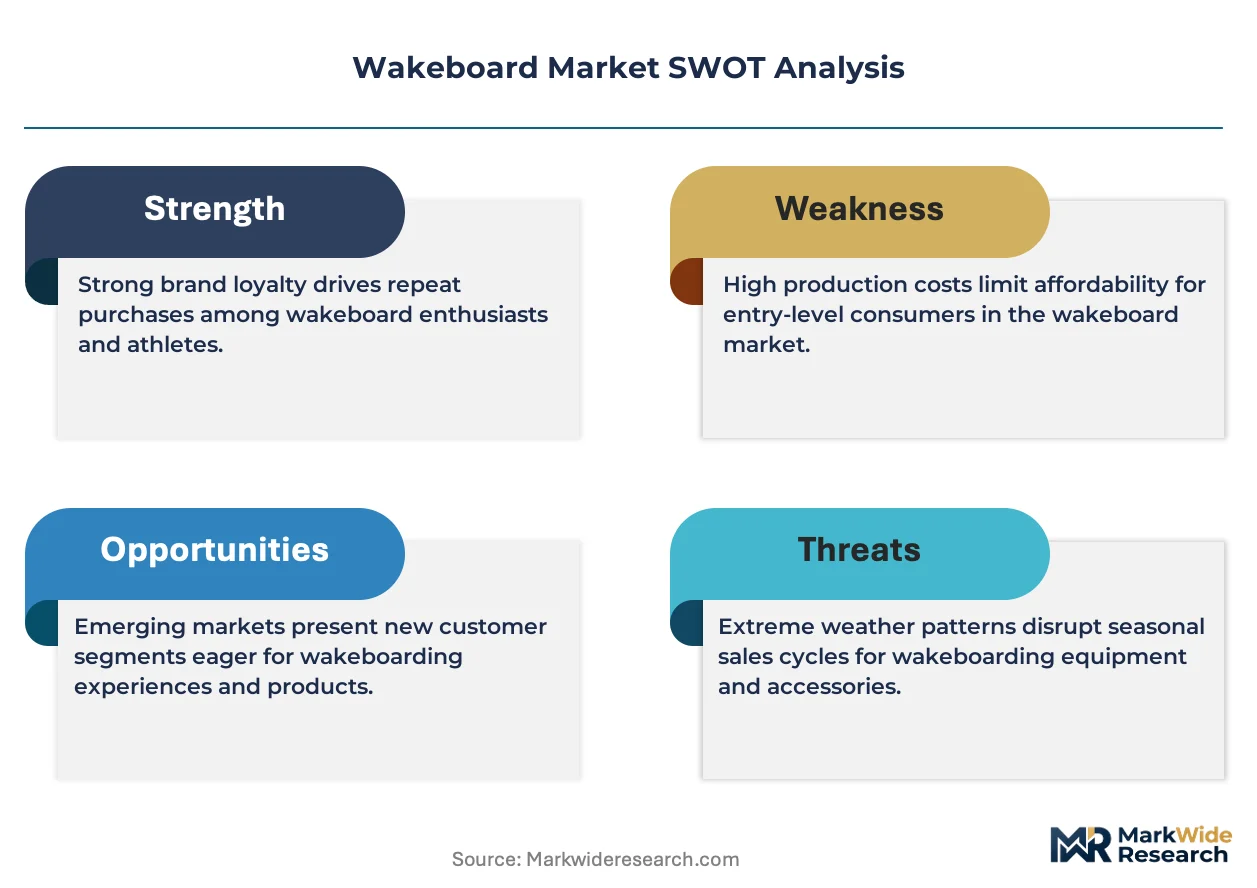
For Investors and Strategic Acquirers: ISO 14001 certification acceleration among mid-tier manufacturers is the leading indicator that environmental management compliance is becoming a gating factor for mass-market procurement access. Position acquisition screening around laminate shops with certified low-carbon core substrate capabilities and established cable park fleet relationships. Watch bio-epoxy adoption rates in European distribution channels as the inflection signal for chemistry transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Epoxy R&D Partnership | REACH compliance secures European procurement access against Asian import competition. |
| Cable Park Fleet Contract | Multi-year durability agreements with German operators lock in recurring revenue streams. |
| Direct-to-Consumer Platform | Custom rocker configuration captures full margin from advanced riders bypassing retail markup. |
| UV-Cured Resin Workflow | EPA VOC compliance enables domestic plant expansion without thermal oxidizer capital burden. |
| Recycled PET Core Substrate | Ocean-plastic recovery logistics satisfy retailer sustainability scorecards for closed-loop positioning. |
Research Methodology
Independent corroboration across cable park operators, composite manufacturing plant managers, and specialty retailer category buyers underwrites the qualitative findings on procurement pattern shifts. Secondary validation draws from EPA emission filings, EU ECHA substance restriction updates, and customs trade data on carbon fiber imports. The analysis triangulates bottom-up segment sizing with top-down market consolidation estimates across the wakeboard equipment value chain.
Comparable-period anchoring to historical cable park installation growth and boat-board replacement cycles establishes the forecast reference baseline across the projection horizon. Modeled dimensions include tow infrastructure type, material chemistry tier, end-user segment, and distribution channel configuration. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion constraints, incorporating bio-resin adoption curves and regional regulatory implementation timelines as industry-specific inputs.
Revisions become necessary when EPA VOC rule enforcement intensifies, EU Green Deal chemistry mandates accelerate, or Chinese carbon fiber export restrictions materialize. Forecasts reflect documented assumptions on technician workforce replenishment rates and cable park infrastructure investment continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Global Hydration Backpack Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Hiking Backpacks Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Recreational Use Water Chute Market