
 India Spectator Sports Market | 2026-2036
India Spectator Sports Market Size, Share, and Industry Trends Forecast 2026-2036
India Spectator Sports Market Insights
Broadcasting rights revenue is tilting from linear television toward over-the-top streaming platforms as cord-cutting accelerates among younger demographics. Disney Star leverages its IPL monopoly to sustain premium advertising rates across multiple language feeds. Viacom18 Media anchors its growth through exclusive digital rights for marquee cricket and football properties. Dream Sports competes aggressively with integrated fantasy gaming tied to live match broadcasts.
Spectator sports encompass organized athletic competitions designed for live or remote viewership, typically delivered through stadium infrastructure, broadcast networks, and digital streaming architecture with latency requirements under thirty seconds for real-time engagement. Revenue Stream segmentation reveals broadcasting rights commanding the dominant margin pool due to multi-year exclusivity contracts, while merchandise remains structurally underdeveloped relative to mature sports economies. Sport Type segmentation shows cricket absorbing disproportionate sponsorship and ticketing investment, though kabaddi and football are carving faster audience growth trajectories among non-traditional viewer bases.
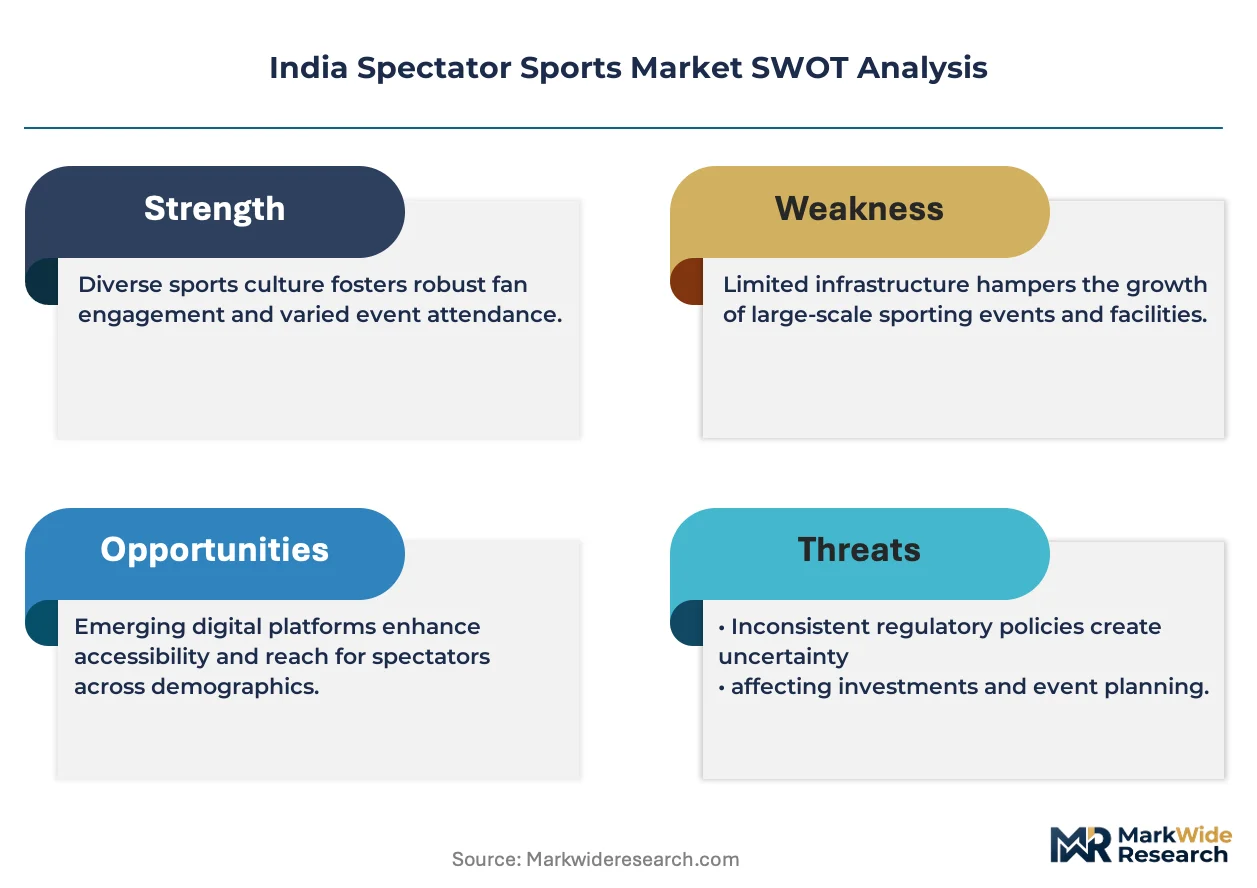
BCCI's self-regulatory framework governs player contracts and franchise operations, while TRAI mandates pricing transparency for sports broadcast channels under its tariff order regime. The Ministry of Information and Broadcasting enforces content certification standards for televised sporting events. Stakeholders must monitor how BCCI's commercial autonomy intersects with emerging antitrust scrutiny over media rights concentration.
Market Dynamics
Broadcasting rights concentration within Disney Star and Viacom18 Media is fragmenting audience access across paywalled platforms, forcing advertisers to navigate multi-platform inventory procurement and compressing reach efficiency for single-channel campaigns.
Growth Catalysts
- Khelo India Programme:The Ministry of Youth Affairs and Sports initiative channels public capital into stadium infrastructure across tier-2 and tier-3 cities, expanding addressable venue inventory for franchise leagues.
- 5G network densification:Telecom infrastructure upgrades in Maharashtra and Karnataka enable sub-10-second streaming latency, unlocking real-time fantasy gaming synchronization with live match broadcasts.
- Regional language feeds:Tamil, Telugu, and Kannada commentary tracks expand cricket's penetration into non-Hindi-speaking demographics previously underserved by national broadcasters.
Market Restraints
- TRAI tariff order compliance costs:Pricing transparency mandates for sports channels compress broadcaster margin flexibility and complicate promotional bundling strategies.
- Stadium infrastructure concentration:Maharashtra, Karnataka, and Tamil Nadu host disproportionate premium venue capacity, limiting match-day revenue scalability for leagues seeking geographic diversification.
- Linear television subscriber erosion:Cord-cutting among urban millennials deflates addressable audience base for traditional advertising-dependent broadcast models.
Strategic Opportunities
- North-east India expansion:Assam and Manipur present underpenetrated football viewership clusters where ISL franchise establishment could anchor regional media rights value.
- Blockchain-based ticketing:Smart contract verification systems enable secondary market royalty capture for franchises and reduce scalping-related brand damage.
- PLI scheme extension:Manufacturing incentives for sports goods production could localize merchandise supply chains currently dependent on Chinese imports.
Industry Challenges
- Antitrust scrutiny of BCCI media rights:Competition Commission of India examination of exclusive contract structures threatens renewal terms for incumbent broadcasters.
- Multi-platform content synchronization:Broadcasters must maintain technical parity across satellite, OTT, and mobile streams while managing divergent latency tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Spectator Sports Market |
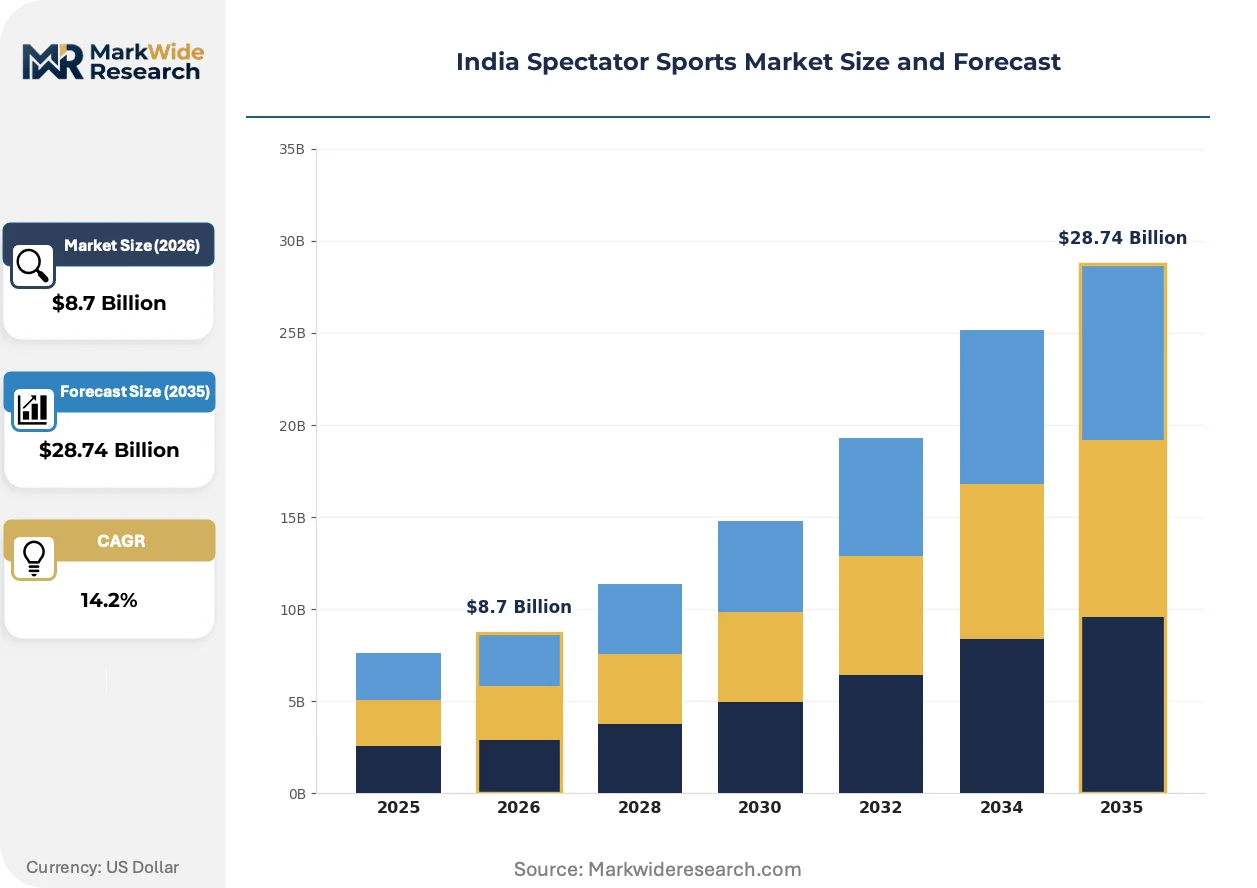
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sport Type: Cricket, Football, Kabaddi, Basketball Revenue Stream: Ticket Sales, Sponsorships, Merchandise, Broadcasting Rights Audience Demographics: Age Groups, Gender, Income Levels, Urban Areas Event Format: League Matches, Tournaments, Knockout, Exhibition |
| Companies Covered | Disney Star, Viacom18 Media, Sony Pictures Networks India, Zee Entertainment Enterprises, Board of Control for Cricket in India, Dream Sports, JSW Sports, GMR Sports, FanCode, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Spectator Sports Market Trends and Innovations
Technology convergence between real-time data feeds and interactive gaming layers is compressing the gap between passive viewership and active participation, redefining how broadcasters monetize attention spans.
AI-powered automated camera systems are rendering obsolete traditional manual broadcast direction for lower-tier cricket matches. State associations in Tamil Nadu and Karnataka deploy these systems for Ranji Trophy fixtures with minimal crew footprint. The technology compresses production costs for secondary-tier content that previously required full OB van deployment.
TRAI's tariff order regime mandates à-la-carte channel pricing transparency, forcing broadcasters to unbundle sports bouquets and exposing true willingness-to-pay elasticities. Disney Star and Sony have restructured subscription tiers to comply while preserving average revenue per user. Smaller regional sports channels face subscriber churn as price visibility concentrates demand on marquee properties.
Fantasy gaming integration is displacing conventional second-screen engagement as the dominant parallel activity during live broadcasts. Dream Sports and MPL embed real-time player statistics directly into match streams, capturing wagering-adjacent revenue streams that traditional broadcasters forfeit. Maharashtra and Karnataka exhibit the highest per-capita fantasy platform penetration, concentrating platform marketing spend in these states.
India Spectator Sports Market Segmentation
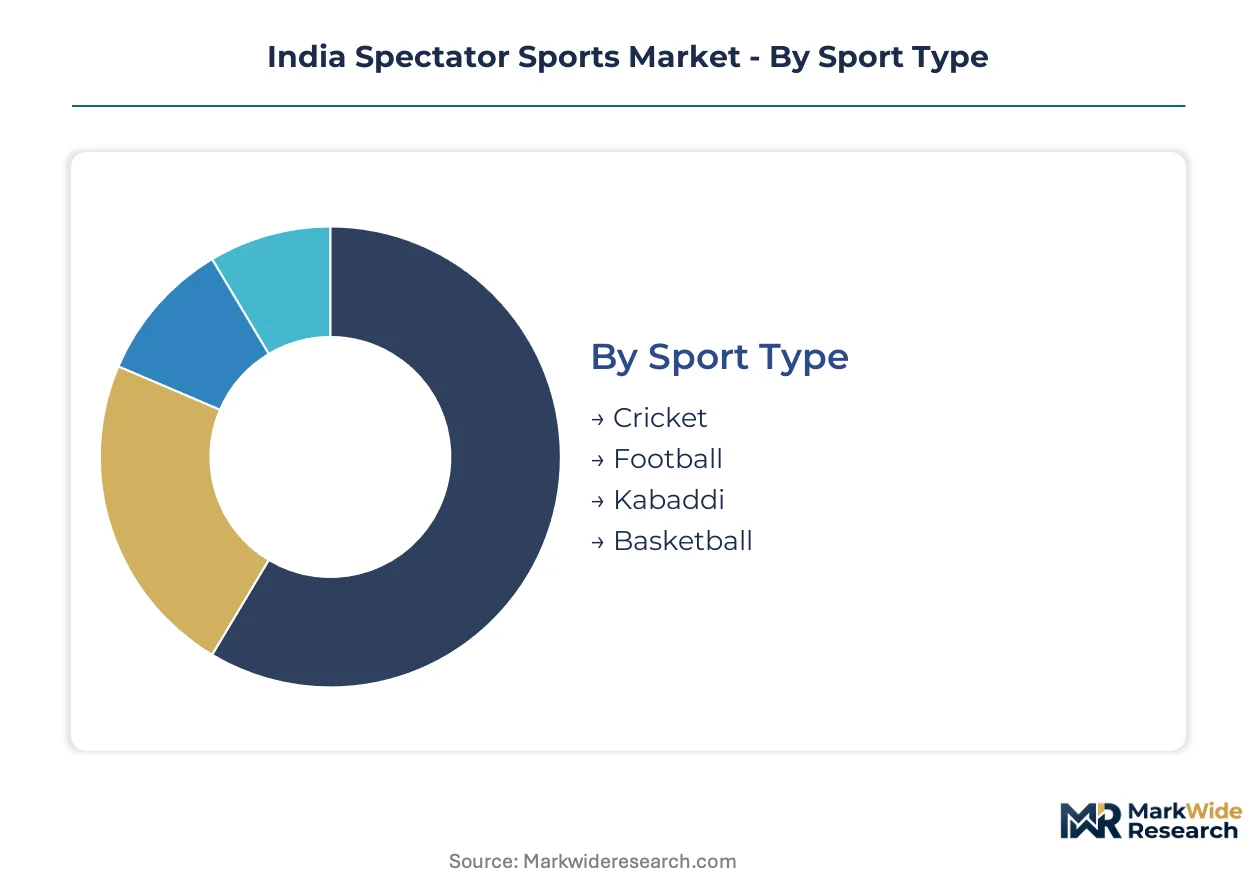
India's spectator sports market fragments across distinct consumption patterns that determine monetization architecture. Broadcasters, franchises, and venue operators calibrate investment based on how sport type, revenue stream, and audience demographics intersect with regional infrastructure availability.
Sport Type:
Commercial intensity varies dramatically across athletic codes, with infrastructure investment and media rights valuations clustering around properties that deliver predictable audience scale.
- Cricket:The BCCI governs a self-contained commercial ecosystem where IPL franchise valuations and international broadcast rights anchor the entire market's revenue ceiling. Maharashtra and Karnataka stadiums host the highest concentration of premium match-day inventory, though Tamil Nadu's Chepauk and Bengaluru's Chinnaswamy compete for marquee fixtures.
- Football:Indian Super League expansion is concentrating in football-penetrated geographies like Kerala, Goa, and West Bengal where European club allegiances have cultivated transferable viewership. ISL franchise establishment in Guwahati and Imphal targets underpenetrated north-eastern markets with demonstrated football culture but limited premium venue infrastructure.
- Kabaddi:Pro Kabaddi League exploits rural familiarity with the sport to build urban franchise loyalty, with Maharashtra and Gujarat franchises capturing disproportionate sponsorship value relative to production costs.
- Basketball:NBA India Games and 3x3 urban court installations in Delhi NCR and Mumbai build participation-to-viewership pipelines, though professional league economics remain subscale compared to cricket and football.
Established volume favors cricket; emerging adoption favors football.
Revenue Stream:
Margin architecture differs materially across monetization mechanisms, with exclusivity duration and scalability determining capital allocation priority.
- Broadcasting Rights:Multi-year exclusivity contracts for IPL and ICC events command the dominant share of franchise and federation revenue, with Disney Star and Viacom18 Media's platform concentration forcing advertisers into fragmented inventory procurement.
- Sponsorships:Front-of-jersey and perimeter advertising integrate brand messaging into live broadcasts and stadium visibility, with Maharashtra-based franchises extracting premium rates due to verified audience scale.
- Ticket Sales:Dynamic pricing for IPL knockout fixtures and international cricket tests venue revenue elasticity, though capacity constraints at Wankhede and Eden Gardens limit match-day upside.
- Merchandise:Replica kit and licensed apparel remain structurally underdeveloped versus mature sports economies, with import-dependent supply chains and limited retail distribution compressing category contribution.
Exclusivity value concentrates in broadcasting rights; operational leverage favors sponsorships.
Audience Demographics:
Consumption platform selection correlates tightly with generational cohort and urban density, determining advertising format effectiveness and subscription pricing tolerance.
- Age Groups:Urban millennials and Gen Z viewers drive OTT platform adoption, while 35-plus audiences sustain linear television subscription bases for cricket coverage.
- Gender:Women's cricket viewership expansion and WPL franchise establishment create addressable inventory previously excluded from premium sponsorship calculations.
- Income Levels:Premium seating and hospitality packages at Mumbai and Delhi venues target upper-income segments, while mobile-only streaming subscriptions capture price-sensitive mass audiences.
- Urban Areas:Metro concentration in Maharashtra, Karnataka, and Tamil Nadu determines fantasy gaming platform marketing spend allocation and regional language feed prioritization.
Platform migration favors younger demographics; purchasing power concentrates in urban agglomerations.
Event Format:
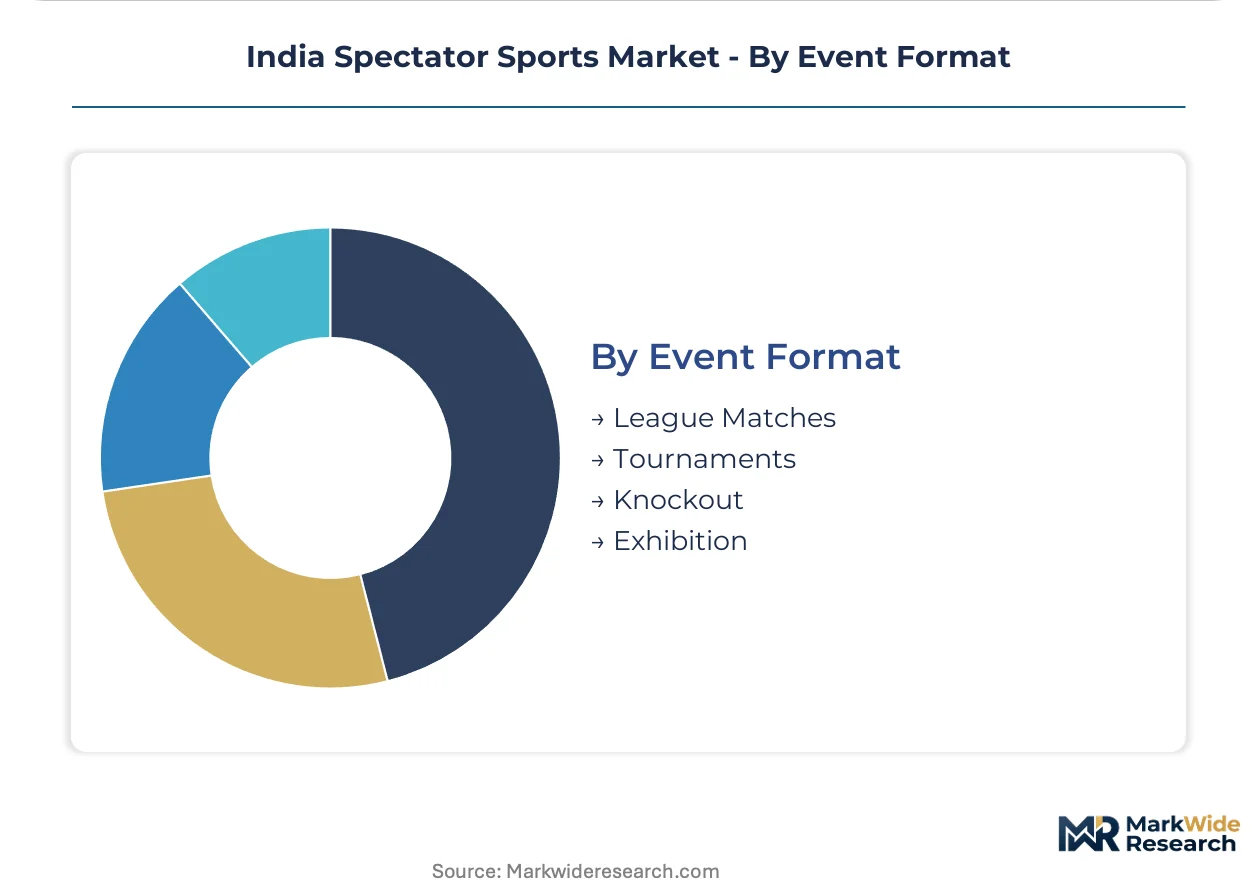
Competition structure governs production cost amortization and audience appointment viewing intensity, with implications for broadcaster scheduling and venue utilization rates.
- League Matches:Round-robin fixtures across home-and-away schedules maximize venue utilization and build sustained franchise loyalty, with IPL's 74-match calendar setting the template for property economics.
- Tournaments:Multi-team events like ICC World Cups concentrate global attention and command peak advertising rates, though host rotation limits India's guaranteed fixture allocation.
- Knockout:Single-elimination formats generate scarcity value for semifinal and final ticketing, with IPL playoff premiums reaching multiples of league-stage pricing.
- Exhibition:All-star fixtures and international club friendlies test market appetite for non-competitive content, with limited repeatability constraining revenue predictability.
Schedule density favors league matches; revenue per fixture peaks at knockout stages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennials in Maharashtra and Karnataka exhibit the highest willingness-to-pay for premium OTT sports subscriptions, while price-sensitive viewers in tier-2 cities sustain linear television demand for free-to-air cricket coverage.
Maharashtra
Wankhede Stadium and MCA Pune anchor the country's densest concentration of IPL match-day inventory and corporate hospitality packages. The state's sports infrastructure receives priority allocation under Khelo India stadium development grants administered by the Ministry of Youth Affairs and Sports. Mumbai's broadcast production cluster houses Disney Star and Viacom18 Media's primary cricket operations centers.
Karnataka
Bengaluru's Chinnaswamy Stadium commands premium ticketing rates for international fixtures while the city hosts the highest per-capita fantasy gaming penetration nationally. TRAI tariff order compliance has forced broadcasters to unbundle regional language feeds here, exposing true demand elasticity for Kannada commentary tracks. The state's 5G network densification enables sub-10-second streaming latency for real-time gaming synchronization.
Tamil Nadu
Chennai's Chepauk stadium sustains franchise cricket loyalty despite limited recent international fixture allocation, with Tamil commentary feeds expanding into non-traditional demographics. State association deployment of AI-powered automated camera systems for Ranji Trophy fixtures reduces production costs for secondary-tier content. The Tamil Nadu Cricket Association's commercial autonomy intersects with emerging antitrust scrutiny over media rights concentration.
West Bengal
Kolkata's Eden Gardens retains iconic status for test cricket and IPL knockout fixtures despite capacity constraints limiting match-day revenue scalability. Football viewership clusters here transfer European club allegiances into ISL franchise engagement, with East Bengal and Mohun Bagan anchoring regional media rights value. The state's underdeveloped merchandise retail infrastructure compresses category contribution relative to western markets.
Kerala
Football-penetrated demographics in Kochi and Thiruvananthapuram demonstrate transferable viewership from European leagues to ISL properties, though premium venue infrastructure remains subscale. The state's absence from Khelo India priority stadium allocation limits franchise league expansion potential. Kerala Blasters' sustained fan engagement despite on-field performance volatility exemplifies regional sports loyalty independent of winning metrics.
India Spectator Sports Market Competitive Landscape
Capability concentration sits with broadcasters holding exclusive multi-year rights contracts; scale advantage sits with platforms integrating fantasy gaming layers into live match streams. The market structure tilts toward duopolistic platform control with Disney Star and Viacom18 Media fragmenting audience access across paywalled services. Three archetypes dominate: legacy broadcasters with satellite infrastructure, pure-play digital platforms with gaming integration, and federation-aligned commercial operators controlling fixture calendars. Competitive moves center on exclusive rights acquisition and secondary revenue stream capture through wagering-adjacent products.
Among federation-aligned operators, the Board of Control for Cricket in India occupies a position exemplifying regulatory-commercial hybridity through its self-governing contract and licensing authority. Disney Star and Viacom18 Media represent the broadcaster archetype, with the former leveraging IPL monopoly for premium advertising rates and the latter anchoring growth through exclusive digital rights. Dream Sports sits within the integrated gaming tier, embedding real-time statistics into match streams to capture parallel engagement revenue that traditional broadcasters forfeit.
| Leading Market Players |
|---|
| Disney Star |
| Viacom18 Media |
| Sony Pictures Networks India |
| Zee Entertainment Enterprises |
| Board of Control for Cricket in India |
| Dream Sports |
| JSW Sports |
| GMR Sports |
| FanCode |
| Others |
Pricing and Supply Chain Analysis
Mumbai's broadcast production cluster concentrates exclusive media rights negotiation leverage, with Disney Star and Viacom18 Media's platform duopoly translating infrastructure scarcity into sustained premium advertising rates across Maharashtra and Karnataka venue networks.
Pricing Analysis
Long-term exclusivity contracts for IPL and ICC events anchor the dominant pricing structure, with multi-year offtake agreements locking in advertiser commitments before competitive bidding cycles. Price differentiation rests on language feed tiering and stadium hospitality bundling, with Kannada and Tamil commentary tracks commanding regional premiums. Cost compression in linear television subscriptions is intensifying because cord-cutting among urban millennials deflates addressable audience bases. Mass-market mobile-only subscribers exhibit highest price sensitivity, while corporate hospitality purchasers at Wankhede and Chinnaswamy demonstrate lowest elasticity.
Supply Chain Analysis
India's import-dependent merchandise supply chains face exposure to DGFT licensing requirements for sports goods manufacturing equipment, with Chinese equipment flows restricted under phased PLI localization mandates. Production capacity concentrates in China, Vietnam, and domestic Tamil Nadu textile clusters for replica kit manufacturing. Raw material dependencies span polyester fiber, synthetic leather, and RFID-enabled ticketing substrates. Single-source vulnerability runs through offshore apparel finishing facilities. Distribution feeds from centralized BCCI-licensed merchandise warehouses into stadium retail and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of real-time data infrastructure and low-latency streaming capability constrains competitive replication, with 5G densification expertise and fantasy gaming integration emerging as the decisive capability gaps separating market leaders from aspirants.
For Market Incumbents: Entrench exclusive fixture control through BCCI contract renewal lobbying and backward integration into venue infrastructure ownership. Threat of antitrust scrutiny over media rights concentration demands proactive regulatory engagement. Capacity addition in Assam and Manipur under Khelo India allocations secures geographic optionality against north-east competitor entry. For New Entrants and Emerging Players: Blockchain-based secondary ticketing in tier-2 cricket markets represents the most penetrable entry point, with AI-powered automated camera systems for Ranji Trophy production offering adjacent revenue capture. ISL franchise establishment in Guwahati and Imphal targets underpenetrated football viewership with transferable European club allegiances. Go-to-market execution should anchor on regional language feed partnerships with Tamil and Telugu broadcast operators. For Investors and Strategic Acquirers: Long-term, this sits as a platform-aggregation play because fantasy gaming integration and wagering-adjacent revenue streams are displacing conventional broadcast monetization. Acquisition targets should screen for real-time data feed infrastructure and sub-10-second latency technical capability. The signal to watch is TRAI tariff order enforcement intensity affecting sports channel bundling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Media Rights Acquisition | Multi-year IPL and ICC contracts lock in advertiser inventory before competitive cycles commence. |
| 5G Network Densification Partnership | Telecom infrastructure alliances in Maharashtra and Karnataka enable sub-10-second fantasy gaming synchronization. |
| Regional Language Feed Expansion | Tamil, Telugu, and Kannada commentary tracks unlock non-Hindi demographics previously underserved by national broadcasters. |
| Blockchain Ticketing Implementation | Smart contract verification at Wankhede and Eden Gardens captures secondary market royalties and reduces scalping damage. |
| North-East Venue Infrastructure Development | Khelo India stadium grants in Assam and Manipur anchor ISL expansion into football-penetrated but venue-constrained markets. |
Research Methodology
Operator-level perspectives from broadcast rights negotiators, franchise commercial directors, stadium operations managers, and fantasy gaming platform executives anchored the qualitative base. Secondary validation drew from BCCI annual reports, TRAI tariff orders, Ministry of Youth Affairs and Sports Khelo India disbursement records, and telecom infrastructure deployment disclosures. Bottom-up venue revenue modeling and top-down advertising spend allocation triangulated market sizing across the analysis window.
Scenario-bracketing framed the analytical approach, with optimistic and conservative cases reflecting divergent assumptions on 5G penetration velocity and fantasy gaming regulatory tolerance. Segmentation dimensions spanned sport type, revenue stream, platform delivery mode, and regional language feed adoption. CAGRs derived from historical rights fee escalation patterns and venue utilization elasticity curves. Forecast inputs incorporated stadium capacity expansion timelines under Khelo India and OTT subscriber migration trajectories.
Practitioners should monitor BCCI media rights antitrust proceedings and TRAI tariff order amendments for early signals of structural revision. Forecasts reflect assumptions on cord-cutting velocity and regional league expansion feasibility that material regulatory intervention could invalidate. Cross-checking against Ministry of Information and Broadcasting content certification enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Global Hydration Backpack Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Rafting Equipment Market
Outdoor and Adventure Activities
Global Ski Poles Market