
 Kayak Market | 2026-2036
Kayak Market Size, Share, and Industry Trends Forecast 2026-2036
Kayak Market Outlook
Aftermarket service revenue is fragmenting across regional outfitters and manufacturer-direct channels. Pelican International leverages its rotomolded manufacturing scale to control replacement parts distribution. Jackson Kayak anchors its position through specialized whitewater refurbishment programs. Old Town Canoe competes by extending its dealer network into seasonal maintenance services.
A kayak is a small, narrow watercraft propelled by a double-bladed paddle, typically constructed from rotomolded polyethylene, thermoformed ABS, or composite laminates such as fiberglass and Kevlar, with hull designs varying from flat-bottomed recreational stability to V-shaped touring efficiency. The craft serves commercial outfitters, competitive athletes, and leisure paddlers across freshwater, coastal, and whitewater environments. Sit-on-top configurations dominate rental and instructional segments due to self-bailing convenience and lower operator liability. Inflatable kayaks represent the fastest-growing type category as advanced drop-stitch PVC construction narrows the performance gap with rigid hulls. Polyethylene material grades retain volume leadership in budget and mid-range tiers, though composite laminates command premium positioning among expedition and racing buyers.
The United States Coast Guard enforces personal flotation device carriage requirements under federal boating safety regulations, directly shaping product bundling and retail compliance standards. EPA oversight of rotational molding emissions and state-level extended producer responsibility frameworks in California and Oregon influence domestic manufacturing location decisions and material recycling obligations. Stakeholders must monitor evolving access permit systems on federally managed waterways and anticipate how state park infrastructure investments will redistribute regional demand patterns.
Market Dynamics
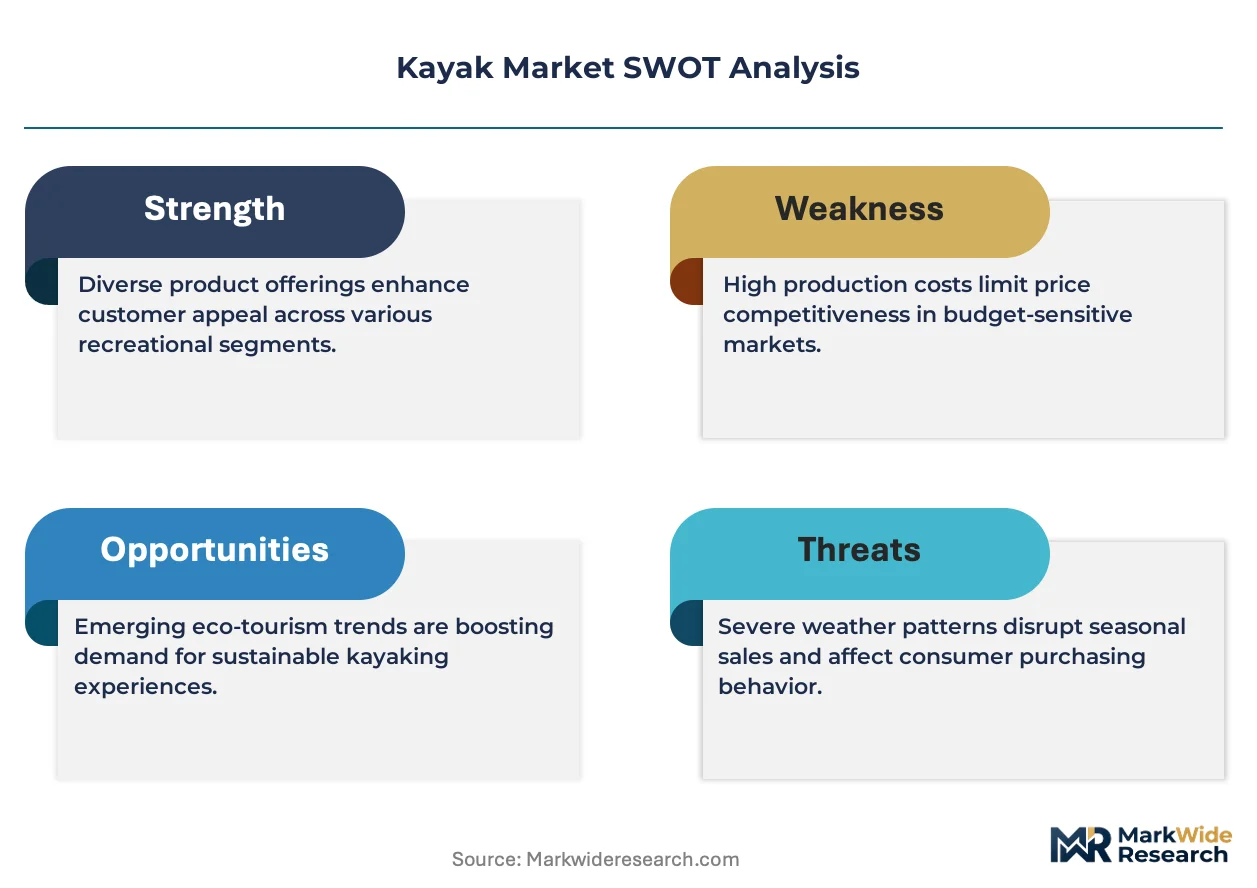
Rotomolded polyethylene hull technology is concentrating production among high-volume manufacturers while compressing margins for composite specialists. EPA emissions oversight and state-level extended producer responsibility frameworks in California and Oregon are reshaping domestic manufacturing location decisions.
Growth Catalysts
- Recreational participation surge:Leisure paddlers drive volume demand as coastal access programs in Florida and Washington expand launch infrastructure.
- REACH-compliant material innovation:European manufacturers adopt low-emission rotomolding compounds to satisfy ECHA substance restrictions.
- Drop-stitch PVC advancement:Inflatable kayak construction achieves rigidity parity with thermoformed ABS through high-pressure air chamber technology.
Market Restraints
- Petroleum feedstock volatility:Polyethylene resin prices fluctuate with crude oil benchmarks, squeezing margin predictability for rotomolded hull producers.
- Great Lakes manufacturing concentration:Hull production clusters in Michigan and Ohio create regional weather risk and logistics bottlenecks.
- Composite laminate substitution ceiling:Expedition and racing segments resist polyethylene migration due to weight and stiffness performance gaps.
Strategic Opportunities
- IRA clean manufacturing credits:Domestic producers qualify for federal incentives by retrofitting rotational molding facilities with electric heating systems.
- Direct-to-consumer channel expansion:Manufacturer-owned digital platforms bypass traditional dealer networks and capture full margin on accessory bundling.
- Adaptive paddle sports programs:Veterans affairs and disability recreation agencies in Texas and Colorado fund specialized sit-on-top configurations.
Industry Challenges
- Rotational molding technician scarcity:Skilled mold operators retire faster than vocational programs in Wisconsin and Minnesota replenish pipeline capacity.
- Multi-material recycling complexity:Cross-linked polyethylene hulls resist conventional reprocessing, complicating California and Oregon extended producer responsibility compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kayak Market |
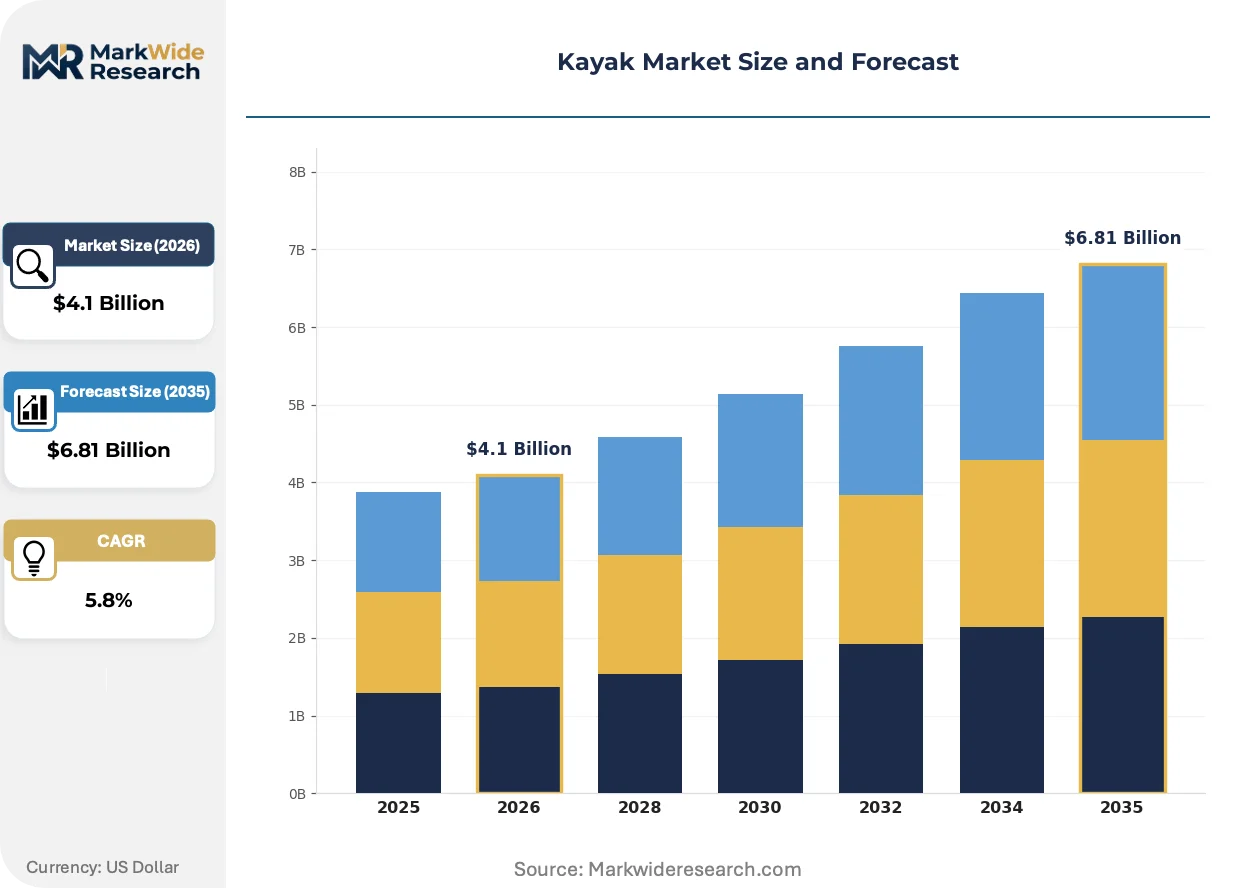
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Inflatable, Sit-On-Top, Touring, Whitewater Material: Polyethylene, Fiberglass, Kevlar, Wood End User: Recreational Enthusiasts, Professional Kayakers, Rentals, Tour Operators Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Perception Kayaks, Wave Sport, Pelican International, Old Town Canoe, Gumotex, Tahe Outdoors, Jackson Kayak, Feelfree US, Riot Kayaks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kayak Market Strategic Shifts
Hull manufacturing is digitizing quality control while regulatory pressure accelerates material transitions. Distribution channels fragment between experiential retail and direct digital fulfillment.
Drop-stitch PVC construction is digitizing inflatable kayak production through automated laser cutting and seam welding systems. Commercial outfitters in Arizona and Utah adopt these platforms for rental fleet standardization. The technology is digitizing inventory management by enabling real-time hull pressure monitoring via embedded Bluetooth sensors.
EPA rotational molding emissions standards tighten volatile organic compound thresholds for polyethylene hull production. Manufacturers in South Carolina and Georgia retrofit thermal oxidizers to maintain operating permits. California Air Resources Board oversight extends to supplier qualification, forcing resin distributors to certify low-emission formulations.
Rental and instructional buyers now specify connected fleet management as a procurement prerequisite. Traditional dealer showrooms lose share to manufacturer-direct experiential centers where buyers test hulls on adjacent water. This shift concentrates in the Mountain West where seasonal tourism operators consolidate purchasing through cooperative buying groups.
Kayak Market Segmentation
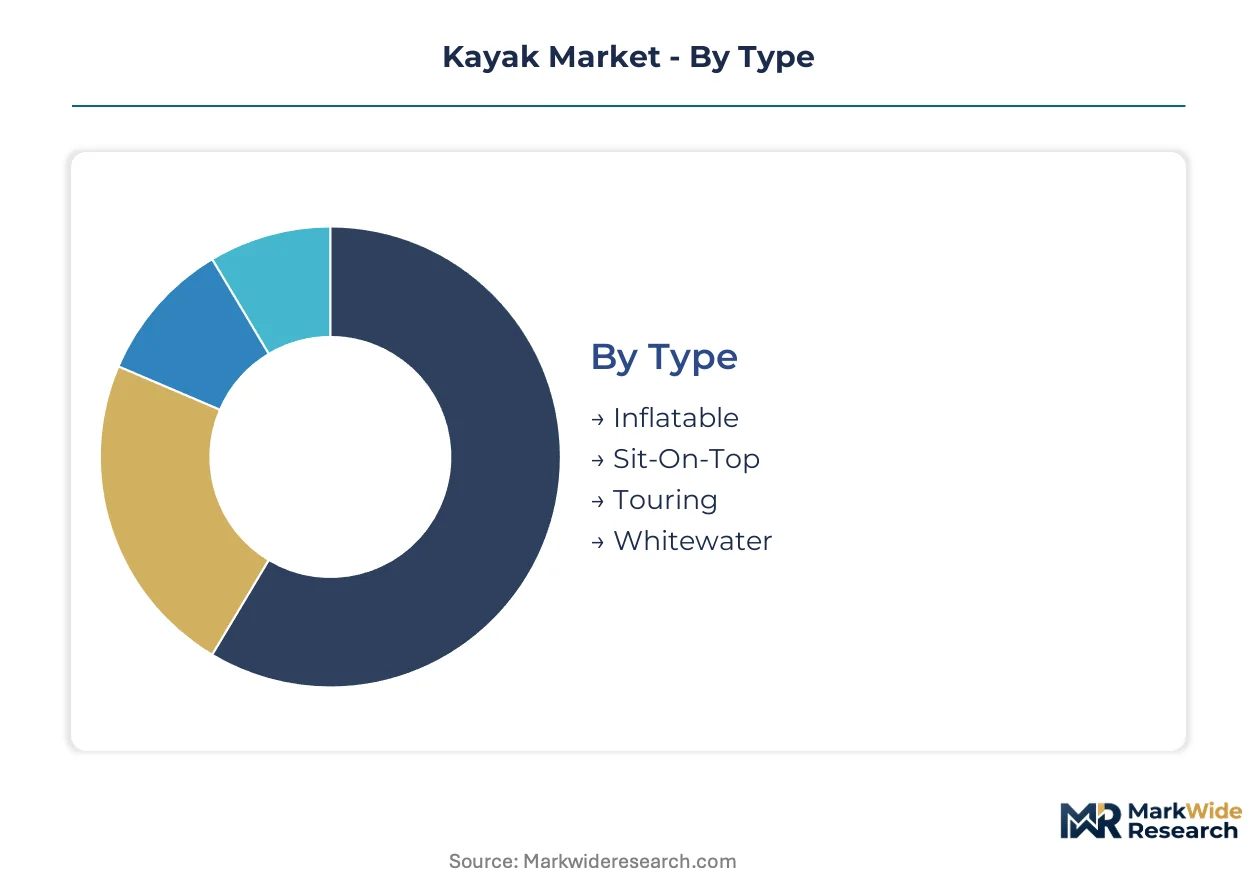
Hull configuration and construction material dictate service intervals, warranty exposure, and parts availability across the aftermarket. Segmentation reveals where specialized refurbishment competes against disposable replacement economics.
Type:
After-sales intensity varies sharply by hull format—self-bailing sit-on-top designs minimize field service while inflatable architectures demand seasonal inspection protocols.
- Inflatable:Drop-stitch PVC construction achieves 15 PSI rigidity through high-pressure air chambers. Arizona and Utah commercial outfitters standardize rental fleets on these platforms for transport logistics and storage density. Momentum concentrates in multi-day expedition operators seeking airline-checkable hulls.
- Sit-On-Top:Self-bailing scupper holes eliminate bilge pump requirements and reduce operator liability in instructional settings. Florida coastal access programs specify these configurations for municipal rental fleets due to capsized-recovery simplicity.
- Touring:V-shaped hulls with skeg or rudder systems optimize open-water tracking efficiency for expedition distances.
- Whitewater:High-rocker displacement hulls with reinforced chines withstand hydraulic impact forces in Class IV-V rapids.
Sit-On-Top holds the largest share; momentum sits with Inflatable.
Material:
Raw material selection drives manufacturing location decisions, EPA compliance exposure, and end-of-life recycling obligations.
- Polyethylene:Cross-linked rotomolded grades dominate volume production through thermal processing efficiency. Michigan and Ohio manufacturing clusters face seasonal weather risk and logistics bottlenecks during peak distribution windows.
- Fiberglass:Hand-layup composite laminates command premium positioning in racing and expedition segments where stiffness-to-weight ratios determine performance.
- Kevlar:Aramid fiber reinforcement reduces hull mass for portage-intensive wilderness routes.
- Wood:Strip-built cedar and plywood constructions serve custom craft buyers and educational boatbuilding programs.
Polyethylene retains volume leadership; Fiberglass captures margin concentration.
End User:
Procurement authority fragments between individual enthusiasts, institutional rental operators, and competitive athletes with divergent specification priorities.
- Recreational Enthusiasts:Leisure paddlers drive volume expansion through coastal access program participation in Washington and Florida. Weekend-use patterns favor stable, low-maintenance hulls with minimal transport complexity.
- Professional Kayakers:Sponsored athletes and coaches demand high-performance composite construction with rapid replacement guarantees for competition schedules.
- Rentals:Fleet operators prioritize durability metrics and standardized parts interchangeability across seasonal inventory rotations.
- Tour Operators:Multi-day expedition providers specify capacity-optimized hulls with integrated storage and rescue compatibility features.
Recreational Enthusiasts anchor demand volume; Tour Operators show steepest expansion trajectory.
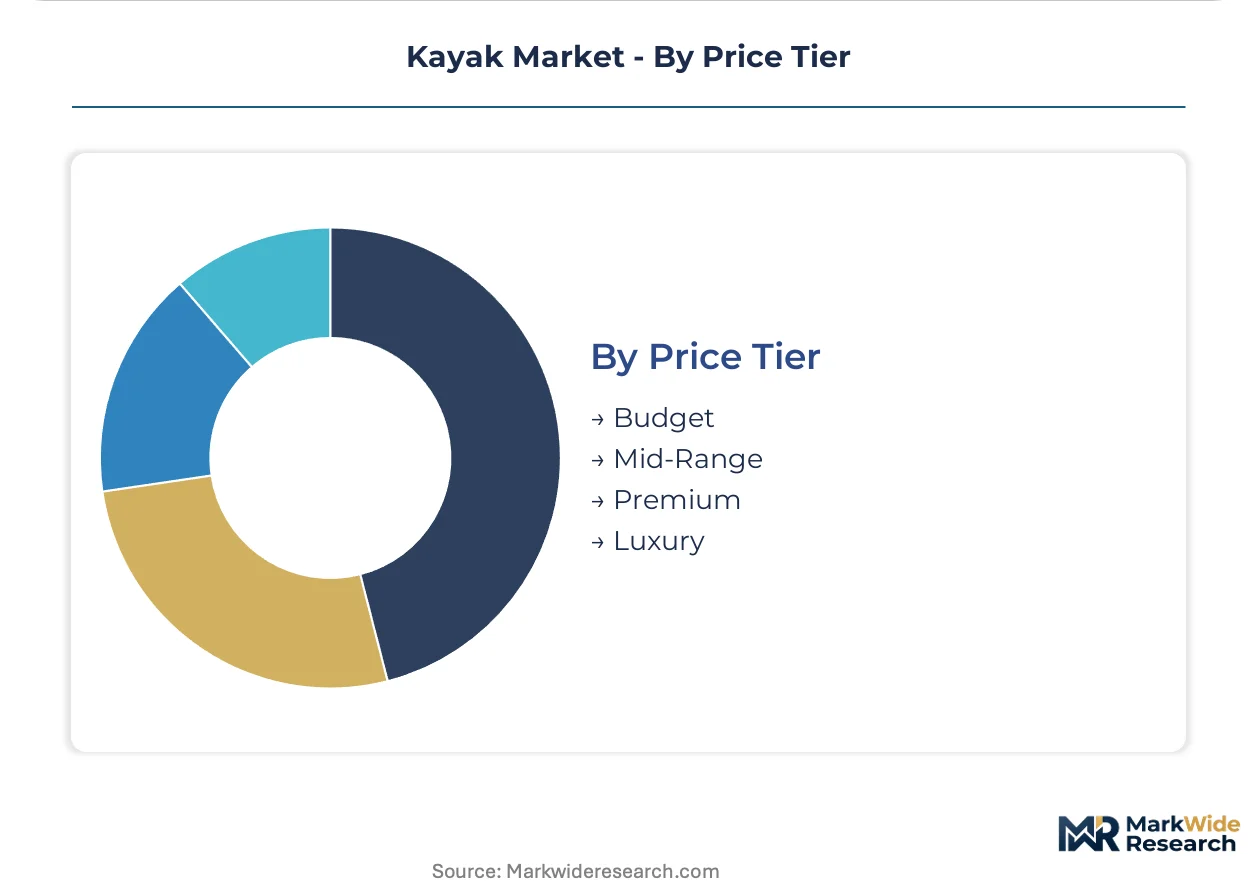
Price Tier:
Margin structure stratifies by material cost, labor intensity, and distribution channel control.
- Budget:Rotomolded polyethylene entry points serve first-time buyers through mass retail and seasonal promotional cycles.
- Mid-Range:Thermoformed ABS and cross-linked polyethylene bridge performance and affordability for committed recreational users.
- Premium:Composite laminates with expedition-grade outfitting target dedicated paddlers with multi-year ownership horizons.
- Luxury:Custom-built and limited-production craft serve collectors, competitive athletes, and expedition film production companies.
Mid-Range captures the widest buyer funnel; Luxury concentrates margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal access programs in the United States emphasize rental fleet standardization, while European buyers prioritize expedition-grade composite construction for wilderness tourism. Asian markets concentrate on inflatable platforms for urban storage constraints and airline portability.
United States
Florida and Washington coastal access programs expand municipal launch infrastructure and rental fleet procurement. The EPA enforces rotational molding emissions standards that reshape manufacturing location decisions in South Carolina and Georgia. Michigan and Ohio hull production clusters face seasonal logistics bottlenecks during peak distribution windows.
Germany
Wilderness tourism operators in Bavaria and Baden-Württemberg drive demand for lightweight expedition configurations. ECHA REACH compliance requirements accelerate adoption of low-emission rotomolding compounds among domestic fabricators. Industrial concentration in North Rhine-Westphalia supports component supply chains for thermoformed ABS hull assembly.
Canada
Park infrastructure investments in British Columbia and Ontario redistribute seasonal demand patterns toward multi-day expedition operators. Transport Canada mandates personal flotation device carriage requirements that influence retail bundling standards. Quebec manufacturing facilities serve Atlantic and Great Lakes rental markets through established distribution corridors.
Australia
Coastal tourism operators in Queensland and New South Wales specify self-bailing sit-on-top configurations for liability reduction. The Australian Maritime Safety Authority administers vessel safety equipment regulations affecting product specification. Melbourne-area fabricators concentrate on thermoformed ABS production for domestic and Asia-Pacific export markets.
United Kingdom
Canal and river trust programs in England and Wales expand paddle sports participation through infrastructure grants. The Maritime and Coastguard Agency enforces buoyancy aid standards that shape product bundling. Scottish Highlands tourism operators drive specialized demand for sea kayak configurations with integrated rescue compatibility.
Kayak Market Competitive Environment
Capability concentration sits with composite specialists; scale advantage sits with rotomolded polyethylene producers. The vendor base organizes around three strategic archetypes: high-volume rotational molders controlling replacement parts distribution, whitewater refurbishment specialists, and dealer-network service extenders. Dominant competitive moves include direct-to-consumer channel expansion and seasonal maintenance service integration.
Within the scale-driven tier, Pelican International represents rotomolded manufacturing consolidation, while Jackson Kayak exemplifies specialized refurbishment program development. Old Town Canoe anchors dealer-network service extension strategies. These three fabricators illustrate how geographic proximity to Great Lakes production clusters and coastal access program procurement channels shapes competitive positioning.
| Leading Market Players |
|---|
| Perception Kayaks |
| Wave Sport |
| Pelican International |
| Old Town Canoe |
| Gumotex |
| Tahe Outdoors |
| Jackson Kayak |
| Feelfree US |
| Riot Kayaks |
| Others |
Value Chain & Pricing Dynamics
Seasonal undercapacity at Michigan and Ohio rotational molding facilities during peak spring distribution windows compresses supplier pricing flexibility while elevating expedited freight premiums. Polyethylene resin contract structures favor annual offtake agreements with volume-tiered discounts, though spot purchases spike when petroleum feedstock volatility disrupts planned production schedules.
Pricing Analysis
Long-term offtake contracts dominate procurement between high-volume manufacturers and rental fleet operators, locking in polyethylene resin pricing across multi-season horizons. Price differentiation rests on hull material grade and EPA compliance certification tier, with low-emission rotomolding compounds commanding modest premiums. Cost compression in budget-tier rotomolded hulls is intensifying because petroleum feedstock volatility squeezes margin predictability. Recreational enthusiasts exhibit highest price sensitivity, while expedition tour operators prioritize performance specifications over unit economics.
Supply Chain Analysis
Export-control scrutiny on advanced drop-stitch PVC manufacturing equipment limits technology transfer to Asian inflatable kayak producers, constraining capacity expansion outside established licensing networks. Hull production draws from Michigan, Ohio, and South Carolina manufacturing clusters, with polyethylene resin sourcing tethered to Gulf Coast petrochemical infrastructure. Single-source vulnerability concentrates in rotational mold tooling fabrication, where specialized CNC machining capacity resides with a limited supplier base. Distribution runs through manufacturer-direct digital platforms and regional dealer networks serving coastal access program procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kayak aftermarket service revenue—encompassing seasonal refurbishment, parts distribution, and fleet management subscriptions—expands faster than hull hardware sales as commercial operators prioritize uptime guarantees over capital replacement cycles.
For Market Incumbents: Pre-empt composite laminate specialists by retrofitting rotomolded facilities with electric heating systems to capture IRA clean manufacturing credits before regulatory deadlines tighten. Consolidate replacement parts distribution through captive digital platforms to defend against regional outfitter fragmentation. Vertical integration into seasonal maintenance services locks in dealer network loyalty against Jackson Kayak's whitewater refurbishment programs. For New Entrants and Emerging Players: Pursue adaptive paddle sports program contracts with Veterans Affairs and disability recreation agencies in Texas and Colorado, where specialized sit-on-top configurations face limited incumbent competition. Target commercial outfitters in Arizona and Utah seeking drop-stitch PVC rental fleet standardization. Anchor go-to-market strategy through embedded Bluetooth sensor integration for real-time hull pressure monitoring. For Investors and Strategic Acquirers: Capital is best deployed toward rotomolded polyethylene specialists with established EPA compliance infrastructure and coastal access program procurement relationships, as these assets compound defensive moats across the analysis window. Monitor state-level extended producer responsibility framework adoption as the signal indicating margin pressure or consolidation opportunity in California and Oregon markets. Material shifts in federal boating safety regulation enforcement would require updated calibration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Manufacturer-owned digital channels capture full margin on accessory bundling beyond dealer networks. |
| Electric Heating Retrofit Program | IRA clean manufacturing credits offset capital expenditure for rotational molding facility upgrades. |
| Drop-Stitch PVC Fleet Standardization | Commercial outfitters in Arizona and Utah adopt automated laser-cut inflatable platforms for rental density. |
| Adaptive Paddle Sports Partnership | Veterans Affairs and disability recreation agencies fund specialized sit-on-top configuration development. |
| Seasonal Maintenance Service Integration | Dealer network extension into hull refurbishment captures recurring revenue from municipal rental operators. |
Study Parameters
Initial hypotheses were tested against primary input from rotational molding plant managers, commercial outfitter procurement directors, coastal access program administrators, and aftermarket service technicians, then refined through secondary validation against EPA emissions filings, state extended producer responsibility regulatory texts, and customs trade data for polyethylene resin imports. Bottom-up hull production estimates triangulated with top-down recreational participation surveys.
Demand-supply balance modeling across the projection horizon incorporated hull type segmentation by inflatable, sit-on-top, touring, and whitewater configurations; material grade tiers spanning polyethylene, thermoformed ABS, and composite laminates; and end-user categories including recreational enthusiasts, rental operators, and tour providers. CAGRs were derived from regression analysis of historical participation rates and infrastructure investment patterns, with petroleum feedstock price indices and EPA compliance cost curves as industry-specific forecast inputs.
Sensitivities concentrate around petroleum resin price volatility, rotational molding technician pipeline constraints in Wisconsin and Minnesota, and state-level extended producer responsibility enforcement intensity. Forecasts reflect documented assumptions regarding coastal access program funding continuity and drop-stitch PVC technology diffusion rates. Material shifts in federal paddle sports infrastructure appropriations or EPA emissions threshold revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Hiking Cleats Market
Outdoor and Adventure Activities
United States and Europe Horse Racing Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Rafting Equipment Market
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Outdoor Living Product Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Asia-Pacific Spectator Sports Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Snorkeling Market