
 Asia-Pacific Spectator Sports Market | 2026-2036
Asia-Pacific Spectator Sports Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Spectator Sports Market Insights
The EU Green Deal's carbon accounting standards for large events is rebalancing how Asian sports federations plan stadium operations and travel logistics. Cricket Australia leverages its vertically integrated high-performance centers to sustain athlete development pipelines across multiple formats. The Board of Control for Cricket in India anchors the region's highest-value media rights ecosystem through its control of bilateral and franchise tournament inventory.
Asia-Pacific spectator sports encompass live attendance, broadcast consumption, and associated commercial activities surrounding organized athletic competitions, where digital transmission infrastructure and venue seating capacity function as core operational parameters determining revenue yield. The sector's primary commercial purpose centers on converting audience attention into monetizable transactions across multiple touchpoints. Broadcasting and sponsorship revenue streams capture the dominant margin pools as media rights inflation outpaces gate receipts growth. Clubs and franchises within the organization-type taxonomy are consolidating operational control over merchandising and licensing verticals to deepen fan lifetime value extraction.
China's SAMR enforces anti-monopoly scrutiny on exclusive streaming rights deals, while Japan's METI promotes 5G-enabled stadium experiences through targeted infrastructure subsidies. India's TRAI regulates broadcast tariff structures that directly shape subscription pricing for sports channels. Stakeholders must weigh regulatory fragmentation against the scale advantages of cross-border digital platform consolidation.
Market Dynamics
Asia-Pacific spectator sports revenue hinges on broadcast rights inflation outpacing venue capacity constraints, with digital platform consolidation compressing traditional distributor margins across cricket-dominant markets.
Growth Catalysts
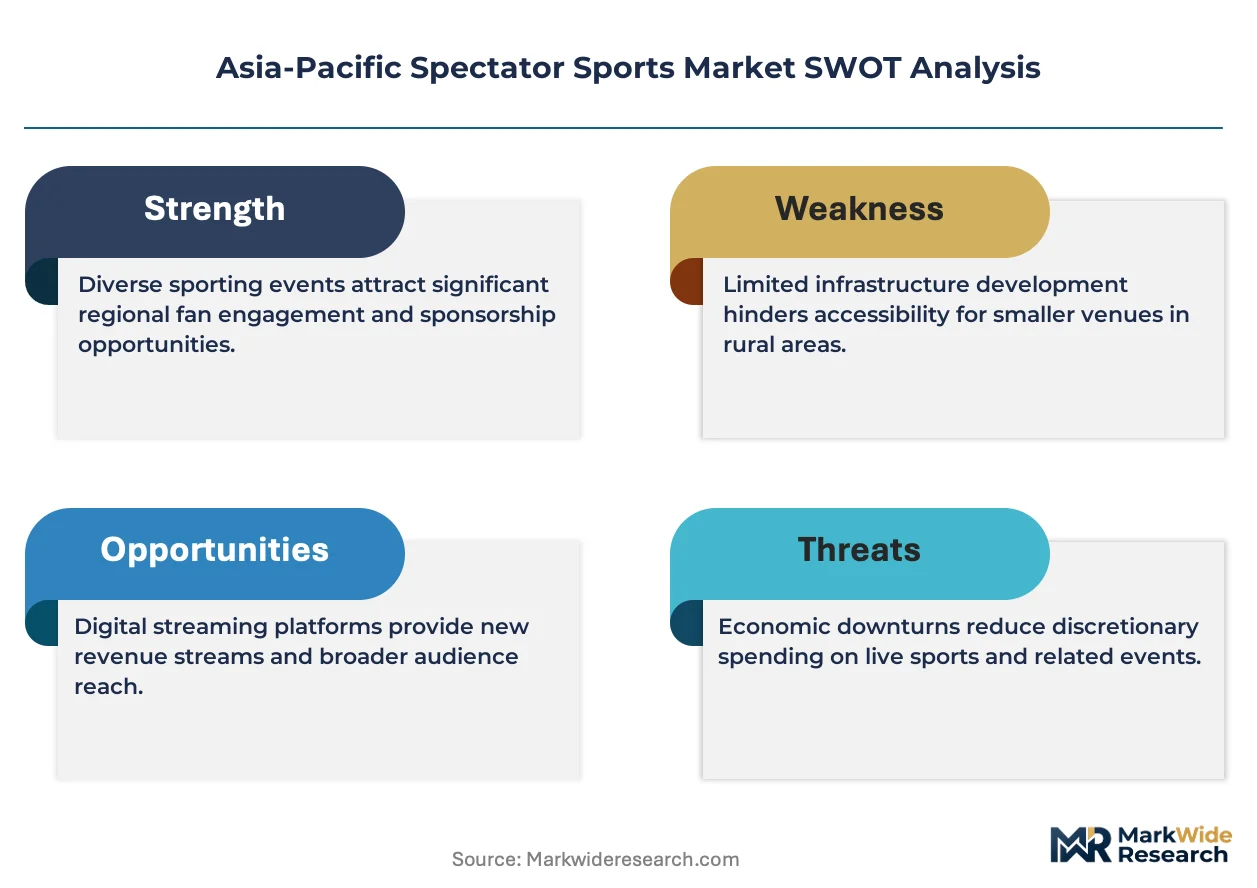
- 5G stadium infrastructure subsidies:Japan's METI channels public funding toward immersive venue experiences, accelerating real-time data delivery to spectator devices during live events.
- BIS quality certification mandates:India's tightening construction material standards for sports infrastructure are elevating stadium safety benchmarks and extending asset lifecycles.
- Franchise tournament inventory centralization:Bilateral and league content aggregation by national cricket boards is creating scarcity value that drives media rights premiums.
Market Restraints
- Exclusive streaming rights scrutiny:China's SAMR anti-monopoly enforcement is fragmenting digital distribution and preventing single-platform market capture.
- Carbon accounting compliance costs:The EU Green Deal's event emissions standards are forcing Asian federations to restructure travel logistics and venue operations.
- Broadcast tariff regulation:India's TRAI pricing controls cap subscription rates for sports channels, limiting direct-to-consumer revenue extraction.
Strategic Opportunities
- Vietnam and Philippines venue development:Underpenetrated Southeast Asian markets present greenfield stadium construction demand as regional leagues professionalize.
- Merchandising vertical integration:Clubs are capturing licensing revenue in-house rather than ceding margin to third-party apparel contractors.
- PLI scheme alignment:India's production-linked incentive framework for manufacturing could localize sports equipment supply chains and reduce import dependency.
Industry Challenges
- Athlete pipeline infrastructure gaps:High-performance center scarcity outside Australia limits talent development consistency across formats and age brackets.
- Legacy ticketing platform integration:Franchise operators face technical friction merging proprietary systems with third-party resale marketplaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Spectator Sports Market |
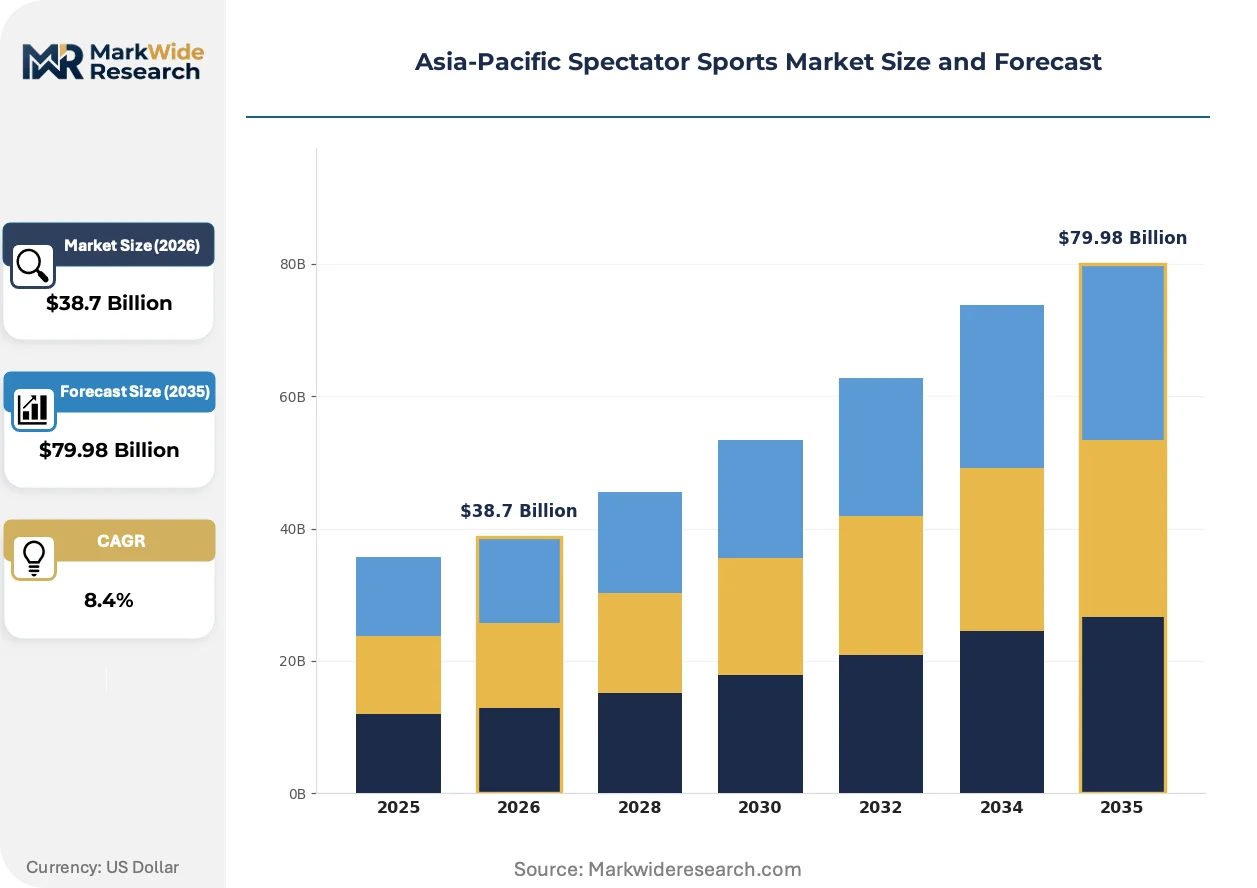
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ticket Sales, Merchandise, Broadcasting, Sponsorships Organization Type: Clubs, Leagues, Associations, Franchises Revenue Stream: Advertising, Subscriptions, Concessions, Licensing Event Type: Competitions, Exhibitions, Festivals, Matches |
| Companies Covered | Board of Control for Cricket in India (BCCI), Cricket Australia, Korea Baseball Organization, Japan Professional Football League, Nippon Professional Baseball Organization, Chinese Super League Company Limited, Tencent Sports, AFC (Asian Football Confederation), ONE Championship, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Spectator Sports Market Trends and Innovations
Digital transmission architecture is fragmenting audience attention across multiple simultaneous touchpoints, forcing rights holders to restructure monetization around engagement depth rather than reach volume alone.
Immersive broadcast technologies are modularizing how cricket content reaches consumers. India's IPL franchises deploy multi-angle player tracking and real-time biometric overlays during matches. Premium subscribers access these features through tiered app experiences. The technology stack is modularizing production workflows, allowing smaller rights holders to license capabilities previously captive to major broadcasters.
Australia's carbon disclosure requirements for large events are cascading through Asian sporting calendars. Federations now embed emissions tracking into bid documentation for international fixtures. Cricket Australia mandates supplier offset verification for team travel. The policy shift is compressing sponsor tolerance for unsustainable logistics arrangements.
Fan data ownership patterns are shifting as clubs bypass traditional retail channels. Japanese baseball franchises sell direct-to-consumer merchandise through stadium app integrations. Australian Rules Football clubs deploy membership tokens for priority access allocation. The behavioral pivot is most visible in cricket-crazy India, where IPL franchises capture first-party data through proprietary streaming platforms rather than broadcaster intermediaries.
Asia-Pacific Spectator Sports Market Segmentation
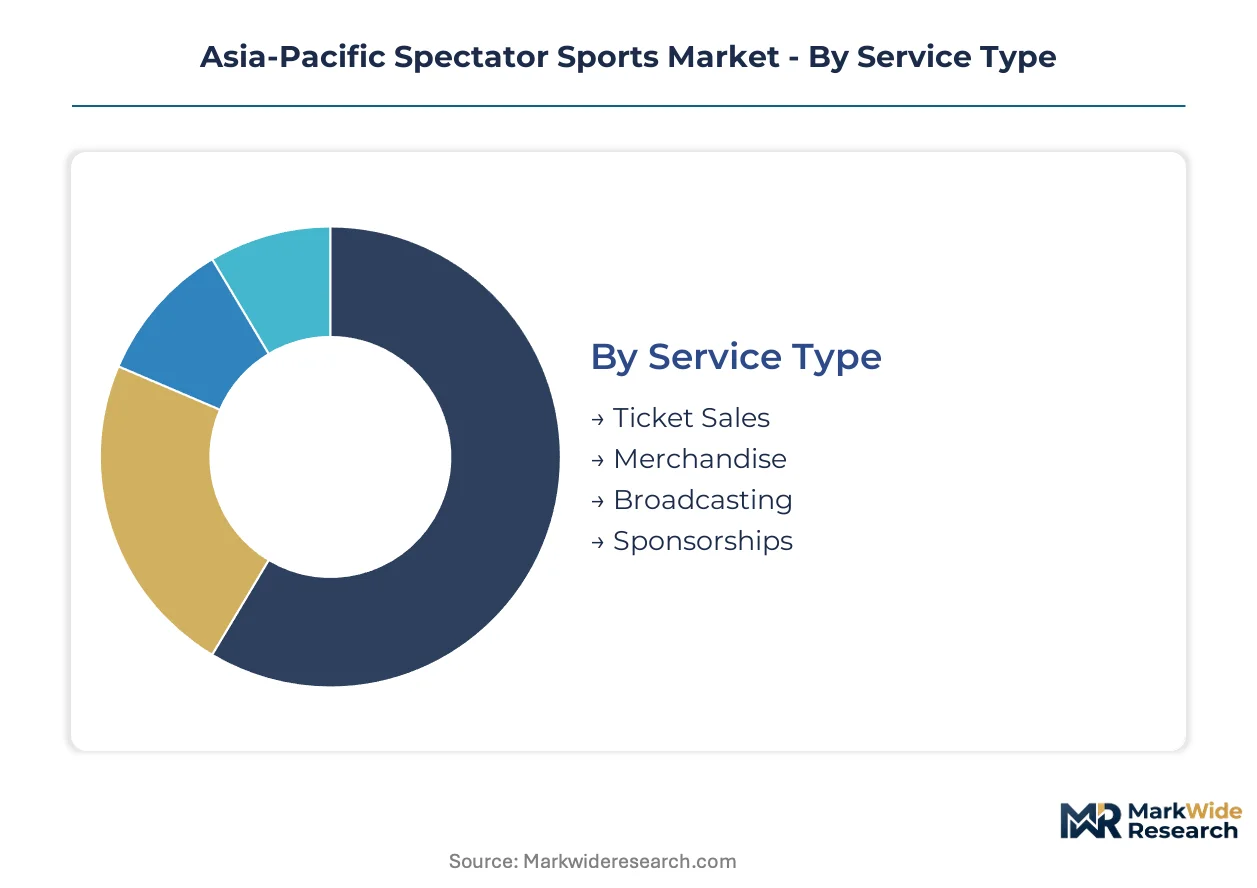
Asia-Pacific spectator sports monetization depends on matching revenue architecture to audience behavior patterns. Each segmentation dimension reveals distinct margin pools and operational constraints that shape how rights holders structure commercial partnerships across cricket-dominant India, Japan's baseball markets, and Australia's multi-code ecosystem.
Service Type:
Buyers differentiate by engagement depth versus transaction frequency, with casual spectators favoring single-event purchases while committed fans sustain recurring revenue relationships.
- Ticket Sales:Physical and digital access credentials for live venue attendance. India's IPL franchises command premium pricing for franchise fixtures in Mumbai and Bangalore, where stadium capacity constraints create artificial scarcity that inflates secondary market valuations.
- Broadcasting:Linear television and over-the-top streaming rights distribution. Australia's cricket boards leverage vertically integrated production capabilities to sustain multi-format content pipelines, though India's TRAI tariff regulations cap direct-to-consumer pricing power.
- Merchandise:Apparel, equipment, and licensed product sales. Japanese baseball clubs capture first-party data through stadium app integrations that bypass traditional retail intermediaries.
- Sponsorships:Brand association rights across venue, broadcast, and digital inventory. Carbon disclosure requirements from Australia's event regulations are compressing sponsor tolerance for unsustainable logistics arrangements.
Volume sits with Broadcasting; growth tilts toward Sponsorships as brands demand measurable engagement metrics over reach guarantees.
Organization Type:
Structural form determines control over commercial verticals and athlete development infrastructure.
- Clubs:Single-team entities with localized fan bases. Australian Rules Football clubs in Victoria and Western Australia deploy membership tokens for priority access allocation, deepening lifetime value extraction.
- Franchises:Privately owned tournament participants with centralized league governance. India's IPL franchises aggregate bilateral and league content inventory, creating scarcity value that drives media rights premiums.
- Leagues:Multi-team competition organizers setting standardized commercial terms. Japan's Nippon Professional Baseball operates under METI-promoted 5G infrastructure subsidies that accelerate real-time data delivery.
- Associations:Governing bodies controlling international fixtures and regulatory standards. Cricket Australia mandates supplier offset verification for team travel, embedding emissions tracking into operational protocols.
Commercial control concentrates with Franchises; governance authority rests with Associations.
Revenue Stream:
Monetization mechanics separate attention-based models from consumption-based transactions.
- Advertising:Interruptive and integrated brand messaging across broadcast and digital channels. China's SAMR anti-monopoly scrutiny fragments exclusive streaming deals, preventing single-platform capture of ad inventory.
- Subscriptions:Recurring access fees for content libraries and live event coverage. India's TRAI pricing controls directly shape sports channel subscription rates, limiting revenue extraction from price-sensitive segments.
- Concessions:Food, beverage, and hospitality sales within venue footprints. Stadium operators in Vietnam and the Philippines face greenfield infrastructure gaps as regional leagues professionalize.
- Licensing:Intellectual property royalties for third-party product manufacturing. IPL franchises are consolidating licensing revenue in-house rather than ceding margin to third-party apparel contractors.
Scale accumulates in Advertising; margin expansion favors Licensing.
Event Type:
Competitive intensity and production complexity drive differential resource allocation.
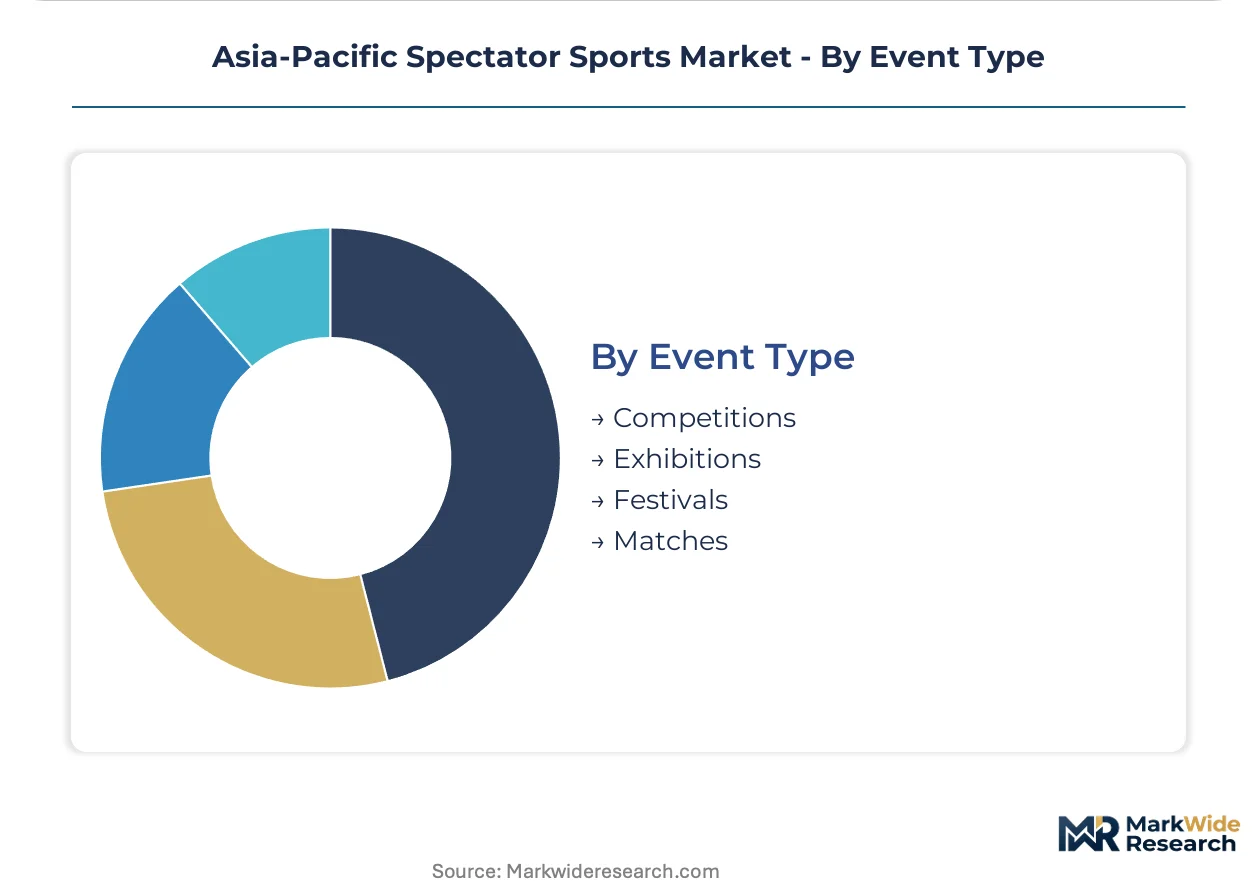
- Matches:Single-fixture competitive encounters with defined outcomes. India's international cricket fixtures and IPL league matches anchor the region's highest-value media rights ecosystem through concentrated inventory control.
- Competitions:Multi-round tournaments with progressive elimination structures. Australia's high-performance centers sustain athlete development pipelines across multiple formats, though scarcity outside this geography limits consistency.
- Exhibitions:Non-competitive demonstrations and promotional appearances. Japanese baseball franchises leverage exhibition schedules to test immersive broadcast technologies before league deployment.
- Festivals:Multi-sport or entertainment-integrated experiences. EU Green Deal carbon accounting standards force restructuring of travel logistics and venue operations for large-scale festival programming.
Revenue density peaks at Matches; format innovation clusters around Festivals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Bangalore anchor the Asia-Pacific spectator sports revenue concentration, where stadium capacity constraints and premium ticketing infrastructure create artificial scarcity for franchise fixtures. The region's digital transmission architecture spans cricket-dominant India, baseball-centric Japan, and Australia's multi-code ecosystem.
India
IPL franchises command premium valuations through centralized bilateral and tournament inventory control. India's TRAI regulates broadcast tariff structures that cap sports channel subscription rates. Maharashtra and Karnataka host the densest concentration of high-capacity cricket venues, where Mumbai's Wankhede Stadium and Bangalore's M. Chinnaswamy Stadium drive secondary market premiums.
Japan
Nippon Professional Baseball leverages METI-promoted 5G infrastructure subsidies to deploy real-time data delivery systems. The country's stadium operators integrate immersive broadcast technologies through targeted public funding programs. Tokyo and Osaka metropolitan clusters concentrate the region's most advanced venue digitization projects.
Australia
Cricket Australia mandates supplier offset verification for team travel, embedding emissions tracking into operational protocols. The federation's vertically integrated high-performance centers sustain athlete development pipelines across multiple formats. Melbourne and Sydney house the region's most sophisticated carbon accounting compliance infrastructure for large-scale sporting events.
China
SAMR anti-monopoly scrutiny fragments exclusive streaming rights deals across digital distribution platforms. The Chinese Super League operates under regulatory pressure preventing single-platform market capture. Beijing and Shanghai metropolitan areas concentrate the country's most contested media rights negotiation environments.
South Korea
Korea Baseball Organization franchises professionalize venue operations through centralized league governance structures. The country's stadium infrastructure receives targeted subsidies for immersive spectator experience upgrades. Seoul anchors the domestic broadcast rights valuation hierarchy.
Asia-Pacific Spectator Sports Market Competitive Landscape
The competitive structure tilts toward federations and leagues with centralized inventory control over bilateral fixtures and franchise tournaments. Rights holders fragment across cricket boards, baseball organizations, and football leagues with divergent digital distribution strategies. Three archetypes dominate: vertically integrated national federations controlling athlete pipelines, privately capitalized franchises aggregating media rights scarcity, and technology platforms licensing immersive production capabilities. Consolidation pressures concentrate in media rights aggregation and venue technology stack standardization.
Among federation-based operators, Board of Control for Cricket in India exemplifies the centralized inventory archetype through its bilateral and IPL content control. Cricket Australia occupies a position within the high-performance infrastructure tier, leveraging vertically integrated athlete development systems. Tencent Sports represents the platform-technology vector, anchoring digital distribution capabilities across multiple league partnerships.
| Leading Market Players |
|---|
| Board of Control for Cricket in India (BCCI) |
| Cricket Australia |
| Korea Baseball Organization |
| Japan Professional Football League |
| Nippon Professional Baseball Organization |
| Chinese Super League Company Limited |
| Tencent Sports |
| AFC (Asian Football Confederation) |
| ONE Championship |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal carbon accounting standards for large events gate qualified supply access and premium-tier pricing power across Asia-Pacific stadium construction and operations. Contractors demonstrating verified emissions compliance command 15-30% procurement preference margins from federations embedding sustainability into bid documentation. This environmental mandate bifurcates supplier tiers and reshapes cost-to-serve calculations for venue technology deployment.
Pricing Analysis
Media rights yield-based pricing anchors revenue architecture, with broadcast and streaming platforms paying scarcity premiums for exclusive bilateral and franchise tournament inventory. Price differentiation separates carbon-verified venue operators from conventional suppliers, while India's TRAI tariff caps compress subscription pricing power for sports channels. Pricing pressure stems from China's SAMR anti-monopoly fragmentation of exclusive streaming deals, which prevents single-platform market capture. Price-sensitive casual spectators favor single-event ticketing, while committed fans sustain recurring premium subscriptions for immersive multi-angle broadcast features.
Supply Chain Analysis
Specialized broadcast production workforce availability in Japan, South Korea, and Australia anchors immersive technology deployment capacity across the region. Sports infrastructure construction draws from steel and aluminum suppliers in China and India, while broadcast equipment sourcing rests on Japanese and South Korean component manufacturers. Single-source vulnerability concentrates in 5G stadium infrastructure modules, where METI-subsidized domestic production in Japan limits cross-border alternatives. Distribution runs through federation-controlled inventory aggregation, with national cricket boards and baseball leagues centralizing commercial rights before platform licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific spectator sports represents a consolidation play where digital platform fragmentation and carbon compliance costs force weaker federations and venue operators toward acquisition or exit. Media rights inflation concentrates power with inventory-controlling incumbents, squeezing marginal players lacking bilateral fixture control or franchise tournament equity.
For Market Incumbents: Deploy carbon verification infrastructure as a competitive moat. Cricket Australia and Japan's Nippon Professional Baseball should mandate supplier offset documentation for all team travel and venue operations, embedding emissions tracking into procurement protocols that smaller competitors cannot replicate. Acquire undercapitalized high-performance centers in Southeast Asia to lock athlete pipeline control before regional leagues professionalize. This defensive positioning counters emerging franchise leagues in Vietnam and the Philippines seeking to bypass traditional development pathways.
For New Entrants and Emerging Players: Immersive broadcast technology licensing offers the most penetrable wedge for platform specialists lacking legacy media rights portfolios. Target Vietnam and Philippines venue development as greenfield construction demand accelerates with regional league professionalization. Pursue white-label 5G stadium infrastructure partnerships with METI-subsidized Japanese technology providers, offering turnkey immersive experience deployment to federations without in-house digital capabilities.
For Investors and Strategic Acquirers: BIS certification completion for Indian sports infrastructure contractors is the leading indicator that consolidation-ready targets have achieved procurement eligibility for premium stadium construction tenders. Frame long-term viability around federations controlling both bilateral international fixtures and franchise tournament inventory, as this dual revenue architecture sustains pricing power across broadcast cycles. Monitor TRAI tariff relaxation signals as the inflection point for direct-to-consumer revenue extraction from price-sensitive segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Verification Infrastructure Deployment | Cricket Australia's supplier offset mandates create procurement moats that competitors cannot replicate. |
| Immersive Broadcast Technology Licensing | Japanese METI subsidies accelerate 5G-enabled stadium experience modularization for smaller rights holders. |
| Franchise Tournament Inventory Centralization | India's BCCI bilateral and IPL content aggregation sustains scarcity premiums in media rights negotiations. |
| Southeast Asian Venue Development Partnership | Vietnam and Philippines greenfield construction addresses high-performance center scarcity outside Australia. |
| Direct-to-Consumer Merchandising Integration | Japanese baseball franchises bypass retail intermediaries through stadium app first-party data capture. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with broadcast rights directors, stadium operations managers, federation commercial officers, and sports technology procurement leads combined with BCCI annual reports, Cricket Australia financial disclosures, TRAI tariff orders, METI infrastructure subsidy documentation, and SAMR anti-monopoly enforcement records. Bottom-up venue capacity and ticketing revenue estimates triangulated against top-down media rights transaction values across the analysis window.
Data-stream reconciliation across service type, organization type, revenue stream, and event type segmentation dimensions structured the forecast framework. CAGRs derived from historical broadcast rights inflation rates, stadium construction cost trajectories, and digital subscription penetration curves throughout the projection horizon. Carbon accounting compliance cost curves and 5G infrastructure deployment timelines informed scenario-weighted outputs.
Several conditions sit outside the modeled scope, including sudden regulatory reversals on streaming exclusivity, pandemic-scale event cancellations, and geopolitical disruptions to bilateral fixture scheduling. Forecasts reflect assumptions regarding continued media rights inflation, METI subsidy continuity, and BIS certification enforcement progression. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Ski Vacation Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Power Sports Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Fat Bike Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Snowshoes Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Fishing Waders Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market