
 South America Oil and Gas Downstream Market | 2026-2036
South America Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
South America Oil and Gas Downstream Market Analytics
Brazil's refinery expansion along its southeastern coast is fragmenting the traditional supply hierarchy that once centralized refined product flows. Petrobras dominates the upstream-to-downstream value chain through captive crude allocation and integrated logistics. Shell PLC competes via differentiated retail networks and lubricant specialization across the Southern Cone. YPF SA anchors Argentine supply security through its Plaza Huincul and Luján de Cuyo refining assets.
South America oil and gas downstream operations encompass crude oil refining, petrochemical conversion, and finished product distribution through pipeline, marine, and road networks. These facilities typically process heavy and extra-heavy crude grades requiring hydrocracking and coking units to yield transportation fuels, feedstock naphtha, and asphalt binders. Refined fuels occupy the largest value share given vehicle fuel demand across Brazil's flex-fuel fleet and Argentina's conventional gasoline market. Petrochemicals represent the fastest-expanding margin pool as Braskem and regional competitors convert ethylene and propylene outputs into polyethylene and polypropylene for packaging and construction applications. Lubricants sustain premium pricing through OEM certification requirements and extended-drain formulations for the region's mining and agriculture equipment sectors.
ANP in Brazil and Argentina's Secretaría de Energía enforce fuel quality specifications that mandate ultra-low sulfur diesel and gasoline blend standards, compelling refinery investment in hydrotreating capacity. Environmental licensing under IBAMA and provincial environmental agencies in Argentina constrains greenfield refinery development while favoring brownfield upgrades and biofuel integration. Stakeholders must weigh stranded asset risk against the capital intensity of residue upgrading as regional crude slates grow heavier and carbon border adjustments reshape export competitiveness.
Market Dynamics
ANP regulatory mandates for ultra-low sulfur fuels are forcing refinery operators across Brazil and Argentina to reallocate capital toward hydrotreating and hydrocracking upgrades rather than greenfield capacity expansion.
Growth Catalysts
- Brazil's flex-fuel fleet expansion:National biofuel blending mandates under RenovaBio sustain ethanol demand and drive investment in fluid catalytic cracking units optimized for heavier feedstock processing.
- ANP cleaner fuel specifications:Regulatory deadlines for sulfur content reduction in diesel and gasoline compel brownfield refinery modernization and residue upgrading capacity additions.
- Petrochemical feedstock demand:Braskem's polyethylene and polypropylene output requirements pull naphtha and ethylene production from integrated refining complexes in the Southeast industrial corridor.
Market Restraints
- Crude slate heaviness:Declining light sweet crude availability from mature fields increases reliance on extra-heavy grades requiring capital-intensive coking and hydrocracking infrastructure.
- Environmental licensing friction:IBAMA permitting timelines for refinery expansions routinely extend beyond capital planning cycles, constraining capacity additions to brownfield retrofits.
- Carbon border adjustment exposure:EU CBAM implementation threatens export competitiveness for refined products and petrochemicals destined for European markets.
Strategic Opportunities
- Argentine Vaca Muerta integration:Unconventional tight oil production growth creates feedstock arbitrage for Luján de Cuyo and Plaza Huincul refining assets seeking lighter crude slates.
- Biofuel refinery co-processing:Hydrotreated vegetable oil and pyrolysis oil integration into existing fluid catalytic cracking units enables renewable diesel and sustainable aviation fuel output.
- Colombia's underdeveloped downstream:Limited domestic refining capacity relative to crude production creates import substitution opportunity for product supply from Brazilian and Argentine exporters.
Industry Challenges
- Specialized hydroprocessing engineering scarcity:Limited regional availability of catalyst specialists and residuum upgrading technologists extends commissioning timelines for complex unit startups.
- Legacy SCADA integration complexity:Brownfield automation upgrades must interface with decades-old distributed control systems, multiplying cybersecurity vulnerability remediation costs.
- ASME pressure vessel certification timelines:Extended third-party inspection queues for high-pressure reactor vessels delay turnaround schedules and compress maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Oil and Gas Downstream Market |
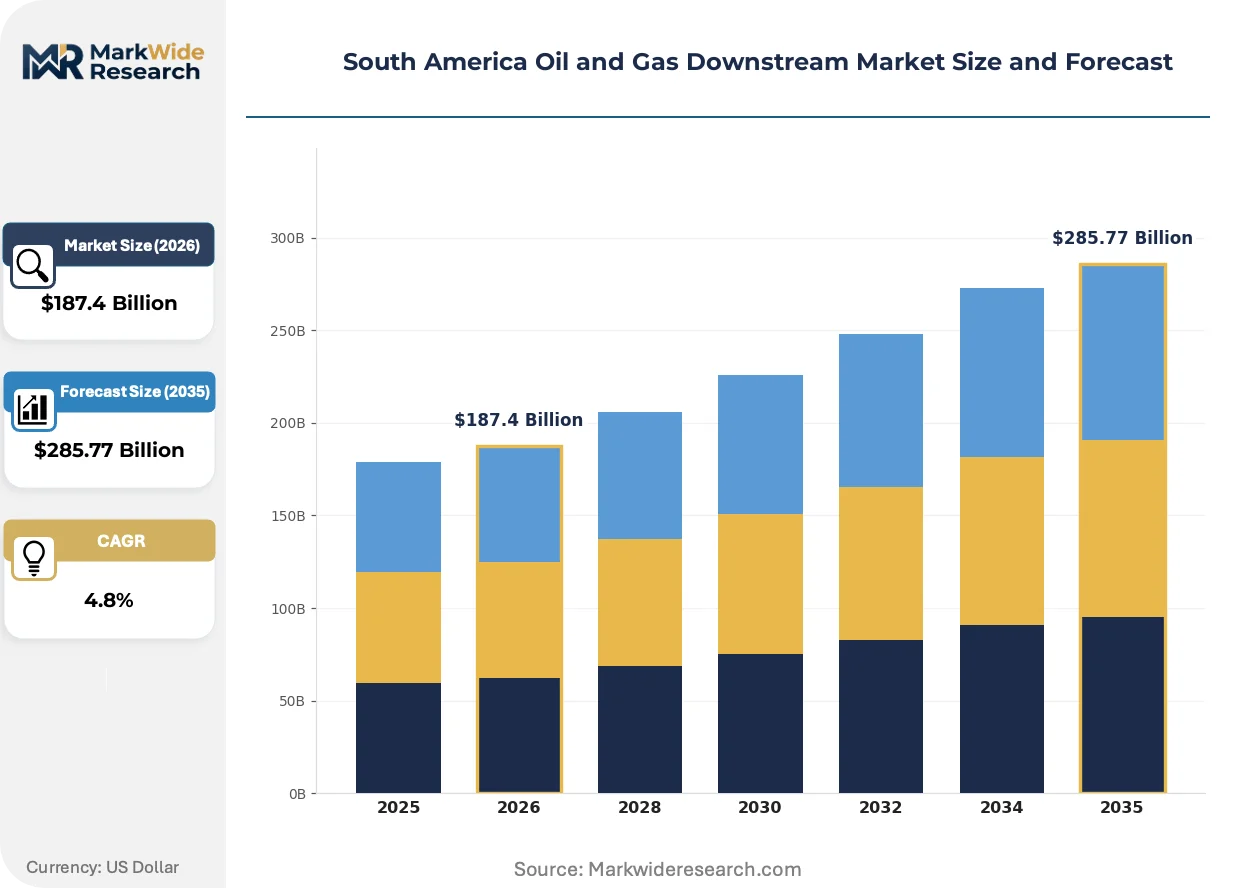
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Petrochemicals, Lubricants, Asphalt Service Type: Transportation, Storage, Trading, Distribution Client Type: Retailers, Industrial Users, Government Agencies, Oil Companies Application: Vehicle Fuel, Heating Oil, Feedstock, Solvents |
| Companies Covered | Shell PLC, Exxon Mobil Corporation, Petrobras, Alupar Investimento, TotalEnergies, YPF SA, BP PLC, Neoenergia SA, Ecopetrol SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Oil and Gas Downstream Market Evolving Landscape
Refinery operators are hybridizing conventional processing with biofuel co-processing and digital twin deployment to navigate carbon intensity reduction mandates while preserving utilization rates on heavy crude slates.
Residue upgrading technology is hybridizing hydrocracking and coking configurations to maximize middle distillate yields from extra-heavy Brazilian pre-salt and Argentine heavy crude streams. Petrobras and YPF are retrofitting existing vacuum residue units with ebullated-bed hydrocracking to avoid standalone coker investments. This hybridization is compressing the economic viability threshold for standalone greenfield refineries by extending the productive life of brownfield assets.
ANP Resolution 885/2022 establishes maximum sulfur content thresholds for diesel and gasoline that tighten progressively through 2028, compelling hydrotreater capacity additions across Brazil's refining fleet. Argentina's Secretaría de Energía mirrors these specifications through fuel quality decrees that harmonize Mercosur product standards. The transportation fuels segment bears the heaviest compliance burden, with distributors absorbing blending cost increases while negotiating pass-through mechanisms with retail networks.
Buyers in Brazil's industrialized Southeast are consolidating procurement through long-term offtake agreements directly with Petrobras refining complexes, bypassing traditional product import traders and wholesale distributors. Argentine agricultural cooperatives and mining operators are replicating this pattern, negotiating volume commitments with YPF's Luján de Cuyo facility. This concentration is most pronounced in São Paulo state's manufacturing belt, where flex-fuel vehicle fleet operators seek supply security through captive storage and direct pipeline connections.
South America Oil and Gas Downstream Market Segmentation
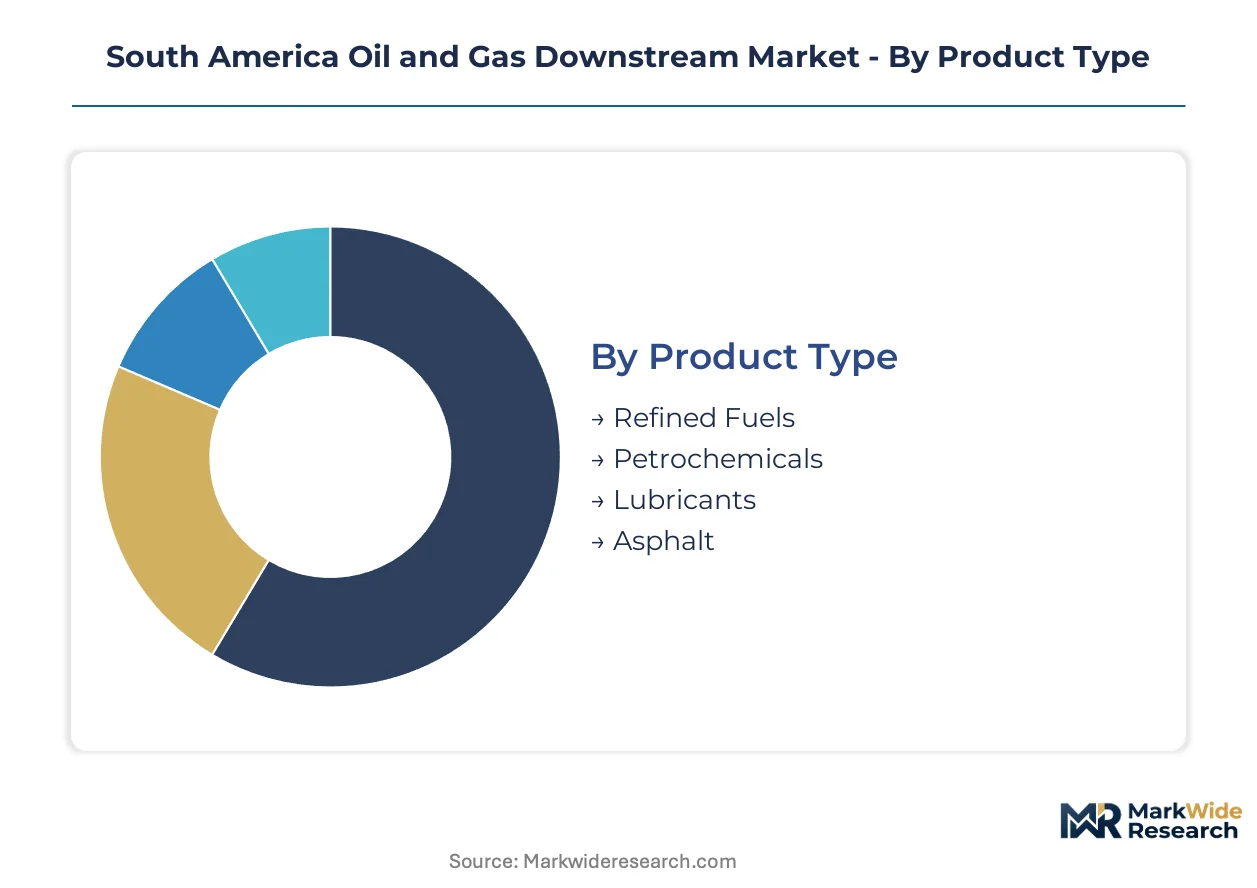
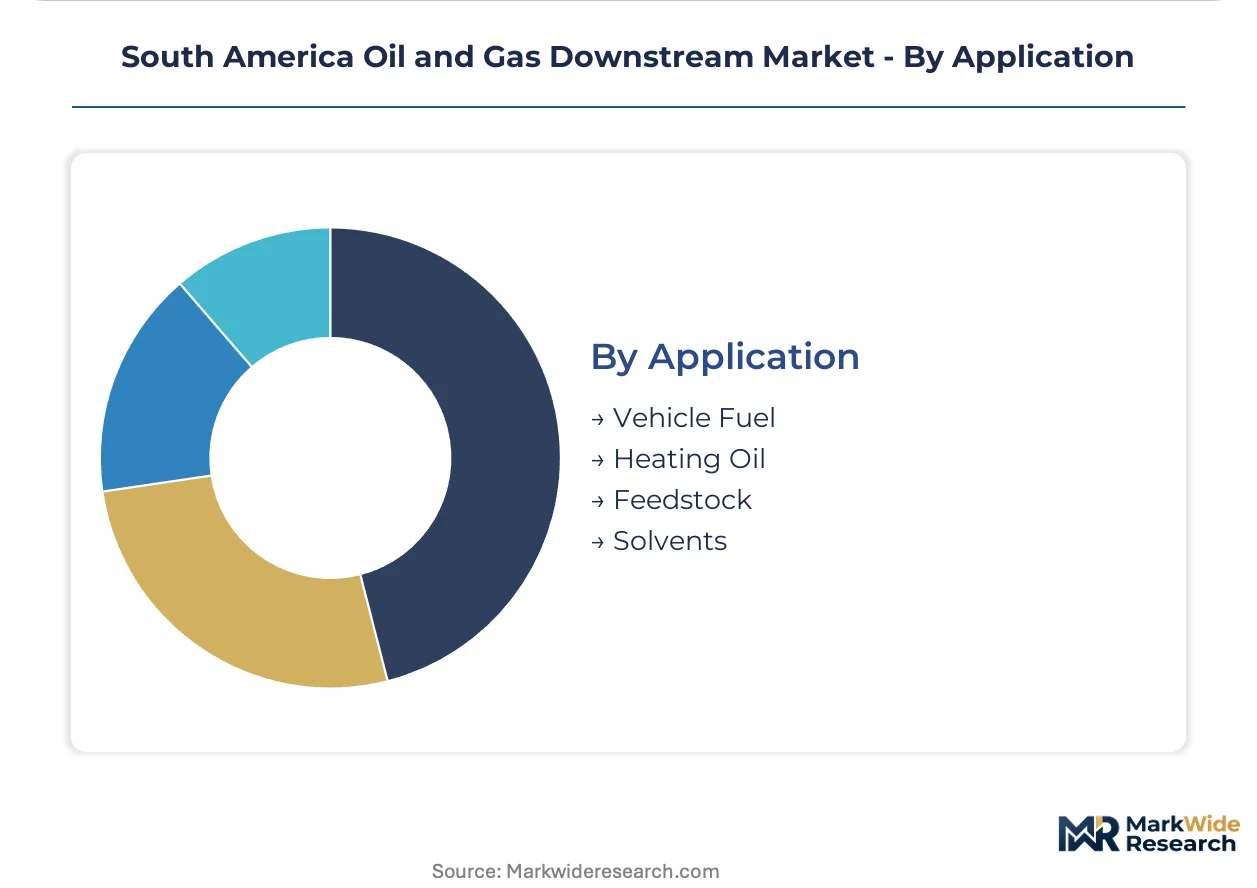
Segmentation in South America's downstream oil and gas market reveals how product specifications, logistics configurations, and customer procurement patterns fragment revenue pools across distinct operational models. Understanding these divisions clarifies where capital allocation concentrates and which service layers command premium margins.
Product Type:
Use-case spectrum spans vehicle mobility, industrial conversion, equipment protection, and infrastructure construction across Brazil and Argentina's core demand zones.
- Refined Fuels:Transportation fuels including gasoline, diesel, and marine bunkers processed through fluid catalytic cracking and hydrotreating units. Demand concentrates in São Paulo state's manufacturing belt where flex-fuel fleet operators secure direct pipeline connections to Petrobras refining complexes.
- Petrochemicals:Ethylene, propylene, and aromatic outputs feeding polyethylene and polypropylene production. Braskem's Southeast Brazilian complexes pull naphtha feedstock from integrated refineries, expanding most quickly as packaging and construction applications multiply.
- Lubricants:Engine oils, transmission fluids, and industrial lubricants formulated for extended-drain intervals. OEM certification requirements sustain premium pricing for mining equipment in Chile's copper belt and Argentine agriculture machinery.
- Asphalt:Binder materials from vacuum residue processing for road construction and waterproofing applications. Brazilian federal infrastructure programs and Argentine provincial road maintenance drive seasonal procurement patterns.
Established volume favors refined fuels; emerging adoption favors petrochemicals.
Service Type:
Cost tier separation distinguishes asset-heavy infrastructure operators from trading intermediaries and logistics specialists.
- Transportation:Pipeline, rail, and coastal marine movements of crude and refined products. Petrobras operates the continent's largest multiproduct pipeline network linking Southeast refineries to inland distribution terminals.
- Storage:Tank farm operations at refining complexes, port facilities, and inland depots. ANP mandates strategic stock requirements that reserve dedicated capacity for diesel and gasoline buffer inventories.
- Trading:Wholesale procurement, arbitrage, and term contract negotiations. Argentine agricultural cooperatives increasingly bypass traders for direct refinery offtake agreements with YPF.
- Distribution:Last-mile delivery through road tankers and retail network supply. Shell PLC differentiates through branded retail stations and lubricant shop-in-shop formats across the Southern Cone.
Capital intensity clusters in transportation and storage; margin expansion concentrates in trading and distribution.
Client Type:
Procurement scale and contract duration separate volume-committed industrial buyers from spot-market participants.
- Retailers:Branded fuel station networks and independent distributors serving consumer vehicle demand. Brazil's fragmented retail landscape consolidates around Petrobras, Shell, and regional independents competing on location density.
- Industrial Users:Manufacturing, mining, and agriculture operations purchasing diesel, fuel oil, and feedstock naphtha. Argentine mining cooperatives negotiate multi-year supply security directly with Luján de Cuyo refining output.
- Government Agencies:Defense, public transport, and emergency reserve procurement with mandated domestic sourcing requirements. ANP strategic reserve mandates specify minimum inventory days for critical fuel categories.
- Oil Companies:Integrated operators managing captive refining, trading, and retail assets. Petrobras internal transfers dominate Brazilian downstream value capture through controlled crude allocation.
Contract stability favors government and oil company procurement; price sensitivity peaks among retailers.
Application:
Volume concentration tracks mobility demand while specialty applications command formulation premiums.
- Vehicle Fuel:Gasoline, diesel, and ethanol blends powering Brazil's flex-fuel fleet and Argentina's conventional vehicle park. ANP sulfur specifications and RenovaBio biofuel mandates reshape refinery yield optimization.
- Heating Oil:Residential and commercial distillate fuel consumption concentrated in Argentine Patagonia and southern Brazil's winter demand zones. Seasonal inventory builds precede cold weather procurement spikes.
- Feedstock:Naphtha, propane, and residual streams supplying petrochemical crackers and industrial gas production. Braskem's polyethylene capacity expansion pulls increasing naphtha volumes from São Paulo state refineries.
- Solvents:Specialized refined fractions for coatings, adhesives, and chemical processing applications. Industrial manufacturing in Brazil's Southeast chemical corridor sustains niche solvent demand.
Volume dominance rests with vehicle fuel; specialty margin capture concentrates in feedstock and solvents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refining capacity clusters along Brazil's southeastern coastline and Argentina's Neuquén basin, with product flows radiating through pipeline networks into Paraguay, Uruguay, and Chile. State-linked operators control crude allocation and integrated logistics, while international traders arbitrage product deficits in Andean markets.
Brazil
Petrobras operates eleven refineries concentrated in São Paulo, Rio de Janeiro, and Bahia states, processing pre-salt heavy crude into gasoline, diesel, and petrochemical feedstock. ANP Resolution 885/2022 mandates progressive sulfur reduction through 2028, compelling hydrotreater investments at the Paulínia and Duque de Caxias complexes. The São Paulo industrial corridor anchors polyethylene demand from Braskem's integrated crackers.
Argentina
YPF SA's Luján de Cuyo and Plaza Huincul refineries process domestic heavy crude and imported light streams for the Buenos Aires-Paraná manufacturing belt. The Secretaría de Energía harmonizes fuel quality standards with Mercosur partners, accelerating hydrotreating retrofits. Vaca Muerta tight oil growth creates feedstock arbitrage opportunities for Neuquén-based processing units.
Chile
ENAP's Biobío and Concón refineries serve mining diesel demand in the Atacama copper belt and Santiago's transport fuels market. The Superintendencia de Electricidad y Combustibles enforces ultra-low sulfur diesel specifications aligned with California CARB standards. Antofagasta's mining cooperatives negotiate direct supply contracts bypassing traditional product importers.
Colombia
Ecopetrol SA's Barrancabermeja and Cartagena refineries operate below domestic crude production volumes, creating structural product import dependence. The Agencia Nacional de Hidrocarburos licenses biofuel blending mandates that reshape refinery yield optimization. Bogotá's Andean transport corridor concentrates diesel demand from trucking fleets serving Pacific port exports.
Peru
Repsol's La Pampilla refinery near Lima processes imported crude for the capital's vehicle fuel market and mining operations in the central highlands. The Organismo Supervisor de la Inversión Privada en Energía regulates downstream tariffs and product quality enforcement. Callao's port infrastructure handles growing refined product imports from Ecuadorian and Brazilian exporters.
South America Oil and Gas Downstream Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in catalyst supply and engineering services. The downstream structure concentrates around state-linked refining operators with captive crude access, while international traders and retail specialists occupy fragmented distribution layers. Three archetypes dominate: integrated national champions controlling refining-to-retail value chains, global majors competing through differentiated lubricants and branded retail networks, and regional utilities managing pipeline and storage infrastructure. Capacity expansion through brownfield retrofits and strategic partnerships for residue upgrading technology licensing represent the primary competitive vectors.
Within the integrated national champion tier, Petrobras and YPF SA anchor state-influenced refining complexes with captive upstream supply. Among global majors competing in retail and specialty products, Shell PLC occupies a position across the Southern Cone through differentiated service station networks. TotalEnergies and BP PLC exemplify the trading-and-logistics archetype, leveraging marine and coastal terminal assets for product arbitrage between surplus and deficit markets.
| Leading Market Players |
|---|
| Shell PLC |
| Exxon Mobil Corporation |
| Petrobras |
| Alupar Investimento |
| TotalEnergies |
| YPF SA |
| BP PLC |
| Neoenergia SA |
| Ecopetrol SA |
| Others |
Value Network & Pricing Analysis
Idle hydrotreating capacity across Brazil's Paulínia complex signals underutilization that compresses spot premiums for ultra-low sulfur diesel. ANP Resolution 885/2022 enforcement tightens through 2028, forcing operators to absorb fixed-cost burdens while negotiating pass-through mechanisms with industrial offtakers in São Paulo state's manufacturing belt.
Pricing Analysis
ANP Resolution 885/2022 dictates the pricing tier structure across Brazil's downstream market, separating certified ultra-low sulfur products from legacy fuel grades. Three-tier pricing structure across premium, standard, and economy levels reflects sulfur content thresholds, with OEM-certified lubricants commanding additional premiums for mining equipment applications. Cost compression in standard-grade diesel is intensifying because Petrobras internal transfer pricing undercuts independent importers. Retail networks show highest price sensitivity due to fragmented competition, while government procurement maintains lowest sensitivity through mandated domestic sourcing requirements.
Supply Chain Analysis
Petrobras operates captive refining capacity across eleven Brazilian complexes, with YPF SA anchoring Argentine processing at Luján de Cuyo and Plaza Huincul. Heavy crude feedstock from Brazil's pre-salt fields and Vaca Muerta tight oil growth in Argentina concentrate supply within these two countries. Catalyst supply for hydrotreating units draws from specialized chemical manufacturers in the United States and Europe, creating import dependency for critical process inputs. Single-source vulnerability concentrates in high-pressure reactor vessel fabrication, where ASME-certified suppliers face extended inspection queues. Distribution runs through multiproduct pipeline networks linking coastal refineries to inland terminals, supplemented by coastal marine movements for product arbitrage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized hydroprocessing engineering talent scarcity constrains brownfield retrofit timelines, with residuum upgrading technologists and ebullated-bed catalyst specialists commanding premium compensation across the region. This capability gap limits how quickly operators can deploy ANP-mandated capacity additions.
For Market Incumbents: Insulate refining margins through backward integration into Vaca Muerta tight oil offtake agreements, securing lighter crude slates that reduce coking intensity at Argentine processing units. Lock in long-term naphtha supply contracts with Braskem's polyethylene expansion to anchor petrochemical feedstock pricing. Carbon border adjustment exposure from EU CBAM implementation threatens export competitiveness for refined products destined for European markets; prioritize hydrotreated vegetable oil co-processing capabilities to qualify for renewable fuel certifications. For New Entrants and Emerging Players: Colombia's underdeveloped refining capacity relative to crude production represents the most penetrable entry point for Brazilian and Argentine product exporters seeking import substitution opportunities. Biofuel refinery co-processing technology licensing for hydrotreated vegetable oil integration offers a second white-space target, enabling renewable diesel output without greenfield construction. Partner with existing fluid catalytic cracking unit operators to deploy pyrolysis oil processing capabilities under tolling arrangements rather than asset ownership. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across residue upgrading infrastructure as standalone coker investments lose economic viability to hybrid hydrocracking configurations. Long-term viability over the coming decade hinges on securing technology licenses for ebullated-bed hydrocracking that extends brownfield asset productive life. Acquisition targets should prioritize operators with stranded hydroprocessing capacity in Brazil's Southeast industrial corridor. Monitor ANP enforcement timelines for sulfur content thresholds as the critical inflection signal for forced modernization waves.| Strategic Initiative | Industry Significance |
|---|---|
| Residue Upgrading Retrofit | Hybrid hydrocracking configurations at Petrobras Paulínia extend asset life without greenfield investment. |
| Biofuel Co-Processing Integration | Hydrotreated vegetable oil blending enables renewable diesel output under ANP RenovaBio compliance frameworks. |
| Vaca Muerta Feedstock Arbitrage | Lighter tight oil slates reduce coking intensity at YPF Luján de Cuyo refining complex. |
| Direct Industrial Offtake Agreements | São Paulo manufacturing belt buyers bypass traders for pipeline-connected supply security. |
| Strategic Reserve Capacity Reservation | ANP-mandated diesel buffer inventories anchor tank farm utilization at inland distribution terminals. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to construct this analysis, combining structured interviews with refinery operations managers, ANP regulatory affairs specialists, petrochemical procurement leads at Braskem, and logistics coordinators at coastal marine terminals. Secondary validation drew from ANP regulatory filings, Secretaría de Energía fuel quality decrees, SEC disclosures by listed operators, and customs trade data for refined product movements. Bottom-up capacity utilization assessments at individual refining complexes were triangulated against top-down demand projections for transportation fuels and petrochemical feedstock.
Calibration against historical capacity addition timelines and regulatory compliance cycles anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, service tier, client procurement scale, and application use-case, with additional granularity on sulfur content specification tiers. CAGRs were derived from elasticity-adjusted demand curves and capital expenditure pipeline analysis. Industry-specific inputs incorporated ANP Resolution 885/2022 phase-in schedules and RenovaBio biofuel mandate trajectories.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Argentine inflation volatility, or global crude benchmark spreads would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology commissioning timelines. Supply chain disruption from catalyst import delays or ASME certification bottlenecks represents specific revision risks. Quarterly review of ANP compliance deadlines and refinery turnaround schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Enhanced Oil Recovery Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Offshore Energy Market