
 South Sudan Oil and Gas Market | 2026-2036
South Sudan Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
South Sudan Oil and Gas Market Analytics
Petroleum sector local content rules is broadening the cost-of-entry calculus for international operators seeking new blocks in South Sudan. China National Petroleum Corporation leverages its pipeline infrastructure and upstream partnerships to sustain dominant production volumes across the Melut Basin. Dar Petroleum Operating Company anchors operational expertise in mature fields through its integrated service model. Nile Petroleum Corporation controls state equity stakes and regulatory liaison functions that differentiate its strategic position from purely commercial peers.
South Sudan oil and gas encompasses the exploration, extraction, processing, and transport of hydrocarbon resources characterized by waxy crude with API gravities ranging from 26 to 34 degrees and high pour points requiring heated pipeline transport. The sector primarily supplies regional refineries and export markets via the Greater Nile Oil Pipeline through Sudan. Conventional production dominates current output from established Paleogene rift basins while enhanced oil recovery technology represents the fastest-growing service category as operators target declining field recovery rates. Exploration services attract renewed capital allocation following seismic surveys in frontier blocks, though drilling activity remains concentrated among a handful of consortium-backed projects.
South Sudan's Ministry of Petroleum enforces local content mandates that shape contractor selection and workforce composition for upstream developments. The country's national petroleum regulator oversees environmental compliance standards aligned with regional extraction protocols. Stakeholders must monitor pipeline transit fee negotiations with Sudan and assess infrastructure security risks before committing long-term capital to new field developments.
Market Dynamics
Pipeline transit fee negotiations with Sudan and local content mandates from South Sudan's Ministry of Petroleum are reshaping capital deployment timelines for upstream operators. Heated transport infrastructure for waxy crude with high pour points adds technical complexity to field development economics.
Growth Catalysts
- Enhanced Oil Recovery Technology:Operators deploy thermal and chemical EOR methods to boost recovery rates from mature Paleogene rift basin fields. Service providers expand technical capacity to meet this demand.
- Regional Refinery Demand:East African power generation utilities extend offtake agreements for South Sudanese crude. Dar Petroleum Operating Company leverages these contracts to stabilize production volumes.
- Seismic Survey Allocation:Frontier block exploration attracts renewed capital following geophysical surveys. Nile Petroleum Corporation facilitates regulatory liaison for consortium-backed drilling programs.
Market Restraints
- Heated Pipeline Infrastructure Costs:Waxy crude with API gravities of 26-34 degrees requires continuous thermal maintenance. Capital intensity for transport infrastructure limits marginal field viability.
- Transit Route Concentration:Dependence on the Greater Nile Oil Pipeline through Sudan creates single-point vulnerability. Fee disputes disrupt export schedules and revenue recognition.
- Security Infrastructure Requirements:Field developments in Upper Nile and Unity states demand armed protection and perimeter fortification. Operating expenditure inflation affects project returns.
Strategic Opportunities
- Unity State Development:Underexplored blocks in this northern region offer untapped reserves. Operators with existing Melut Basin expertise can extend technical capabilities northward.
- Local Content Compliance Services:Foreign operators require specialized contractors to meet workforce and procurement mandates. Advisory and logistics providers fill this execution gap.
- White Nile Corridor Integration:Riverine transport alternatives to pipeline dependency reduce Sudan transit exposure. Barge and storage infrastructure investments enable export route diversification.
Industry Challenges
- Petroleum Engineering Talent Scarcity:Local workforce development lags behind technical requirements for EOR operations. Training programs require multi-year lead times.
- Environmental Compliance Timelines:National petroleum regulator standards for extraction protocols extend permitting durations. Operators face schedule compression during regulatory review.
- Legacy Field Integration:Brownfield redevelopment requires compatibility with existing wellhead infrastructure and gathering systems. Technical debt limits modernization options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Sudan Oil and Gas Market |
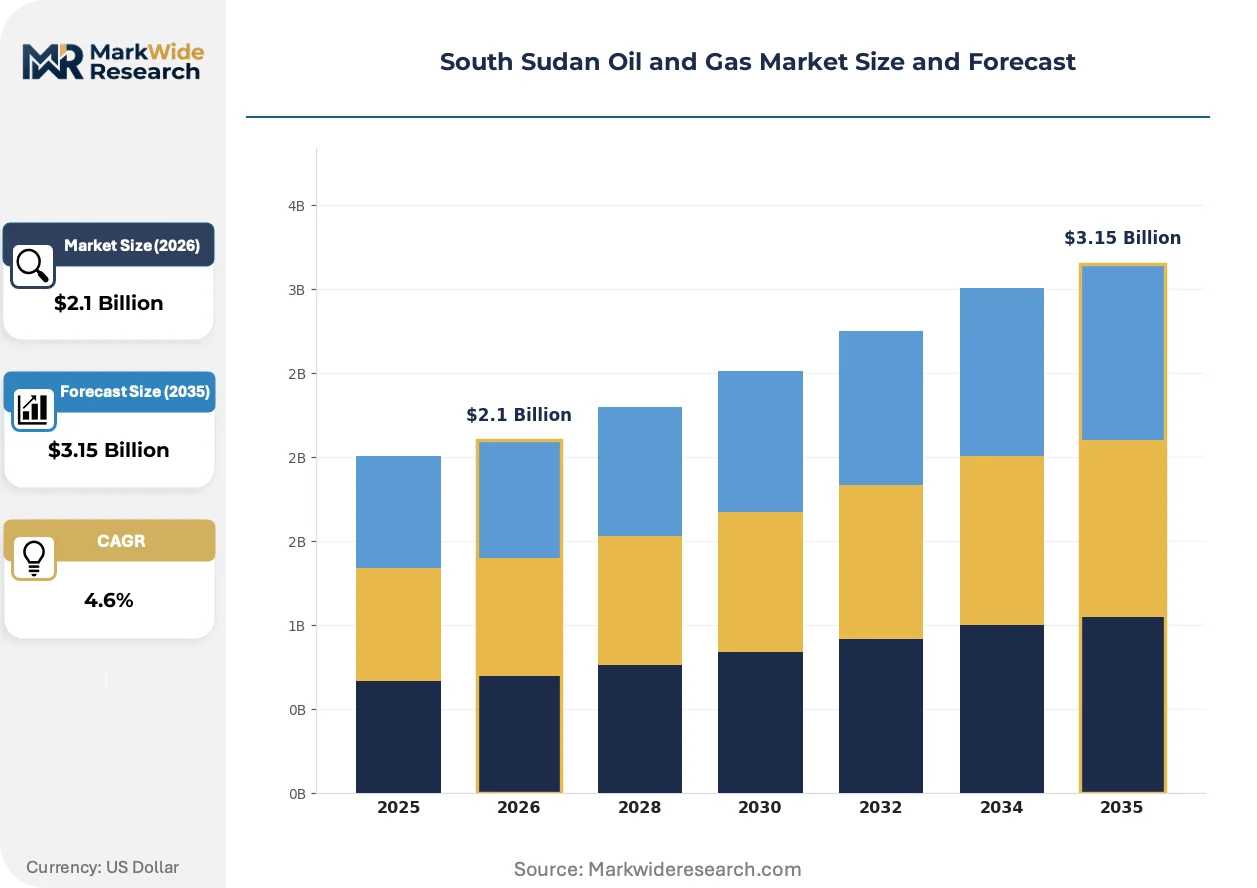
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Type: Conventional, Unconventional, Oil Sands, Tight Oil Service Type: Exploration, Drilling, Production, Refining Technology: Offshore, Onshore, Enhanced Oil Recovery, Seismic End User: Petroleum Companies, Energy Traders, Industrial Users, Governments |
| Companies Covered | Nile Petroleum Corporation, China National Petroleum Corporation, Petroliam Nasional Berhad (Petronas), ONGC Videsh Ltd., Sinopec Group, Akon Refinery Company Ltd., Dar Petroleum Operating Company, Oranto Petroleum, TriOcean Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Sudan Oil and Gas Market Evolving Landscape
Upstream technology deployment in South Sudan is consolidating around efficiency imperatives as operators target declining recovery rates. Regulatory pressure and infrastructure constraints accelerate adoption of precision extraction methods.
Artificial lift systems with intelligent monitoring capabilities are consolidating operational control across mature fields in the Melut Basin. China National Petroleum Corporation deploys these systems to optimize production from high-water-cut wells. Real-time data transmission is consolidating maintenance scheduling and reducing unplanned downtime in remote field locations.
South Sudan's Ministry of Petroleum local content regulations mandate progressive workforce nationalization and domestic procurement quotas. Foreign operators must restructure contractor selection processes to maintain license validity. Service companies with established local partnerships capture preferred supplier status under these compliance frameworks.
Power generation utilities in Kenya and Uganda now specify crude quality parameters and delivery reliability clauses in term contracts. Long-term offtake agreements displace spot market purchases for regional refinery feedstock. This contractual evolution concentrates buyer power among East African state-owned energy companies.
South Sudan Oil and Gas Market Segmentation
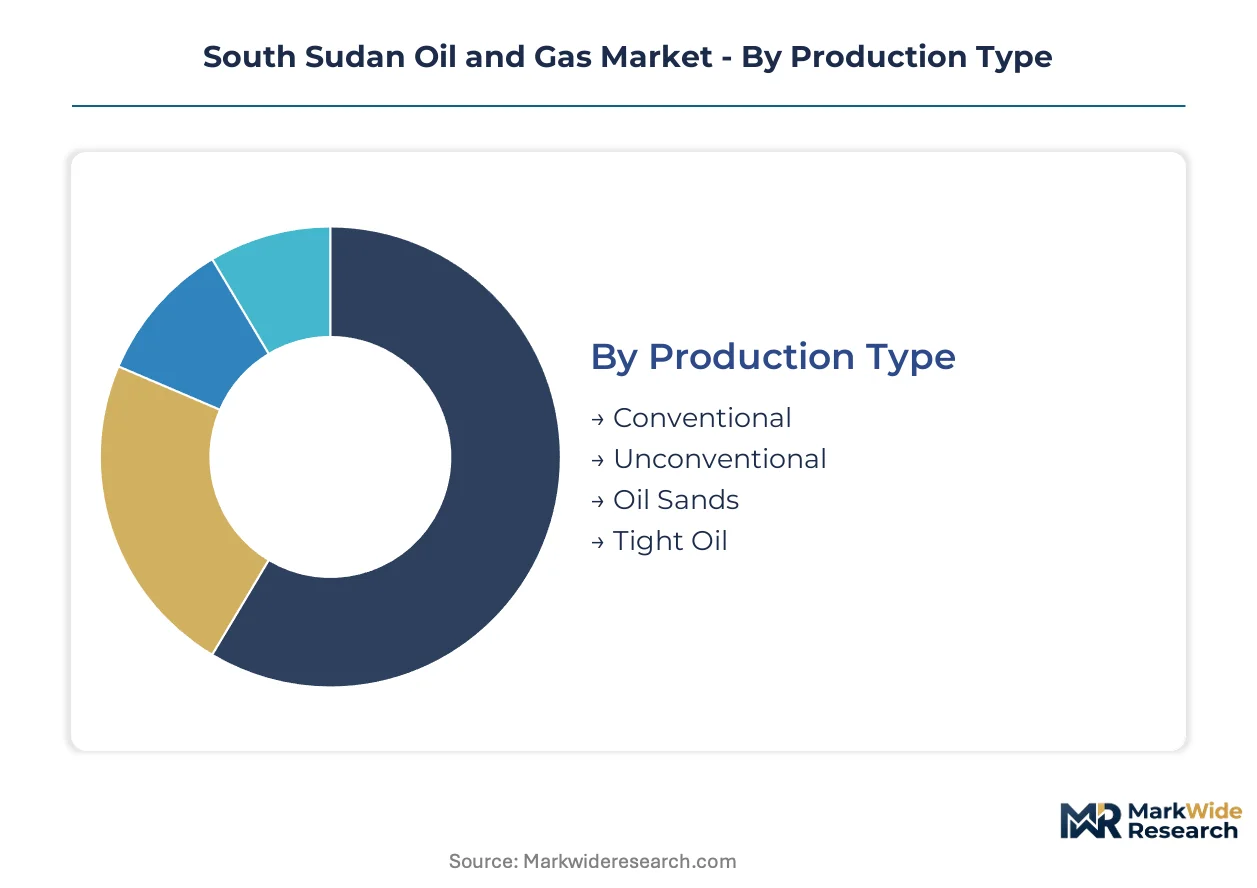
South Sudan's oil and gas segmentation reflects the dominance of mature Paleogene rift basin production and the technical constraints of waxy crude transport. Understanding how supply concentrates across production methods, service categories, and technology deployment reveals where capital flows and regulatory pressure intersect.
Production Type:
Supply concentration in South Sudan's productive basins favors established extraction methods over frontier development.
- Conventional:Paleogene rift basin fields in Upper Nile and Unity states yield waxy crude with API gravities of 26-34 degrees. Dar Petroleum Operating Company sustains output from these mature assets through integrated field management.
- Unconventional:Tight formations and shale resources remain undeveloped due to infrastructure deficits and capital intensity. No active commercial production exists in this category.
- Oil Sands:Heavy bituminous deposits lack thermal extraction infrastructure. The country's heated pipeline network serves conventional crude, not oil sands processing requirements.
- Tight Oil:Low-permeability reservoirs in frontier blocks await hydraulic fracturing investment. Seismic surveys identify targets, but drilling programs remain unfunded.
Conventional production absorbs the bulk of installed capacity; tight oil is expanding most quickly in terms of exploration interest.
Service Type:
Cost tier differentiation separates high-margin production services from commoditized exploration work.
- Exploration:Seismic surveying and geophysical interpretation for frontier blocks in Melut Basin extensions. Nile Petroleum Corporation facilitates regulatory permits for consortium-backed programs.
- Drilling:Well construction services concentrate among contractors with heated mud systems for waxy crude conditions. China National Petroleum Corporation leverages existing rig fleets for development drilling.
- Production:Artificial lift, well intervention, and facility maintenance generate recurring revenue streams. Intelligent monitoring systems optimize high-water-cut wells across mature fields.
- Refining:No domestic refining capacity exists; crude moves via Greater Nile Oil Pipeline to Sudanese terminals. Downstream services are limited to storage and loading operations.
Production services capture the highest margin tier; exploration is climbing the fastest as block licensing accelerates.
Technology:
Application requirements dictate technology deployment, with heated transport infrastructure commanding capital allocation priority.
- Offshore:No active offshore production exists. The country's hydrocarbon endowment lies entirely within onshore rift basins.
- Onshore:Land-based drilling and production infrastructure dominates the Upper Nile corridor. Pipeline gathering systems connect wellheads to export terminals.
- Enhanced Oil Recovery:Thermal and chemical methods target declining recovery rates in mature Paleogene fields. Service providers expand technical capacity to meet operator demand for secondary recovery.
- Seismic:2D and 3D geophysical surveys identify stratigraphic traps in underexplored blocks. Data acquisition supports licensing rounds and farm-in negotiations.
Onshore technology holds the largest installed base; enhanced oil recovery is gaining share fastest as field maturation accelerates.
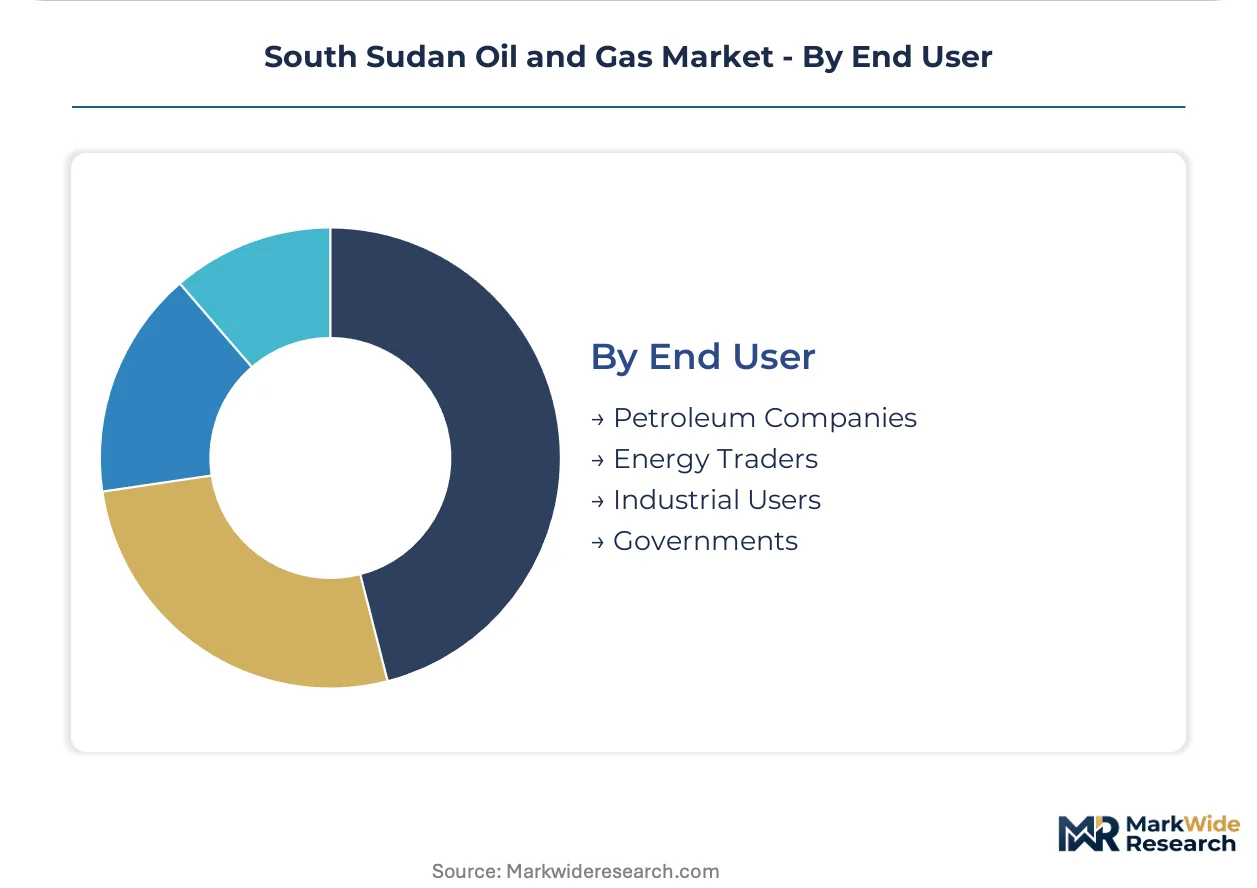
End User:
Customer type segmentation reveals how crude offtake concentrates among institutional buyers with term contracting power.
- Petroleum Companies:Integrated operators and national oil companies lift equity crude for internal refining or trading. Dar Petroleum Operating Company and China National Petroleum Corporation dominate this category.
- Energy Traders:Merchants arbitrage regional price differentials between South Sudanese export terminals and East African refineries. Transit fee volatility creates hedging demand.
- Industrial Users:Power generation utilities in Kenya and Uganda specify crude quality and delivery reliability in term contracts. Long-term offtake agreements displace spot purchases.
- Governments:State entities manage strategic petroleum reserves and bilateral supply agreements. Nile Petroleum Corporation controls equity stakes and regulatory liaison functions.
Petroleum companies absorb the bulk of lifting volumes; industrial users are expanding most quickly as regional refinery demand formalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Melut Basin special petroleum development zone concentrates upstream investment through production-sharing agreements and infrastructure concessions. State-level licensing frameworks in Upper Nile and Unity govern field access and contractor selection.
Upper Nile State
Power generation offtake contracts from Kenyan utilities drive crude lifting schedules in this northeastern zone. The Ministry of Petroleum enforces local content workforce quotas for all drilling contractors. The Paloich oilfield cluster hosts gathering facilities and heated pipeline terminals serving the Greater Nile Oil Pipeline.
Unity State
Underexplored Paleogene rift blocks attract seismic survey investment from consortium-backed exploration programs. State environmental compliance standards align with national petroleum regulator extraction protocols. The Heglig and Unity oilfield corridors anchor mature production infrastructure requiring enhanced oil recovery retrofitting.
Central Equatoria State
Juba-based regulatory liaison functions concentrate procurement oversight and license administration for foreign operators. The Ministry of Petroleum mandates domestic supplier registration for service contracts above threshold values. The capital corridor hosts logistics hubs and equipment staging yards for Upper Nile field support.
Jonglei State
Frontier block licensing rounds target stratigraphic traps along the White Nile corridor for future development drilling. National petroleum regulator permitting timelines extend environmental review durations for greenfield projects. The Bor region serves as riverine transport staging for barge-based crude movement alternatives.
South Sudan Oil and Gas Market Competitive Landscape
Chinese state-owned producers anchor one tier; South Sudanese state equity holders and regional African specialists occupy differentiated positions. The market structure consolidates around integrated operators with pipeline infrastructure control and state-backed capital access. Three archetypes dominate: state equity vehicles managing regulatory liaison, Asian national oil companies with integrated upstream-midstream positions, and independent African operators leveraging local partnership networks. Competitive moves concentrate on production-sharing renegotiations and enhanced oil recovery technology licensing.
Within the state equity tier, Nile Petroleum Corporation occupies a position managing regulatory permits and domestic procurement mandates. Among Asian national oil companies, China National Petroleum Corporation exemplifies integrated infrastructure control through pipeline and upstream joint venture positions. Dar Petroleum Operating Company represents the African independent archetype with operational focus on mature field management.
| Leading Market Players |
|---|
| Nile Petroleum Corporation |
| China National Petroleum Corporation |
| Petroliam Nasional Berhad (Petronas) |
| ONGC Videsh Ltd. |
| Sinopec Group |
| Akon Refinery Company Ltd. |
| Dar Petroleum Operating Company |
| Oranto Petroleum |
| TriOcean Energy |
| Others |
Value Network & Pricing Analysis
Petroleum engineering specialists concentrated in Juba and Upper Nile State command wage premiums that compress margin spreads between integrated operators and service contractors. Labor-cost differentials between expatriate technical staff and nationalized workforce tiers widen pricing spreads for drilling and production services across the Melut Basin.
Pricing Analysis
Short-lead-time drilling contracts for workover rigs in mature Paleogene fields command premium day rates versus long-dated exploration commitments. Contract-based long-term offtake agreements dominate crude pricing, with premium differentiation tied to delivery reliability clauses and API gravity specifications. Pricing pressure stems from transit fee volatility with Sudan, which erodes netback values for marginal field developments. National oil companies exhibit lowest price sensitivity due to state-backed capital access, while independent African operators face acute margin compression from security infrastructure requirements.
Supply Chain Analysis
Direct-to-operator procurement channels handle capital equipment and specialized EOR chemicals for China National Petroleum Corporation and Dar Petroleum Operating Company. Equipment manufacturing concentrates in China, the United Arab Emirates, and Singapore, with drilling rigs and artificial lift systems sourced from these hubs. Waxy crude heating infrastructure, specialty chemicals for thermal EOR, and intelligent monitoring hardware constitute critical input dependencies. Single-source vulnerability runs through the Greater Nile Oil Pipeline as the sole export corridor. Distribution runs through Juba-based logistics hubs and riverine staging at Bor for White Nile corridor alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Sudan's oil and gas sector functions as a cost-of-compliance market where Ministry of Petroleum local content mandates erect barrier-to-entry moats favoring established operators with proven workforce nationalization programs.
For Market Incumbents: Deepen local partnership networks to secure preferred supplier status under evolving procurement mandates. Expand technical training capacity for petroleum engineering talent development to preempt regulatory workforce quota tightening. Integrate backward into heated transport infrastructure to capture midstream margins and reduce Sudan transit exposure vulnerability.
For New Entrants and Emerging Players: Launch via specialized local content compliance advisory services targeting foreign operators restructuring contractor selection processes. Target Unity State underexplored blocks where seismic survey investment precedes drilling program commitments. White Nile corridor logistics and barge-based transport alternatives represent the most penetrable infrastructure gap.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated operators possessing pipeline infrastructure control and state-backed capital access given regional refinery demand formalization. Long-term viability hinges on sustained East African power generation utility offtake growth and successful EOR technology deployment in mature fields. Monitor Greater Nile Oil Pipeline transit fee negotiation outcomes as the critical inflection signal for export revenue stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Oil Recovery Technology Licensing | Thermal and chemical EOR methods boost recovery rates from Paleogene rift basin fields for Dar Petroleum Operating Company. |
| Local Content Compliance Program | Workforce nationalization and domestic procurement quotas satisfy Ministry of Petroleum mandates for license retention. |
| White Nile Corridor Infrastructure | Riverine transport alternatives reduce Sudan pipeline dependency and enable export route diversification for Nile Petroleum Corporation. |
| Regional Offtake Agreement Expansion | Long-term contracts with Kenyan and Ugandan power utilities stabilize production volumes and crude lifting schedules. |
| Security Infrastructure Integration | Armed protection and perimeter fortification capabilities address operating expenditure inflation in Upper Nile and Unity states. |
Research Methodology
Multi-period observation of drilling activity levels, transit fee negotiations, and local content compliance rates anchored the trend analysis, supplemented by interviews with upstream operators, petroleum ministry officials, and regional refinery procurement managers. Secondary validation drew from Ministry of Petroleum regulatory filings, Sudanese transit authority disclosures, East African power utility offtake announcements, and regional energy trade databases. Bottom-up field-level production estimates and top-down macroeconomic demand projections underwent systematic triangulation.
Input-output matrices mapped crude flow volumes against infrastructure capacity constraints and regulatory cost overlays across the projection horizon. Segmentation dimensions encompassed production type, service category, technology deployment, and end-user archetype, with specific modeling of waxy crude transport requirements and EOR adoption curves. CAGRs were derived from regression analysis of historical production trends and forward-looking capital allocation patterns, incorporating heated pipeline maintenance schedules and seismic survey licensing rounds as industry-specific forecast inputs.
The model assumes a particular technology adoption path for intelligent monitoring systems and thermal EOR methods; alternative pathways for artificial lift optimization would alter the outlook for mature field recovery rates. Forecasts reflect assumptions regarding pipeline transit fee stability, security environment continuity, and regional refinery demand growth. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Enhanced Oil Recovery Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Qatar Oil and Gas Upstream Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Europe LNG Bunkering Market