
 Freezer Bags Market | 2026-2036
Freezer Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Freezer Bags Market Intelligence
Subscription-based replenishment programs for household essentials is shifting how freezer bags reach end users, bypassing traditional retail shelf competition. SC Johnson leverages its Ziploc brand strength to anchor direct-to-consumer channel control. Huhtamaki Oyj competes through specialized industrial formats for food processing units. Reynolds Consumer Products sustains manufacturing scale across North American retail partnerships.
Freezer bags are multi-layer polymer pouches engineered to withstand temperatures from ambient to minus twenty degrees Celsius without embrittlement or seal failure, primarily serving food preservation and laboratory specimen storage. Polyethylene formulations dominate volume production due to cost-efficiency and moisture-barrier performance, while biodegradable polymers represent the fastest-growing material category as regulatory pressure intensifies. Medium-format packaging sizes capture the largest household segment, whereas extra-large formats concentrate margin pools in food service and scientific laboratory procurement.
FDA food-contact regulations govern polymer composition and migration limits in the United States, while REACH and the EU Green Deal restrict certain plastic additives across European markets. China's SAMR enforces GB standards for food packaging safety, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor evolving state and provincial single-use plastic restrictions to anticipate material substitution timelines and reformulation investments.
Market Dynamics
State-level single-use plastic bans across the United States are forcing polyethylene suppliers to accelerate bio-based polymer development while maintaining seal integrity at cryogenic temperatures. This regulatory pressure is compressing reformulation timelines and redrawing competitive boundaries between incumbent petrochemical producers and emerging biomaterial specialists.
Growth Catalysts
- EU Green Deal packaging mandates:Biodegradable polymer specifications in European markets create certified demand pools for compostable freezer bag alternatives, rewarding early reformulators with preferential procurement status.
- Food processing automation:Industrial-scale flash-freezing lines in protein processing facilities require extra-large format bags with machine-compatible sealing surfaces, expanding addressable volume beyond household segments.
- Specimen biobanking expansion:Academic medical centers and pharmaceutical cold-chain operations are standardizing on medical-grade polyethylene pouches for temperature-stable biological sample storage.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings directly compress polyethylene resin margins, forcing bag manufacturers to absorb cost spikes or risk volume loss to private-label alternatives.
- China resin supply concentration:Over half of global linear low-density polyethylene capacity sits with state-controlled petrochemical complexes, creating geopolitical exposure for Western converters.
- Biodegradable performance gaps:Current PLA and starch-blend formulations embrittle below minus ten degrees Celsius, limiting substitution in deep-freeze applications.
Strategic Opportunities
- India cold-chain infrastructure:FSSAI-mandated food safety modernization and PLI scheme subsidies for packaging equipment create first-mover advantage for freezer bag suppliers establishing local compounding partnerships.
- Subscription replenishment channels:Direct-to-consumer auto-ship models bypass retail slotting fees and capture lifetime value data for personalized format recommendations.
- Dual-carbon compliance in China:SAMR carbon footprint labeling requirements favor domestic producers with integrated bio-feedstock supply chains, disadvantaging import-dependent competitors.
Industry Challenges
- Multilayer film recycling infrastructure:Current mechanical separation technologies cannot process adhesive-laminated polyethylene-nylon structures, creating extended producer responsibility liabilities in jurisdictions with packaging waste laws.
- Cryogenic seal validation protocols:FDA migration testing and seal-strength certification cycles extend eighteen to twenty-four months, delaying new product launches behind reformulation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freezer Bags Market |
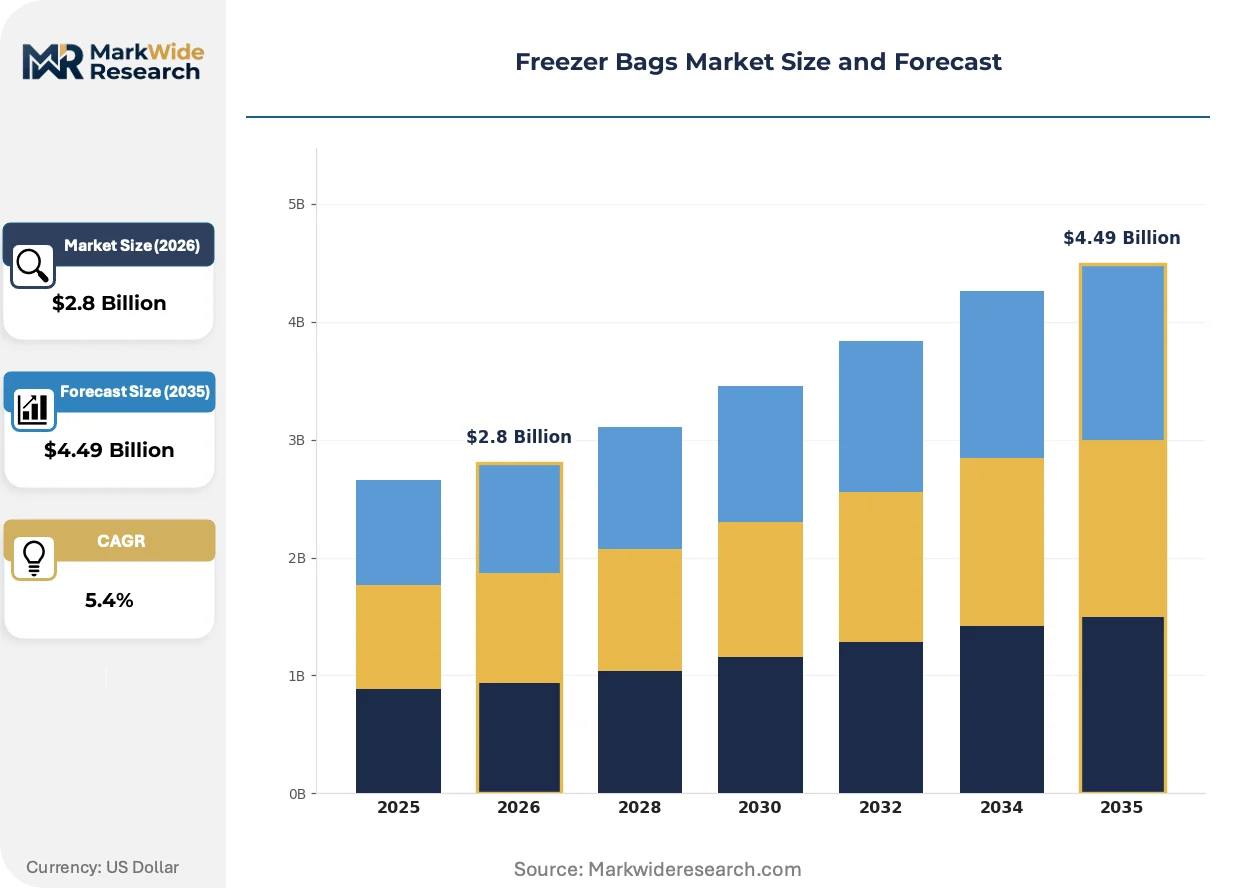
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Biodegradable Polymers, Nylon, Composite Films Packaging Size: Small (1-5 Gallon), Medium (6-10 Gallon), Large (11-15 Gallon), Extra Large (16 Gallon & Above) End User: Household Consumers, Food Processing Units, Catering Services, Scientific Laboratories Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Specialty Stores, Wholesale Suppliers |
| Companies Covered | Berry Global Inc., Huhtamaki Oyj, SC Johnson (Ziploc), Cosmoplast Industrial Company LLC, Tesco PLC, Reynolds Consumer Products, Inteplast Group, Great American Packaging, The Glad Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freezer Bags Market Strategic Shifts & Innovations
Material science breakthroughs and channel restructuring are converging to redefine how freezer bags are formulated, certified, and delivered to end users. These shifts favor suppliers with integrated polymer research capabilities and flexible manufacturing footprints.
Mono-material polyethylene constructions is unifying previously separate barrier and sealant layers into single-polymer films that maintain oxygen transmission rates below 0.5 cc per square meter per day. Food service distributors in Germany and the Netherlands are qualifying these structures for commercial kitchen procurement. The technology is unifying recycling streams by eliminating adhesive lamination, enabling mechanical reprocessing at standard polyethylene recovery facilities.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated polymer treatments previously used for grease resistance in freezer-to-microwave applications. European converters must reformulate without PFAS by 2025, accelerating silicone-based and bio-wax barrier coating development. Medium-format household bags face the steepest reformulation cost impact, driving consolidation among regional European suppliers lacking R&D scale.
Replenishment algorithms tied to smart appliance inventory tracking are displacing periodic retail purchasing for suburban households with connected freezer systems. Amazon Dash and proprietary hardware integrations from major appliance manufacturers capture demand before it reaches physical stores. This pattern concentrates most visibly in United States metropolitan corridors with high penetration of internet-connected kitchen appliances.
Freezer Bags Market Segmentation
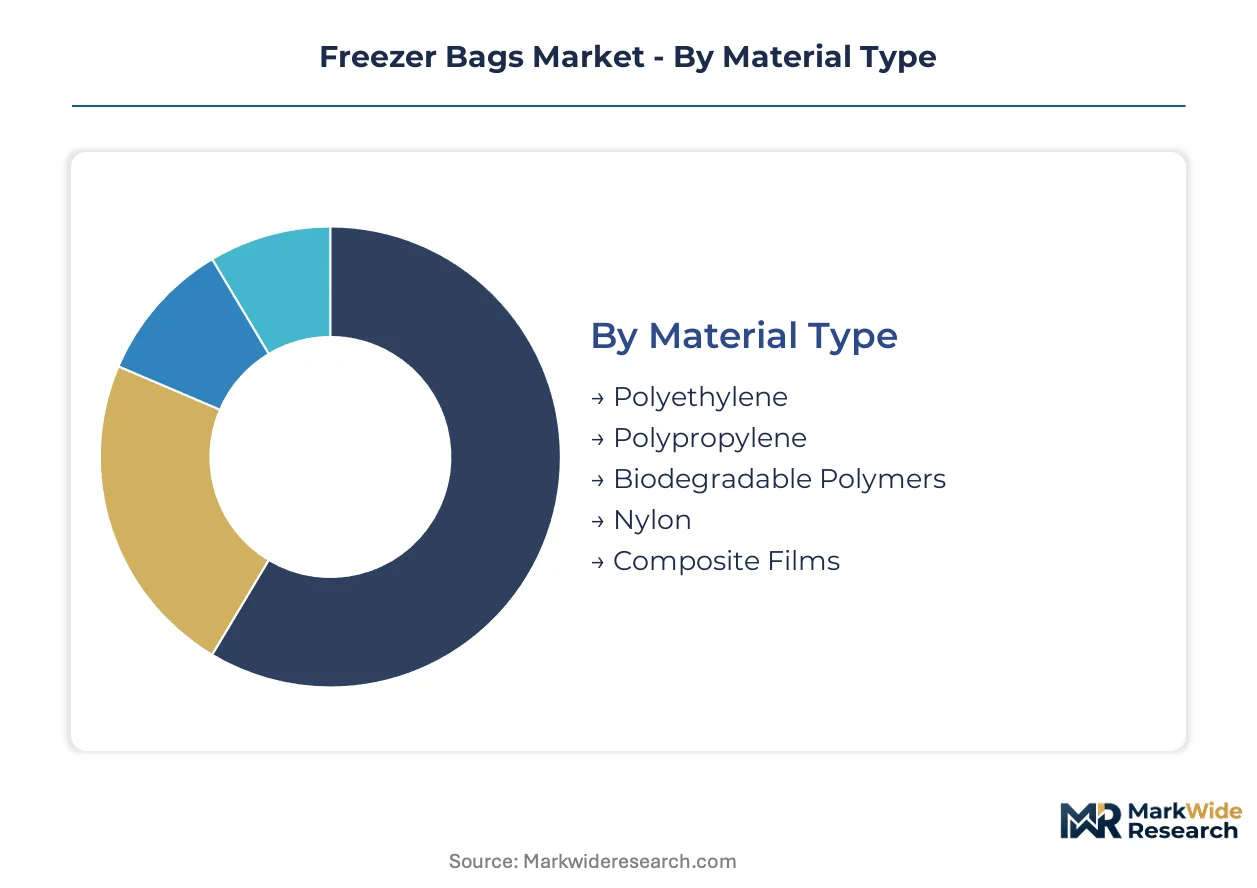
Freezer bag suppliers configure product portfolios across four intersecting dimensions that determine formulation investment, margin structure, and channel access. Material chemistry and packaging format decisions cascade through end-use specifications and distribution economics, creating distinct competitive battlegrounds within each slice.
Material Type:
Supply concentration in polyethylene resin production shapes cost structures and reformulation timelines across all material categories.
- Polyethylene:Linear low-density polyethylene formulations dominate volume manufacturing through superior flexibility at cryogenic temperatures and moisture-barrier performance. Demand concentrates in United States suburban households and Chinese cold-chain logistics networks where cost-per-unit sensitivity governs procurement.
- Biodegradable Polymers:PLA and starch-blend alternatives are expanding most quickly as EU Green Deal mandates and state-level plastic bans in California and New York compress substitution timelines. Performance gaps below minus ten degrees Celsius limit penetration in deep-freeze scientific applications.
- Polypropylene:Higher melting point suits microwave-compatible formats for food service distributors in Germany seeking freezer-to-oven convenience.
- Nylon:Oxygen barrier properties serve premium protein packaging for flash-frozen seafood exporters in Norway and Japan.
- Composite Films:Multilayer adhesive-laminated structures concentrate in medical-grade specimen biobanking where FDA migration limits require specialized certification cycles.
Today's leader: Polyethylene. Tomorrow's challenger: Biodegradable Polymers.
Packaging Size:
Volume throughput and margin capture diverge sharply across format tiers, with household-scale bags running on high-speed converting lines while industrial formats command pricing premiums.
- Medium (6-10 Gallon):Resealable zipper formats in this range anchor suburban North American household adoption, with SC Johnson's Ziploc brand controlling shelf placement in Walmart and Target retail partnerships.
- Extra Large (16 Gallon & Above):Machine-compatible sealing surfaces serve automated flash-freezing lines in Tyson Foods and JBS protein processing facilities, expanding addressable volume beyond consumer segments.
- Small (1-5 Gallon):Single-serve portion control formats concentrate in Japanese convenience store supply chains and European meal-kit subscription services.
- Large (11-15 Gallon):Bulk storage formats serve restaurant chain procurement through Sysco and US Foods distribution networks.
Volume concentrates in Medium formats. Margin expansion concentrates in Extra Large.
End User:
Application requirements determine seal validation protocols, with scientific and medical segments imposing eighteen-to-twenty-four-month certification timelines that delay new product launches.
- Household Consumers:Suburban United States demand drives resealable format innovation, with smart appliance integration enabling subscription replenishment through Amazon Dash and proprietary hardware partnerships.
- Food Processing Units:Industrial-scale protein freezing operations in Brazil and Australia require extra-large formats with machine-compatible sealing surfaces and batch-traceable labeling.
- Catering Services:Commercial kitchen procurement in Germany and the Netherlands favors mono-material polyethylene constructions that unify recycling streams.
- Scientific Laboratories:Academic medical centers and pharmaceutical cold-chain operations standardize on medical-grade polyethylene pouches for temperature-stable biological sample storage.
Certification intensity peaks with Scientific Laboratories. Volume scale peaks with Household Consumers.
Distribution Channel:
Channel control determines customer data access and margin retention, with direct-to-consumer models bypassing retail slotting fees that erode profitability in traditional brick-and-mortar.
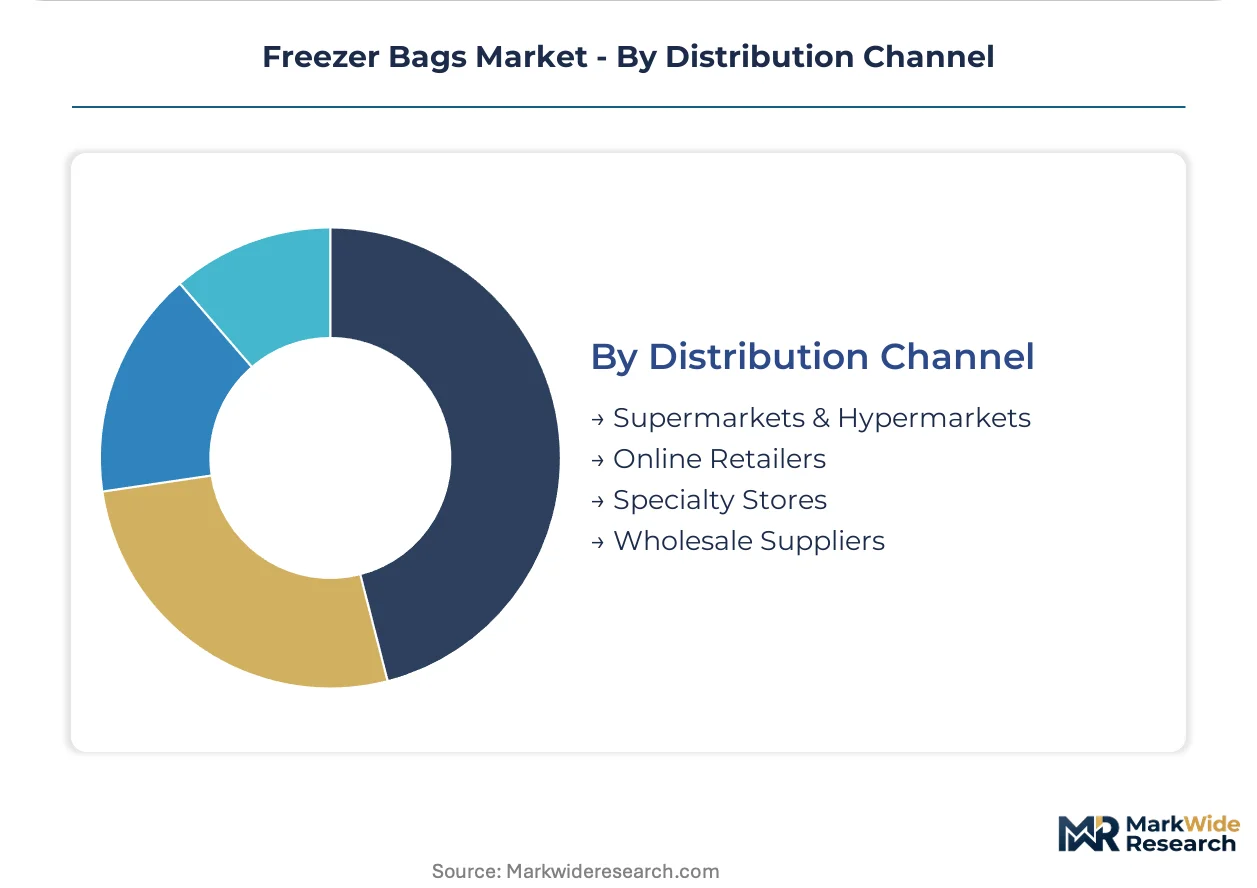
- Supermarkets & Hypermarkets:Walmart, Kroger, and Costco shelf placement requires trade promotion spending and category management relationships that concentrate share among scaled manufacturers.
- Online Retailers:Amazon and Alibaba platforms enable subscription auto-ship models that capture lifetime value data for personalized format recommendations.
- Specialty Stores:Restaurant supply and scientific equipment distributors serve niche procurement with technical specification support.
- Wholesale Suppliers:Sysco, US Foods, and McLane Company networks aggregate food service demand through contracted pricing agreements.
Margin retention favors Online Retailers. Volume throughput favors Supermarkets & Hypermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing freezer bag production capacity toward jurisdictions with lower compliance burdens, even as end-use demand concentrates in high-income suburban markets with stringent material specifications.
United States
Suburban household demand for resealable formats drives volume, with smart appliance integration enabling subscription replenishment models. FDA food-contact regulations govern polymer composition and migration limits, creating eighteen-to-twenty-four-month certification cycles. Chicago and Dallas-Fort Worth metropolitan corridors concentrate retail distribution partnerships for medium-format household bags.
China
Cold-chain logistics expansion for protein processing creates industrial-scale demand for extra-large format bags. SAMR enforces GB standards for food packaging safety and carbon footprint labeling requirements that favor domestic producers with integrated bio-feedstock supply chains. Yangtze River Delta manufacturing clusters house state-controlled petrochemical complexes supplying over half of global linear low-density polyethylene capacity.
Germany
Commercial kitchen procurement favors mono-material polyethylene constructions that unify recycling streams and satisfy EU Green Deal packaging mandates. REACH restrictions on per- and polyfluoroalkyl substances eliminate fluorinated polymer treatments by 2025, accelerating silicone-based barrier coating development. Hamburg and Rotterdam port complexes serve as distribution hubs for flash-frozen seafood exporters requiring premium oxygen barrier specifications.
India
FSSAI-mandated food safety modernization and PLI scheme subsidies for packaging equipment create first-mover opportunities for suppliers establishing local compounding partnerships. Cold-chain infrastructure gaps in perishable logistics generate demand for temperature-stable storage formats. Maharashtra and Gujarat industrial corridors concentrate emerging converter capacity for domestic food processing units.
Japan
Single-serve portion control formats concentrate in convenience store supply chains with exacting shelf-life requirements. METI standards govern food-contact material safety, while JIS certification protocols extend product qualification timelines. Osaka-Kobe manufacturing clusters specialize in precision-seal technologies for scientific laboratory specimen biobanking applications.
Freezer Bags Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with household consumer markets consolidating around recognizable trade names while industrial procurement favors technical specification suppliers. The vendor base organizes into three strategic archetypes: integrated petrochemical converters with captive resin supply, specialized flexible packaging engineers serving scientific and medical channels, and private-label manufacturers competing on cost-per-unit for retail shelf placement. Dominant competitive moves include backward integration into resin compounding to secure feedstock margins and geographic expansion through local partnerships to satisfy divergent national certification requirements.
Among North American branded incumbents, SC Johnson and Reynolds Consumer Products exemplify the marketing-intensive archetype, leveraging consumer recognition to anchor retail shelf placement and direct-to-consumer channel control. Huhtamaki Oyj represents the technical-specialist positioning, occupying a position in industrial and food service segments where machine-compatible sealing surfaces and batch-traceable labeling command procurement preference. These three companies illustrate how divergent strategic postures—consumer brand equity versus technical specification expertise—can coexist within the same product category without direct head-to-head competition.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Huhtamaki Oyj |
| SC Johnson (Ziploc) |
| Cosmoplast Industrial Company LLC |
| Tesco PLC |
| Reynolds Consumer Products |
| Inteplast Group |
| Great American Packaging |
| The Glad Products Company |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up flexible packaging specialists have consolidated regional converting capacity across the United States Midwest, tightening supply discipline while anchoring contract pricing to ethylene feedstock indices. This ownership pattern concentrates pricing power among scaled producers who can absorb resin volatility through backward integration into compounding operations.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for linear low-density polyethylene resin, compressing margins for import-dependent Western converters. Pricing stratifies across premium, standard, and economy tiers, with FDA-certified medical-grade bags commanding substantial premiums over household formats. Cost compression in standard-tier household segments is intensifying because private-label alternatives capture shelf space at major retailers. Food processing units exhibit lowest price sensitivity due to batch-traceability requirements, while suburban households drive volume through promotional elasticity.
Supply Chain Analysis
Regional distribution centers in Chicago, Dallas-Fort Worth, and Rotterdam anchor hub-and-spoke patterns that consolidate last-mile delivery for retail and food service channels. Manufacturing concentrates in China, the United States, and Germany, with each hub serving distinct regulatory compliance pathways. Raw material flows draw from ethylene crackers, bio-based polymer pilot plants, and adhesive lamination chemical suppliers. Single-source vulnerability runs through state-controlled Chinese petrochemical complexes that supply over half of global linear low-density polyethylene capacity. Distribution runs through wholesale food service networks, direct-to-consumer subscription platforms, and retail shelf partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The freezer bags market functions as a stable compounder anchored by perpetual replenishment demand from suburban households and institutional food service operations. Regulatory-driven material transitions create sustained reformulation cycles that reward suppliers with integrated R&D capabilities.
For Market Incumbents: Deepen backward integration into bio-based polymer compounding to capture margin from EU Green Deal mandates and California plastic restrictions. Accelerate certification investment for medical-grade specifications to defend against emerging biomaterial specialists. Anchor direct-to-consumer channel control through smart appliance partnerships that preempt retail slotting fee erosion.
For New Entrants and Emerging Players: The price-point gap between premium medical-grade and economy household tiers offers white-space opportunity for mid-market biodegradable alternatives. Target India's Maharashtra and Gujarat industrial corridors where FSSAI modernization and PLI subsidies reduce entry barriers. Pursue local compounding partnerships as the primary go-to-market angle to satisfy SAMR carbon footprint labeling requirements.
For Investors and Strategic Acquirers: Integrated petrochemical conglomerates are the most active acquirer in this space, seeking flexible packaging converters to secure downstream demand for captive resin output. Five-to-ten-year viability hinges on successful navigation of multilayer film recycling infrastructure gaps and PFAS reformulation timelines. Monitor state-level plastic ban acceleration as the key inflection signal for bio-based polymer substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Feedstock Compounding | Captures margin from EU Green Deal mandates and state plastic bans. |
| Medical-Grade Certification Investment | Extends eighteen-to-twenty-four-month FDA validation cycles that deter competitors. |
| Direct-to-Consumer Subscription Launch | Bypasses Walmart and Target slotting fees while capturing lifetime value data. |
| Mono-Material Polyethylene Transition | Satisfies Germany and Netherlands commercial kitchen recycling requirements. |
| India Local Manufacturing Partnership | Positions for FSSAI-mandated cold-chain infrastructure expansion and PLI subsidies. |
Research Approach
Direct dialogue with polymer plant managers, retail category buyers, food service procurement directors, and scientific laboratory supply managers grounded qualitative insights in operational reality. Secondary validation drew from FDA migration limit filings, SAMR GB standard updates, EU REACH restriction notices, and customs trade data for polyethylene resin flows. Bottom-up and top-down triangulation cross-checked volume estimates across material type, packaging format, end-use segment, and distribution channel dimensions.
Bottom-up modeling built from named facility capacities and throughput assumptions, while top-down verification anchored against regional cold-chain infrastructure investment patterns. Segmentation dimensions included material chemistry, packaging size tier, end-use application, and distribution channel structure across the analysis window. CAGRs were derived from regression analysis against historical ethylene price elasticity and regulatory substitution timelines. Forecast inputs incorporated EU Green Deal implementation velocity and China dual-carbon labeling adoption curves.
Caveats apply where crude oil price volatility, geopolitical disruption to Chinese resin supply, or accelerated PFAS restriction timelines could materially shift the outlook. Forecasts reflect documented assumptions around bio-based polymer performance gap closure and mechanical recycling infrastructure buildout. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Bag-In-Box Packaging Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Global High Abuse Shrink Bags Market